
 Fish Gelatin Market | 2026-2036
Fish Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Gelatin Market Analysis
Custom hydrolysis service contracts is realigning how fish gelatin gets monetized, shifting volume buyers toward toll-manufacturing arrangements rather than spot purchases. Gelita AG leverages captive coldwater fish sourcing from Nordic waters to sustain premium-grade output for European pharmaceutical clients. Weishardt Group anchors its position through integrated collagen-to-gelatin processing in France. Nitta Gelatin Inc. competes on specialized low-odor formulations for Japanese nutraceutical applications.
Fish gelatin is a thermally reversible hydrocolloid extracted from collagen-rich fish skins and bones, typically exhibiting bloom strengths between 50 and 250 g and forming thermostable gels below 35°C for encapsulation and food binding. Its primary commercial purpose centers on replacing mammalian gelatin in halal, kosher, and allergen-sensitive formulations across pharmaceuticals and confectionery. Powdered grades dominate current volume owing to dispersibility advantages in industrial mixing equipment, while capsule-grade material commands the strongest margin pool due to pharmaceutical certification burdens. The nutraceuticals end-user segment represents the fastest-expanding demand channel, driven by soft-gel dietary supplement production in Southeast Asia.
EMA guidelines on transmissible spongiform encephalopathy risks in marine-derived biologics shape pharmaceutical-grade fish gelatin approval pathways in Europe. The FDA's Food Safety Modernization Act and USDA import inspection protocols govern U.S. market access, while China's NMPA enforces GB standards on collagen peptide purity for domestic capsule manufacturers. Stakeholders must monitor evolving halal certification reciprocity agreements between Southeast Asian processors and Middle Eastern import authorities, as these accreditations increasingly determine contract eligibility for multinational pharmaceutical buyers.
Market Dynamics
Pharmaceutical capsule manufacturers are systematically replacing mammalian gelatin with fish-derived alternatives, driven by halal certification requirements and EMA's tightened traceability mandates for marine-sourced biologics. This substitution wave is restructuring procurement relationships across Southeast Asian processing clusters.
Growth Catalysts
- REACH traceability mandates:The European Union's ECHA framework requires batch-level documentation for marine collagen inputs, accelerating qualified supplier consolidation among Nordic and Mekong Delta processors serving pharmaceutical clients.
- Soft-gel nutraceutical expansion:Japanese and South Korean dietary supplement manufacturers are expanding fish gelatin offtake for omega-3 and vitamin encapsulation, prioritizing low-odor formulations for consumer palatability.
- Coldwater species sourcing:Premium-grade material extracted from cod and haddock skins commands preference in European pharmaceutical applications due to superior bloom strength consistency and lower heavy metal bioaccumulation.
Market Restraints
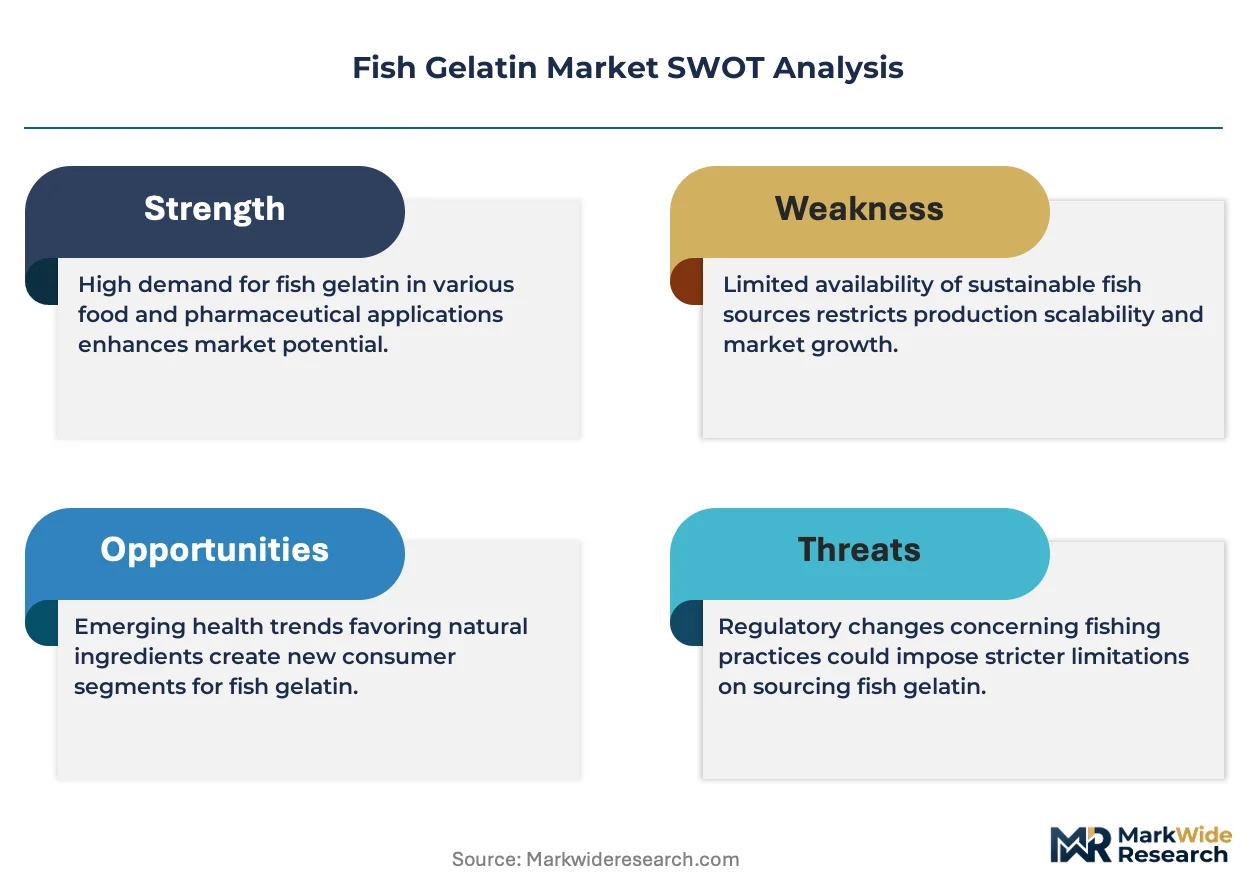
- Pangasius skin price volatility:Vietnam's Mekong Delta aquaculture output fluctuates with monsoon patterns and disease outbreaks, creating raw material cost instability for regional hydrolysis facilities.
- Religious certification fragmentation:Non-uniform halal accreditation standards between Indonesian, Malaysian, and Middle Eastern authorities create compliance friction for multinational pharmaceutical buyers seeking single-source supply.
- Plant-based hydrocolloid substitution:Carrageenan and pectin formulations are capturing confectionery applications where gel strength requirements permit, particularly in European gummy candy production.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with ICH guidelines for capsule excipients creates entry pathways for certified fish gelatin suppliers as domestic soft-gel production expands under PLI scheme incentives.
- Enzymatic hydrolysis advancement:Protease engineering combined with membrane filtration is enabling higher-yield extraction from fish bone collagen, opening underutilized raw material streams currently discarded by filleting operations.
- Toll-manufacturing contracts:Volume buyers are abandoning spot purchases for dedicated processing agreements, allowing gelatin producers to secure forward revenue while buyers guarantee supply security.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA's transmissible spongiform encephalopathy assessment protocols for marine-derived biologics extend approval cycles to 18-24 months, constraining new entrant market access.
- Cross-species collagen characterization:Analytical chemists with expertise in distinguishing teleost from mammalian peptide markers remain scarce, limiting quality control scalability for expanding production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Gelatin Market |
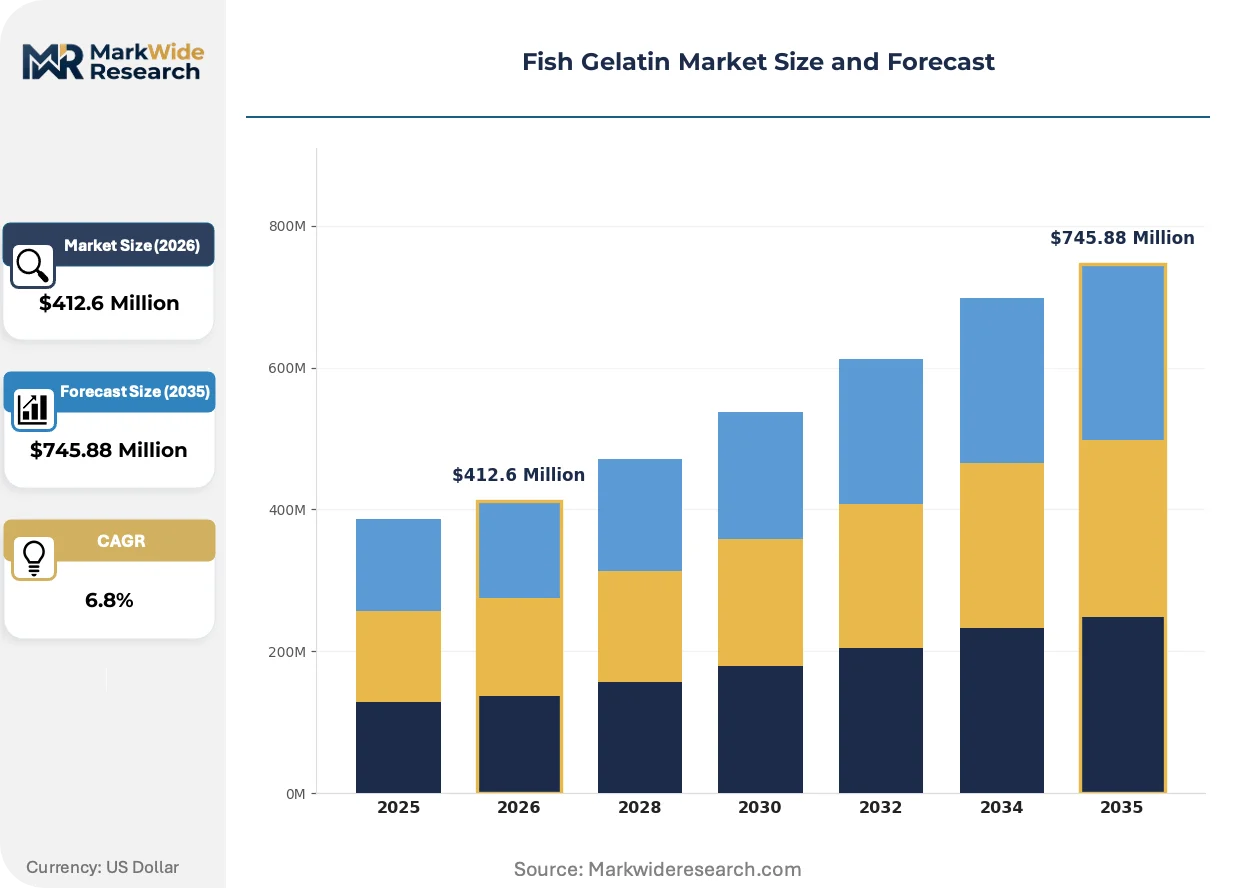
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Sheets, Capsules End User: Food Industry, Pharmaceuticals, Cosmetics, Nutraceuticals Application: Desserts, Gummies, Beverages, Dietary Supplements Source: Wild-Caught, Farmed, Organic, Non-Organic |
| Companies Covered | Weishardt Group, Nitta Gelatin Inc., Gelita AG, Norland Products Incorporated, Lapi Gelatine S.p.A., Vinh Hoan Corporation, Kenney & Ross Limited, Foodchem International Corporation, PB Leiner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Gelatin Market Emerging Trajectories
Enzymatic processing technologies and regulatory harmonization efforts are compressing the traditional gelatin value chain, while buyer procurement patterns shift toward integrated supply agreements that bypass commodity trading layers.
Membrane filtration coupled with precision protease hydrolysis is consolidating extraction efficiency benchmarks across Vietnamese and French processing facilities. Pharmaceutical capsule manufacturers are adopting these systems to secure consistent bloom strength specifications. The technology is consolidating competitive advantage among operators with captive enzyme supply or in-house biotechnology capabilities.
EMA's updated guidance on transmissible spongiform encephalopathy risks in marine-derived biologics now mandates species-level documentation for all collagen inputs. European pharmaceutical buyers are responding by restricting approved supplier lists to processors with full-chain traceability systems. Capsule-grade material faces the steepest compliance burden, with certification costs now embedded in contract pricing structures.
Soft-gel dietary supplement manufacturers are consolidating procurement through direct toll-manufacturing arrangements with Mekong Delta hydrolysis facilities, bypassing traditional gelatin traders. Japanese nutraceutical brands are driving this behavioral shift, seeking locked-in volume commitments in exchange for technical collaboration on low-odor formulation development. Southeast Asian processing clusters are capturing the margin previously extracted by European distributors.
Fish Gelatin Market Segmentation
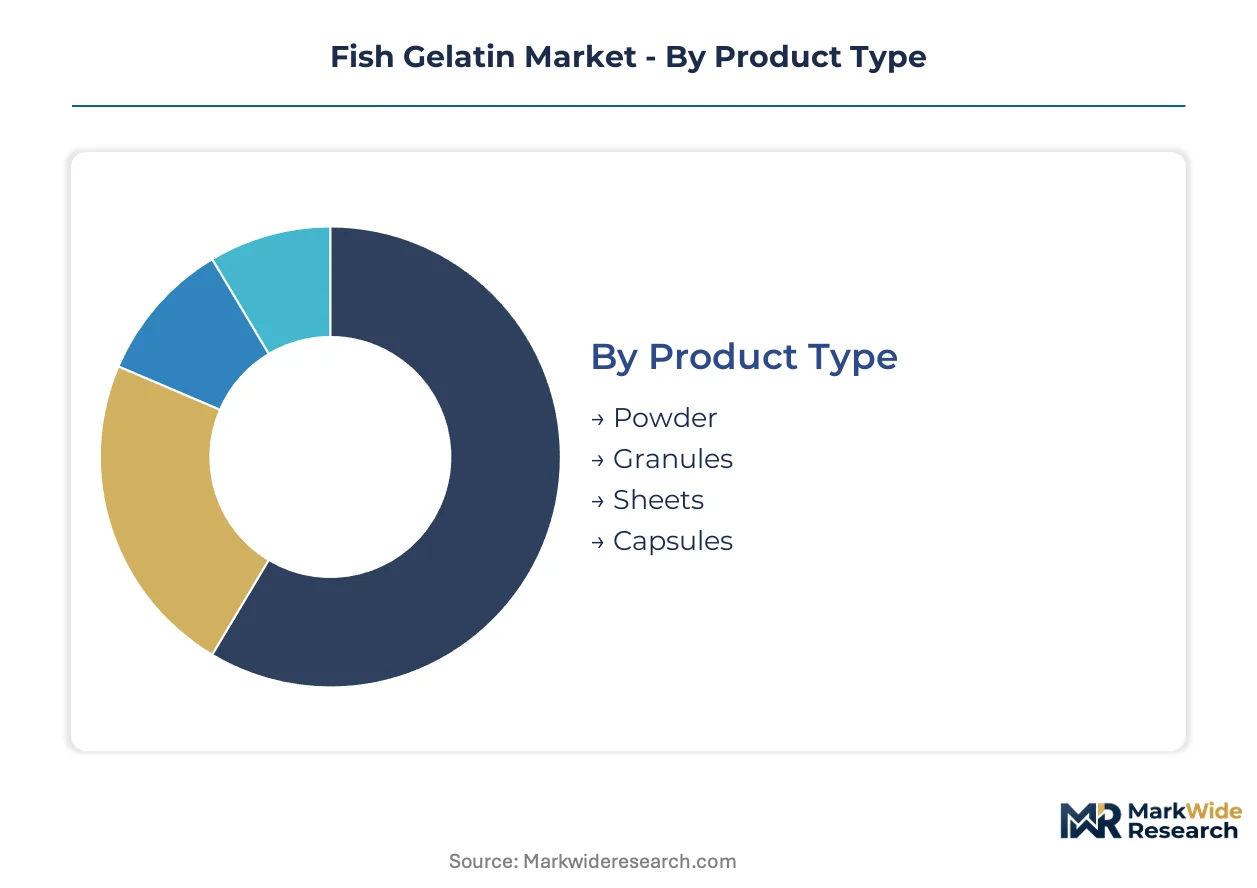
Segmentation in fish gelatin markets reveals how procurement priorities diverge across buyer archetypes. Pharmaceutical manufacturers prioritize bloom strength consistency and traceability documentation, while food processors optimize for dispersibility and cost efficiency in high-throughput mixing environments.
Product Type:
Form factor selection separates industrial-scale buyers from artisanal or specialized pharmaceutical purchasers.
- Powder:Fine-milled particles between 40-80 mesh enable rapid hydration in continuous mixing systems. Food manufacturers in Vietnam's confectionery sector favor powdered grades for gummy production lines requiring uniform gel strength distribution.
- Capsules:Pre-formed gelatin shells for soft-gel encapsulation demand pharmaceutical-grade certification and species-level documentation under EMA traceability mandates. Japanese nutraceutical brands source capsule-grade material through direct toll-manufacturing arrangements with Mekong Delta processors.
- Granules:Intermediate particle size suits small-batch food processors and specialty dessert manufacturers seeking controlled dissolution rates.
- Sheets:Traditional leaf gelatin serves European artisanal confectioners and high-end patisserie applications requiring precise bloom strength layering.
Volume sits with powder; growth tilts toward capsules.
End User:
Regulatory burden and certification requirements fragment buyer priorities across consumption channels.
- Pharmaceuticals:Soft-gel and hard-shell capsule excipients require EMA transmissible spongiform encephalopathy assessments and batch-level species documentation. European manufacturers restrict approved supplier lists to processors with full-chain traceability systems.
- Nutraceuticals:Omega-3 and vitamin encapsulation drives demand for low-odor formulations in Japanese and South Korean dietary supplement production. This segment is expanding most quickly as direct-to-consumer supplement brands proliferate.
- Food Industry:Confectionery, dairy, and meat processing applications prioritize cost efficiency and dispersibility over certification depth.
- Cosmetics:Collagen peptide derivatives for topical formulations occupy a niche position with distinct hydrolysis requirements.
Revenue concentrates in pharmaceuticals; nutraceuticals capture the steepest expansion trajectory.
Application:
Functional performance requirements determine grade selection and supplier qualification pathways.
- Dietary Supplements:Soft-gel encapsulation of lipophilic vitamins and omega-3 fatty acids demands thermostable gel matrices with low oxidation sensitivity. Southeast Asian manufacturers are consolidating procurement through toll-manufacturing contracts.
- Gummies:Confectionery applications require rapid-set properties and consumer-friendly texture profiles. Vietnamese processors supply Mekong Delta-derived material to regional candy producers.
- Desserts:Mousses, panna cotta, and gelatin-based sweets favor neutral flavor profiles and controlled bloom strength ranges.
- Beverages:Clarification and stabilization applications in fruit juices and alcoholic drinks utilize lower-grade hydrolysates.
Contract value clusters in dietary supplements; gummies show the fastest volume climb.
Source:
Raw material provenance shapes regulatory compliance burden and end-market access eligibility.
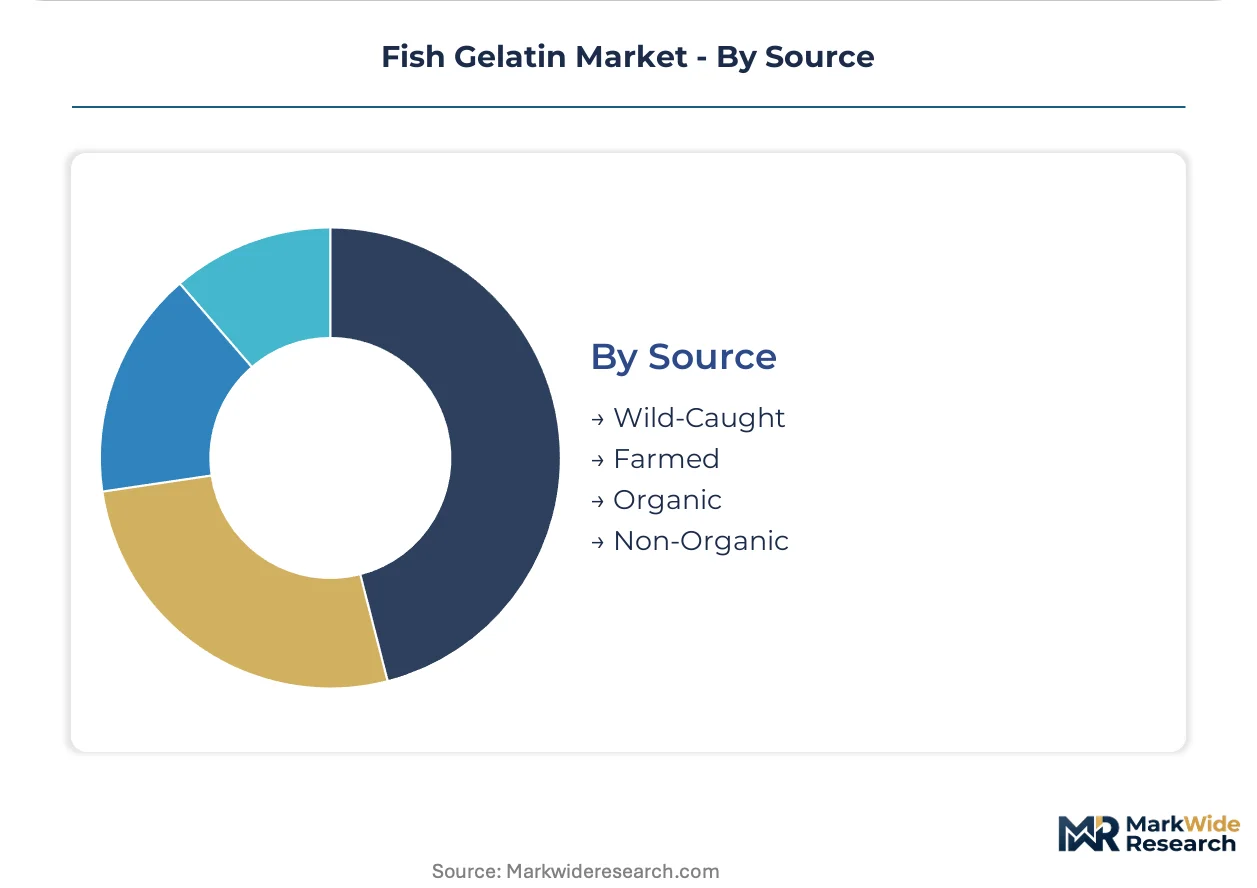
- Wild-Caught:Coldwater species from Nordic waters deliver superior bloom strength consistency and lower heavy metal bioaccumulation. Gelita AG leverages captive sourcing from these fisheries for European pharmaceutical clients.
- Farmed:Pangasius skin from Vietnam's Mekong Delta aquaculture operations feeds regional hydrolysis facilities with scale advantages but price volatility exposure to monsoon patterns.
- Organic:Certified aquaculture and wild harvest operations command premium positioning in clean-label nutraceutical formulations.
- Non-Organic:Conventional sourcing dominates commodity-grade applications where certification costs exceed value capture.
Supply volume rests with farmed; wild-caught commands the strongest margin position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta processing clusters anchor global fish gelatin manufacturing, with pangasius skin supply chains feeding hydrolysis facilities that serve pharmaceutical and nutraceutical buyers across three continents.
Vietnam
Pangasius aquaculture output from An Giang and Dong Thap provinces supplies raw material for regional hydrolysis facilities. Vietnam's Ministry of Agriculture and Rural Development enforces aquaculture disease control protocols that stabilize skin quality for collagen extraction. Can Tho City hosts integrated processing complexes where toll-manufacturing contracts now dominate procurement relationships with Japanese nutraceutical brands.
United States
Soft-gel dietary supplement manufacturers in New Jersey and California drive pharmaceutical-grade fish gelatin imports. The FDA's Food Safety Modernization Act mandates foreign supplier verification programs that extend approval timelines for Vietnamese processors. Port of Long Beach logistics corridors handle bulk powder shipments destined for contract encapsulation facilities serving direct-to-consumer supplement brands.
Japan
Low-odor formulation requirements from omega-3 encapsulators in Osaka and Tokyo shape technical specifications for imported material. The PMDA enforces pharmaceutical excipient standards that restrict approved supplier lists to processors with species-level documentation systems. Kobe port customs clearance procedures prioritize batch-level traceability for marine-sourced collagen inputs.
Germany
EMA's transmissible spongiform encephalopathy assessment protocols govern pharmaceutical capsule excipient approvals for European manufacturers. The ECHA REACH framework requires batch-level documentation for marine collagen inputs, accelerating qualified supplier consolidation. Hamburg trading houses historically mediated Mekong Delta supply but now face displacement from direct toll-manufacturing arrangements.
India
Domestic soft-gel pharmaceutical production expansion under the PLI scheme creates entry pathways for certified fish gelatin suppliers. CDSCO alignment with ICH guidelines for capsule excipients streamlines import registration procedures. Hyderabad and Mumbai pharmaceutical corridors represent the fastest-emerging demand centers as contract manufacturing organizations scale encapsulation capacity.
Fish Gelatin Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fish gelatin value chain, with integrated processors controlling raw material access while specialized formulators capture premium positioning. The vendor base concentrates among European and Asian operators with captive hydrolysis capabilities or toll-manufacturing relationships. Three archetypes dominate: integrated collagen-to-gelatin processors with Nordic or Mekong Delta sourcing, specialized low-odor formulators serving Japanese nutraceuticals, and toll-manufacturing platforms offering custom hydrolysis services. Capacity expansion and backward integration into captive enzyme supply represent the dominant competitive moves as bloom strength consistency becomes a procurement differentiator.
Within the integrated processor tier, Gelita AG exemplifies Nordic coldwater sourcing strategies, while Weishardt Group anchors European pharmaceutical supply through French manufacturing assets. Among Asian specialists, Nitta Gelatin Inc. occupies a position emphasizing formulation refinement for odor-sensitive applications. These three operators represent contrasting geographic and technical positioning archetypes that structure competitive rivalry across certification tiers.
| Leading Market Players |
|---|
| Weishardt Group |
| Nitta Gelatin Inc. |
| Gelita AG |
| Norland Products Incorporated |
| Lapi Gelatine S.p.A. |
| Vinh Hoan Corporation |
| Kenney & Ross Limited |
| Foodchem International Corporation |
| PB Leiner |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between pharmaceutical and food-grade fish gelatin manifests in both contract pricing and raw material sourcing configurations, with EMA traceability mandates embedding compliance costs that commodity buyers avoid through Mekong Delta spot markets.
Pricing Analysis
Margin tightening in capsule-grade material reflects EMA's 18-24 month approval timelines and species-level documentation burdens that commodity powder grades bypass. Three-tier pricing structure across pharmaceutical, nutraceutical, and food-grade levels separates buyers by certification depth and bloom strength consistency. Price differentiation traces to heavy metal testing protocols and halal accreditation reciprocity rather than volume scale alone. Food manufacturers in Vietnam's confectionery sector exhibit highest price sensitivity, while Japanese nutraceutical brands absorb premium positioning for low-odor formulations.
Supply Chain Analysis
Pharmaceutical-grade qualification gating restricts approved supplier lists to processors with full-chain traceability systems, concentrating certified capacity in Vietnam, France, and Germany. Raw material flows draw from pangasius aquaculture in the Mekong Delta, cod and haddock fisheries in Nordic waters, and enzymatic hydrolysis inputs from captive biotech operations. Single-source vulnerability runs through Vietnam's monsoon-exposed pangasius skin supply. Distribution runs through direct toll-manufacturing arrangements that displace Hamburg trading houses from pharmaceutical procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis technology is displacing traditional acid-extraction methods, compressing yield ratios and restructuring competitive advantage toward biotechnology-capable processors.
For Market Incumbents: Extend backward integration into captive enzyme supply and Nordic coldwater sourcing to defend bloom strength consistency against emerging protease-engineering specialists. Lock in toll-manufacturing contracts with Japanese nutraceutical brands before CDSCO's ICH-aligned registration procedures open Indian pharmaceutical corridors to new entrants. Prioritize EMA pre-approval dossier investment to maintain restricted supplier list status. For New Entrants and Emerging Players: Direct-to-nutraceutical procurement platforms offer the most penetrable route, bypassing entrenched distributor relationships that pharmaceutical-grade certification barriers protect. Target Indian contract manufacturing organizations scaling soft-gel capacity under PLI scheme incentives, where CDSCO's streamlined excipient registration creates entry pathways without EMA's extended timelines. Lead with enzymatic hydrolysis yield advantages and membrane filtration capabilities as technical differentiation. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated collagen processors seeking Southeast Asian manufacturing footprints, with IPO viability tethered to demonstration of consistent pharmaceutical-grade batch approval. Mid-cap specialists with captive Mekong Delta sourcing and in-house protease engineering represent priority acquisition archetypes. Watch for EMA approval timeline compression or halal certification reciprocity breakthroughs as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Scale-Up | Membrane filtration integration enables higher-yield extraction from underutilized fish bone collagen streams. |
| CDSCO Registration Investment | ICH-aligned capsule excipient approvals unlock Indian pharmaceutical manufacturing expansion under PLI incentives. |
| Toll-Manufacturing Contract Expansion | Direct processor relationships with Japanese nutraceutical brands capture margin previously extracted by European distributors. |
| Captive Coldwater Sourcing | Nordic fishery integration secures premium-grade material with superior bloom strength consistency for EMA-regulated clients. |
| Halal Certification Reciprocity Negotiation | Indonesian-Malaysian-Middle Eastern accreditation alignment reduces compliance friction for multinational pharmaceutical buyers. |
Methodological Framework
Trade data from Vietnam's Ministry of Agriculture and Rural Development, EMA transmissible spongiform encephalopathy assessment protocols, and Japanese PMDA pharmaceutical excipient filings formed the secondary backbone. Primary interviews with hydrolysis facility technical directors, pharmaceutical procurement managers at soft-gel manufacturers, CDSCO registration consultants, and Mekong Delta aquaculture operations validated supply chain configurations. Bottom-up volume modeling from pangasius skin availability and top-down value triangulation from contract pricing disclosures cross-checked segment-level outputs.
Bottom-up modeling anchored projections in species-specific collagen yield coefficients and hydrolysis capacity utilization across Vietnamese, French, and German processing facilities. Segmentation dimensions included product form, end-user regulatory tier, application functionality, and raw material provenance. CAGRs derived from weighted average of historical volume trajectories and forward contract coverage ratios, with enzymatic processing adoption curves and halal certification expansion timelines as key sensitivity inputs across the projection horizon.
The model holds under stable EMA approval protocols and continued PLI scheme support in India; deviation in pangasius disease outbreak severity or REACH traceability mandate acceleration would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context and captive sourcing capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Ximenia Oil Market
Ingredients
Dill Seed Oil Market
Ingredients
Pulses Ingredients Market
Ingredients
Potato Granules Market
Ingredients
Cheese Ingredients Market
Ingredients
Wort Concentrate Market
Ingredients
Mung Bean Starch Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Omega 3 Ingredients Market
Ingredients
Mussel Oil and Powder Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Chickpea Fiber Market
Ingredients
United States Wheat Protein Market