
 Calcium Caseinate Market | 2026-2036
Calcium Caseinate Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Caseinate Market Insights
Clean-label extraction technology is reconfiguring how calcium caseinate achieves functional parity with synthetic stabilizers in fortified beverages. Fonterra Co-operative Group leverages its New Zealand dairy network to sustain long-term supply contracts with Asian nutraceutical buyers. FrieslandCampina Ingredients anchors European production capacity through specialized spray-drying facilities in the Netherlands. Arla Foods Ingredients differentiates via vertically controlled milk sourcing that ensures consistent mineral-protein ratios across batches.
Calcium caseinate denotes a milk-derived protein complex produced by precipitating casein with calcium hydroxide, yielding a product containing approximately 90% protein with elevated calcium content and slow gastric emptying properties. Manufacturers employ isoelectric precipitation followed by neutralization and spray-drying to retain functional emulsification and water-binding capacity for processed foods. Powder formats dominate current volume flows due to superior shelf stability and logistical efficiency in bulk ingredient distribution. Sports nutrition applications are expanding fastest as protein fortification extends beyond traditional bodybuilding into mainstream recovery beverages. Food processing units represent the deepest margin pool, given their technical specifications for heat-stable emulsifiers in extended-shelf-life products.
EFSA novel food evaluations and FDA GRAS self-affirmation pathways shape calcium caseinate market access across Europe and North America, with compliance costs filtering smaller traders from premium supply tiers. BIS food additive standards in India and China's SAMR dairy ingredient registrations add further jurisdictional complexity for exporters seeking multi-territory placement. ISO 22000 and FSSC 22000 certifications function as baseline qualifiers rather than differentiators in tender processes for multinational buyers. Stakeholders must monitor evolving protein origin disclosure requirements, as regulatory bodies tighten traceability mandates that could restructure sourcing relationships between dairy processors and finished goods manufacturers.
Market Dynamics
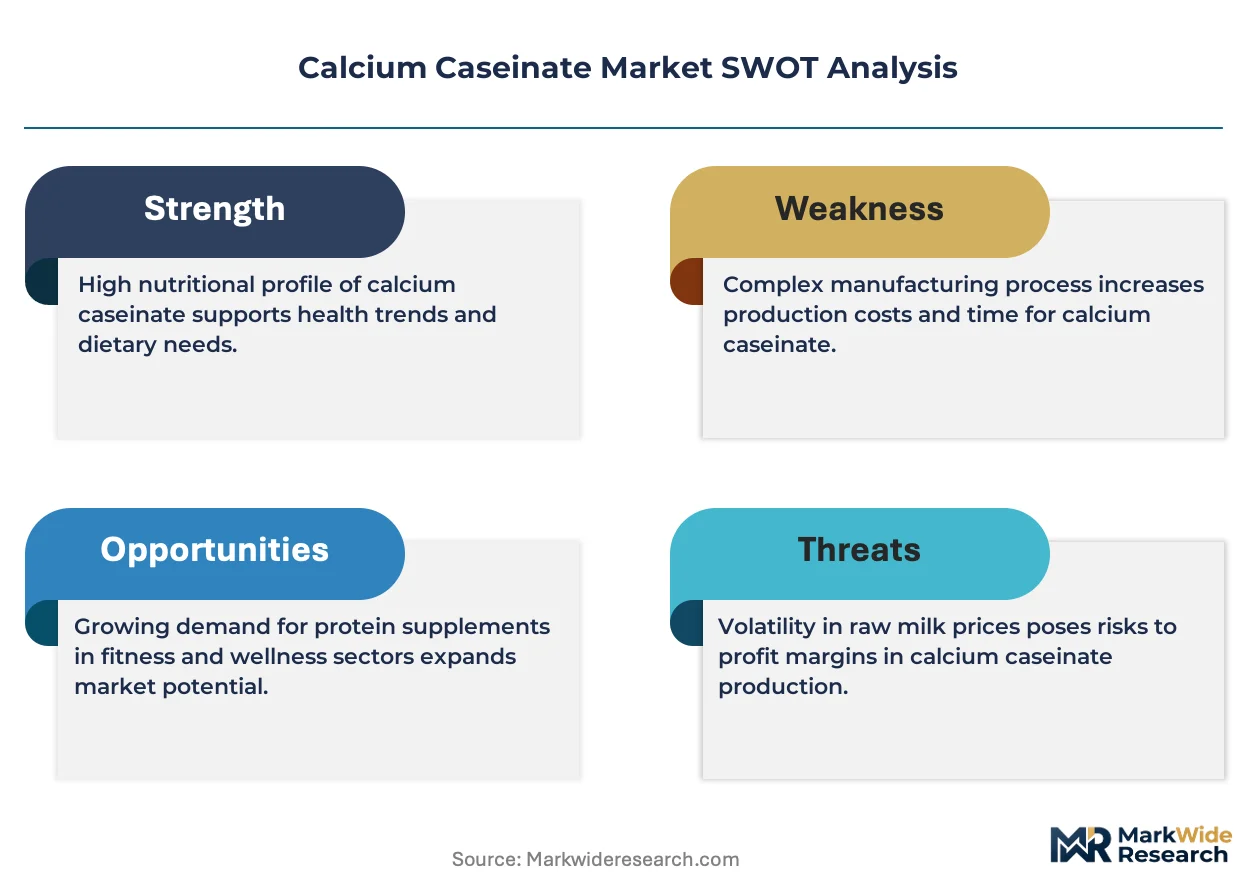
Clean-label extraction protocols are forcing dairy processors to rebuild their precipitation and drying infrastructure around minimally processed output, compressing margins for operators still running legacy isoelectric systems.
Growth Catalysts
- EFSA novel food evaluations:Accelerated approval pathways for enzymatically modified caseinates are opening premium positioning in fortified beverages across EU member states.
- Sports nutrition formulations:Athletes and fitness consumers are pivoting toward slow-digesting protein sources for overnight recovery applications, pulling calcium caseinate into mainstream ready-to-drink products.
- German precision dairy infrastructure:Concentrated spray-drying capacity in Bavaria and Lower Saxony enables high-purity output for export markets demanding consistent mineral-protein ratios.
Market Restraints
- Skim milk powder price volatility:Input cost swings tied to New Zealand and EU dairy auction cycles squeeze margin predictability for caseinate manufacturers without backward integration into milk sourcing.
- Supply concentration in Oceania:Fonterra's dominance in milk protein isolate production creates bottleneck risk for calcium caseinate processors dependent on external casein streams.
- Plant protein substitution:Pea and fava protein isolates are capturing share in sports nutrition, pressuring caseinate pricing in mid-tier powder segments.
Strategic Opportunities
- India BIS food additive standards:Streamlined registration pathways for dairy-derived ingredients are lowering market entry barriers for exporters targeting nutraceutical contract manufacturers in Mumbai and Hyderabad.
- Medical nutrition applications:Enteral feeding formulations for sarcopenia patients represent an underserved application with higher formulation tolerance than commodity sports powders.
- China SAMR dairy ingredient registrations:Accelerated review timelines for GRAS-equivalent substances are creating first-mover advantages for processors with pre-submitted dossiers.
Industry Challenges
- FSSC 22000 certification timelines:Extended audit backlogs at accredited bodies are delaying tender eligibility for multinational food manufacturers with strict supplier qualification windows.
- Traceability system integration:Mandatory blockchain-linked origin disclosure requirements in EU and UK markets are forcing legacy ERP upgrades that strain mid-cap processor IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Caseinate Market |
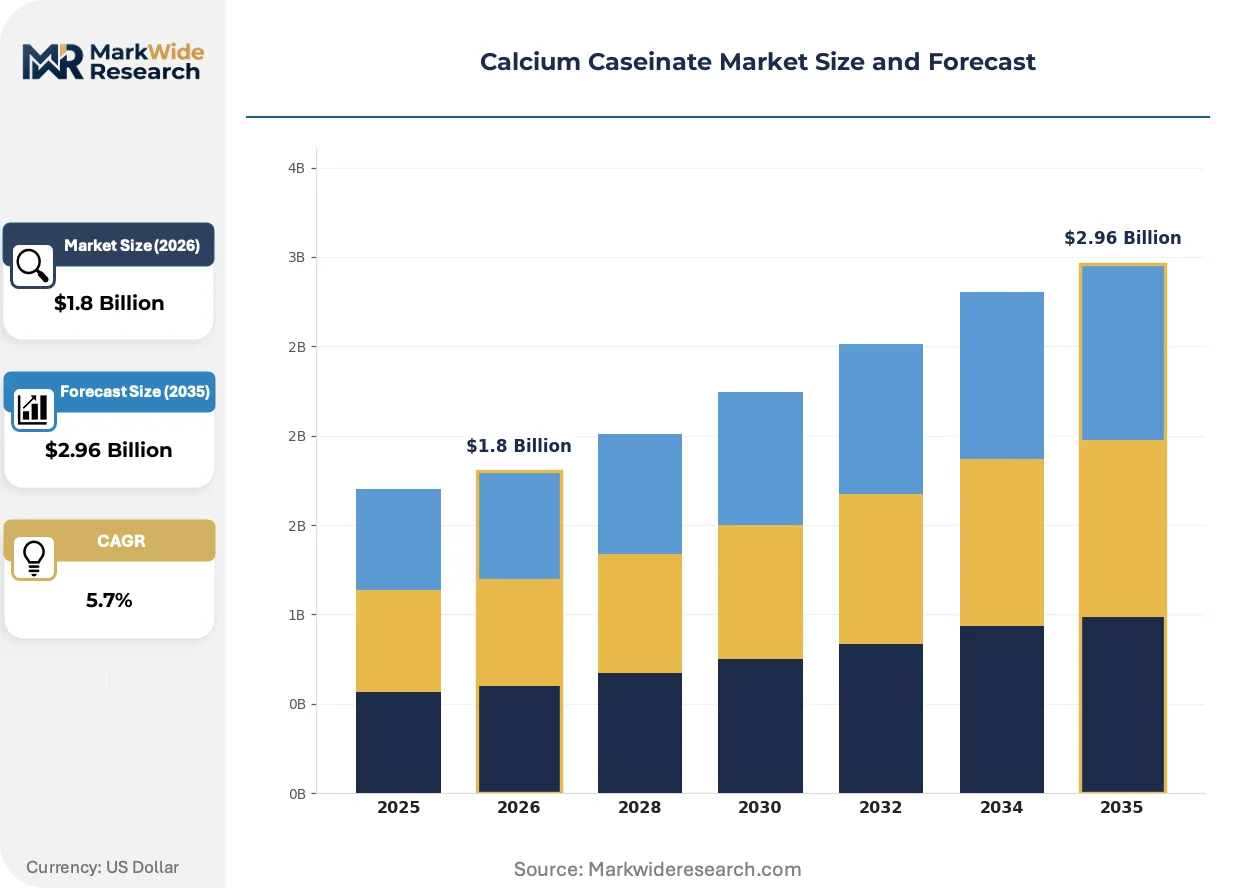
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Instant, Microencapsulated, Spray-Dried Application: Infant Nutrition, Sports Nutrition, Bakery, Dairy Alternatives, Confectionery End User: Food Processing Units, Nutraceutical Manufacturers, Beverage Producers, Cosmetic Firms Packaging Type: Stand-Up Pouches, Bulk Bags, Drums, Valved Bags, Cartons |
| Companies Covered | Fonterra Co-operative Group, FrieslandCampina Ingredients, Arla Foods Ingredients, Lactalis Ingredients, Kerry Group, AMCO Proteins, Armor Protéines, EPI Ingredients, Hoogwegt Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Caseinate Market Trends and Innovations
Enzymatic modification and membrane filtration are collapsing the functional gap between native caseinates and chemically stabilized alternatives, redrawing competitive boundaries across beverage and medical nutrition segments.
Membrane-based microfiltration is collapsing energy and water intensity benchmarks for casein separation, replacing traditional acid precipitation with ceramic membrane cascades that preserve native protein structure. Dairy processors in the Netherlands and Denmark are retrofitting existing spray-dry towers to handle these gentler feed streams. The technology is collapsing capital barriers for regional entrants previously excluded by the scale economics of acid-whey disposal.
EU F-Gas Regulation phase-down schedules are pressuring spray-drying operations to abandon conventional refrigerants in favor of heat-pump-assisted drying or mechanical vapor recompression systems. Industrial consequence includes 15-25% throughput penalties during retrofit periods and accelerated obsolescence of aging facilities in Southern Europe. German and Polish processors with newer installations are absorbing displaced contract volumes from Italian and Spanish competitors facing extended downtime.
Direct-to-brand ingredient sourcing is fragmenting traditional distribution through dairy traders and commodity houses, with finished goods manufacturers in sports nutrition and clinical nutrition establishing direct technical relationships with caseinate producers. This disintermediation compresses trader margins while demanding enhanced regulatory dossier support and co-development capabilities from processors. The pattern is most visible in Nordic markets where Arla Foods Ingredients and local brands have pioneered transparent origin labeling partnerships.
Calcium Caseinate Market Segmentation
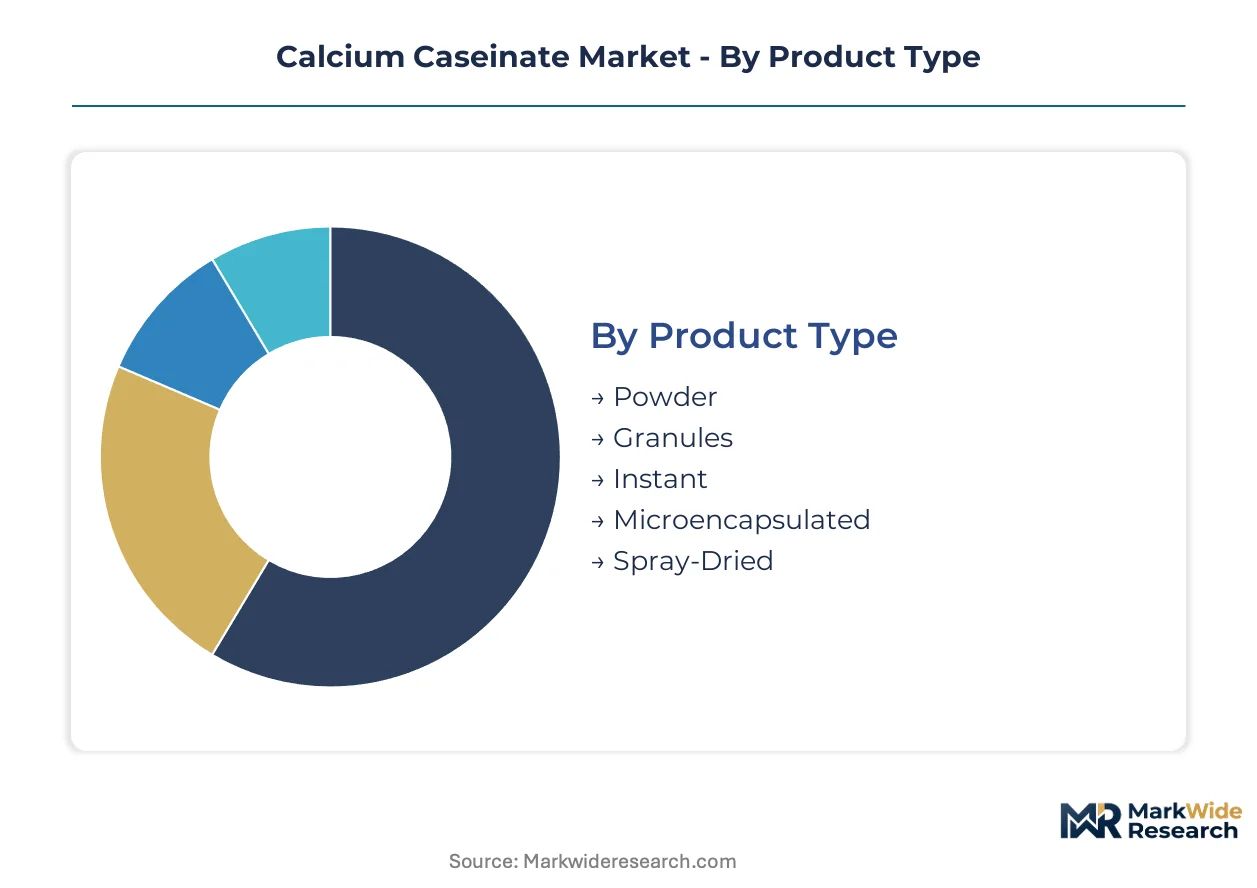
Calcium caseinate exhibits divergent performance characteristics across physical formats and end-use specifications, forcing processors to align precipitation and drying investments with downstream technical requirements rather than commodity protein economics.
Product Type:
After-sales technical support intensity escalates with formulation complexity, as instant and microencapsulated grades demand sustained co-development relationships with finished goods manufacturers.
- Powder:Standard spray-dried format with 90% protein content and 12-month ambient stability dominates bulk ingredient procurement for food processing units in Germany and the Netherlands. Demand concentrates in extended-shelf-life applications where heat-stable emulsification properties outweigh solubility premiums.
- Instant:Agglomerated particles with enhanced dispersibility command formulation support resources from Arla Foods Ingredients and FrieslandCampina for ready-to-drink beverage manufacturers. Sports nutrition brands in Denmark and Sweden prioritize this grade for protein fortification without high-shear mixing equipment.
- Granules:Intermediate particle size for controlled dissolution in enteral feeding applications.
- Microencapsulated:Lipid-coated variants masking bitter notes for functional food matrices.
- Spray-Dried:Conventional format serving cost-sensitive bakery and confectionery compounders.
By volume, Powder leads. By growth pace, Instant is ahead.
Application:
Margin capture potential varies sharply across application tiers, with clinical and performance nutrition segments tolerating purity premiums that commodity food processing rejects.
- Sports Nutrition:Overnight recovery positioning drives slow-digesting protein demand from endurance athletes and bodybuilders in Nordic markets. Ready-to-drink formulations in Germany and France require instant-grade solubility specifications that filter out commodity suppliers lacking technical service capabilities.
- Infant Nutrition:Mineral-protein ratio consistency mandates vertically controlled milk sourcing from Arla Foods Ingredients for hypoallergenic formula manufacturers. EFSA novel food evaluations and traceability requirements compress the qualified supplier base to ISO 22000-certified processors with batch-level documentation systems.
- Bakery:Heat-stable emulsification for extended shelf-life bread and pastry applications.
- Dairy Alternatives:Functional protein fortification in plant-based beverage systems.
- Confectionery:Water-binding capacity for reduced-fat chocolate and caramel matrices.
Sports Nutrition generates the steepest expansion trajectory, while Infant Nutrition retains the deepest margin pool.
End User:
Procurement sophistication divides the customer base between multinational manufacturers with FSSC 22000 mandates and regional compounders prioritizing logistical flexibility over certification depth.
- Food Processing Units:Volume concentration in German and Polish meat and bakery sectors demands consistent emulsification performance across seasonal milk protein input variation. These buyers negotiate annual contracts with mineral-protein ratio specifications that smaller processors cannot guarantee.
- Nutraceutical Manufacturers:Mumbai and Hyderabad contract manufacturers drive demand for microencapsulated and instant grades under streamlined BIS food additive registration pathways. Direct technical relationships with European processors are displacing traditional trader intermediation.
- Beverage Producers:Ready-to-drink fortification requiring cold-process solubility without sedimentation.
- Cosmetic Firms:Film-forming properties for hair and skin conditioning applications.
Food Processing Units anchor volume flows. Nutraceutical Manufacturers are climbing the fastest.
Packaging Type:
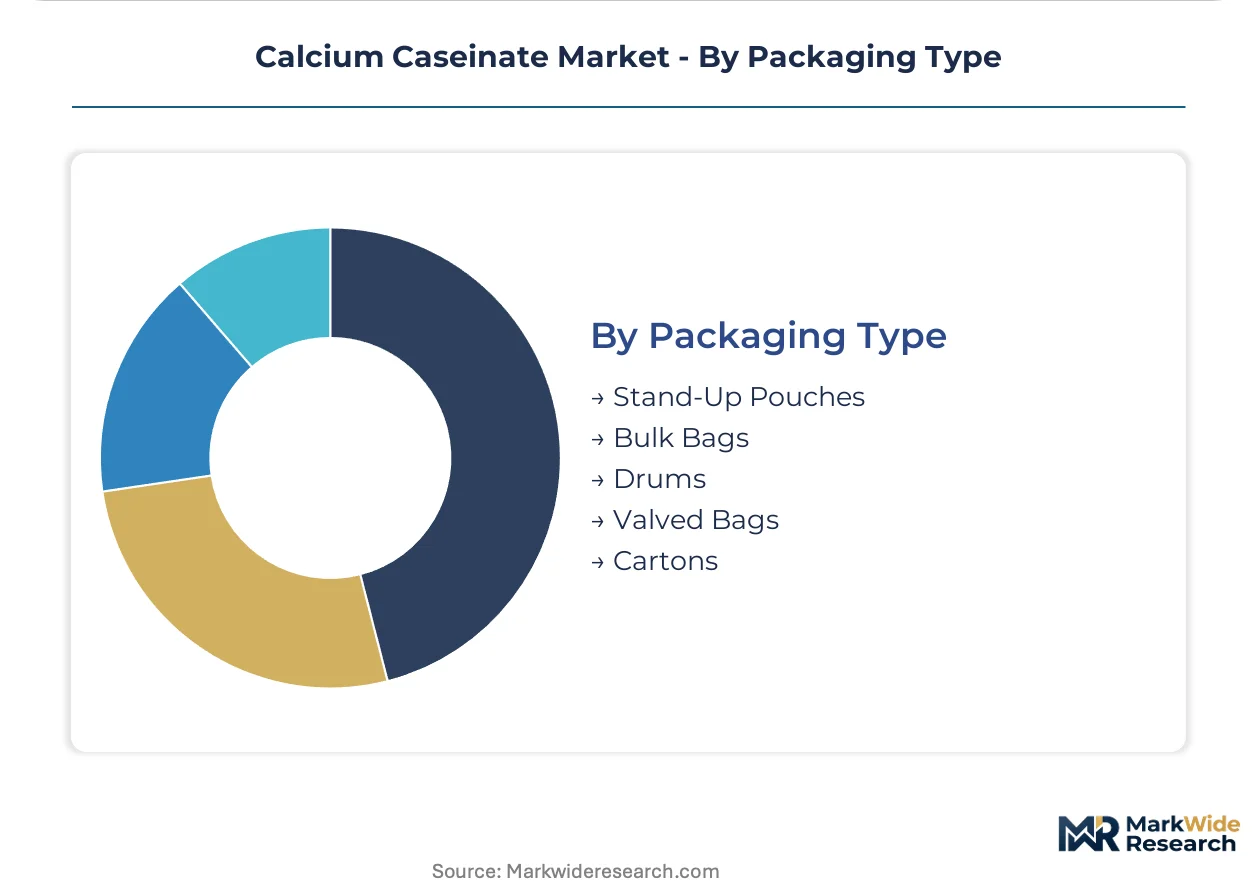
Handling automation requirements and contamination risk profiles dictate packaging selection, with valved and bulk formats dominating ingredient-grade shipments while retail-facing formats remain negligible.
- Bulk Bags:One-tonne flexible intermediate bulk containers with liner systems serve dairy processors and food manufacturers with pneumatic conveying infrastructure in Bavaria and Lower Saxony. German precision dairy infrastructure supports high-purity output for export markets demanding intact packaging seals through multi-modal transport.
- Valved Bags:25-kilogram formats with dust-free discharge enable manual handling at nutraceutical contract manufacturers in India lacking bulk handling systems. SAMR dairy ingredient registration holders in China specify this format for first-landing customs inspection efficiency.
- Stand-Up Pouches:Limited adoption for specialty cosmetic and small-batch nutraceutical applications.
- Drums:Steel containment for moisture-sensitive microencapsulated grades.
- Cartons:Corrugated secondary packaging for retail-channel protein supplements.
Bulk Bags dominate tonnage movements. Valved Bags are gaining share fastest among export-oriented processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision dairy infrastructure channels high-purity calcium caseinate exports toward Asian nutraceutical contract manufacturers and Nordic sports nutrition brands, establishing a transcontinental trade corridor anchored by Bavarian spray-drying capacity.
Germany
Sports nutrition brands in Denmark and Sweden source instant-grade calcium caseinate from Bavarian and Lower Saxony processors for ready-to-drink recovery formulations. EFSA novel food evaluation pathways for enzymatically modified caseinates accelerate premium positioning in fortified beverages across EU member states. Precision dairy clusters in Bavaria sustain high-purity output for export markets demanding consistent mineral-protein ratios through multi-modal transport.
Netherlands
Membrane filtration retrofit projects at FrieslandCampina facilities serve European beverage manufacturers seeking clean-label emulsification alternatives. EU F-Gas Regulation phase-down schedules pressure spray-drying operations toward heat-pump-assisted systems, creating 15-25% throughput penalties during transition periods. Specialized spray-drying infrastructure in the Netherlands anchors regional production capacity for heat-stable protein ingredients.
India
Nutraceutical contract manufacturers in Mumbai and Hyderabad drive demand for microencapsulated and instant grades under streamlined BIS food additive registration pathways. FSSAI dairy ingredient standards and CDSCO quality mandates shape import compliance frameworks for European exporters. Direct technical relationships between Indian compounders and European processors displace traditional trader intermediation in ingredient procurement.
China
SAMR dairy ingredient registrations for GRAS-equivalent substances create first-mover advantages for processors with pre-submitted dossiers targeting clinical nutrition applications. Accelerated review timelines attract European caseinate exporters seeking placement in enteral feeding formulations. Yangtze River Delta nutraceutical manufacturers specify valved bag formats for customs inspection efficiency at first-landing ports.
United States
FDA GRAS self-affirmation pathways shape calcium caseinate market access for sports nutrition and medical nutrition applications. Sports nutrition brands pivot toward slow-digesting protein sources for overnight recovery positioning in mainstream ready-to-drink products. Midwest dairy processing corridors supply casein streams to domestic caseinate manufacturers serving fortified beverage compounders.
Calcium Caseinate Market Competitive Landscape
On the supply side, the industry is consolidating around dairy cooperatives with backward integration into milk sourcing and specialized ingredients divisions of multinational nutrition conglomerates. Three archetypes dominate: Oceania-based dairy cooperatives controlling casein isolate supply, European dairy processors with precision spray-drying infrastructure, and diversified nutrition ingredient houses with cross-portfolio formulation capabilities. Capacity expansion in membrane filtration technology and direct-to-brand technical service relationships represent the dominant competitive moves reshaping procurement patterns.
Within the cooperative tier, Fonterra Co-operative Group exemplifies supply-side concentration through its New Zealand dairy network and long-term Asian supply contracts. FrieslandCampina Ingredients and Arla Foods Ingredients occupy positions in the European precision processing segment, with the former anchoring Netherlands-based spray-drying capacity and the latter representing vertically controlled milk sourcing architectures. These three entities collectively illustrate how geographic origin and organizational structure determine competitive positioning in mineral-protein ingredient supply.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| FrieslandCampina Ingredients |
| Arla Foods Ingredients |
| Lactalis Ingredients |
| Kerry Group |
| AMCO Proteins |
| Armor Protéines |
| EPI Ingredients |
| Hoogwegt Group |
| Others |
Pricing and Supply Chain Analysis
Bavarian spray-drying clusters concentrate high-purity calcium caseinate capacity that filters downstream pricing power toward processors with backward integration into milk sourcing and membrane filtration infrastructure. Input cost swings from New Zealand and EU dairy auction cycles compress margin predictability for operators lacking captive casein supplies, while clean-label extraction investments reshape competitive pricing tiers.
Pricing Analysis
Legacy acid-precipitation systems, transitional membrane filtration installations, and next-generation enzymatic modification platforms anchor three distinct pricing tiers in calcium caseinate procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth—FSSC 22000 and ISO 22000 tiers command formulation support premiums—while volume scale and after-sales technical service intensity differentiate contract terms. Cost compression in standard-grade powder segments intensifies because pea and fava protein isolates capture mid-tier sports nutrition share. Nutraceutical contract manufacturers in India exhibit highest price sensitivity due to BIS registration cost burdens, whereas infant formula compounders tolerate purity premiums for vertically controlled mineral-protein consistency.
Supply Chain Analysis
Tariff exposure between New Zealand and China dominates supply chain risk calculus for calcium caseinate processors dependent on Fonterra's casein isolate streams. Production gravity centers on Germany, the Netherlands, and New Zealand, with Bavarian and Lower Saxony facilities feeding Nordic sports nutrition brands while Dutch membrane filtration retrofits serve beverage manufacturers. Raw material dependencies rest on skim milk powder, calcium hydroxide precipitation agents, and ceramic membrane cascades. Single-source vulnerability from Fonterra's Oceania dominance creates bottleneck exposure for external caseinate processors. Distribution runs through dairy ingredient traders and direct-to-brand technical relationships, with finished goods manufacturers in sports and clinical nutrition fragmenting traditional commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium caseinate incumbents face substitution defense imperatives as plant protein isolates capture formulation share in mid-tier sports nutrition segments, demanding strategic repositioning toward functional performance advantages that pea and fava proteins cannot replicate.
For Market Incumbents: Pre-empt plant protein encroachment by accelerating membrane filtration capacity additions in Bavaria and Lower Saxony to deliver clean-label functional parity at cost structures legacy acid-precipitation competitors cannot match. Anchor backward integration into milk sourcing to neutralize skim milk powder price volatility from New Zealand auction cycles. Defensive consolidation through FSSC 22000 certification depth filters tender eligibility for multinational food manufacturers with strict supplier qualification windows. For New Entrants and Emerging Players: Pursue white-space positioning in Indian nutraceutical contract manufacturing, where streamlined BIS food additive registrations lower market entry barriers relative to saturated European sports nutrition channels. Target microencapsulated and instant grades for Mumbai and Hyderabad compounders lacking European technical service relationships. Go-to-market leverage rests on direct processor relationships that displace trader intermediation and enable co-development partnerships for ready-to-drink beverage formulations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane filtration retrofit specialists with installed spray-drying infrastructure and established SAMR dairy ingredient registration dossiers for Chinese clinical nutrition placement. Long-term viability across the projection horizon hinges on enteral feeding formulation expansion for sarcopenia applications, where higher formulation tolerance supports margin premiums unavailable in commodity sports powders. Acquisition target archetype: European precision processors with vertically controlled milk sourcing and pre-submitted China regulatory pathways. Signal to watch: accelerated SAMR review timelines for GRAS-equivalent substances as inflection indicator for first-mover advantage realization.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Netherlands and Danish processors preserve native protein structure while collapsing energy intensity benchmarks. |
| Backward Integration into Milk Sourcing | Arla Foods Ingredients and FrieslandCampina neutralize input cost volatility through captive supply chains. |
| Direct-to-Brand Technical Relationships | Nordic sports nutrition brands bypass commodity traders for transparent origin labeling partnerships. |
| SAMR Dairy Ingredient Registration | Pre-submitted dossiers create first-mover placement in Yangtze River Delta enteral feeding formulations. |
| FSSC 22000 Certification Investment | Baseline qualification for multinational food manufacturer tender eligibility filters smaller competitors. |
Research Methodology
The analysis maps spray-dried, instant, and microencapsulated calcium caseinate grades, each validated through dairy processor technical directors, nutraceutical contract manufacturing procurement leads, and infant formula compounder regulatory affairs specialists. Primary interview intelligence triangulates against secondary validation from EFSA novel food evaluation databases, FDA GRAS self-affirmation filings, SAMR dairy ingredient registration records, and BIS food additive standard documentation. Bottom-up volume modeling across product type, application, and end-user segments reconciles with top-down trade flow analysis from German, Dutch, and New Zealand customs data.
Forecast assumptions hold fixed EFSA and FDA regulatory pathway timelines, EU F-Gas Regulation phase-down schedules, and plant protein substitution rates in sports nutrition, while varying membrane filtration adoption curves and China SAMR review acceleration scenarios. Segmentation dimensions span physical format, end-use specification, packaging automation requirements, and regional regulatory cluster. CAGRs derive from installed capacity utilization trajectories, substitution elasticity estimates between caseinate and plant protein isolates, and enteral feeding formulation penetration models for sarcopenia applications.
Sensitivities concentrate around skim milk powder auction cycle volatility, Fonterra supply concentration disruption scenarios, and blockchain-linked traceability mandate implementation timelines that could restructure sourcing relationships. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Marine Peptides Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Middle East and Africa Pea Starch Market
Ingredients
Phytogenic Market
Ingredients
Honey Powder Market
Ingredients
Gluten-Free Flour Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Cacao Bean Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Malted Barley Flour Market
Ingredients
Dry Blended Products Market
Ingredients
Tuberose Extract Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
Fish Peptones Market
Ingredients
Fermented Rennet Market