
 Agave Inulin Market | 2026-2036
Agave Inulin Market Size, Share, and Industry Trends Forecast 2026-2036
Agave Inulin Market Outlook
Organic certification tier migration is unwinding conventional supply contracts across the agave inulin value chain. Ingredion Incorporated leverages its corn-processing infrastructure to achieve manufacturing scale in prebiotic ingredients. Beneo GmbH sustains European market anchorage through sustained chicory and agave dual-sourcing. Naturel West Corp specializes in Jalisco-origin organic grades, occupying a premium channel position in North American natural retail.
Agave inulin is a fructan polysaccharide extracted from Agave tequilana Weber blue variety, comprising beta-(2,1)-linked fructose chains with terminal glucose units, typically ranging from 2 to 60 degrees of polymerization; it functions as a soluble dietary fiber and prebiotic bulking agent in reduced-sugar formulations. Organic inulin commands margin concentration due to certification scarcity and three-year field conversion requirements, while conventional inulin retains volume leadership in cost-sensitive bakery applications. Food and beverage end-use dominates throughput, though pharmaceutical-grade specifications for enhanced inulin are attracting quality-premium positioning.
FDA GRAS determinations and EFSA health claim assessments shape market access thresholds for prebiotic positioning in the United States and European Union respectively, with Mexico's national organic certification aligning to USDA NOP equivalency for cross-border organic trade. Stakeholders must monitor evolving fiber definition rulemakings across multiple jurisdictions, as regulatory reclassification of inulin's fiber status directly alters permissible label claims and formulation economics. The decisive variable remains certification-grade supply security rather than commodity volume expansion.
Market Dynamics
Organic certification scarcity is compressing supply timelines while FDA GRAS determinations for novel prebiotic claims create dual-track regulatory pathways that favor established processors with compliance infrastructure.
Growth Catalysts
- Clean-label prebiotic demand:Functional beverage formulators in North America are reformulating reduced-sugar lines with agave inulin as a soluble fiber bulking agent, bypassing synthetic alternatives.
- EFSA Article 13.1 health claims:Successful dossier submissions for digestive health positioning unlock premium pricing in EU member state retail channels.
- Jalisco highland agave concentration:Mexico's blue agave terroir delivers consistent fructan profiles that industrial buyers specify in multi-year supply agreements.
Market Restraints
- Three-year organic conversion lag:USDA NOP certification requires field transition periods that prevent rapid supply response to spot organic premiums.
- Chicory inulin substitution:European processors with established chicory extraction capacity can switch feedstocks when agave prices spike, capping price elasticity.
- Single-origin supply risk:Raw agave dependence on Mexico's Jalisco, Guanajuato, and Michoacán states exposes processors to climate volatility and agricultural policy shifts.
Strategic Opportunities
- Pharmaceutical-grade inulin:Enhanced purification protocols for high-DP (degree of polymerization) fractions target drug delivery and nutraceutical encapsulation applications.
- Direct-to-manufacturer e-procurement:Bulk ingredient platforms are disintermediating traditional distributor layers for mid-volume bakery and confectionery buyers.
- USDA BioPreferred program:Federal procurement preferences for biobased products create a mandated demand floor for domestic-blended prebiotic formulations.
Industry Challenges
- GRAS self-determination documentation:FDA notification pathway complexity requires specialized regulatory affairs capacity that smaller processors lack.
- Fructan chain-length standardization:Lot-to-lot DP variability complicates consistent functional performance in precision fermentation feedstock applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agave Inulin Market |
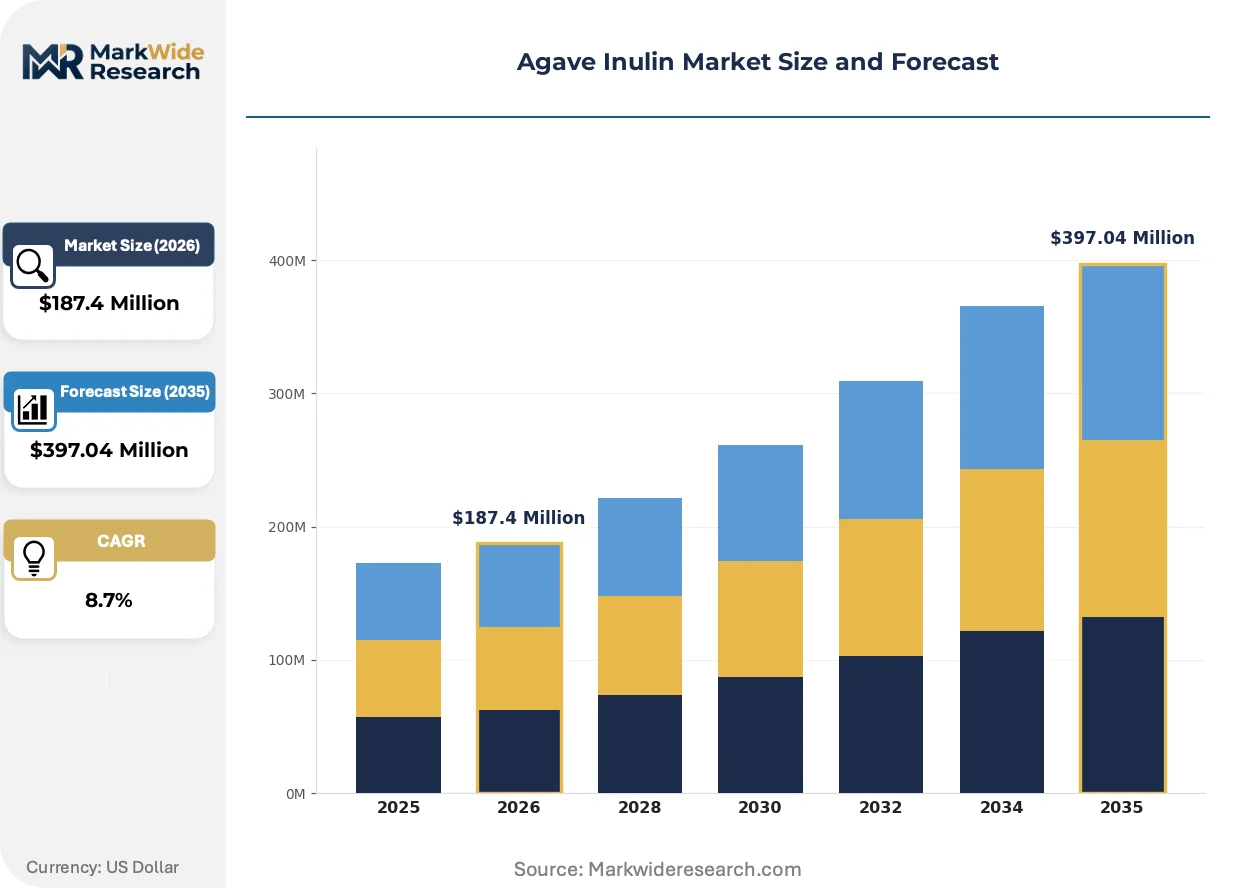
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Inulin, Conventional Inulin, Enhanced Inulin, Native Inulin Application: Food & Beverage, Pharmaceuticals, Nutritional Supplements, Cosmetics End User: Manufacturers, Retailers, Distributors, Food Service Providers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Naturel West Corp, Sensus, The Tierra Group, AGAVE CANADA, Nutra Food Ingredients, LOC Industries, Maretai Organics, Ingredion Incorporated, Beneo GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agave Inulin Market Strategic Shifts
Extraction technology diffusion and regulatory claim pathways are simultaneously expanding addressable applications and compressing margin structures for commodity-grade supply.
Membrane filtration is fragmenting the traditional thermal concentration monopoly in agave inulin processing. Mid-scale Mexican processors are deploying ceramic ultrafiltration skids to achieve food-grade purity without energy-intensive evaporation stages. This capital-light approach is fragmenting market share concentration among legacy thermal processors and enabling regional supply fragmentation.
EFSA's 2024 updated guidance on prebiotic substantiation demands human intervention trials with validated biomarkers, raising dossier preparation costs. European formulators are consolidating supplier relationships to processors with existing positive opinions, compressing the vendor base. Premium organic grades face the steepest compliance burden as EFSA scrutiny disproportionately targets health-positioned products.
Certificate-of-analysis purchasing is displacing long-term contracting for conventional inulin grades. North American bakery manufacturers are spot-buying through ingredient trading platforms, shortening procurement cycles from annual to quarterly. This behavior is most pronounced in cost-sensitive private-label channels where formulation flexibility trumps supply security.
Agave Inulin Market Segmentation
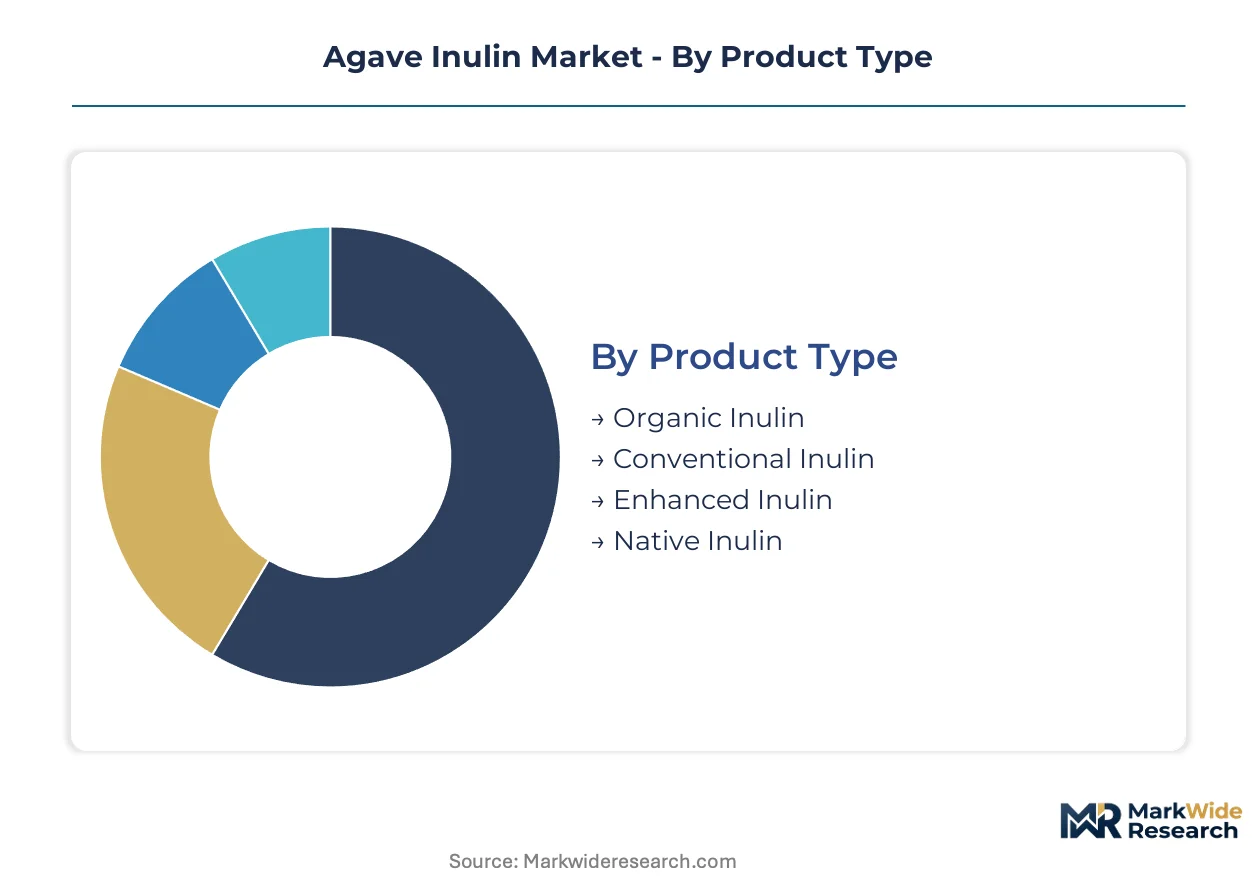
Segmentation in agave inulin reveals how certification grade, application purity requirements, and channel economics split procurement behavior. Buyers optimize across these dimensions to balance label claims, formulation performance, and landed cost.
Product Type:
Organic inulin draws disproportionately from Jalisco highland exports to US natural retail, while conventional grades serve domestic Mexican bakery chains and cost-sensitive North American manufacturers.
- Organic Inulin:Derived from USDA NOP-certified blue agave fields with three-year conversion timelines, this grade carries fructan purity above 90% and terminal glucose specifications that satisfy clean-label positioning. Premium beverage formulators in California and Texas specify organic certificates for prebiotic positioning in kombucha and functional waters. The three-year field transition creates supply inelasticity that processors exploit through forward contracting.
- Conventional Inulin:Standard-grade extraction from non-certified agave delivers equivalent DP distribution at 40-60% lower unit cost. Mexican domestic bakery manufacturers and US private-label cookie producers absorb volume here, prioritizing bulking functionality over certification claims. Jalisco processors maintain dedicated conventional lines to preserve organic integrity in parallel facilities.
- Enhanced Inulin:High-DP fractions above 25 degrees of polymerization target pharmaceutical encapsulation and precision fermentation feedstocks.
- Native Inulin:Unhydrolyzed fructan chains retain natural agave oligosaccharide complexity for artisanal food applications.
Conventional inulin commands the established base. The steepest expansion runs through organic certification tiers.
Application:
Pharmaceutical and nutraceutical buyers impose the strictest certificate-of-analysis requirements, while food and beverage procurement tolerates broader DP variability.
- Food & Beverage:Reduced-sugar formulation drives soluble fiber incorporation across dairy alternatives, sports drinks, and bakery. North American clean-label momentum positions agave inulin against corn-derived resistant dextrin, with taste neutrality and prebiotic substantiation as comparative advantages. EFSA Article 13.1 dossier costs concentrate this demand among processors with existing positive opinions.
- Pharmaceuticals:Enhanced purification to injectable-grade standards unlocks drug delivery applications where inulin functions as excipient and stabilizer. European contract manufacturers specify high-DP fractions for parenteral formulations, with lot-to-lot consistency requirements that exclude smaller Mexican processors.
- Nutritional Supplements:Capsule and powder prebiotic products target digestive health positioning in direct-to-consumer channels.
- Cosmetics:Humectant and film-forming properties drive inclusion in natural skincare formulations.
Food and beverage absorbs the volume base. Pharmaceutical-grade specifications are climbing the fastest.
End User:
Manufacturer procurement consolidates around multi-year supply agreements, while food service and retail channels fragment across spot purchasing.
- Manufacturers:Industrial formulators in baked goods, dairy, and beverages negotiate annual or multi-year contracts with specified DP ranges and organic certification tiers. Ingrediention and Beneo leverage established GRAS notifications to secure preferred supplier status with multinational CPG accounts.
- Retailers:Private-label prebiotic supplement brands and natural grocery chains source through distributor intermediaries with certificate-of-analysis requirements.
- Distributors:Regional ingredient traders bridge small and mid-volume buyers to Mexican processors.
- Food Service Providers:Commercial bakery and beverage operations purchase conventional grades through broadline distribution.
Manufacturers anchor contract volume. Retailer direct-sourcing is expanding most quickly.
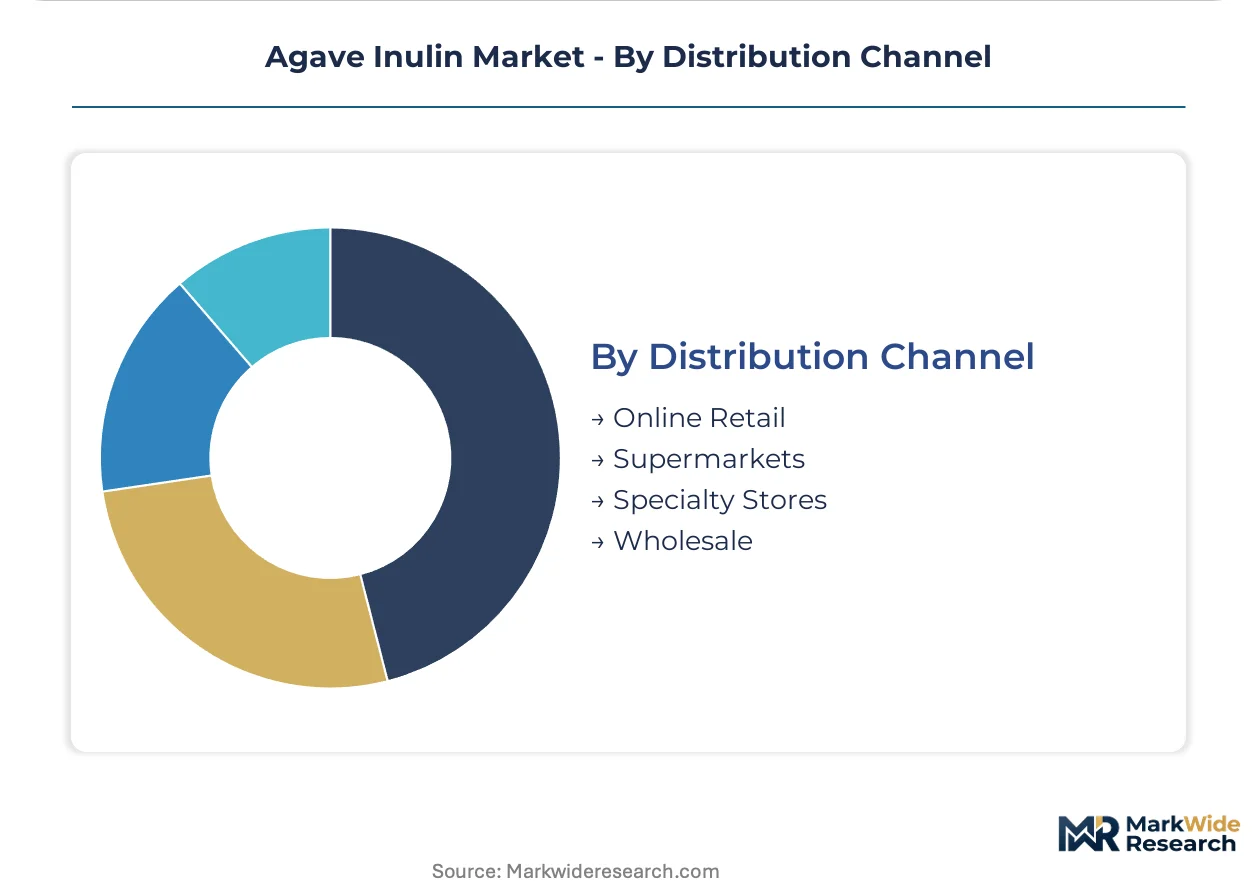
Distribution Channel:
Online platforms disintermediate traditional wholesale layers for mid-volume buyers, while specialty stores concentrate premium organic grades.
- Online Retail:Bulk ingredient marketplaces and processor-direct portals enable quarterly spot purchasing for bakery and confectionery manufacturers previously locked into annual distributor contracts. Naturel West Corp and comparable Jalisco-origin specialists use e-procurement to capture margin otherwise absorbed by importer-distributors.
- Supermarkets:Mass retail channels for finished prebiotic supplements and functional foods drive packaged goods placement rather than bulk ingredient flow.
- Specialty Stores:Natural products retailers and co-op distribution networks prioritize USDA NOP-certified organic grades with transparent supply chain documentation.
- Wholesale:Traditional ingredient distributors maintain relevance for large manufacturers requiring technical service and formulation support.
Wholesale retains the volume base. Online retail channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blue agave cultivation concentrates in Mexico's Jalisco highlands, binding processor economics to a single terroir. The United States and Germany absorb premium organic grades for functional beverage and pharmaceutical applications. Regulatory divergence between FDA GRAS pathways and EFSA health claim requirements fragments market access protocols.
United States
California and Texas beverage formulators drive organic inulin procurement for kombucha and functional water lines. FDA GRAS self-determination notifications for novel prebiotic claims require specialized regulatory affairs capacity that favors established importers. Jalisco-origin shipments through Laredo and San Diego ports supply West Coast clean-label manufacturers.
Mexico
Jalisco, Guanajuato, and Michoacán states host the concentrated blue agave cultivation base for fructan extraction. Mexico's national organic certification aligns to USDA NOP equivalency, enabling seamless cross-border organic trade. Tequila corridor processors in Arandas and Atotonilco maintain dedicated organic and conventional production lines.
Germany
European pharmaceutical contract manufacturers specify high-DP inulin fractions for parenteral drug delivery applications. EFSA Article 13.1 health claim dossiers for digestive positioning concentrate procurement among processors with existing positive opinions. Hamburg and Frankfurt ingredient distributors bridge Mexican supply to EU formulators.
Canada
Health Canada natural health product regulations govern prebiotic supplement positioning in domestic retail channels. Toronto and Vancouver natural products distributors source USDA NOP-certified grades for organic private-label brands. AGAVE CANADA represents domestic import-processing capacity for North American distribution.
Netherlands
Rotterdam port logistics and Amsterdam-headquartered ingredient traders consolidate EU-bound agave inulin flows. REACH compliance documentation for novel food ingredients adds regulatory layering for non-traditional suppliers. Beneo GmbH's European chicory-agave dual-sourcing anchors continental prebiotic supply security.
Agave Inulin Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with membrane filtration specialists competing against thermal concentration legacy operators. The vendor base organizes around three strategic tiers: multinational ingredient platforms with GRAS infrastructure, Jalisco-origin organic specialists with terroir positioning, and regional distributors with formulation technical service. Consolidation pressure runs through M&A activity among mid-scale Mexican processors and strategic partnerships between European traders and highland extraction facilities.
Among North American market participants, Ingredion Incorporated leverages established corn-processing infrastructure to achieve manufacturing scale in prebiotic ingredients, while Beneo GmbH sustains European anchorage through sustained chicory and agave dual-sourcing strategies. Naturel West Corp occupies a premium channel position in natural retail through Jalisco-origin organic specialization. These three entities represent distinct competitive archetypes: scale-driven platform diversification, continental multi-source security, and single-origin certification depth.
| Leading Market Players |
|---|
| Naturel West Corp |
| Sensus |
| The Tierra Group |
| AGAVE CANADA |
| Nutra Food Ingredients |
| LOC Industries |
| Maretai Organics |
| Ingredion Incorporated |
| Beneo GmbH |
| Others |
Value Chain & Pricing Dynamics
Three-year organic conversion timelines stretching across Jalisco highland fields compress supply elasticity and anchor pricing power with certified processors holding forward-contracted inventory. This lead-time rigidity intersects with FDA GRAS notification requirements to stratify procurement costs between established importers and spot-market buyers.
Pricing Analysis
USDA NOP certification dictates the pricing tier structure across organic, conventional, and pharmaceutical-grade segments. Three-tier pricing structure across premium organic, standard conventional, and economy bulk grades separates Jalisco-origin certified supply from non-certified Mexican domestic channels. Cost compression in conventional grades is intensifying because membrane filtration entrants fragment thermal-processor margins. Private-label bakery manufacturers exhibit highest price sensitivity, while pharmaceutical contract manufacturers absorb premium positioning for high-DP fractions.
Supply Chain Analysis
Jalisco highland agave concentration anchors raw material flows through Arandas and Atotonilco extraction corridors. Blue agave fructan extraction draws from Mexico, with secondary processing capacity in the United States and Germany. Ceramic membrane filtration equipment, thermal evaporation infrastructure, and organic certification audit services constitute critical input dependencies. Single-origin vulnerability runs through climate exposure across Guanajuato and Michoacán cultivation zones. Distribution runs through Rotterdam and Hamburg consolidation points for European pharmaceutical buyers, with Laredo port serving North American natural retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chicory inulin substitution threat from European processors with established extraction infrastructure demands defensive positioning from agave-specialist incumbents. Market participants must navigate feedstock-switching elasticity that caps price premiums during supply disruptions.
For Market Incumbents: Compound GRAS notification infrastructure to lock in multinational CPG preferred supplier status against chicory substitution pressure. Secure multi-year organic supply agreements across Jalisco highland fields before three-year conversion windows close. Backward integration into membrane filtration technology preserves margin structure against thermal-processing commoditization.
For New Entrants and Emerging Players: Lead with pharmaceutical-grade high-DP purification protocols to bypass established food-grade competition. Target European contract manufacturers seeking parenteral formulation excipients with EFSA-positive opinion requirements that exclude smaller Mexican processors. Deploy direct-to-manufacturer e-procurement platforms to capture distributor margin in mid-volume bakery and confectionery segments.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-scarcity play because three-year organic field conversion creates supply inelasticity that forward-contracting processors exploit. Acquisition targets should display existing USDA NOP infrastructure with Jalisco terroir positioning rather than commodity volume scale. Monitor EFSA prebiotic substantiation guidance evolution as the signal indicating whether health-claim positioning premiums sustain or compress.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | Three-year field conversion locks in premium channel access against late entrants. |
| Membrane Filtration Capacity Addition | Ceramic ultrafiltration skids reduce energy intensity versus thermal concentration legacy. |
| FDA GRAS Notification Completion | Self-determination pathway secures prebiotic positioning claims for functional beverage formulators. |
| Pharmaceutical-Grade Purification Protocol | High-DP fractionation unlocks parenteral drug delivery applications with quality premiums. |
| Direct E-Procurement Platform Launch | Processor-direct portals disintermediate distributor layers for mid-volume bakery buyers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across ingredient procurement, formulation R&D, and regulatory affairs functions. Primary interviews with functional beverage formulators, pharmaceutical contract manufacturers, and Mexican extraction facility managers combined with secondary validation through FDA GRAS notification databases, USDA NOP certification records, and EFSA Article 13.1 health claim opinions. Bottom-up volume triangulation from Jalisco processor capacity and top-down value estimation from North American import data reinforced forecast integrity.
Across the projection horizon, the analytical framework modeled certification grade, application purity tier, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from historical price trajectory analysis and forward supply elasticity assessments incorporated organic conversion timeline constraints and EFSA substantiation cost evolution. Membrane filtration adoption curves and pharmaceutical-grade specification penetration served as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained FDA GRAS pathway stability or Jalisco climate conditions would require recalibration. Practitioners should keep alternative scenarios live as EFSA prebiotic guidance and chicory-agave substitution elasticity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Moringa Ingredients Market
Ingredients
Bean Ingredients Market
Ingredients
Soy Flour Market
Ingredients
Starch-Derived Fiber Market
Ingredients
Europe Potato Protein Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
North America Cocoa Products Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
GCC Egg Powder Market
Ingredients
Hemp Seed Peptide Market
Ingredients
Broccoli Powder Market
Ingredients
Food Botanicals Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Dry Malt Products Market
Ingredients
Pet Food Premix Market
Ingredients
Food Minerals Market