
 Upcycled Citrus Peel Fiber Concentrates Market | 2026-2036
Upcycled Citrus Peel Fiber Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Upcycled Citrus Peel Fiber Concentrates Market Insights
Petrochemical-derived texturizers and synthetic hydrocolloids is shifting toward upcycled citrus fiber in bakery, dairy, and plant-meat formulations as ingredient costs and label-conscious procurement converge. Cargill leverages its global agricultural sourcing infrastructure to secure citrus peel supply from juice processing partners across multiple continents. Fiberstar anchors its position through proprietary Citri-Fi technology that maintains functional performance across pH and temperature extremes. Tate & Lyle competes by extending its clean-label ingredient portfolio into upcycled fiber concentrates for beverage stabilization.
Upcycled citrus peel fiber concentrates comprise cellulosic and pectin-rich matrices recovered from post-juicing citrus waste, typically processed through washing, enzymatic treatment, drying, and milling to achieve dietary fiber contents exceeding 80 percent with water-binding capacities critical to food texture modification. Soluble fiber fractions command premium positioning in beverage and dairy applications where clarity and viscosity control determine formulation success, while insoluble fiber dominates bakery and meat analog segments where moisture retention and bite structure drive purchasing decisions. Pectin extract represents a mature, high-margin sub-segment with established pharmacopeial and food-grade specifications, whereas flavonoid concentrate occupies an emerging niche in nutraceutical and cosmetic applications where antioxidant claims support pricing power.
The FDA's GRAS notification pathway shapes market access timelines for novel citrus fiber applications in the United States, while EFSA's health claim substantiation requirements govern European positioning for cholesterol and glycemic response marketing. China's SAMR enforces GB standards for dietary fiber labeling that influence export-ready product specifications from concentrate producers. Stakeholders must monitor evolving national dietary fiber definition harmonization between Codex Alimentarius and major importing jurisdictions, as divergent analytical methods for soluble versus insoluble fiber content create compliance complexity for cross-border formulation consistency.
Market Dynamics
The EU's F-Gas Regulation and circular economy directives are compressing virgin petrochemical texturizer demand while concentrating agricultural waste sourcing around Mediterranean citrus processing clusters.
Growth Catalysts
- Clean-label procurement mandates:Food and beverage formulators in Germany are eliminating synthetic hydrocolloids from bakery and plant-meat formulations. EFSA's health claim substantiation pathway accelerates fiber ingredient approvals.
- Juice industry waste stream capture:Citrus processing infrastructure in Spain and Italy generates concentrated peel supply. Enzymatic fiber extraction technology recovers cellulosic matrices at industrial scale.
- SAMR dietary fiber labeling harmonization:China's GB standards for soluble versus insoluble fiber content create export-ready specifications. Concentrate producers align analytical methods for cross-border formulation consistency.
Market Restraints
- Seasonal raw material volatility:Citrus peel supply fluctuates with Mediterranean harvest cycles and juice processing volumes. Concentrate producers face input cost instability during off-peak months.
- Logistics concentration risk:Ingredient houses near southern European processing clusters command freight advantages. Remote formulators absorb higher transport costs for temperature-sensitive fiber concentrates.
- Petrochemical substitute price competition:Synthetic hydrocolloids maintain cost advantages in commodity bakery applications. Clean-label premiums compress margin recovery in price-sensitive segments.
Strategic Opportunities
- Flavonoid concentrate nutraceutical expansion:Antioxidant-rich citrus extracts target cosmetic and supplement applications. SAMR's evolving health food regulations create pathway for functional ingredient positioning.
- Beverage stabilization technology convergence:Soluble fiber fractions integrate with high-pressure processing for clarity retention. Dairy and ready-to-drink formulators adopt dual-function stabilization systems.
- Direct-to-formulator digital channels:Ingredient houses bypass traditional distribution tiers through technical specification platforms. Smaller craft food producers access previously unavailable concentrate volumes.
Industry Challenges
- GRAS notification timeline compression:FDA's novel fiber application reviews extend market access lead times. Upcycled ingredient startups lack regulatory affairs capacity of established suppliers.
- Enzymatic treatment IP fragmentation:Proprietary extraction processes face patent thickets across multiple jurisdictions. Licensing complexity slows technology transfer between research institutions.
- Legacy formulation integration friction:Bakery and meat analog producers retrofit existing production lines for fiber hydration requirements. Capex for mixing and holding equipment delays adoption in mid-cap facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Upcycled Citrus Peel Fiber Concentrates Market |
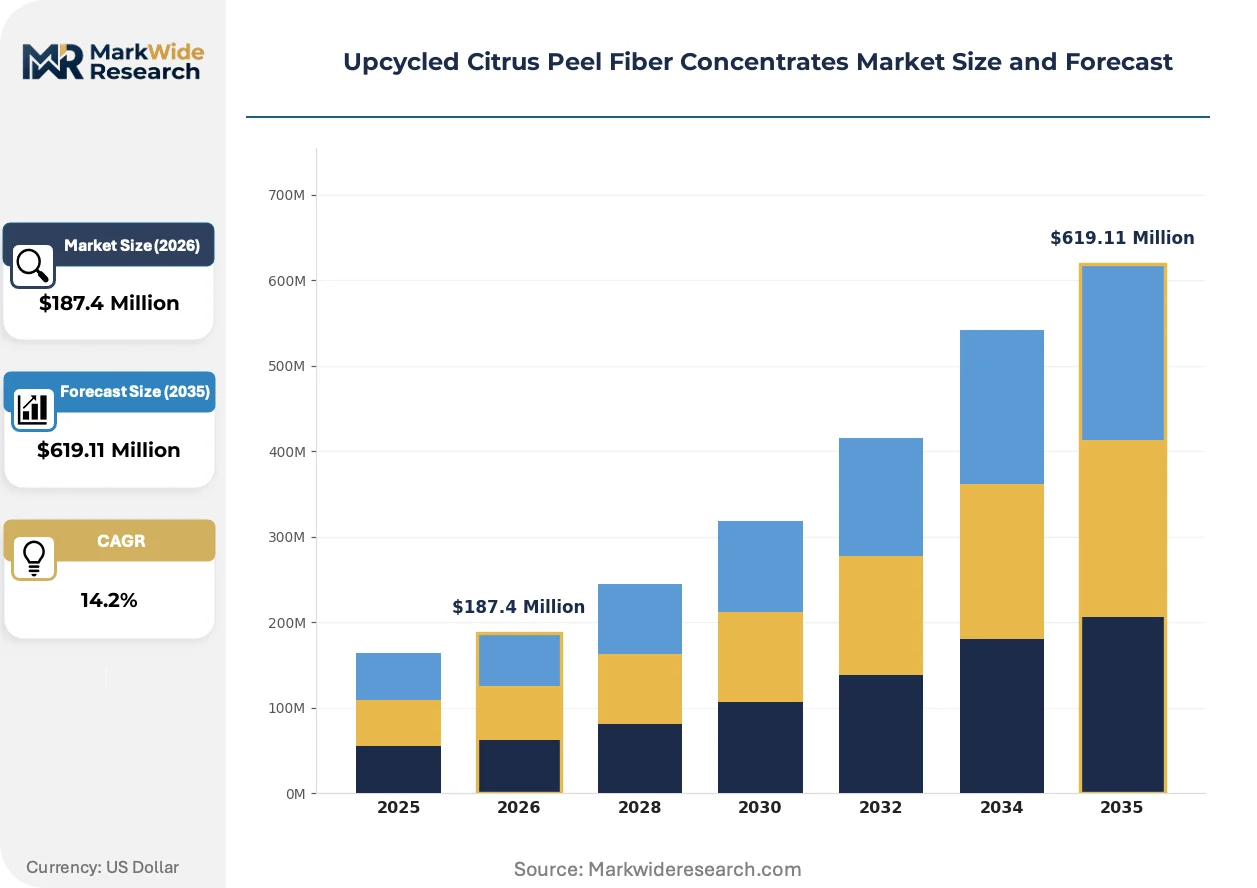
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble Fiber, Insoluble Fiber, Mixed Fiber, Pectin Extract, Flavonoid Concentrate Application: Food & Beverage, Animal Nutrition, Personal Care, Bioplastics, Dietary Supplements End User: Dietary Manufacturers, Pet Food Producers, Cosmetic Brands, Packaging Firms, Nutraceutical Companies Form: Powder, Granules, Liquid Extract, Pelletized, Flake |
| Companies Covered | Tate & Lyle, Ingredion, Cargill, Fiberstar, Herbafood Ingredients, JRS Silvateam Ingredients, CEAMSA, CP Kelco, Carolina Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Upcycled Citrus Peel Fiber Concentrates Market Trends and Innovations
Enzymatic fiber extraction and clean-label stabilization are converging to displace synthetic hydrocolloids across temperature-sensitive food processing applications.
Cellulase and pectinase enzyme systems are integrating into continuous processing lines for citrus peel fiber recovery. Large-scale juice processors in Spain deploy in-house enzymatic treatment capacity rather than selling raw peel to third-party concentrate houses. This backward integration is compressing merchant market supply while raising quality consistency for beverage-grade soluble fiber.
REACH registration requirements for novel food-contact substances are tightening purity specifications for citrus-derived ingredients. The European Chemicals Agency's evolving guidance on enzymatic processing residues affects extraction technology selection. Concentrate producers serving EU export markets are reformulating treatment protocols to preempt authorization delays.
Formulator technical service models are displacing traditional ingredient brokerage in high-value applications. Dairy and plant-meat developers in Germany demand application-specific hydration and viscosity data rather than standard specifications. Direct technical collaboration between concentrate houses and R&D teams is shortening formulation cycles for clean-label product launches.
Upcycled Citrus Peel Fiber Concentrates Market Segmentation
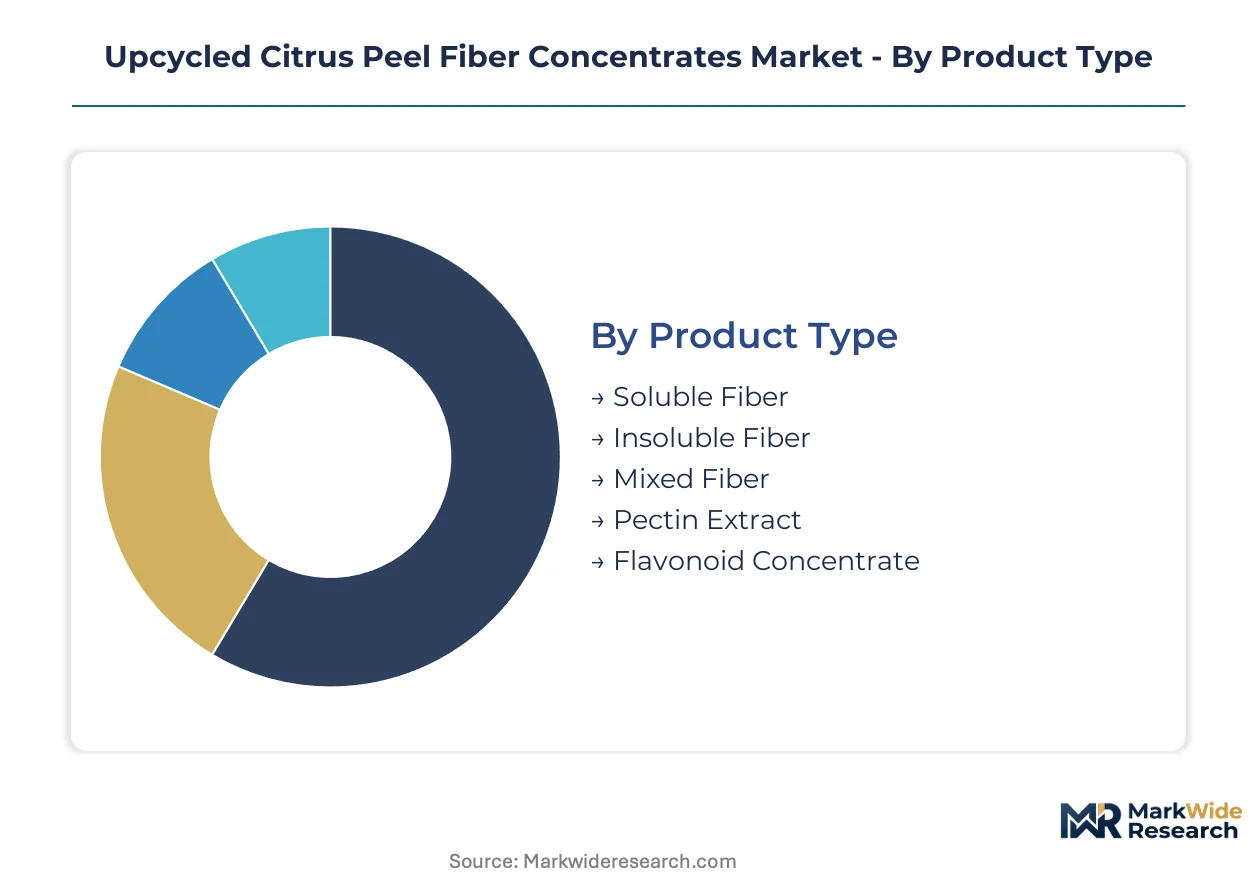
Upcycled citrus peel fiber concentrates demand diverges sharply across product chemistry and end-use specifications. Certification burdens from FDA GRAS, EFSA health claims, and SAMR GB standards fragment addressable markets by segment maturity.
Product Type:
FDA GRAS notifications apply to novel soluble fiber applications, while EFSA health claim substantiation governs pectin extract positioning in Europe. SAMR GB standards for dietary fiber labeling create additional compliance layers for flavonoid concentrates entering China.
- Soluble Fiber:Pectin-rich fractions enable beverage clarity and dairy viscosity control. Beverage stabilization demand concentrates in Germany where clean-label procurement mandates eliminate synthetic hydrocolloids. EFSA approval timelines compress market access for novel hydrocolloid replacements.
- Insoluble Fiber:Cellulosic matrices deliver moisture retention in bakery and meat analog applications. Plant-meat formulators in the United States specify insoluble fiber for bite structure replication. FDA GRAS self-affirmation offers faster pathway than novel food petitions.
- Mixed Fiber:Balanced soluble-insoluble ratios target cost-sensitive bakery applications.
- Pectin Extract:Pharmacopeial-grade specifications command premium positioning in gelling applications.
- Flavonoid Concentrate:Antioxidant-rich extracts target nutraceutical and cosmetic segments with evolving SAMR health food regulations.
Leading the category by volume: Insoluble Fiber. Growing fastest: Flavonoid Concentrate.
Application:
Cost tier stratification separates commodity food-grade specifications from pharmaceutical and cosmetic purity grades. REACH registration requirements for food-contact substances tighten entry barriers for bioplastics applications.
- Food & Beverage:Clean-label texturizers displace petrochemical hydrocolloids in bakery, dairy, and plant-meat formulations. German formulators lead procurement volume. EFSA health claim substantiation accelerates fiber ingredient approvals for cholesterol and glycemic response marketing.
- Animal Nutrition:Citrus fiber concentrates replace synthetic binders in pet food extrusion. Pet food producers in the United States specify prebiotic fiber content for digestive health claims. AAFCO ingredient definition approvals govern market access timelines.
- Personal Care:Flavonoid concentrates target antioxidant positioning in cosmetic formulations.
- Bioplastics:Cellulosic fiber reinforces biodegradable packaging with REACH food-contact compliance requirements.
- Dietary Supplements:Pectin and flavonoid extracts target capsule and gummy delivery formats.
Dominating procurement spend: Food & Beverage. Expanding most quickly: Personal Care.
End User:
Customer type determines technical service intensity and specification customization depth. Direct-to-formulator digital channels are compressing traditional distribution tiers for mid-cap dietary manufacturers.
- Dietary Manufacturers:Bakery and dairy formulators demand application-specific hydration data. German R&D teams collaborate directly with concentrate houses to shorten clean-label product launch cycles. Technical service models displace ingredient brokerage in high-value stabilization applications.
- Pet Food Producers:Extrusion processors specify pelletized fiber forms for binding efficiency. United States pet food facilities retrofit mixing equipment for fiber hydration requirements. Capital expenditure constraints delay adoption in mid-cap production lines.
- Cosmetic Brands:Antioxidant claims support premium pricing for flavonoid concentrates.
- Packaging Firms:Bioplastic compounders source cellulosic fiber for biodegradable film reinforcement.
- Nutraceutical Companies:Supplement formulators target soluble fiber for capsule and gummy applications.
Highest specification complexity: Dietary Manufacturers. Fastest channel shift: Pet Food Producers.
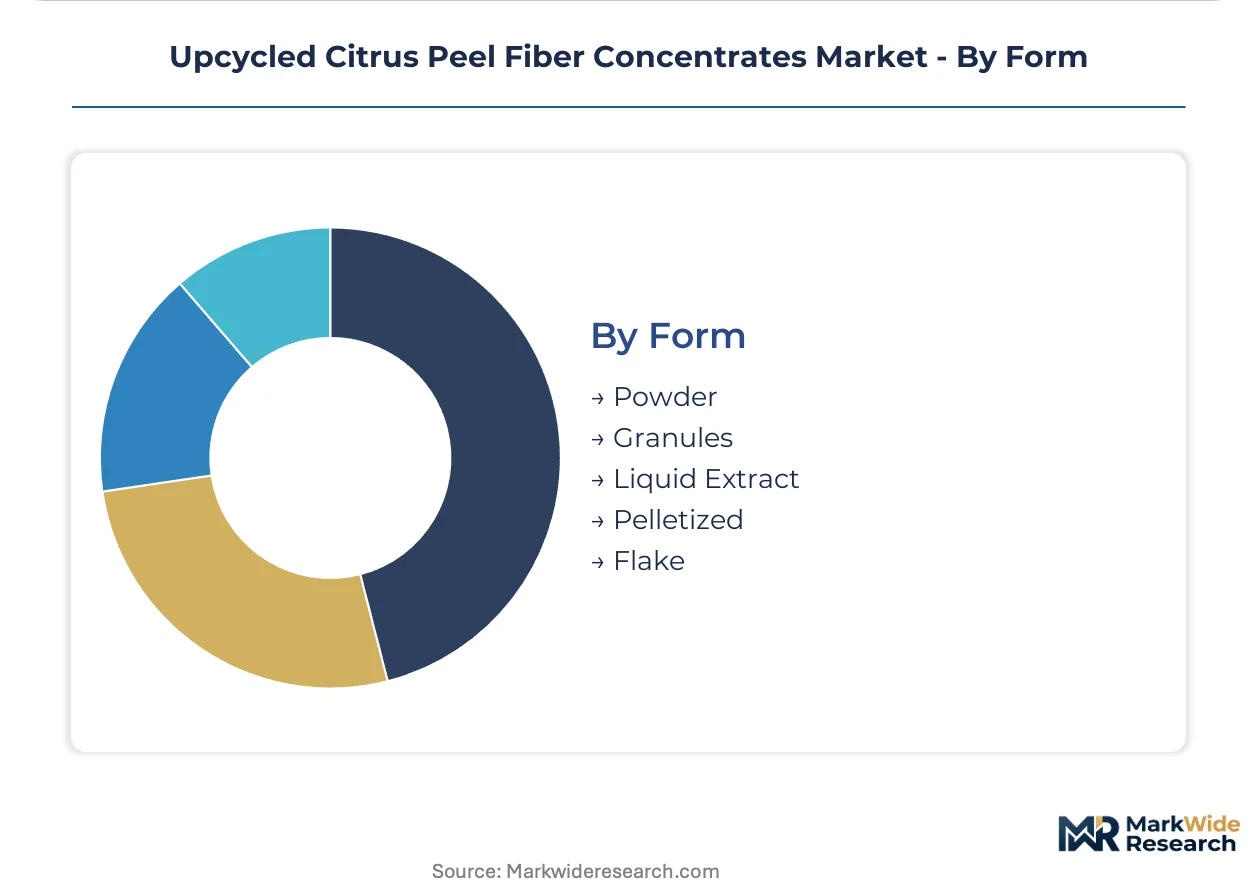
Form:
Supply concentration around Mediterranean citrus processing clusters advantages powder and granule producers with integrated drying capacity. Liquid extract transport costs constrain remote formulator adoption.
- Powder:Spray-dried concentrates achieve shelf stability for global distribution. Spanish juice processors deploy in-house enzymatic treatment capacity, compressing merchant powder supply. Backward integration raises quality consistency for beverage-grade specifications.
- Granules:Agglomerated forms improve dispersibility in high-shear mixing environments. Bakery producers in Germany specify granules for dust reduction during automated handling. Equipment retrofit requirements create adoption friction in legacy facilities.
- Liquid Extract:Soluble fiber suspensions target beverage stabilization with temperature-controlled logistics constraints.
- Pelletized:Compressed fiber forms optimize pet food extrusion feed rates.
- Flake:Irregular particles target cosmetic exfoliant and visual texture applications.
Highest volume form: Powder. Steepest expansion trajectory: Liquid Extract.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient procurement concentrates in Germany where clean-label mandates eliminate synthetic hydrocolloids from bakery and plant-meat formulations. EFSA health claim substantiation accelerates fiber approvals across cholesterol and glycemic response marketing. Processing infrastructure clusters around Mediterranean juice production zones in Spain and Italy.
Germany
Food and beverage formulators in Baden-Württemberg and Bavaria drive soluble fiber demand for beverage stabilization and dairy viscosity control. The F-Gas Regulation and EU circular economy directives pressure manufacturers to abandon virgin petrochemical inputs. Ingredient houses near Stuttgart leverage logistics advantages from southern European citrus processing clusters.
United States
Bakery and plant-meat producers in California and the Midwest specify insoluble fiber for moisture retention and bite structure replication. FDA GRAS self-affirmation offers faster market access than novel food petitions for upcycled fiber applications. Pet food facilities in Kansas and Nebraska retrofit mixing equipment for fiber hydration requirements.
Spain
Juice processors in Valencia and Murcia deploy in-house enzymatic treatment capacity rather than selling raw peel to third-party concentrate houses. REACH registration requirements for food-contact substances tighten purity specifications for citrus-derived ingredients. Backward integration compresses merchant market supply while raising quality consistency for beverage-grade soluble fiber.
China
SAMR enforces GB standards for dietary fiber labeling that influence export-ready product specifications from concentrate producers. Beverage and dairy formulators in Shanghai and Guangdong demand analytical method alignment for cross-border formulation consistency. Yangtze River Delta ingredient traders navigate evolving health food regulations for functional positioning.
Italy
Citrus processing infrastructure in Sicily and Calabria generates concentrated peel supply for enzymatic fiber extraction. EFSA health claim substantiation requirements govern European positioning for cholesterol marketing. Southern processing clusters command freight advantages to German ingredient houses seeking clean-label texturizers.
Upcycled Citrus Peel Fiber Concentrates Market Competitive Landscape
Strategic partnerships dominate the current landscape as ingredient houses secure captive peel supply from juice processing partners across multiple continents. The vendor base stratifies into three tiers: multinational agricultural processors with integrated sourcing infrastructure, specialized fiber technology firms with proprietary extraction systems, and regional ingredient traders serving price-sensitive commodity applications. Tier-one players compete through backward integration into citrus waste streams. Tier-two specialists differentiate via enzymatic treatment IP and application-specific technical service. Geographic expansion and technology licensing represent the dominant competitive vectors.
Among North American agricultural processors, Cargill anchors the integrated sourcing archetype through its global infrastructure. Tate & Lyle occupies a position within the clean-label portfolio extension tier, while Fiberstar exemplifies the proprietary technology specialist model with its Citri-Fi positioning. European ingredient houses including Herbafood Ingredients and JRS Silvateam Ingredients represent regional specialists with Mediterranean supply proximity. CEAMSA and CP Kelco occupy positions in the hydrocolloid and fiber convergence space. These named entities illustrate competitive positioning without exhaustive market mapping.
| Leading Market Players |
|---|
| Tate & Lyle |
| Ingredion |
| Cargill |
| Fiberstar |
| Herbafood Ingredients |
| JRS Silvateam Ingredients |
| CEAMSA |
| CP Kelco |
| Carolina Ingredients |
| Others |
Pricing and Supply Chain Analysis
Enzymatic treatment costs cascade from Spanish juice processors through three pricing tiers for German formulators, with backward integration by Mediterranean suppliers compressing merchant margins for independent concentrate houses.
Pricing Analysis
Volume concentration in insoluble fiber for commodity bakery applications compresses margins, while soluble fiber fractions for beverage stabilization retain premium positioning. Price differentiation hinges on EFSA health claim certification tier and direct technical service bundling. Pricing pressure stems from synthetic hydrocolloid substitutes in price-sensitive plant-meat segments. Mid-cap bakery producers exhibit highest price sensitivity; pharmaceutical-grade pectin extract buyers show lowest.
Supply Chain Analysis
Reverse-logistics flows of temperature-sensitive liquid extracts require refrigerated return lanes from remote formulators to Spanish reprocessing facilities, adding cost layers that powder and granule formats avoid. Raw material supply concentrates in Spain, Italy, and southern France around Mediterranean citrus processing clusters. Enzyme inputs, drying energy, and freight capacity constitute critical dependencies. Single-source vulnerability runs through Valencia and Murcia juice processor consolidation. Distribution runs through Stuttgart-based ingredient houses serving German formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance cost escalation is compressing weaker concentrate producers lacking GRAS notification capacity or EFSA health claim substantiation resources.
For Market Incumbents: Deepen captive peel supply agreements with Spanish and Italian juice processors to preempt backward integration by competitors. Expand in-house enzymatic treatment capacity to control quality consistency for beverage-grade specifications. Patent licensing revenue from proprietary extraction IP offers defensive moat against emerging technology specialists.
For New Entrants and Emerging Players: The mid-tier price gap between pharmacopeial-grade pectin extract and commodity insoluble fiber presents white-space opportunity. Target flavonoid concentrate nutraceutical applications where SAMR regulatory pathways remain unsettled. Direct-to-formulator digital channels bypass entrenched distribution tiers for craft food producers.
For Investors and Strategic Acquirers: FDA GRAS notification backlog clearance is the leading indicator that regulatory capacity constraints are easing for upcycled fiber applications. Long-term viability favors acquisition targets with integrated Mediterranean supply proximity and proprietary enzymatic IP. Monitor EFSA health claim approval velocity for cholesterol marketing as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Peel Supply | Cargill's agricultural sourcing infrastructure secures captive waste streams from juice processing partners. |
| Proprietary Enzymatic Treatment Licensing | Fiberstar's Citri-Fi technology patents generate royalty revenue across multiple jurisdictions. |
| EFSA Health Claim Substantiation Investment | Herbafood Ingredients accelerates European market access for cholesterol marketing applications. |
| Direct-to-Formulator Digital Channel Launch | Technical specification platforms bypass traditional distribution tiers for mid-cap dietary manufacturers. |
| Flavonoid Concentrate Capacity Expansion | Antioxidant extraction lines target cosmetic and nutraceutical segments with evolving SAMR regulations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with citrus processing plant managers, ingredient house procurement leads, German bakery R&D directors, EFSA regulatory affairs specialists, and SAMR compliance officers. FDA GRAS notification databases, REACH registration filings, Spanish agricultural ministry production statistics, and EU circular economy directive implementation reports provided validation layers. Bottom-up volume modeling from enzymatic treatment capacity installations triangulated against top-down demand estimates from clean-label formulation trends.
Granularity-level modeling operated at product chemistry tier, end-use application, and geographic regulatory cluster dimensions across the analysis window. CAGRs derived from segment-level growth rate differentials weighted by procurement volume concentration. Forecast inputs incorporated juice industry waste stream capture rates, enzymatic extraction yield improvements, and EFSA health claim approval pipeline velocity.
Inputs from EFSA pre-submission consultations and SAMR draft GB standard comment periods were available through the study window; gaps in real-time juice processor inventory data introduce uncertainty bands around seasonal raw material volatility assumptions. Practitioners should monitor FDA novel fiber petition queue lengths and Mediterranean citrus harvest yield reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Fruit and Vegetable Ingredients Market
Ingredients
Global Pregelatinized Starch Market
Ingredients
Date Syrup Market
Ingredients
Global Tomato Powder Market
Ingredients
North America Dairy Protein Market
Ingredients
North America Gluten Free Flour Market
Ingredients
South America Phytosterols Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Compressed Yeast Market
Ingredients
Codonopsis Extract Market
Ingredients
Australia Sodium Reduction Ingredients Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
North America Feed Yeast Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Bean Ingredients Market