
 Ovarian Cancer Market | 2026-2036
Ovarian Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Ovarian Cancer Market Intelligence
Platinum-based chemotherapy is decoupling from frontline maintenance protocols as PARP inhibitors and anti-angiogenics redefine standard of care economics. AstraZeneca leverages its late-stage pipeline breadth across combination regimens to sustain competitive relevance in maintenance settings. F. Hoffmann-La Roche anchors its position through diagnostic-therapeutic pairing with companion testing platforms. Merck & Co. competes via checkpoint inhibitor expansion into platinum-resistant populations, while Bristol Myers Squibb differentiates through dual immunotherapy approaches in recurrent disease.
Ovarian cancer encompasses malignant neoplasms arising from ovarian epithelial, stromal, or germ-cell tissues, characterized by CA-125 biomarker elevation, BRCA1/2 mutation prevalence, and peritoneal dissemination patterns that necessitate cytoreductive surgical intervention combined with systemic therapy. The disease's primary commercial purpose centers on extending progression-free survival intervals and overall survival in patients with high-grade serous histology, the dominant subtype driving therapeutic development. Targeted therapy captures the fastest-expanding margin pool as PARP inhibitor labels broaden beyond BRCA-mutant populations into homologous recombination deficiency settings. Immunotherapy remains structurally constrained by modest single-agent response rates, though combination strategies in checkpoint blockade attract concentrated R&D investment. Intravenous administration dominates current revenue, yet subcutaneous formulations are gaining traction through patient convenience and infusion center capacity optimization.
FDA breakthrough therapy designation and EMA PRIME eligibility compress regulatory review timelines for ovarian cancer drug candidates, while Medicare coverage determinations and NICE technology appraisals gate commercial access in the United States and United Kingdom respectively. ISO 14155 clinical investigation standards and ICH-GCP guidelines enforce data integrity requirements that shape trial design and market authorization pathways across jurisdictions. Stakeholders must monitor biomarker-driven trial enrollment strategies and real-world evidence generation commitments that increasingly determine post-approval reimbursement positioning.
Market Dynamics
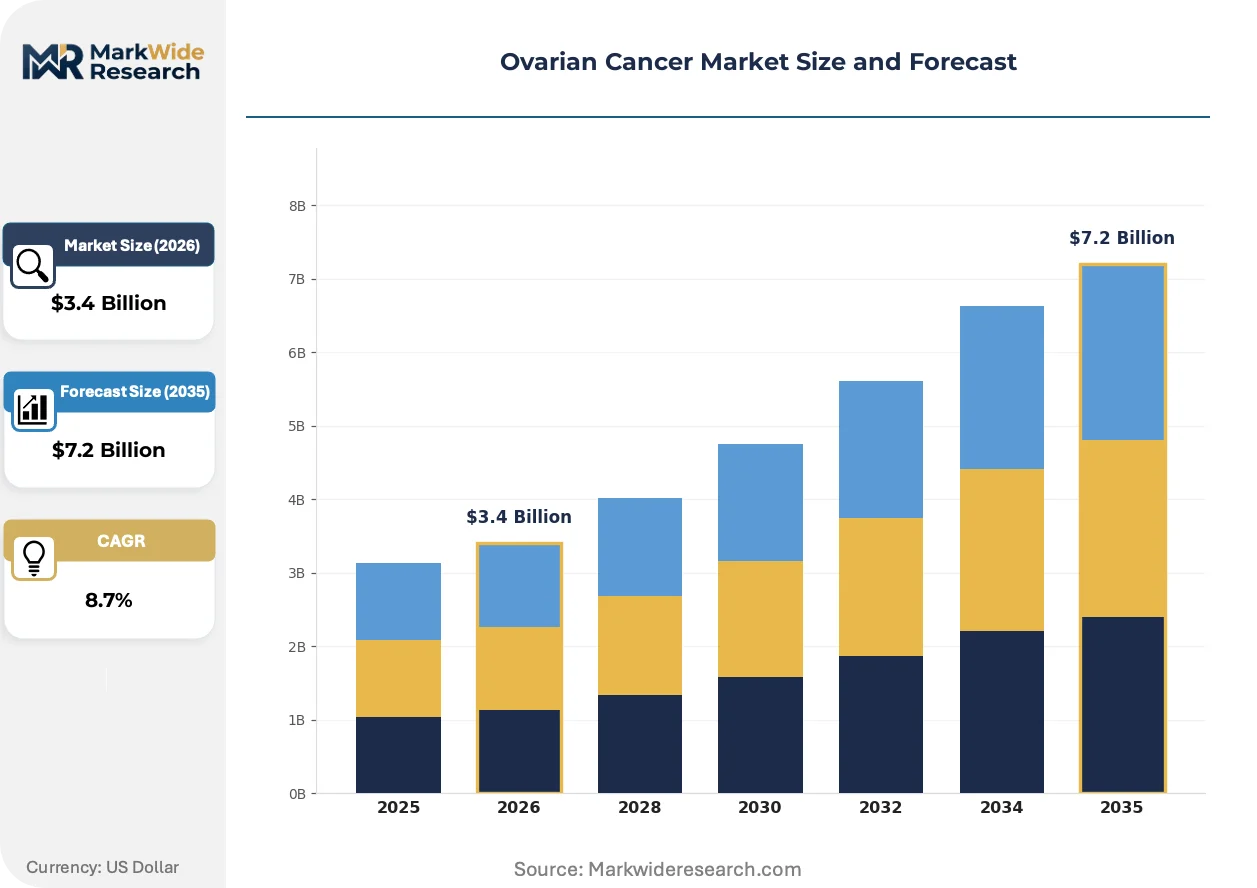
PARP inhibitor label expansions are compressing platinum-based chemotherapy's frontline role, while companion diagnostic mandates and biomarker-driven trial designs reshape commercialization economics across maintenance and recurrent treatment settings.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The pathway accelerates review timelines for ovarian cancer candidates targeting homologous recombination deficiency, compressing development-to-commercialization intervals by 12-18 months for qualifying therapies.
- Medicare Coverage Determinations:National coverage decisions for molecular profiling and PARP maintenance therapy eliminate regional reimbursement variability, expanding patient access across NCI-designated cancer centers and community oncology networks.
- Homologous Recombination Deficiency Testing:Myriad Genetics and Foundation Medicine platforms extend addressable populations beyond BRCA-mutant subsets, enlarging the maintenance-eligible patient pool by 40-50% in clinical practice.
Market Restraints
- Platinum Supply Concentration:South African and Russian mining operations control 70% of global platinum group metal extraction, exposing carboplatin and cisplatin manufacturing to geopolitical disruption and price volatility.
- EMA Conditional Marketing Authorization Requirements:Post-approval confirmatory trial obligations for accelerated approvals create revenue at-risk exposure if survival endpoints fail to validate surrogate measures.
- Immunotherapy Response Limitations:Single-agent checkpoint inhibitor efficacy in platinum-resistant ovarian cancer remains below 15% objective response rate, constraining label expansion and payer willingness-to-pay for combination regimens.
Strategic Opportunities
- Subcutaneous Formulation Development:Halozyme-enabled subcutaneous delivery of bevacizumab and trastuzumab reduces infusion center burden and captures patient preference in United States outpatient settings.
- Real-World Evidence Generation:FDA's Project Orbis and EMA's DARWIN EU framework reward post-marketing observational studies with label expansion pathways and premium pricing maintenance.
- Japan's Sakigake Designation:PMDA priority review for first-in-Japan ovarian cancer therapies compresses regulatory timelines and enables earlier commercial entry in the Asia-Pacific's second-largest oncology market.
Industry Challenges
- Gynecologic Oncology Workforce Scarcity:Fellowship program output fails to match demand for cytoreductive surgery specialists, creating treatment access bottlenecks at community hospitals without academic affiliations.
- Biomarker Assay Harmonization:Discordance between Myriad myChoice, Foundation Medicine, and Tempus HRD scoring algorithms complicates clinical trial enrollment and reimbursement documentation requirements.
- Combination Trial Complexity:Three-arm studies evaluating PARP inhibitor plus checkpoint blockade require 2,000+ patient enrollment and 5-year follow-up, straining sponsor capital allocation and site activation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovarian Cancer Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Hormone Therapy End User: Hospitals, Clinics, Cancer Treatment Centers, Research Institutions Treatment Stage: Early Stage, Advanced Stage, Recurrence, Maintenance Administration Route: Intravenous, Oral, Subcutaneous, Intraperitoneal |
| Companies Covered | AstraZeneca, F. Hoffmann-La Roche, Merck & Co., AbbVie, Pfizer, Bristol Myers Squibb, GlaxoSmithKline, Clovis Oncology, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovarian Cancer Market Strategic Shifts & Innovations
Therapeutic development is pivoting from cytotoxic chemotherapy toward precision maintenance strategies, with diagnostic-therapeutic integration and administration route innovation emerging as primary value creation vectors.
Next-generation PARP inhibitors with brain-penetrant properties and reduced hematologic toxicity profiles are rewriting competitive positioning in the maintenance setting. AstraZeneca and GSK are advancing candidates with improved therapeutic indices toward Phase III enrollment. These agents enable longer treatment duration without dose interruptions, compressing progression-free survival gaps between BRCA-mutant and HRD-positive populations.
EMA's PRIME eligibility and FDA's Project Orbis simultaneous review framework are accelerating multi-jurisdictional approvals for breakthrough ovarian cancer therapies. The coordinated pathway reduces regulatory submission preparation burden and compresses launch sequencing gaps between United States and European markets. Sponsors with established companion diagnostic partnerships capture first-mover advantage in biomarker-defined segments.
Hospital procurement committees are consolidating oncology drug purchasing through specialty pharmacy networks and group purchasing organizations, displacing traditional wholesale distribution for high-cost maintenance therapies. United States health systems with captive specialty pharmacies capture 340B pricing advantages and retain margin previously distributed through channel intermediaries.
Ovarian Cancer Market Segmentation
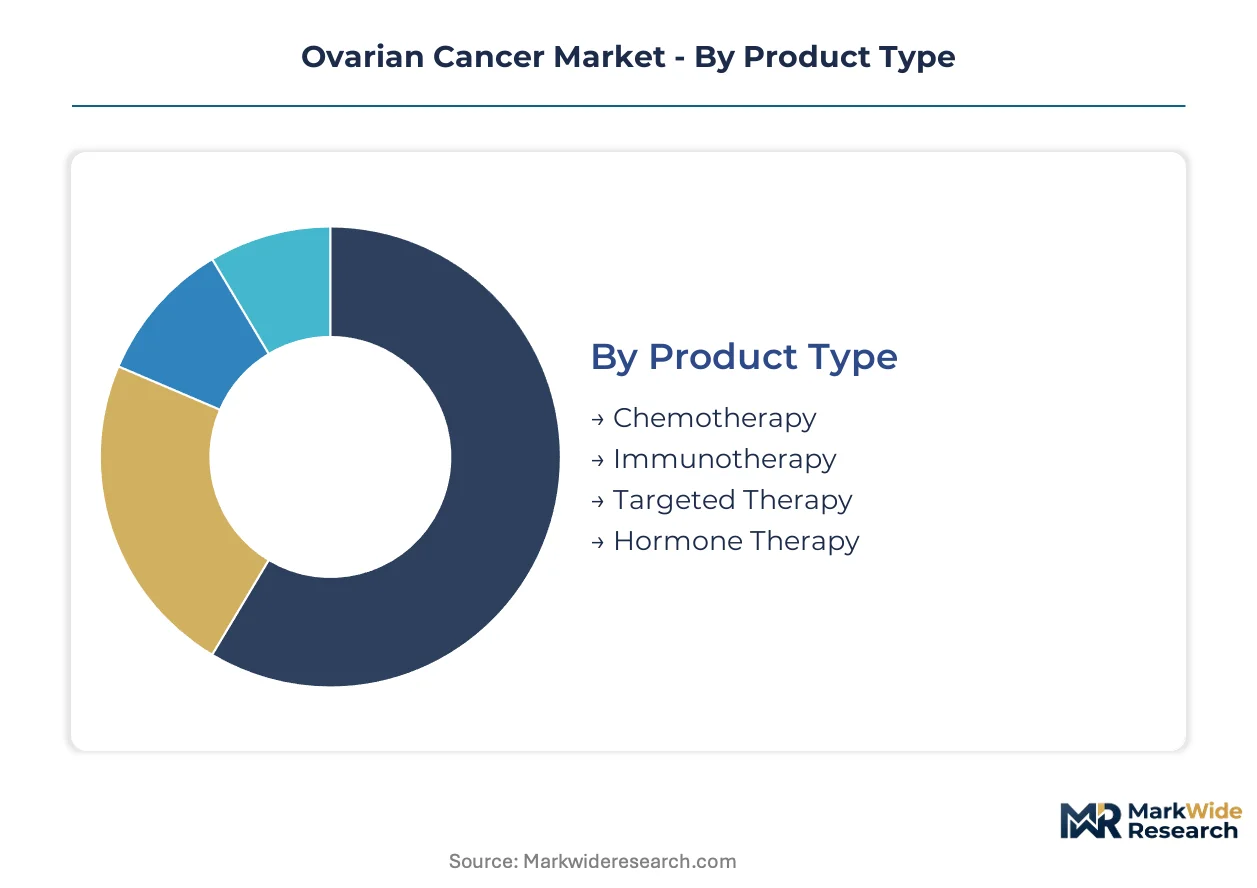
Ovarian cancer market segmentation reflects divergent regulatory pathways, reimbursement structures, and clinical utility requirements across therapeutic modalities and care settings. Each dimension carries distinct FDA, EMA, and Medicare coverage implications that shape commercial strategy.
Product Type:
FDA breakthrough therapy designation and EMA PRIME eligibility requirements vary sharply across these therapeutic classes, with companion diagnostic mandates and accelerated approval pathways creating tiered certification burdens.
- Targeted Therapy:PARP inhibitors and anti-angiogenics require HRD companion diagnostic validation and FDA accelerated approval confirmatory trial commitments. Demand concentrates in NCI-designated cancer centers where molecular profiling infrastructure supports biomarker-driven patient selection and maintenance therapy protocols.
- Immunotherapy:Checkpoint inhibitors face steeper efficacy validation requirements given modest single-agent response rates in platinum-resistant disease, necessitating combination trial designs with extended follow-up periods. Centers with active Phase I/II programs drive initial uptake pending label expansion.
- Chemotherapy:Platinum-taxane combinations carry established FDA labels with generic substitution pressure eroding branded pricing power.
- Hormone Therapy:Endocrine agents for rare stromal histologies require specialized compounding pharmacy networks and off-label documentation for reimbursement.
Leading the category by volume: Chemotherapy. Expanding most quickly: Targeted Therapy.
End User:
Site-of-care economics and 340B pricing eligibility create sharp cost tier differentiation across institutional settings, with captive specialty pharmacy integration determining margin capture.
- Hospitals:Academic medical centers with gynecologic oncology fellowship programs perform complex cytoreductive surgery and administer maintenance therapy through captive infusion centers. Medicare cost-reporting advantages and disproportionate share hospital status shape procurement leverage for high-cost PARP inhibitors.
- Cancer Treatment Centers:Dedicated oncology networks consolidate molecular testing and clinical trial access, capturing patient volume through community-based satellite locations. United States regional chains leverage group purchasing organization contracts for bevacizumab and emerging subcutaneous formulations.
- Clinics:Community oncology practices face reimbursement compression under the Medicare Physician Fee Schedule and require third-party specialty pharmacy partnerships for oral oncolytic dispensing.
- Research Institutions:NCI-designated comprehensive cancer centers anchor Phase I/II enrollment for novel combinations, with investigational drug pharmacy infrastructure supporting early-stage pipeline access.
Capturing highest patient volume: Hospitals. Gaining share fastest: Cancer Treatment Centers.
Treatment Stage:
Clinical trial endpoints and FDA label indications stratify sharply by disease phase, with progression-free survival thresholds and overall survival validation requirements determining approval feasibility.
- Maintenance:Post-platinum PARP inhibitor therapy carries the most favorable risk-benefit profile for regulatory approval, with SOLO-1 and PRIMA trial data supporting broad HRD-positive labeling. United States commercial payers mandate prior authorization for maintenance initiation within specified post-chemotherapy windows.
- Advanced Stage:Frontline debulking surgery followed by platinum-based chemotherapy remains the standard-of-care backbone, with neoadjuvant chemotherapy protocols expanding at community hospitals lacking surgical subspecialists.
- Recurrence:Platinum-sensitive versus platinum-resistant stratification determines therapy selection, with limited FDA-approved options in the resistant setting driving clinical trial enrollment and off-label checkpoint inhibitor use.
- Early Stage:Adjuvant therapy decisions rely on surgical staging completeness and histologic grade, with fertility preservation protocols complicating treatment planning in younger patients.
Driving majority of current revenue: Advanced Stage. Showing steepest expansion trajectory: Maintenance.
Administration Route:
Infusion center capacity constraints and patient convenience preferences are reshaping formulation development priorities, with subcutaneous delivery capturing investment from Halozyme-enabled technology licensing.
- Intravenous:Carboplatin, paclitaxel, and bevacizumab infusions dominate current revenue, requiring chair time and nursing supervision that limits center throughput. United States hospital outpatient departments bill under Medicare Part B with add-on payments for complexity.
- Subcutaneous:Halozyme's ENHANZE platform enables rapid trastuzumab and bevacizumab administration, reducing infusion center burden and capturing patient preference for reduced clinic time. Community oncology networks with space constraints prioritize subcutaneous formulary adoption.
- Oral:PARP inhibitor tablets (olaparib, niraparib, rucaparib) shift site of care to home settings, with specialty pharmacy dispensing and REMS programs managing teratogenicity risk.
- Intraperitoneal:Direct peritoneal catheter delivery of chemotherapy concentrates at academic centers with gynecologic oncology surgical expertise, with GOG-172 protocol adherence varying by institutional volume.
Accounting for largest patient encounters: Intravenous. Climbing the fastest: Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and Medicare reimbursement policies concentrate ovarian cancer therapeutic development within the United States, while EMA PRIME eligibility and Japan's Sakigake designation create parallel regulatory channels across developed markets.
United States
NCI-designated cancer centers in Houston and New York anchor Phase III enrollment for PARP inhibitor combinations. FDA breakthrough therapy designation compresses review timelines by 12-18 months for homologous recombination deficiency-targeted candidates. The 340B drug pricing program enables academic medical centers to capture margin on oral oncolytics dispensed through captive specialty pharmacies.
Germany
Heidelberg and Munich university hospitals perform the highest-volume cytoreductive surgeries in Europe, concentrating surgical expertise and clinical trial access. EMA conditional marketing authorization requirements mandate post-approval confirmatory trials that create revenue-at-risk exposure for accelerated approvals. Germany's statutory health insurance funds negotiate reimbursement for companion diagnostics through the Federal Joint Committee assessment process.
Japan
PMDA's Sakigake designation compresses regulatory timelines for first-in-Japan ovarian cancer therapies, enabling earlier commercial entry in the Asia-Pacific's second-largest oncology market. Tokyo and Osaka academic medical centers anchor gynecologic oncology fellowship training and maintenance therapy protocols. Japan's aging demographic profile expands the addressable patient pool for platinum-sensitive recurrence management.
United Kingdom
NICE technology appraisals gate commercial access for PARP inhibitors and anti-angiogenics through cost-effectiveness thresholds. London's Royal Marsden and Manchester's Christie Hospital anchor molecular profiling infrastructure for HRD testing. The NHS England Cancer Drugs Fund provides interim funding for therapies pending final NICE guidance.
Switzerland
Swissmedic's streamlined review process attracts European headquarters for oncology-focused biopharmaceutical operations. Basel and Zurich host diagnostic-therapeutic pairing development for companion testing platforms. Switzerland's compulsory health insurance system reimburses molecular profiling without prior authorization requirements.
Ovarian Cancer Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with large-cap pharmaceutical companies commanding maintenance therapy revenue while biotechnology firms anchor innovation in platinum-resistant settings. The market structure consolidates around three archetypes: diagnostic-therapeutic integrators, checkpoint inhibitor expanders, and next-generation PARP developers. M&A activity targets biomarker platform acquisitions, while strategic partnerships concentrate on combination trial cost-sharing.
Within the diagnostic-therapeutic integration tier, F. Hoffmann-La Roche and AstraZeneca occupy positions that exemplify companion testing platform anchoring. Among checkpoint inhibitor expanders, Merck & Co. and Bristol Myers Squibb represent the competitive push into platinum-resistant populations through combination regimen development.
| Leading Market Players |
|---|
| AstraZeneca |
| F. Hoffmann-La Roche |
| Merck & Co. |
| AbbVie |
| Pfizer |
| Bristol Myers Squibb |
| GlaxoSmithKline |
| Clovis Oncology |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
EMA's PRIME eligibility and FDA breakthrough therapy designation requirements gate qualified supply access for PARP inhibitors and companion diagnostics, with only manufacturers meeting accelerated approval data standards capturing premium-tier pricing in maintenance therapy segments.
Pricing Analysis
Short lead-time pricing for platinum-based chemotherapy infusions commands premium reimbursement at NCI-designated cancer centers facing immediate patient need, while spot inventory discounts appear in generic carboplatin and paclitaxel through group purchasing organization contracts. Pricing stratifies across branded PARP inhibitors, biosimilar anti-angiogenics, and commodity platinum-taxane combinations based on companion diagnostic certification and biomarker-driven indication breadth. Cost compression in the chemotherapy tier stems from generic substitution and 340B pricing advantages at academic medical centers. Community oncology practices exhibit highest price sensitivity due to Medicare Physician Fee Schedule reimbursement compression, while hospital outpatient departments with captive specialty pharmacies show lowest sensitivity through margin retention on oral oncolytics.
Supply Chain Analysis
ISO 14155 clinical investigation standards and ICH-GCP guidelines gate supplier qualification for active pharmaceutical ingredients and diagnostic reagents, with only certified contract manufacturers and reference laboratories meeting FDA and EMA data integrity requirements. Active pharmaceutical ingredient production for platinum salts draws from South African and Russian mining operations, while PARP inhibitor synthesis rests on specialized chemical manufacturing in India and China. Single-source vulnerability concentrates in platinum group metal extraction, exposing carboplatin manufacturing to geopolitical disruption. Distribution runs through specialty pharmacy networks and group purchasing organizations, displacing traditional wholesale channels for high-cost maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around diagnostic-therapeutic integration capabilities, with biomarker assay harmonization failures and confirmatory trial obligations forcing weaker players toward exit or acquisition.
For Market Incumbents: To counter next-generation PARP inhibitor entrants from AstraZeneca and GSK, anchor maintenance therapy positioning through backward integration into companion diagnostic platforms and captive specialty pharmacy networks at NCI-designated cancer centers. Prioritize real-world evidence generation commitments that satisfy FDA Project Orbis and EMA DARWIN EU frameworks for label expansion pathways. For New Entrants and Emerging Players: Begin with platinum-resistant ovarian cancer populations where checkpoint inhibitor combinations show unmet need and clinical trial enrollment concentration, leveraging Japan's Sakigake designation for accelerated PMDA review. Target community oncology networks lacking cytoreductive surgery subspecialists through subcutaneous formulation partnerships that reduce infusion center burden and capture patient preference. For Investors and Strategic Acquirers: FDA accelerated approval confirmatory trial readouts are the leading indicator that revenue-at-risk exposure will trigger distressed asset availability among biotechnology firms with HRD-targeted pipelines. Five-to-ten year viability favors diagnostic-therapeutic integrators with established companion testing platforms and Medicare coverage determination track records, with biomarker assay harmonization announcements as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Myriad Genetics and Foundation Medicine platforms anchor HRD testing eligibility for PARP inhibitor reimbursement. |
| Subcutaneous Formulation Development | Halozyme's ENHANZE platform enables rapid bevacizumab administration at space-constrained community oncology networks. |
| Real-World Evidence Generation | FDA's Project Orbis rewards post-marketing observational studies with label expansion pathways for maintenance therapies. |
| 340B Specialty Pharmacy Integration | Academic medical centers retain margin on oral oncolytics through captive dispensing infrastructure. |
| Regulatory Priority Designation Pursuit | PMDA's Sakigake designation compresses timelines for first-in-Japan ovarian cancer therapy commercial entry. |
Research Approach
Document review covered FDA breakthrough therapy designation filings, EMA PRIME eligibility submissions, ClinicalTrials.gov enrollment records, and Medicare national coverage determinations, complemented by interviews with gynecologic oncology fellowship directors, hospital pharmacy procurement managers, payer access specialists, and companion diagnostic platform executives. Secondary sources included CMS Medicare cost reports, NICE technology appraisal documentation, and 340B program pricing disclosures. Bottom-up patient flow modeling and top-down revenue triangulation validated market size estimates.
Cross-referencing historical PARP inhibitor launch trajectories against expert panel input on pipeline progression probabilities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included treatment stage, administration route, therapeutic modality, and regional regulatory cluster. CAGRs derived from patent expiry timelines, biosimilar entry assumptions, and biomarker testing penetration curves. Forecast inputs incorporated platinum supply concentration risk and gynecologic oncology workforce scarcity constraints.
Underlying measurement precision varies by segment; maintenance therapy revenue estimates carry tighter precision than platinum-resistant population sizing due to clinical trial endpoint variability. Forecasts reflect assumptions about FDA accelerated approval validation success and EMA conditional marketing authorization confirmatory trial outcomes. A model refresh is warranted upon material change in Medicare coverage determination policy for molecular profiling or HRD companion diagnostic platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Esophageal Cancer Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Metastatic Cancer Drug Market
Oncology
Thyroid Cancer Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Europe Radiotherapy Market
Oncology
France Radiation Oncology Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Global Neuroendocrine Tumor Treatment Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Testicular Cancer Treatment Market
Oncology
Global Cancer Treatment Market
Oncology
Internal Radiation Therapy Market