
 Europe Kidney Cancer Therapeutics and Diagnostics Market | 2026-2036
Europe Kidney Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kidney Cancer Therapeutics and Diagnostics Market Foresight
The EU Medical Device Regulation is hardening the cost-of-entry calculus for diagnostic manufacturers seeking European market access. Bristol Myers Squibb leverages its immuno-oncology portfolio to sustain leadership in combination regimens for advanced renal cell carcinoma. Bayer AG anchors its position through targeted therapy specialization in tyrosine kinase inhibitors.
Europe kidney cancer therapeutics and diagnostics encompasses systemic treatments and molecular diagnostic tools designed to identify, stage, and monitor renal cell carcinoma, including companion diagnostics that detect VHL gene mutations or PD-L1 expression to guide therapy selection. The primary purpose centers on improving progression-free survival through biomarker-driven treatment assignment while enabling real-time therapeutic monitoring. Immunotherapy now leads the product type landscape as checkpoint inhibitors displace cytokine-based protocols in first-line settings, while intravenous delivery mode dominates hospital administration despite oral tyrosine kinase inhibitors capturing outpatient share. Research laboratories represent the fastest-growing end user segment as centralized molecular testing consolidates volume across hospital networks.
The European Medicines Agency governs centralized marketing authorization for oncology therapeutics, while the In Vitro Diagnostic Regulation mandates enhanced clinical evidence for companion diagnostic platforms. REACH compliance constrains reagent chemistry sourcing, creating procurement complexity for multiplex assay developers. Stakeholders must monitor reimbursement negotiations between national health technology assessment bodies and manufacturers, as these determinations will shape adoption velocity for novel combination protocols across European markets.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing market access timelines for companion diagnostic developers while simultaneously elevating clinical evidence requirements. This regulatory tightening is concentrating procurement authority within centralized hospital laboratory networks across Germany, France, and Italy.
Growth Catalysts
- EMA centralized authorization pathway:The European Medicines Agency's oncology fast-track designation accelerates market entry for novel immunotherapy combinations. Academic medical centers in the Rhine-Main cluster prioritize these approved protocols.
- Research laboratory consolidation:Hospital networks across France and Italy are centralizing molecular testing volume into regional reference laboratories. This concentration drives demand for high-throughput diagnostic platforms.
- Biomarker-driven treatment assignment:PD-L1 expression testing and VHL mutation detection now guide first-line therapy selection. Pathology departments are upgrading immunohistochemistry infrastructure to support this precision oncology shift.
Market Restraints
- REACH compliance complexity:The European Chemicals Agency's registration requirements constrain reagent chemistry sourcing for multiplex assay manufacturers. Procurement teams face extended supplier qualification timelines.
- IVDR clinical evidence burden:The In Vitro Diagnostic Regulation mandates expanded performance studies for companion diagnostics. Smaller diagnostic developers lack capital reserves to meet these evidentiary thresholds.
- Reimbursement negotiation fragmentation:National health technology assessment bodies in Germany, France, and Italy operate divergent value assessment frameworks. Manufacturers must navigate parallel pricing negotiations without harmonized criteria.
Strategic Opportunities
- Central and Eastern Europe laboratory buildout:Poland and Romania are constructing molecular diagnostic capacity to reduce sample referral dependence on Western European reference centers. Equipment vendors can capture greenfield installation demand.
- EU AI Act diagnostic imaging pathway:The regulation's risk-classification framework creates a compliance roadmap for artificial intelligence-enabled radiology tools. Developers of CT-based renal mass characterization algorithms gain regulatory clarity.
- Home-based therapeutic monitoring:Oral tyrosine kinase inhibitor regimens enable outpatient pharmacokinetic tracking through dried blood spot sampling. Specialty diagnostic laboratories can extend service lines beyond hospital confines.
Industry Challenges
- Histopathologist workforce scarcity:European training programs produce insufficient specialist pathologists to meet molecular diagnostic reporting demand. Automated image analysis tools remain unvalidated for primary diagnosis.
- Companion diagnostic-treatment coordination:Pharmaceutical and diagnostic developers must synchronize regulatory submissions across EMA and notified body review cycles. Misaligned timelines delay combined market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kidney Cancer Therapeutics and Diagnostics Market |
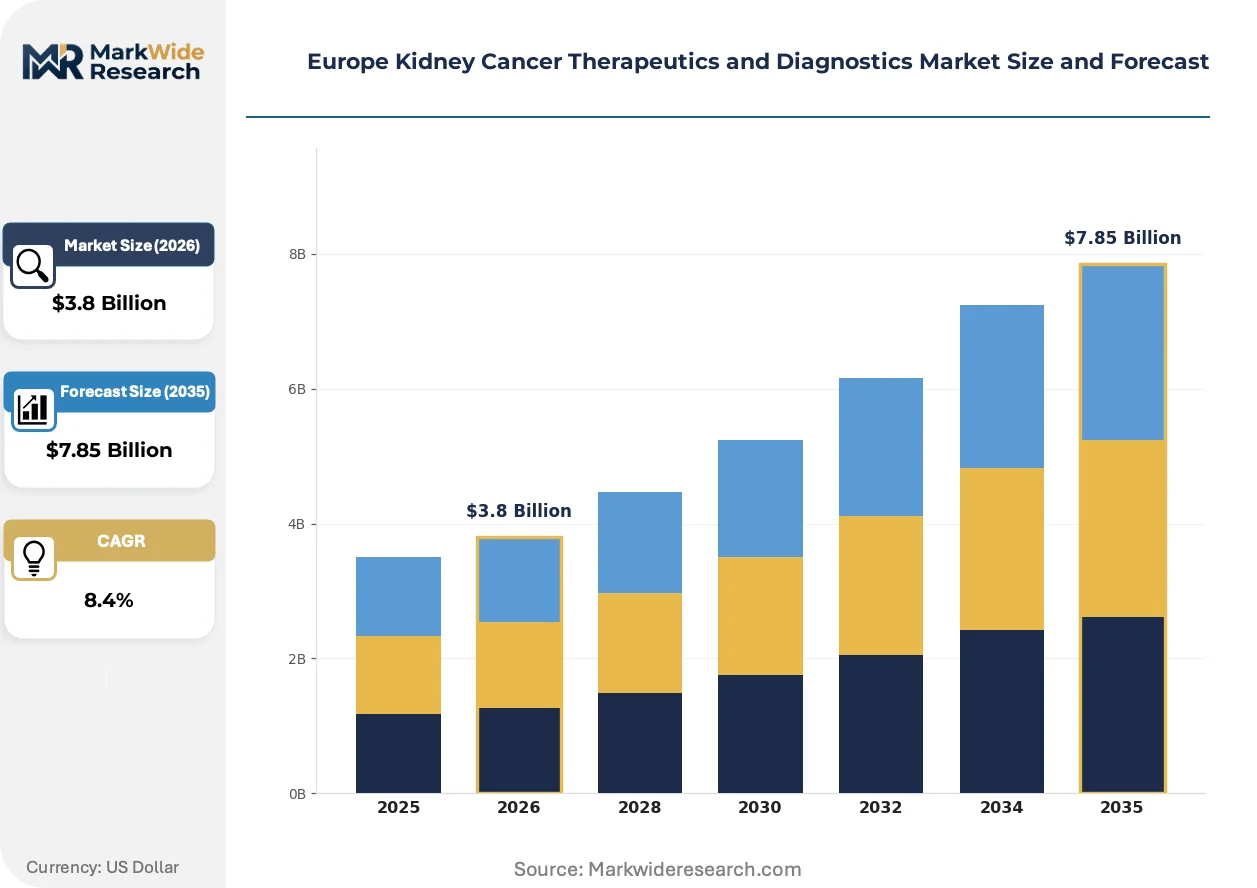
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Radiation Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Research Laboratories, Home Care Application: Diagnosis, Treatment, Monitoring, Palliative Care |
| Companies Covered | Bristol Myers Squibb, Novartis AG, Bayer AG, GlaxoSmithKline Plc, Pfizer, F. Hoffmann-La Roche, Abbott Laboratories, Siemens Healthineers AG, Amgen Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kidney Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Checkpoint inhibitor protocols are displacing cytokine-based first-line therapies across European oncology practice. This therapeutic shift is compressing diagnostic testing windows and reshaping laboratory service requirements.
Liquid biopsy platforms for circulating tumor DNA detection are modularizing the surveillance workflow for renal cell carcinoma recurrence. University hospital networks in Germany and the Netherlands are piloting these assays for post-surgical monitoring. The technology is modularizing longitudinal patient tracking away from periodic imaging toward continuous molecular surveillance.
The EU Medical Device Regulation's 2021 implementation is forcing diagnostic manufacturers to rebuild quality management systems around notified body oversight. Class C and D companion diagnostics now require annual surveillance audits. French and Italian IVD developers are prioritizing MDR certification to maintain market access ahead of legacy directive expiration.
Hospital procurement departments are consolidating molecular diagnostic contracts under framework agreements with single-source vendors. Germany's university hospital purchasing cooperatives now dominate reagent and instrument acquisition. This concentration is visible across the Nordrhein-Westfalen and Bavaria hospital networks, where centralized tenders displace site-level purchasing autonomy.
Europe Kidney Cancer Therapeutics and Diagnostics Market Segmentation
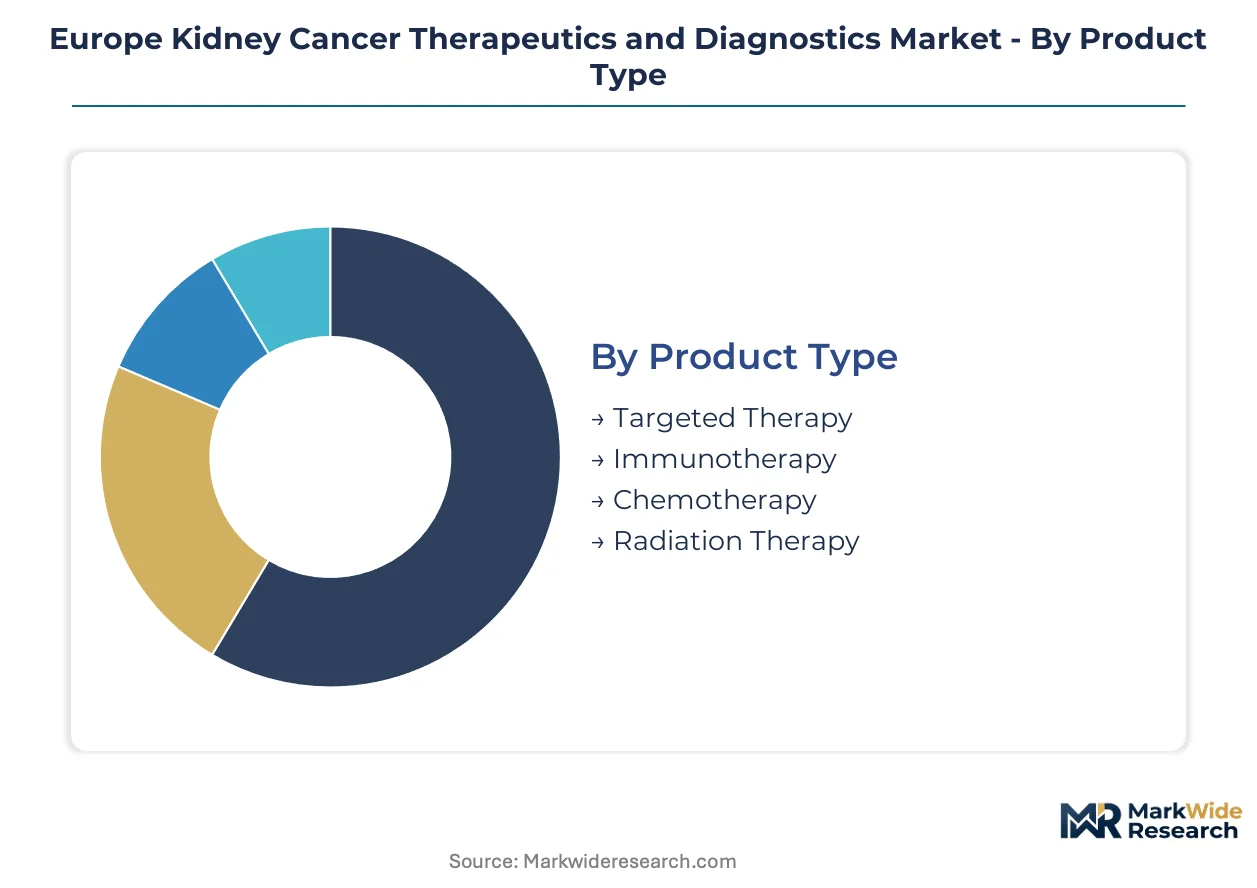
Segmentation in kidney cancer care reveals how therapeutic modalities and diagnostic access points diverge across European healthcare systems. Understanding these splits helps manufacturers align development pipelines with where clinical decisions actually occur.
Product Type:
Immunotherapy and targeted therapy function as standalone systemic interventions, while chemotherapy and radiation therapy embed within multimodal protocols requiring diagnostic coordination.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 and CTLA-4 pathways dominate first-line renal cell carcinoma protocols across European university hospitals. Demand concentrates in Germany's Rhine-Main academic cluster where EMA-approved combination regimens receive priority formulary placement.
- Targeted Therapy:Tyrosine kinase inhibitors (TKIs) and mTOR inhibitors interrupt angiogenic signaling in VHL-mutated tumors. Oral administration enables outpatient distribution, with prescribing concentrated in France's regional cancer centers where molecular profiling infrastructure supports biomarker-driven selection.
- Chemotherapy:Cytotoxic agents retain limited utility in sarcomatoid variant cases and salvage settings.
- Radiation Therapy:Stereotactic body radiotherapy addresses oligometastatic disease and symptomatic bone lesions.
Volume placements concentrate in immunotherapy; the faster expansion belongs to targeted therapy as oral regimens extend treatment into community settings.
Delivery Mode:
Route selection shapes where care occurs: infusion-dependent modes tether patients to hospital infrastructure, while self-administered alternatives shift monitoring burden to outpatient and home environments.
- Intravenous:Infusion protocols for checkpoint inhibitors and combination therapies require oncology day unit capacity. Germany's university hospital networks capture the majority of European IV immunotherapy volume through centralized administration.
- Oral:TKI regimens enable distributed prescribing across Italy's regional health systems, with pharmacy benefit management determining access tiers.
- Subcutaneous:Limited current application in renal cell carcinoma with emerging interest for supportive care agents.
- Topical:Negligible role in systemic renal malignancy management.
Hospital infusion capacity constrains intravenous expansion; oral delivery gains share fastest as health systems prioritize bed-day conservation.
End User:
Care setting determines diagnostic intensity and reimbursement pathway, with academic centers driving protocol innovation while community sites execute standardized regimens.
- Hospitals:Comprehensive cancer centers integrate surgical, medical, and radiation oncology with embedded molecular pathology. France's 18 Unicancer centers and Germany's comprehensive cancer networks concentrate complex case volume.
- Research Laboratories:Centralized molecular testing facilities across hospital networks in Italy and the Netherlands consolidate biomarker analysis. These sites are expanding fastest as regional reference laboratory models disperse site-specific testing.
- Clinics:Community oncology practices manage stable patients on oral TKI maintenance.
- Home Care:Emerging role for oral therapy monitoring and symptom management in select European markets.
Hospital systems anchor current therapeutic volume; research laboratories are climbing the fastest as molecular diagnostic centralization accelerates.
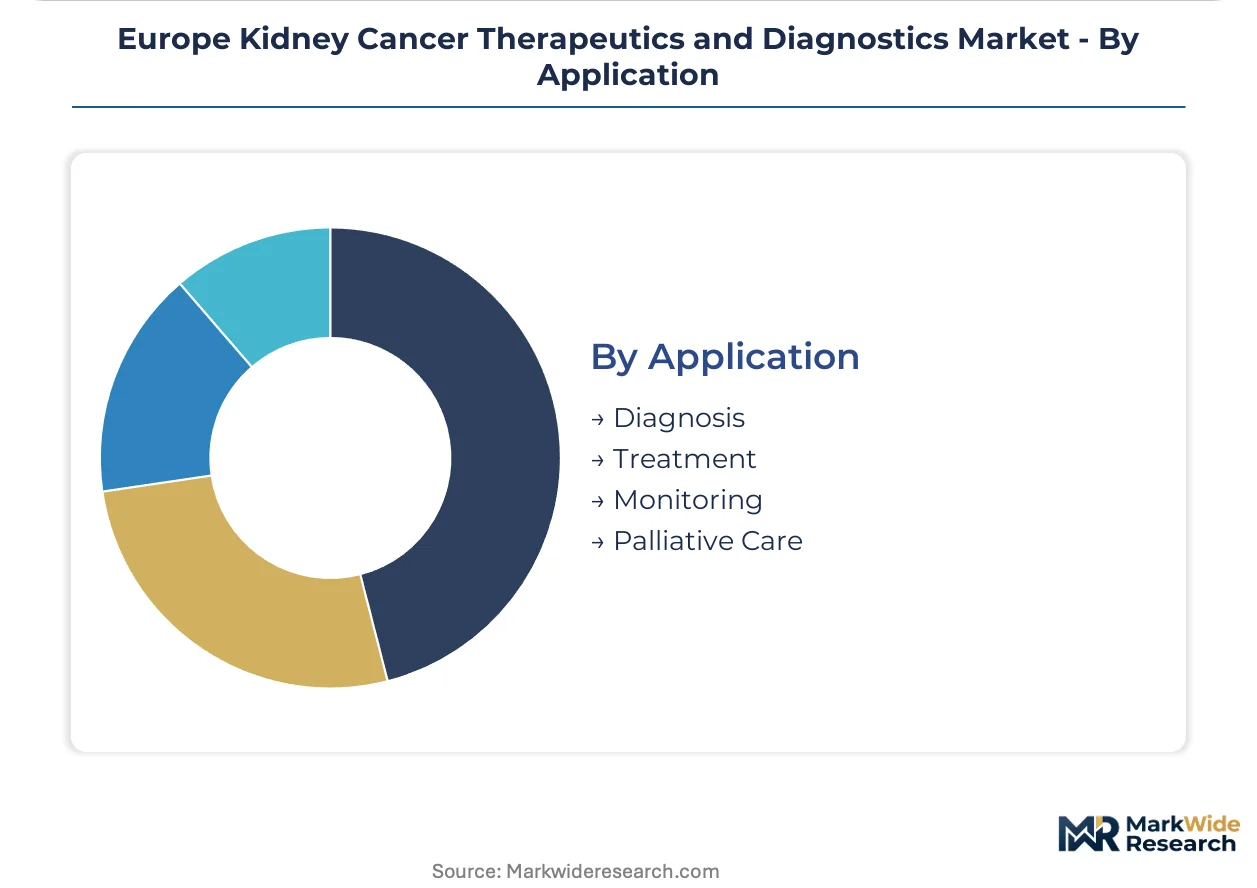
Application:
Clinical purpose segments reveal where diagnostic and therapeutic investments compete for budget allocation across the patient journey.
- Treatment:Curative-intent systemic therapy and neoadjuvant protocols command the largest share of pharmaceutical expenditure. Germany's health technology assessment processes for novel combinations set reimbursement precedents across European markets.
- Monitoring:Surveillance for recurrence using imaging and emerging liquid biopsy platforms represents the fastest-expanding application. Dutch university hospitals pilot ctDNA assays for post-nephrectomy surveillance, shifting monitoring from periodic scans toward continuous molecular tracking.
- Diagnosis:Cross-sectional imaging and biopsy confirmation establish histology and stage.
- Palliative Care:Symptom-directed interventions for advanced disease.
Treatment applications capture current spending concentration; monitoring is gaining share fastest as surveillance intervals compress and molecular tools proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Main metropolitan cluster concentrates the highest diagnostic testing volume for renal cell carcinoma in Europe. France and Italy follow with expanding molecular pathology networks. Regulatory divergence across national health technology assessment bodies fragments reimbursement pathways.
Germany
University hospital purchasing cooperatives in Nordrhein-Westfalen and Bavaria centralize molecular diagnostic procurement under framework agreements. The Federal Joint Committee (G-BA) conducts health technology assessments for novel immunotherapy combinations. The Rhine-Main academic medical center cluster captures the majority of European checkpoint inhibitor administration volume.
France
Eighteen Unicancer centers integrate surgical and medical oncology with embedded biomarker testing infrastructure. The National Authority for Health (HAS) evaluates clinical benefit for reimbursement eligibility of companion diagnostics. The Île-de-France region houses the highest concentration of centralized molecular pathology laboratories.
Italy
Regional health systems consolidate molecular testing into reference laboratories across Lombardy and Emilia-Romagna. The Italian Medicines Agency (AIFA) negotiates price-volume agreements for oncology therapeutics. The Milan-Turin corridor anchors pharmaceutical distribution networks serving Mediterranean markets.
Netherlands
Dutch university hospitals pilot circulating tumor DNA assays for post-nephrectomy surveillance protocols. The Healthcare Institute (ZIN) manages conditional reimbursement for innovative diagnostics. The Utrecht-Rotterdam corridor concentrates pathology informatics development for renal mass characterization.
United Kingdom
NHS England's specialized commissioning framework directs complex renal cancer cases to designated cancer centers. The National Institute for Health and Care Excellence (NICE) publishes technology appraisals for systemic therapies. The Greater Manchester and London cancer networks consolidate genomic testing capacity.
Europe Kidney Cancer Therapeutics and Diagnostics Market Competitive Landscape
German and Swiss pharmaceutical anchors occupy the premium therapeutics tier; American biotech specialists hold parallel positions in immuno-oncology combinations. The market structure concentrates around large-cap developers with EMA-approved portfolios and diagnostic manufacturers with MDR-certified platforms. Three archetypes dominate: integrated pharma-diagnostic alliances, standalone targeted therapy developers, and centralized laboratory service providers. Capacity consolidation through hospital network procurement contracts and strategic technology licensing for biomarker detection platforms represent the dominant competitive moves.
Within the integrated pharmaceutical tier, Bristol Myers Squibb and Bayer AG exemplify contrasting strategic positions. Bristol Myers Squibb anchors the checkpoint inhibitor combination segment through EMA-authorized first-line protocols. Bayer AG occupies the targeted therapy specialization vector with tyrosine kinase inhibitor development. Novartis AG sits within the diagnostic-therapeutic convergence archetype through companion diagnostic coordination capabilities.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| Novartis AG |
| Bayer AG |
| GlaxoSmithKline Plc |
| Pfizer |
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Amgen Inc. |
| Others |
Supply & Pricing Matrix
Captive supply of companion diagnostic reagents by Germany's consolidated hospital purchasing cooperatives anchors both procurement leverage and pricing power across European oncology networks. This backward integration into centralized tender frameworks compresses margins for standalone IVD developers while elevating barriers for non-integrated entrants.
Pricing Analysis
Volume-vs-margin splits sharply across the European kidney cancer market: immunotherapy combinations command premium positioning through EMA fast-track exclusivity, while oral tyrosine kinase inhibitors face cost compression from Italy's regional pharmacy benefit tenders. Price differentiation rests on biomarker complexity and MDR certification tier, with Class D companion diagnostics carrying substantial compliance premiums. Pricing pressure stems from Germany's Federal Joint Committee health technology assessments, which benchmark clinical benefit against standard-of-care costs. Hospital procurement committees exhibit highest price sensitivity, whereas academic medical centers prioritize protocol innovation over unit economics.
Supply Chain Analysis
Histopathologist workforce scarcity across German and Dutch university hospital networks constrains diagnostic platform deployment regardless of manufacturing capacity. Supply concentrates in Germany, Switzerland, and the United States for precision oncology instrumentation, while reagent chemistry draws from ECHA-registered suppliers under REACH constraints. Single-source vulnerability pervades multiplex assay component sourcing, particularly for VHL mutation detection kits. Distribution runs through centralized hospital laboratory networks in France's Unicancer centers and Italy's regional reference facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: histopathologist training pipeline limitations prop pricing power for automated diagnostic platforms capable of compensating for specialist scarcity.
For Market Incumbents: To counter margin compression from centralized hospital procurement tenders, Bristol Myers Squibb and Bayer AG should deepen backward integration into companion diagnostic development, synchronizing EMA therapeutic submissions with notified body MDR reviews. Capacity addition in Poland and Romania's emerging molecular laboratory networks offers geographic diversification against Western European purchasing concentration. For New Entrants and Emerging Players: The premium-economy price-point gap in oral tyrosine kinase inhibitor monitoring creates white-space opportunity for home-based pharmacokinetic tracking services using dried blood spot sampling. Central and Eastern Europe's greenfield laboratory buildout represents the most penetrable geography, with outsourced reference testing contracts as the viable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in pharma-diagnostic alliance structures and specialized reference laboratory acquisitions. Long-term viability over the coming decade hinges on biomarker portfolio breadth and MDR certification velocity. The signal to watch is EMA oncology fast-track designation frequency, which indicates pipeline quality and regulatory relationship strength.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Coordination | Synchronized EMA and notified body submissions accelerate combined market entry timelines. |
| Central and Eastern Europe Laboratory Buildout | Greenfield installations in Poland and Romania reduce Western European sample referral dependence. |
| MDR Certification Investment | Class C and D companion diagnostics require annual surveillance audits under EU Medical Device Regulation. |
| Liquid Biopsy Platform Development | Circulating tumor DNA assays shift post-surgical monitoring from imaging toward continuous molecular surveillance. |
| Hospital Procurement Contract Consolidation | Germany's university hospital purchasing cooperatives dominate reagent and instrument acquisition frameworks. |
Research Methodology
Independent corroboration across EMA regulatory filings, hospital procurement databases, and French HAS reimbursement decisions underwrites the qualitative findings in this study. Primary interviews with oncology department heads, molecular pathology laboratory directors, hospital procurement managers, and pharmaceutical regulatory affairs leads combined with secondary validation from ClinicalTrials.gov records, EU Medical Device Regulation notified body documentation, and national health technology assessment body publications. Bottom-up and top-down triangulation anchored segmentation-level estimates against aggregate market sizing.
Rate-of-change decomposition across therapeutic modality, delivery mode, end-user setting, and application purpose structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories and pricing evolution assumptions, with immunotherapy adoption curves and molecular diagnostic centralization patterns serving as primary forecast inputs.
Underlying measurement precision varies by segment; immunotherapy volume estimates carry tighter precision than emerging liquid biopsy surveillance due to established hospital billing records. Forecasts reflect assumptions regarding EMA approval timelines, MDR implementation enforcement, and national reimbursement negotiations. Material deviation in health technology assessment outcomes or histopathologist workforce expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market