
 Early-Stage Lung Cancer Diagnostics Therapy Market | 2026-2036
Early-Stage Lung Cancer Diagnostics Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Early-Stage Lung Cancer Diagnostics Therapy Market Foresight
A shortage of molecular pathologists trained in next-generation sequencing interpretation is reorganizing how diagnostic laboratories build staffing models and partner with technology vendors. F. Hoffmann-La Roche Ltd leverages its integrated diagnostics portfolio to anchor clinical trial partnerships across academic medical centers. Thermo Fisher Scientific sustains instrument placement through reagent rental programs that lock in consumable revenue streams. Illumina Inc. dominates sequencing hardware installed base in oncology, giving it channel control over emerging assay developers.
Early-stage lung cancer diagnostics therapy encompasses the detection, characterization, and therapeutic guidance of lung malignancies prior to metastatic spread, employing modalities that resolve nodules under three centimeters and detect circulating tumor DNA at allelic frequencies below one percent. Its commercial purpose centers on shifting patient identification from symptomatic presentation to asymptomatic screening intervals, thereby expanding the resectable candidate pool. Liquid biopsy and biomarker tests are capturing margin pools as physicians seek tissue-sparing alternatives for patients with inadequate tumor samples. Genomic sequencing competes with imaging tests for initial risk stratification, though CT scan retains its position as the gatekeeping modality for screening eligibility under established guidelines. Diagnostic laboratories occupy the fastest-growing end-user channel as centralized testing models reduce per-sample costs.
The FDA breakthrough device program and Medicare National Coverage Determinations shape reimbursement access and commercial viability for novel diagnostics in the United States. The Centers for Medicare & Medicaid Services lung cancer screening coverage framework directly determines addressable patient volume for companion diagnostic developers. Stakeholders must monitor how the FDA's evolving stance on artificial learning-based diagnostic algorithms reshapes predicate pathways and clinical evidence requirements for premarket submissions.
Market Dynamics
Liquid biopsy platforms are compressing tissue-based diagnostic timelines while Medicare coverage determinations for lung cancer screening create volume pull-through for companion tests.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited premarket review timelines compress commercialization cycles for novel diagnostic assays targeting early-stage malignancies.
- CT-based screening protocols:United States Medicare National Coverage Determinations expand eligible patient pools for low-dose computed tomography surveillance programs.
- Next-generation sequencing panels:Multi-gene liquid biopsy workflows enable comprehensive genomic profiling from peripheral blood samples when tissue acquisition fails.
Market Restraints
- Reimbursement fragmentation:Variable private payer coverage policies create payment uncertainty for molecular diagnostic services outside Medicare fee schedules.
- Pathologist workforce constraints:Limited fellowship-trained molecular pathology specialists restrict laboratory throughput for complex genomic interpretation.
- CT radiation exposure concerns:Persistent clinical anxiety regarding cumulative ionizing radiation dose limits annual screening compliance in risk-appropriate populations.
Strategic Opportunities
- Artificial intelligence-enabled image analysis:Machine learning algorithms applied to chest CT scans automate nodule detection and volumetric tracking for radiology workflow integration.
- Community oncology expansion:Decentralized testing models bring liquid biopsy capabilities to non-academic practice settings previously dependent on referral laboratory networks.
- Plasma-based minimal residual disease monitoring:Post-surgical circulating tumor DNA surveillance creates recurring revenue streams through longitudinal patient monitoring protocols.
Industry Challenges
- Assay analytical validation complexity:Demonstrating clinical sensitivity at allelic frequencies below 0.1 percent requires extensive reference material development and cross-platform concordance studies.
- Electronic health record integration friction:Structured genomic data interoperability with legacy hospital information systems delays test result availability at point-of-care decision moments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Early-Stage Lung Cancer Diagnostics Therapy Market |
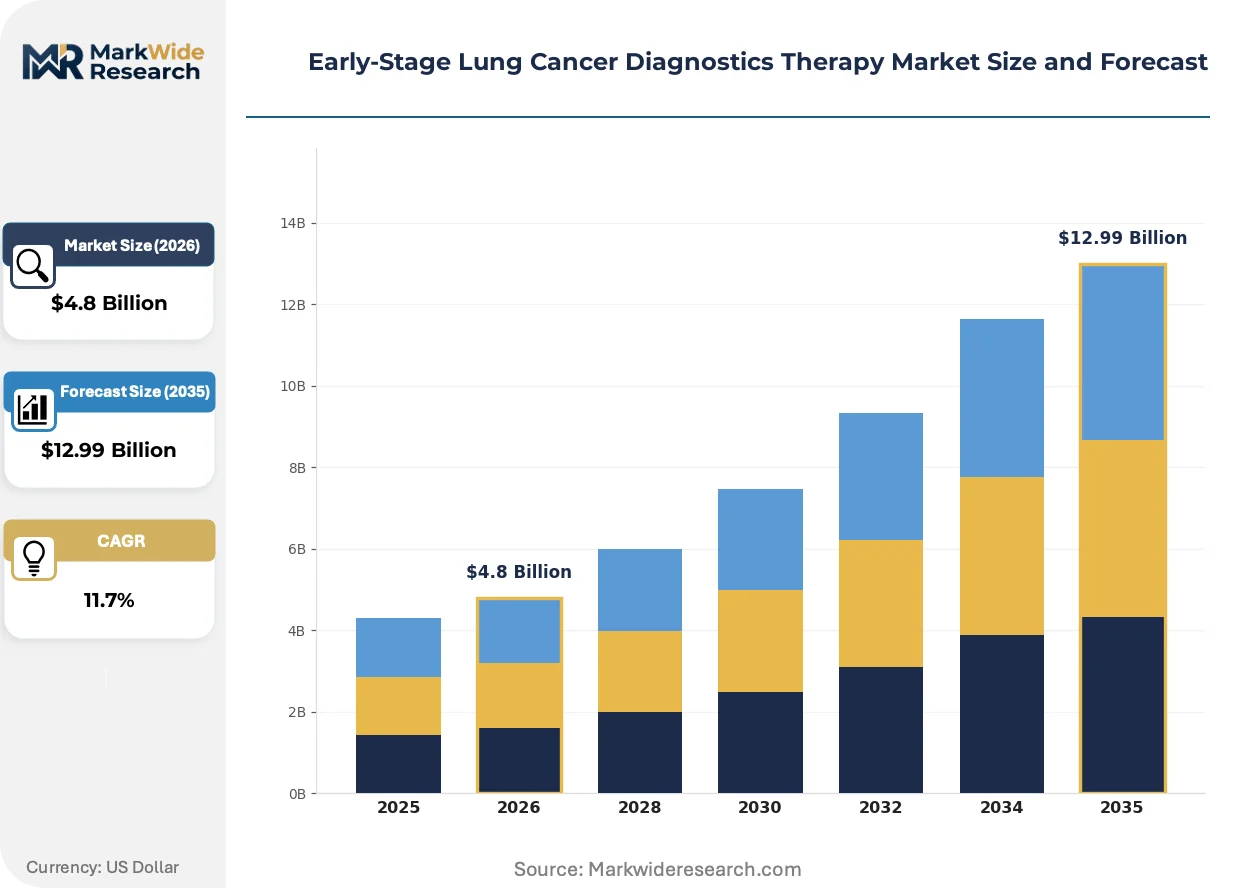
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Tests, Biomarker Tests, Bronchoscopy, Liquid Biopsy Technology: CT Scan, PET Scan, MRI, Genomic Sequencing End User: Hospitals, Diagnostic Laboratories, Oncology Clinics, Research Institutions Application: Screening, Diagnosis, Treatment Monitoring, Prognosis |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Illumina Inc., Agilent Technologies, QIAGEN, Abbott Laboratories, Myriad Genetics, Inc., Guardant Health, Inc., bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Early-Stage Lung Cancer Diagnostics Therapy Market Shifts & Advancements
Digital pathology workflows and artificial intelligence-augmented image analysis are reconfiguring how diagnostic laboratories process tissue specimens and report results to treating oncologists.
Microfluidic sample preparation systems for circulating tumor DNA extraction are miniaturizing laboratory infrastructure requirements. Community hospital laboratories lacking high-complexity molecular testing capacity are adopting cartridge-based platforms to retain specimen volume locally. This technology shift is compressing the addressable market for centralized reference laboratories while expanding test access to underserved geographic regions.
The FDA's evolving framework for artificial intelligence-based diagnostic algorithms is reshaping predicate pathway requirements for premarket submissions. Software-as-medical-device classifications now demand prospective clinical validation studies rather than retrospective algorithm training demonstrations. Early-stage lung cancer screening device developers are responding by embedding prospective trial designs into initial development roadmaps.
Oncology practices are consolidating procurement decisions for molecular diagnostic services under centralized value analysis committees. Individual physician test ordering autonomy is yielding to standardized pathway protocols that designate preferred laboratory vendors based on quality metrics and episode-based pricing agreements. This behavioral shift is most visible in United States integrated delivery networks where capitated reimbursement models align diagnostic selection with total cost of care accountability.
Early-Stage Lung Cancer Diagnostics Therapy Market Segmentation
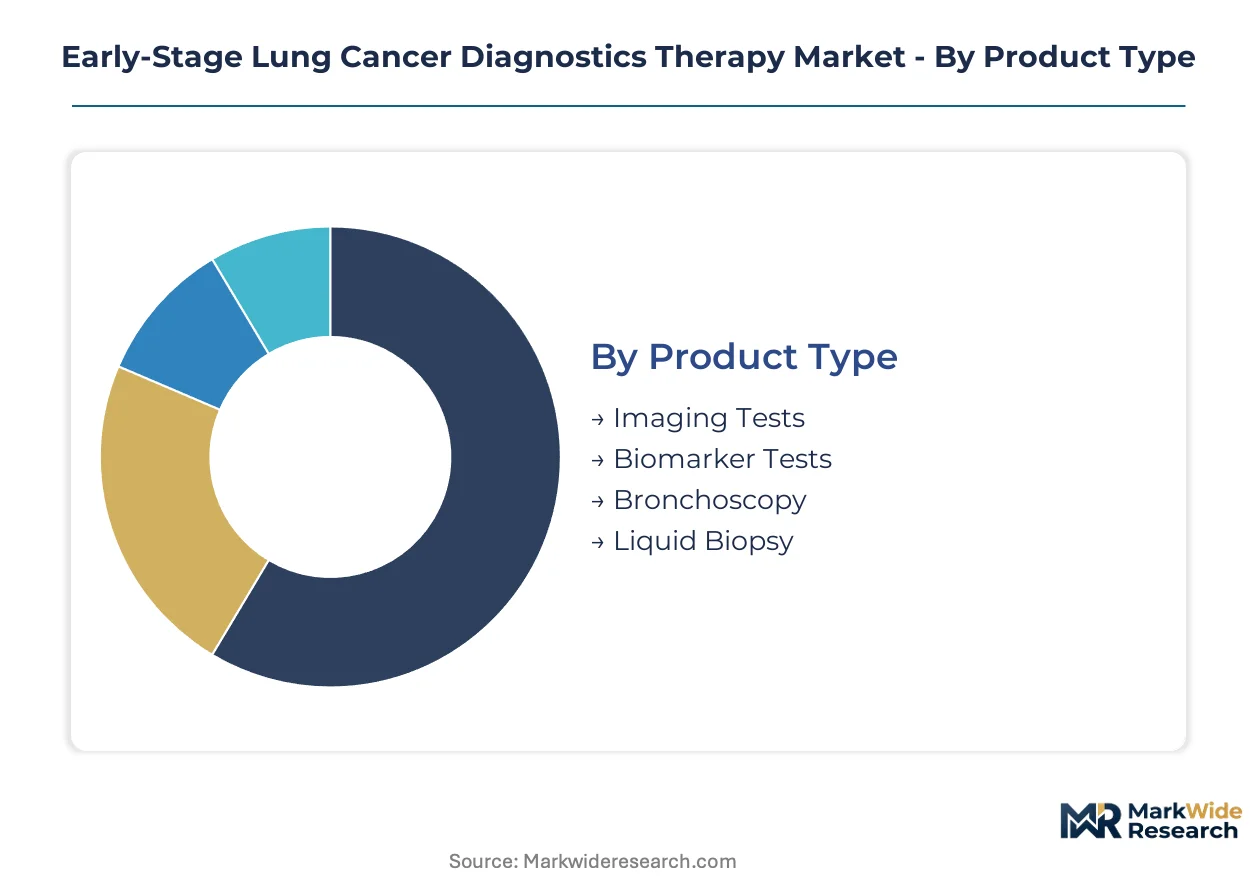
Segmentation in early-stage lung cancer diagnostics reveals how substitute technologies compete for the same clinical decision points. Liquid biopsy workflows now challenge imaging for initial risk stratification, while genomic sequencing displaces single-analyte biomarker tests in academic medical centers.
Product Type:
Imaging tests face the most acute substitution pressure from blood-based alternatives that promise tissue-sparing workflows and repeat monitoring capability.
- Imaging Tests:CT, PET, and MRI modalities resolve pulmonary nodules under three centimeters with spatial precision measured in millimeters. Demand concentrates in United States integrated delivery networks where Medicare National Coverage Determinations mandate low-dose CT as the screening gatekeeper.
- Liquid Biopsy:Circulating tumor DNA detection platforms achieve analytical sensitivity below 0.1 percent allelic frequency through digital PCR and next-generation sequencing. Oncology clinics in community settings drive volume as these platforms eliminate invasive tissue acquisition for patients with inadequate tumor samples.
- Biomarker Tests:Protein and metabolite assays provide rapid turnaround for EGFR, ALK, and PD-L1 status determination.
- Bronchoscopy:Navigational bronchoscopy systems enable peripheral nodule biopsy with electromagnetic guidance.
Imaging tests anchor the volume base while liquid biopsy gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive hardware installations from consumable-driven molecular workflows.
- CT Scan:Low-dose computed tomography delivers sub-millimeter resolution at radiation doses below 3 mSv per examination. United States lung cancer screening programs at Veterans Affairs medical centers and academic hospitals generate the dominant procedure volume under Medicare reimbursement protocols.
- Genomic Sequencing:Next-generation sequencing panels profile 50-500 genes from tissue or plasma to guide targeted therapy selection. Diagnostic laboratories with centralized high-complexity certification capture margin pools as community hospitals outsource complex molecular interpretation.
- PET Scan:Fluorodeoxyglucose positron emission tomography quantifies metabolic activity for nodule characterization and staging.
- MRI:Magnetic resonance imaging provides radiation-free soft tissue contrast for patients with contraindications to iodinated contrast agents.
CT scan technology commands the installed base while genomic sequencing expands most quickly through reagent rental and partnership models.
End User:
Customer type determines procurement autonomy, with centralized value analysis committees displacing individual physician ordering in consolidated health systems.
- Diagnostic Laboratories:Centralized reference facilities and hospital-based labs process high-complexity molecular testing with CAP/CLIA accreditation. United States commercial laboratories leverage economies of scale to reduce per-sample costs for next-generation sequencing panels.
- Oncology Clinics:Community and academic oncology practices integrate point-of-care molecular testing through cartridge-based platforms. These settings prioritize rapid turnaround for treatment-naive patients where tissue acquisition has failed.
- Hospitals:Inpatient and outpatient departments coordinate multidisciplinary tumor boards for nodule management.
- Research Institutions:Academic medical centers conduct prospective validation studies for artificial intelligence algorithms and novel biomarker discovery.
Diagnostic laboratories anchor the volume base while oncology clinics gain share fastest through decentralized testing adoption.
Application:
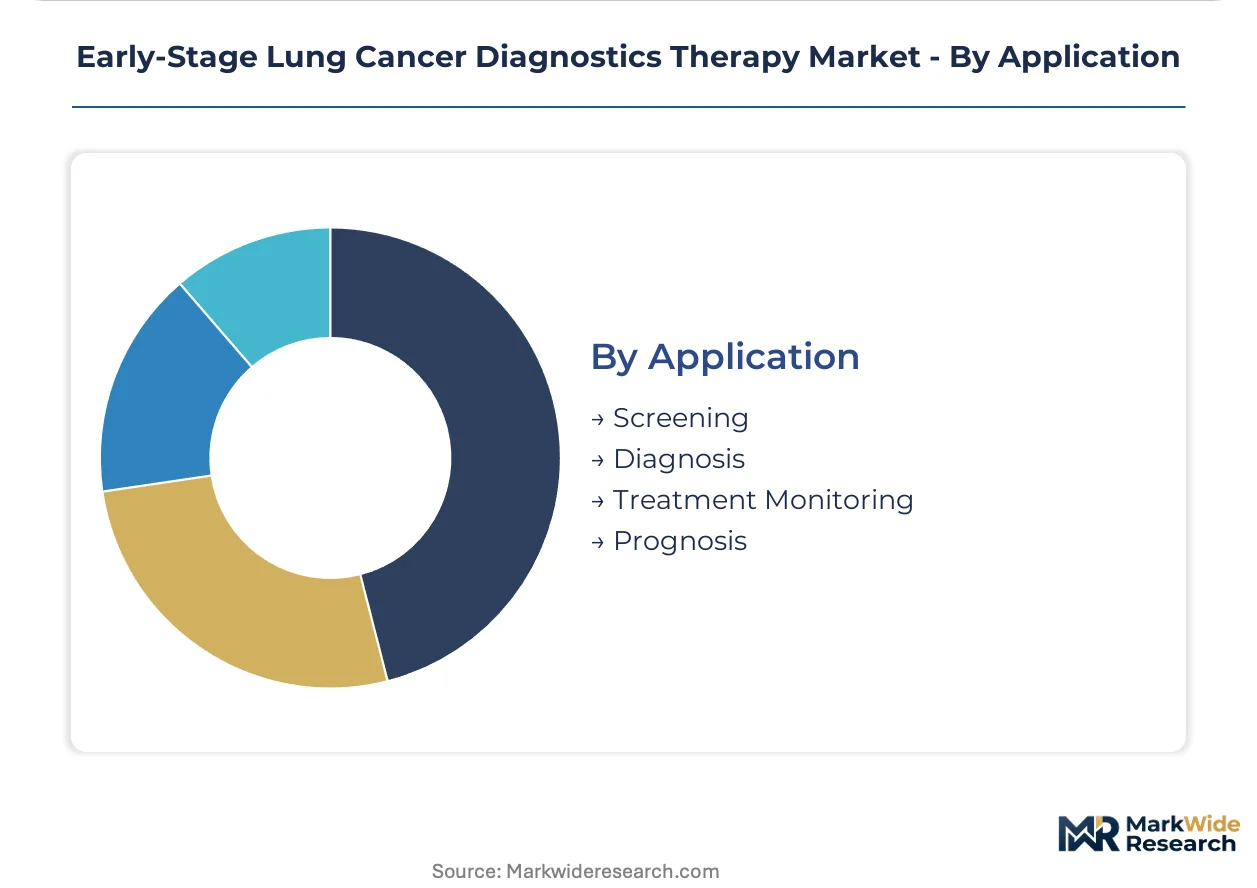
Application maturity varies sharply, with screening protocols established under guideline consensus while minimal residual disease monitoring remains investigational.
- Screening:Asymptomatic surveillance of high-risk populations using low-dose CT identifies Stage I malignancies at resectable rates exceeding 80 percent. United States Medicare coverage determinations for annual screening of 50-80 year-old smokers with 20 pack-year histories define the addressable patient pool.
- Treatment Monitoring:Serial circulating tumor DNA quantification tracks therapeutic response and detects recurrence earlier than radiographic progression. Academic medical centers in the United States pilot post-surgical surveillance protocols with quarterly plasma collection.
- Diagnosis:Tissue confirmation and molecular subtyping guide initial therapy selection for incidentally detected nodules.
- Prognosis:Genomic risk signatures stratify recurrence probability following curative-intent resection.
Screening anchors the volume base while treatment monitoring climbs the fastest toward commercial standard-of-care adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where Medicare reimbursement rates for liquid biopsy panels exceed comparable procedures in Germany by margins exceeding 40 percent. This asymmetry reflects divergent regulatory frameworks and coverage determination timelines across North American and European markets.
United States
Oncology clinics in Texas and Florida drive liquid biopsy volume as community practices adopt cartridge-based platforms for tissue-sparing workflows. The FDA breakthrough device designation pathway compresses premarket review timelines for novel diagnostic assays. Academic medical centers in Boston and Houston anchor clinical trial partnerships that validate artificial intelligence-enabled nodule detection algorithms.
Germany
Diagnostic laboratories in Bavaria and Baden-Württemberg process centralized high-complexity molecular testing under EMA harmonized standards. The EU Medical Device Regulation mandates stricter clinical evidence requirements for software-as-medical-device classifications. Industrial clusters around Munich and Heidelberg concentrate next-generation sequencing instrument installations for translational oncology research.
China
Community hospital laboratories in Shanghai and Guangzhou retain specimen volume locally through microfluidic cartridge adoption. The NMPA's evolving stance on artificial intelligence-based diagnostic algorithms reshapes predicate pathway requirements for premarket submissions. Manufacturing corridors in Suzhou and Hangzhou produce digital PCR platforms for domestic liquid biopsy workflows.
Japan
Oncology practices in Tokyo and Osaka consolidate procurement decisions under centralized value analysis committees aligned with capitated reimbursement models. PMDA regulatory timelines for companion diagnostic approvals lag FDA pathways by 18-24 months. Research institutions in Kobe and Yokohama pilot plasma-based minimal residual disease monitoring protocols for post-surgical surveillance.
United Kingdom
Integrated care systems in London and Manchester standardize molecular diagnostic pathways through episode-based pricing agreements with reference laboratories. NHS England coverage determinations for lung cancer screening create volume pull-through for companion tests. Biotech clusters in Cambridge and Oxford develop circulating tumor DNA extraction technologies for decentralized testing deployment.
Early-Stage Lung Cancer Diagnostics Therapy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated diagnostics portfolios compete against specialized liquid biopsy platforms. The market consolidates around three strategic archetypes: diversified life science conglomerates with instrument-installed bases, pure-play molecular diagnostic specialists, and emerging artificial intelligence-enabled image analysis developers. Dominant competitive moves include strategic partnerships anchoring clinical trial access and reagent rental programs locking in consumable revenue streams.
Within the diversified conglomerate tier, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific exemplify archetypes that leverage integrated portfolios to secure instrument placement and consumable lock-in. Illumina Inc. occupies a position representing sequencing hardware channel control, giving it leverage over emerging assay developers. Among specialized molecular diagnostic developers, Guardant Health, Inc. and Myriad Genetics, Inc. sit within the pure-play tier focused on tissue-sparing workflows and genomic risk stratification.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Illumina Inc. |
| Agilent Technologies |
| QIAGEN |
| Abbott Laboratories |
| Myriad Genetics, Inc. |
| Guardant Health, Inc. |
| bioMérieux |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day reagent backlogs for next-generation sequencing consumables concentrate pricing power with instrument-anchored suppliers while compressing margins for independent assay developers lacking captive manufacturing. This lead-time volatility reinforces how supply chain shape and pricing leverage intertwine in molecular diagnostics.
Pricing Analysis
Configured-to-order pricing for laboratory-developed tests commands 25-40% premiums over standardized kitted assays. The dominant pricing structure stratifies across premium, standard, and economy tiers based on turnaround time and biomarker breadth. Price differentiation hinges on FDA breakthrough device status and CAP/CLIA laboratory accreditation tier. Cost compression in the economy tier intensifies as community hospital laboratories adopt cartridge-based platforms. Community oncology clinics exhibit highest price sensitivity; academic medical centers with value analysis committees demonstrate lowest sensitivity due to episode-based pricing accountability.
Supply Chain Analysis
Single-source dependency on Illumina flowcell manufacturing in San Diego and Singapore creates chokepoint vulnerability for sequencing-dependent diagnostic workflows. Geographic supply concentration centers on the United States for sequencing hardware, Germany for precision optics components, and China for microfluidic cartridge fabrication. Raw material dependencies include semiconductor-grade silicon wafers, fluorinated polymers for microfluidics, and recombinant enzymes for DNA amplification. Tariff exposure on Chinese-manufactured cartridges presents structural risk. Distribution runs through diagnostic laboratory networks and direct-to-hospital contracts rather than traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as decentralized testing adoption creates niches for specialized liquid biopsy developers outside conglomerate-dominated sequencing hardware channels. Demand-side shift toward community oncology point-of-care workflows fragments procurement authority previously concentrated in academic medical center value analysis committees.
For Market Incumbents: Secure channel control through reagent rental programs that lock in consumable revenue streams and extend instrument placement tenure. Consolidate clinical trial partnerships with academic medical centers to anchor validation data generation for artificial intelligence-enabled diagnostic algorithms. Threat from emerging cartridge-based platform developers intensifies in community settings where tissue-sparing workflows command premium positioning. Vertical integration into microfluidic consumable manufacturing reduces cost exposure to single-source suppliers. For New Entrants and Emerging Players: Differentiate on plasma-based minimal residual disease monitoring protocols where longitudinal patient surveillance creates recurring revenue models underserved by incumbent imaging-centric portfolios. Target community hospital laboratories in underserved United States regions lacking high-complexity molecular testing capacity. Most penetrable segment: post-surgical surveillance applications currently piloted at academic medical centers. Go-to-market angle: cartridge-based platforms eliminating referral laboratory dependency for nodule management. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core diagnostic assets amid portfolio rationalization pressures. Long-term viability favors pure-play molecular diagnostic specialists with demonstrated reimbursement traction and proprietary biomarker intellectual property. Acquisition target archetype: artificial intelligence-enabled image analysis developers with FDA breakthrough device designations and prospective clinical validation data. Signal to watch: Medicare National Coverage Determination expansions for liquid biopsy companion diagnostics as inflection indicator for addressable market scaling.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited premarket review compresses commercialization timelines for novel early-stage malignancy assays. |
| Hospital System Partnership | Integrated delivery network contracts anchor volume commitments under episode-based pricing accountability. |
| Reagent Rental Program Expansion | Instrument placement with consumable lock-in secures recurring revenue against independent assay competitors. |
| Software Companion Development | Artificial intelligence-augmented image analysis embedded in radiology workflow creates differentiation from tissue-based diagnostics. |
| Community Laboratory Partnership | Decentralized testing deployment captures specimen volume outside centralized reference laboratory networks. |
Research Methodology
A standing panel of molecular pathologists, diagnostic laboratory directors, oncology practice administrators, and payer access specialists provided ongoing calibration across primary data collection. Secondary validation drew from FDA 510(k) and PMA filings, CMS National Coverage Determination documents, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up testing volume estimates triangulated against top-down Medicare reimbursement claims data.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology platform, end-user channel, and application maturity stage. CAGRs derived from logistic diffusion curves fitted to adoption rate observations. Industry-specific forecast inputs incorporated Medicare coverage determination timelines and FDA breakthrough device approval velocities.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement expansion and regulatory pathway stability would require recalibration. Forecasts reflect documented assumptions regarding screening guideline adherence and liquid biopsy analytical validation progression. Practitioners should keep alternative scenarios live as Medicare coverage determinations and FDA software-as-medical-device framework evolution reshape commercial viability timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Lung Cancer Liquid Biopsy Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market