
 Kidney Cancer Therapeutics and Diagnostics Market | 2026-2036
Kidney Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Cancer Therapeutics and Diagnostics Market Foresight
Consolidation among oncology clinic networks is recalibrating procurement patterns for kidney cancer therapeutics and diagnostics. Bristol Myers Squibb leverages its immuno-oncology portfolio to anchor relationships with integrated delivery networks. Pfizer Inc. competes through targeted therapy specialization in renal cell carcinoma lines. Novartis AG differentiates via radioligand therapy manufacturing scale across major markets.
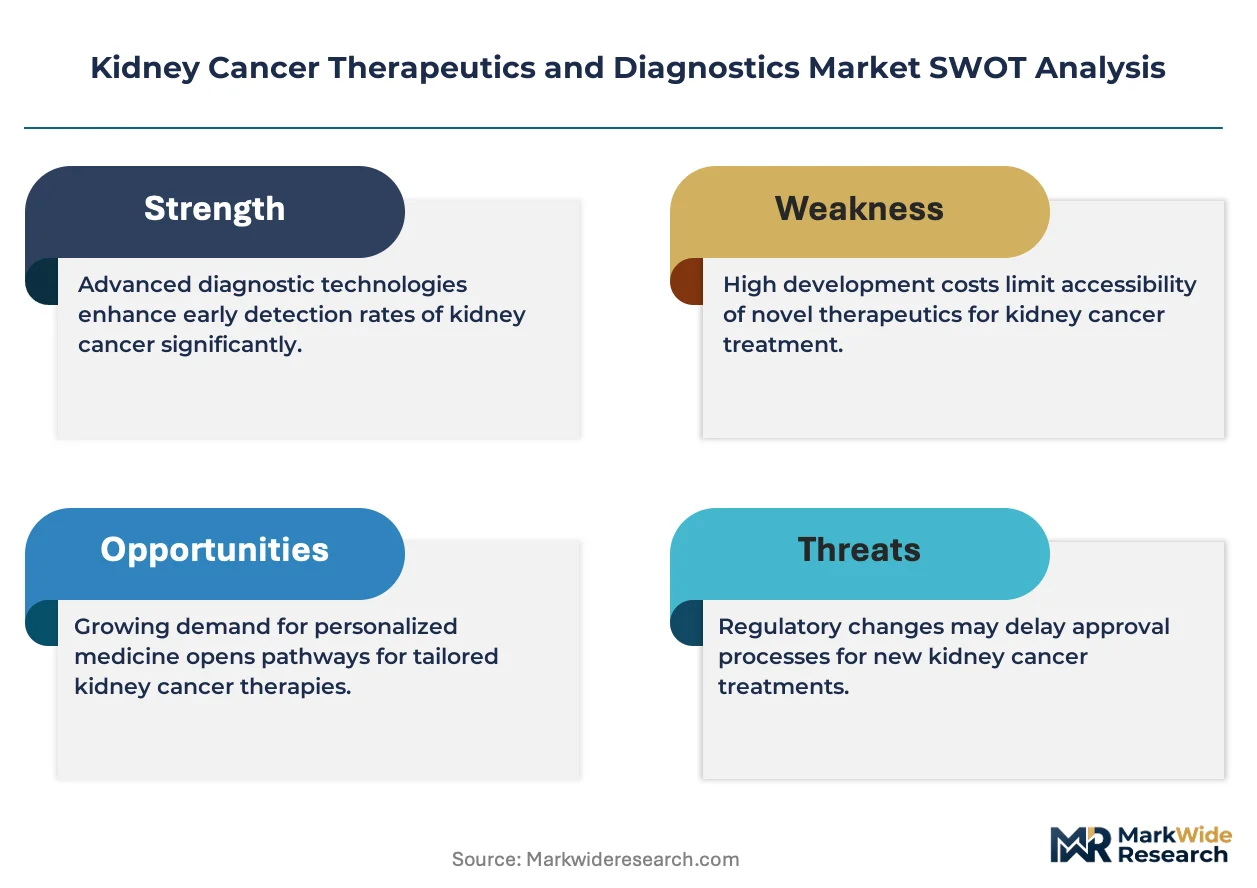
Kidney cancer therapeutics and diagnostics encompass systemic agents and molecular tools designed to treat or detect malignancies of the renal parenchyma, including tyrosine kinase inhibitors, immune checkpoint inhibitors, and ctDNA-based liquid biopsy platforms operating at detection thresholds below 0.1% variant allele frequency. Immunotherapy occupies the dominant margin pool as first-line combination regimens displace monotherapy standards, while next-generation sequencing technology leads diagnostic growth by enabling patient stratification for targeted therapy selection. Hospitals remain the primary end-user channel, though oncology clinics gain share as outpatient administration protocols expand.
FDA breakthrough therapy designations and EMA conditional approval pathways shape development timelines and commercial access for novel renal cell carcinoma agents. The EPA and OSHA frameworks govern manufacturing site compliance for biologic production facilities. Stakeholders must monitor evolving payer evidence requirements for companion diagnostic reimbursement alongside biomarker-driven therapy labels.
Market Dynamics
First-line immunotherapy combinations are compressing treatment timelines and forcing diagnostic platforms to deliver biomarker results within days rather than weeks. Hospital procurement committees now weight companion diagnostic integration as heavily as therapeutic efficacy in formulary decisions.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Accelerated review timelines for renal cell carcinoma agents compress development-to-commercialization cycles from five years to under three. Oncology clinics in the United States prioritize formulary slots for designated therapies.
- Liquid Biopsy ctDNA Sensitivity:Detection thresholds below 0.1% variant allele frequency enable minimal residual disease monitoring without invasive tissue sampling. Academic medical centers in Germany integrate these platforms into post-surgical surveillance protocols.
- Japan's PMDA Sakigake Designation:Priority review status for innovative oncology products reduces regulatory lag. Japanese referral networks for renal cell carcinoma expand molecular diagnostic capacity to match therapeutic availability.
Market Restraints
- Radioligand Manufacturing Bottlenecks:Isotope supply concentration in five North American and European production facilities creates dose allocation constraints. Lutetium-177 production schedules dictate patient eligibility windows.
- Companion Diagnostic Reimbursement Gaps:Payer evidence requirements under Germany's G-BA framework delay coverage decisions for biomarker-driven therapy labels. Testing laboratories absorb uncompensated costs during technology assessment periods.
- Immune-Related Adverse Event Management:Toxicity monitoring requirements extend hospital observation protocols. Outpatient administration expansion stalls where infusion center nursing ratios cannot support extended stays.
Strategic Opportunities
- Underpenetrated Molecular Profiling in Community Oncology:United States community practices outside major metropolitan referral networks lack next-generation sequencing infrastructure. Regional laboratory partnerships can capture specimens currently sent to academic centers.
- EMA Conditional Approval Data Collection:Post-authorization study requirements create demand for real-world evidence platforms. Registry-integrated diagnostic systems in France and Italy capture longitudinal outcomes for label expansion.
- Artificial Intelligence-Enhanced Pathology:Deep learning algorithms applied to renal tumor histology accelerate PD-L1 scoring. Convergence with digital slide scanning reduces inter-observer variability in community hospital settings.
Industry Challenges
- Biomarker Assay Harmonization:Discordant PD-L1 scoring between 22C3 and 28-8 antibody platforms complicates clinical trial enrollment. Reference standard development consumes regulatory affairs resources.
- Cold Chain Logistics for Cellular Therapies:Chimeric antigen receptor T-cell products require cryogenic transport infrastructure that most hospital pharmacies lack. Capital deployment for vapor-phase liquid nitrogen storage strains oncology unit budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Cancer Therapeutics and Diagnostics Market |
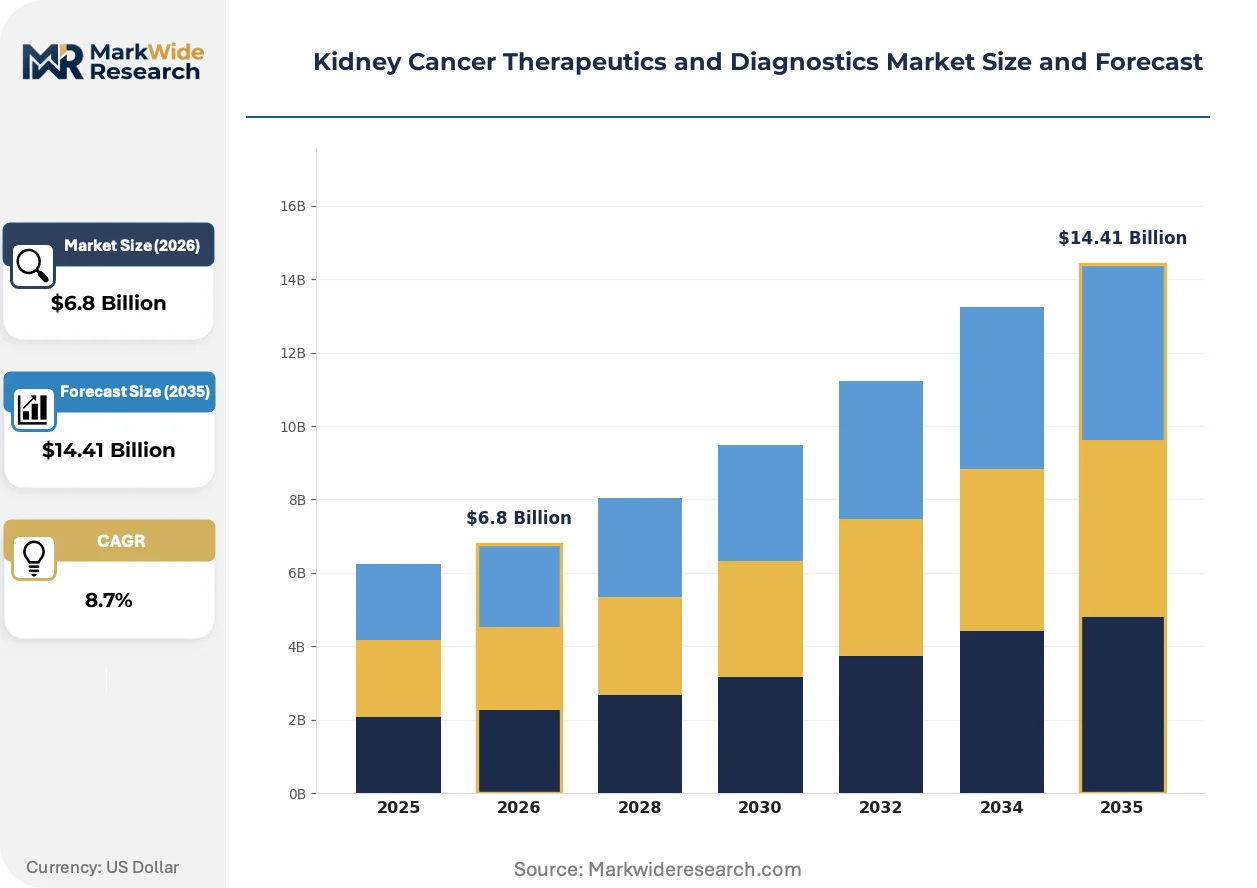
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiotherapy End User: Oncology Clinics, Hospitals, Research Laboratories, Home Care Delivery Mode: Intravenous, Subcutaneous, Oral, Topical Technology: Next-Generation Sequencing, Microarray, PCR, Biomarker Analysis |
| Companies Covered | Amgen Inc., F. Hoffmann-La Roche Ltd., Bayer AG, Bristol Myers Squibb, Pfizer Inc., Novartis AG, Abbott Laboratories, Merck & Co., Inc., Astellas Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Cancer Therapeutics and Diagnostics Market Shifts & Advancements
Liquid biopsy platforms are compressing diagnostic timelines from weeks to days, forcing tissue-based pathology into a confirmatory rather than primary role. This shift reconfigures laboratory economics and hospital referral patterns simultaneously.
Next-generation sequencing panels for renal cell carcinoma are decentralizing molecular profiling from centralized academic laboratories to community hospital pathology departments. Regional medical centers in the United States and Germany now deploy CLIA-certified platforms internally. Turnaround times compress from fourteen days to seventy-two hours, enabling same-visit treatment decisions.
The European Union's In Vitro Diagnostic Regulation (IVDR) reclassifies companion diagnostic assays as Class C devices requiring notified body review. Manufacturers face consolidated technical documentation requirements for CE marking. Smaller diagnostic developers in France and the Netherlands exit the renal cancer biomarker space rather than absorb compliance costs.
Integrated delivery networks in the United States are consolidating oncology pharmacy purchasing under centralized specialty pharmacy contracts. Hospital systems negotiate directly with manufacturers for checkpoint inhibitor and tyrosine kinase inhibitor bundles. Independent oncology clinics lose access to buy-and-bill margins as 340B program restrictions tighten.
Kidney Cancer Therapeutics and Diagnostics Market Segmentation
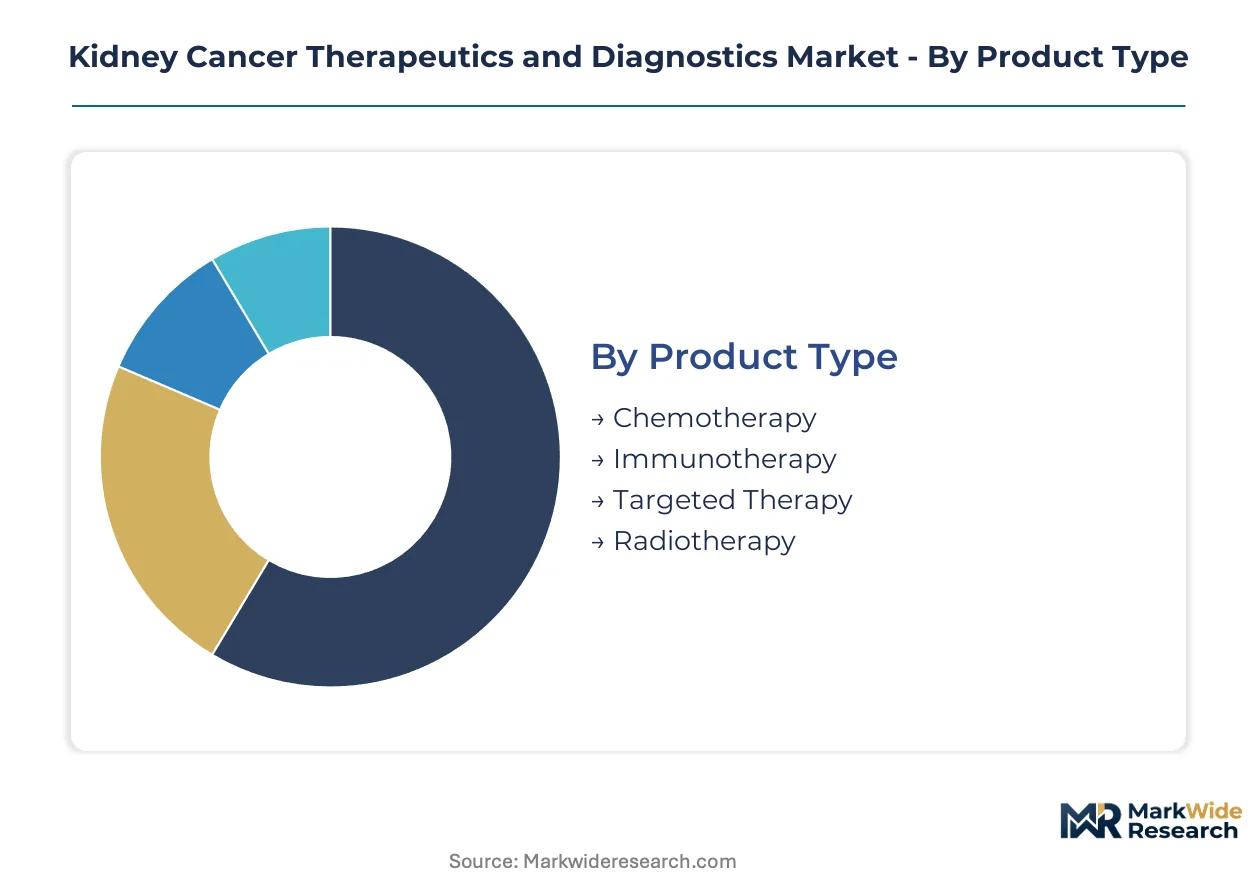
Segmentation in kidney cancer therapeutics and diagnostics determines which stakeholders control procurement decisions and which regulatory pathways govern commercial access. Product type and technology segments carry distinct FDA and EMA certification burdens that shape development timelines and reimbursement eligibility.
Product Type:
FDA breakthrough therapy designation and EMA conditional approval pathways apply unevenly across therapeutic modalities, with biologics facing distinct CMC requirements from small molecules.
- Immunotherapy:Checkpoint inhibitors and cytokine therapies command premium formulary positioning in United States oncology clinics. PD-1/PD-L1 combinations now dominate first-line renal cell carcinoma protocols, displacing prior monotherapy standards.
- Targeted Therapy:Tyrosine kinase inhibitors and mTOR inhibitors require companion diagnostic linkage for reimbursement under Medicare coverage determinations. German hospital procurement committees weight biomarker integration heavily in formulary decisions.
- Chemotherapy:Cytotoxic agents retain niche utility in sarcomatoid histology variants. Japanese referral networks deploy these regimens where immunotherapy contraindications exist.
- Radiotherapy:External beam and stereotactic ablative modalities serve oligometastatic disease management. Lutetium-177 radioligand therapy manufacturing bottlenecks constrain dose availability across North American and European production facilities.
Immunotherapy sits at the top of the volume ranking, with radiotherapy climbing the fastest as isotope supply chains mature.
End User:
Site-of-care economics and infusion infrastructure capacity determine where different therapeutic modalities concentrate administratively.
- Hospitals:Academic medical centers in the United States and Germany anchor complex immunotherapy administration and immune-related adverse event management. Extended observation protocols require nursing ratios that strain outpatient capacity.
- Oncology Clinics:Community-based infusion centers in United States metropolitan areas capture share as 340B program restrictions tighten hospital purchasing advantages. Buy-and-bill margin compression redirects patient volume.
- Research Laboratories:Centralized next-generation sequencing facilities handle specimen processing for biomarker-driven trial enrollment. CLIA certification requirements limit decentralization speed.
- Home Care:Oral tyrosine kinase inhibitor dispensing expands where pharmacy benefit management structures support remote monitoring. Adherence tracking platforms enable this shift.
Hospitals retain the dominant share position, though oncology clinics are gaining volume fastest as administration protocols simplify.
Delivery Mode:
Route of administration directly shapes cold chain requirements, nursing labor intensity, and patient convenience profiles that drive site-of-care selection.
- Intravenous:Checkpoint inhibitor infusions require controlled-temperature transport and specialized infusion center capacity. United States integrated delivery networks consolidate purchasing for these agents under centralized specialty pharmacy contracts.
- Oral:Tyrosine kinase inhibitors enable decentralized administration but require hepatotoxicity monitoring protocols. German statutory health insurance funds negotiate outcome-based rebate arrangements for these agents.
- Subcutaneous:Reduced infusion duration supports outpatient migration where nursing ratios constrain intravenous capacity. Japanese clinics favor this route for maintenance regimens.
- Topical:Limited applicability in renal cell carcinoma restricts this mode to palliative skin lesion management in metastatic presentations.
Intravenous delivery dominates current volumes, with oral formulations expanding most quickly as adherence monitoring technology matures.
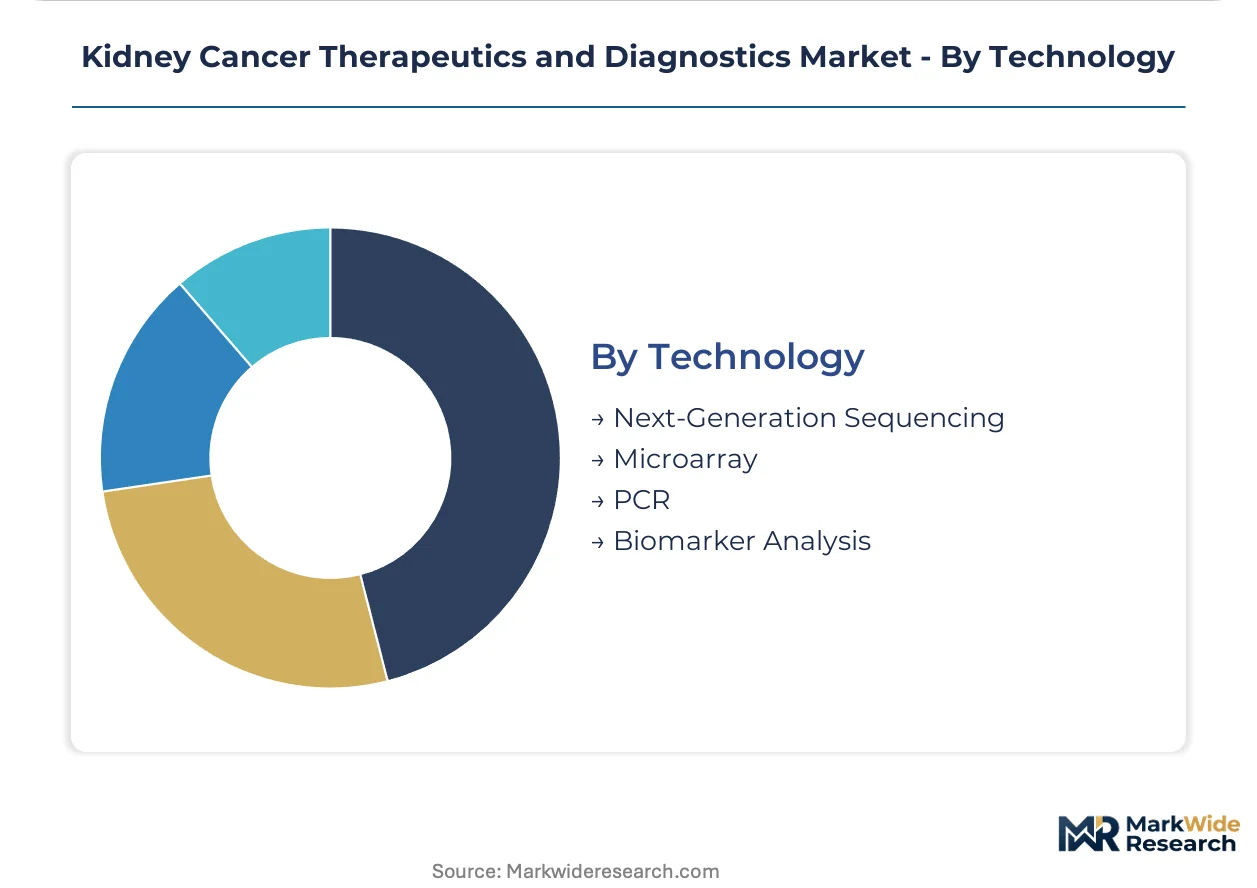
Technology:
Diagnostic platform selection determines turnaround time, sensitivity thresholds, and regulatory classification under IVDR and FDA oversight frameworks.
- Next-Generation Sequencing:Comprehensive genomic profiling panels enable patient stratification for targeted therapy selection. United States community hospital pathology departments deploy CLIA-certified platforms internally, compressing turnaround from fourteen days to seventy-two hours.
- PCR:Rapid turnaround supports same-visit treatment decisions in German academic medical centers. Limited multiplexing constrains comprehensive biomarker assessment.
- Biomarker Analysis:PD-L1 immunohistochemistry scoring guides immunotherapy eligibility, though discordance between 22C3 and 28-8 antibody platforms complicates clinical trial enrollment. Reference standard development consumes regulatory affairs resources.
- Microarray:Copy number variation analysis supports research applications but faces displacement by sequencing-based approaches in clinical diagnostic settings.
Next-generation sequencing leads the volume ranking, with biomarker analysis climbing fastest as companion diagnostic labels proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's G-BA framework demands rigorous companion diagnostic evidence, while Japan's PMDA Sakigake designation accelerates priority oncology reviews. These divergent regulatory postures create distinct procurement timelines across major markets.
United States
FDA breakthrough therapy designations compress renal cell carcinoma agent development cycles to under three years. Medicare coverage determinations mandate companion diagnostic linkage for tyrosine kinase inhibitor reimbursement. Academic medical centers in Boston and Houston anchor complex immunotherapy administration capacity.
Germany
Statutory health insurance funds negotiate outcome-based rebate arrangements for oral targeted therapies. The G-BA framework delays biomarker-driven therapy label coverage during technology assessment periods. Hospital procurement committees in Munich and Heidelberg weight diagnostic integration heavily in formulary decisions.
Japan
PMDA Sakigake designation reduces regulatory lag for innovative oncology products. Referral networks in Tokyo and Osaka expand molecular diagnostic capacity to match therapeutic availability. Extended observation protocols for immune-related adverse events strain infusion center nursing ratios.
United Kingdom
NICE technology appraisals determine NHS England commissioning for renal cell carcinoma agents. The MHRA operates under retained EU law for IVD regulation post-Brexit. Cancer Alliance networks in London and Manchester consolidate molecular profiling referrals to centralized laboratories.
France
ANSM oversees marketing authorization for radioligand therapies requiring isotope supply coordination. HAS transparency committee assessments influence hospital formulary inclusion. Academic hospitals in Paris and Lyon deploy registry-integrated diagnostic systems for EMA conditional approval data collection.
Kidney Cancer Therapeutics and Diagnostics Market Competitive Landscape
United States-based pharmaceutical conglomerates anchor the immunotherapy tier; Swiss and German specialists hold targeted therapy and diagnostic positions. Market structure concentrates around integrated oncology portfolios rather than single-product competitors. Three archetypes dominate: diversified biopharmaceutical majors with immuno-oncology depth, precision therapy specialists with companion diagnostic partnerships, and radiopharmaceutical manufacturers with isotope supply control. Competitive moves center on formulary bundling negotiations and regional laboratory partnership networks.
Among United States-based biopharmaceutical leaders, Bristol Myers Squibb and Pfizer Inc. exemplify the diversified portfolio archetype, anchoring relationships with integrated delivery networks through checkpoint inhibitor and targeted therapy combinations. Novartis AG represents the radioligand therapy specialization vector, with manufacturing scale across major markets distinguishing its competitive position.
| Leading Market Players |
|---|
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd. |
| Bayer AG |
| Bristol Myers Squibb |
| Pfizer Inc. |
| Novartis AG |
| Abbott Laboratories |
| Merck & Co., Inc. |
| Astellas Pharma Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up oncology clinic networks in the United States now control formulary negotiations for checkpoint inhibitors, compressing buy-and-bill margins and forcing manufacturers toward outcome-based contract structures that tie pricing to real-world response rates.
Pricing Analysis
Capacity additions in Germany's G-BA assessment infrastructure are reshaping price floors for companion diagnostic-linked therapies. Three-tier pricing structure across premium, standard, and economy levels separates branded immunotherapy combinations from biosimilar TKIs and generic mTOR inhibitors. Price differentiation hinges on biomarker stratification accuracy and infusion center nursing intensity. Cost compression in the oral targeted therapy tier is intensifying because German statutory health insurance funds negotiate outcome-based rebate arrangements. Community oncology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Reverse-logistics for cryogenically stored CAR-T cellular therapies requires vapor-phase liquid nitrogen transport infrastructure that most hospital pharmacies lack, creating refurbishment and remanufacturing bottlenecks for dose allocation. Active pharmaceutical ingredient production concentrates in Switzerland, Ireland, and Singapore for biologic therapies. Isotope supply for radioligand therapies draws from five North American and European production facilities. Single-source vulnerability in lutetium-177 manufacturing creates dose allocation constraints that dictate patient eligibility windows. Distribution runs through integrated delivery network specialty pharmacy contracts in the United States and hospital procurement committees in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in kidney cancer therapeutics rests on biomarker-driven patient stratification enabling premium pricing for first-line combination regimens, while diagnostic automation reduces per-test cost structures across community laboratory networks.
For Market Incumbents: Anchor formulary positioning through companion diagnostic bundling with integrated delivery networks. Defend against biosimilar TKI entry by deepening PD-1/PD-L1 combination data packages. Vertical integration into next-generation sequencing platform partnerships secures specimen flow from community oncology practices. FDA breakthrough therapy designation maintenance requires continuous real-world evidence generation. For New Entrants and Emerging Players: Japan's PMDA Sakigake designation opens a window for priority review status in renal cell carcinoma. Target underpenetrated molecular profiling in United States community practices outside major metropolitan referral networks. White-space capture in AI-enhanced pathology algorithms for PD-L1 scoring offers fastest penetration. Go-to-market through regional laboratory partnerships captures specimens currently sent to academic centers. For Investors and Strategic Acquirers: Valuations sit cheapest among diagnostic developers facing EU IVDR Class C reclassification compliance costs. Five-to-ten year viability favors radiopharmaceutical manufacturers with isotope supply control and manufacturing scale across major markets. Acquisition target archetype: precision therapy specialists with companion diagnostic partnerships and CLIA-certified platform infrastructure. Signal to watch: EMA conditional approval data collection requirements creating demand for registry-integrated diagnostic systems.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Biomarker-driven therapy labels require FDA-mandated diagnostic linkage for Medicare reimbursement eligibility. |
| Real-World Evidence Platform | Registry-integrated systems in France and Italy capture longitudinal outcomes for EMA conditional approval label expansion. |
| Radioligand Manufacturing Scale-Up | Isotope supply concentration in five North American and European facilities creates dose allocation constraints for patient eligibility. |
| AI-Enhanced Pathology Development | Deep learning algorithms for renal tumor histology accelerate PD-L1 scoring and reduce inter-observer variability. |
| Community Laboratory Partnership | Regional alliances capture specimens from United States practices lacking next-generation sequencing infrastructure. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and France, with primary inputs from each market's regulatory and reimbursement environment. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up and top-down triangulation anchored volume and value estimates across the analysis window.
Granularity-level modeling deployed treatment line, administration route, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from patient population epidemiology, therapy adoption curves, and pricing trajectory assumptions. Forecast inputs incorporated biomarker prevalence rates, companion diagnostic penetration, and site-of-care shift dynamics.
Revisions become necessary when regulatory pathway accelerations, isotope supply disruptions, or reimbursement policy shifts materialize outside modeled assumptions. Practitioners should monitor FDA breakthrough therapy designation velocity, G-BA technology assessment timelines, and PMDA Sakigake approval rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Global Nephropathic Cystinosis Treatment Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Hypothyroidism Market