
 Coal Gasification Market | 2026-2036
Coal Gasification Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Gasification Market Analysis
EPA emission standards for gasification facilities is broadening the cost-of-entry calculus for new coal-to-chemical investments. Shell leverages its proprietary gasification technology leadership across Asian project deployments. Sasol Ltd. anchors its position through deep operational experience in Fischer-Tropsch synthesis integration. Air Products and Chemicals Inc. sustains competitive differentiation via its gasification-as-a-service model and hydrogen corridor development.
Coal gasification converts solid coal into synthetic gas through partial oxidation at elevated temperatures and pressures, typically producing a hydrogen-carbon monoxide mixture for downstream chemical synthesis. The process operates at 1200–1600°C in entrained flow reactors to maximize carbon conversion efficiency and minimize tar formation. Entrained flow technology leads the technology segment due to superior feedstock flexibility and higher syngas quality for chemical applications. Hydrogen production within the product type segment is attracting capital as industrial decarbonization mandates expand offtake from refineries and ammonia plants. Chemical feedstock applications dominate the application segment, though power generation through integrated gasification combined cycle configurations retains structural importance in markets with stranded coal reserves.
China's MEE enforces dual carbon goals that constrain new coal-to-chemical approvals while grandfathering existing gasification complexes. The EU F-Gas Regulation and REACH framework restrict certain syngas-derived fluorinated product pathways, redirecting European demand toward lower-emission hydrogen alternatives. India's PLI scheme for clean hydrogen production creates indirect pressure on coal gasification economics through subsidized electrolyzer deployment. Stakeholders must monitor carbon border adjustment mechanisms and evolving green hydrogen cost curves to time capacity commitments across competing feedstock technologies.
Market Dynamics
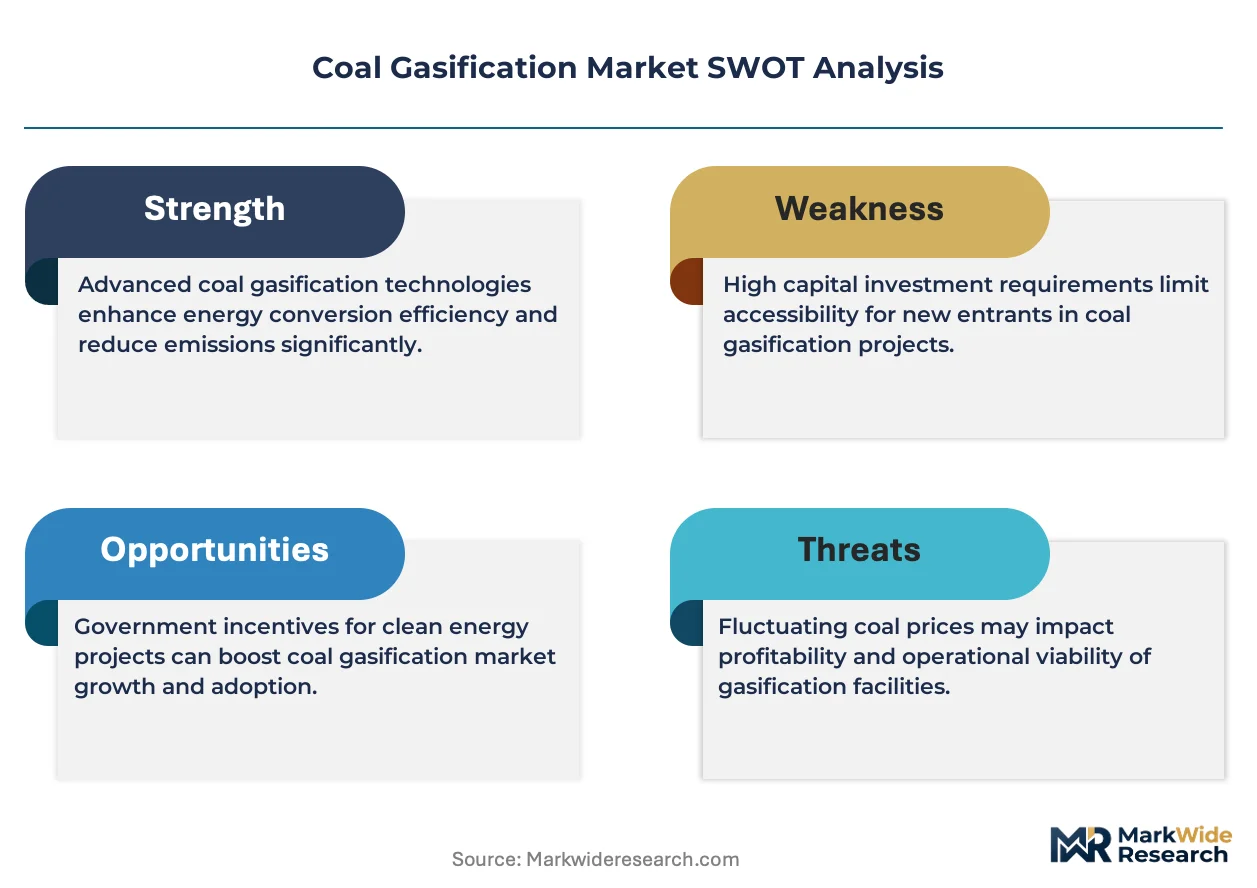
China's dual carbon goals are compressing new project approvals while tightening emission benchmarks for existing coal-to-chemical complexes, forcing operators toward carbon capture retrofits and hydrogen co-production configurations.
Growth Catalysts
- Entrained flow reactor advancement:Higher carbon conversion efficiency at 1400–1600°C reduces tar formation and expands feedstock flexibility for high-ash domestic coals in Shanxi province.
- India's PLI scheme for clean hydrogen:Subsidized electrolyzer deployment creates indirect pressure that accelerates coal gasification-to-hydrogen economics in ammonia and refinery offtake.
- Integrated gasification combined cycle expansion:Stranded coal reserves in Inner Mongolia anchor regional industrial clusters with captive power-chemical integration.
Market Restraints
- Capital intensity of carbon capture retrofits:Post-combustion amine scrubbing and pre-combustion water-gas shift systems add 30–50% to baseline gasification capex.
- Green hydrogen cost curve compression:Alkaline and PEM electrolyzer learning rates in China and Europe narrow the feedstock cost gap for ammonia and methanol synthesis.
- EU F-Gas Regulation pathway restrictions:Fluorinated product bans redirect syngas-derived chemical demand toward bio-based and electrolytic hydrogen alternatives.
Strategic Opportunities
- Carbon border adjustment mechanism timing:EU CBAM phased implementation from 2026 creates a window for low-carbon syngas certification and CCS-integrated exports.
- Blue hydrogen offtake from refineries:Hydrotreating and hydrocracking demand in Rotterdam and Singapore favors gasification-plus-CCS over unabated steam methane reforming.
- Entrained flow-biomass co-gasification:Municipal solid waste and agricultural residue blending ratios up to 20% enable partial decarbonization without full feedstock switch.
Industry Challenges
- Gasification-as-a-service contract structuring:Long-term hydrogen and syngas offtake agreements require credit-worthy counterparty pools that thin outside state-backed chemical majors.
- Fischer-Tropsch catalyst deactivation management:Cobalt and iron-based catalyst poisoning by sulfur and trace metals demands rigorous feedstock preparation and reactor turnaround scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Gasification Market |
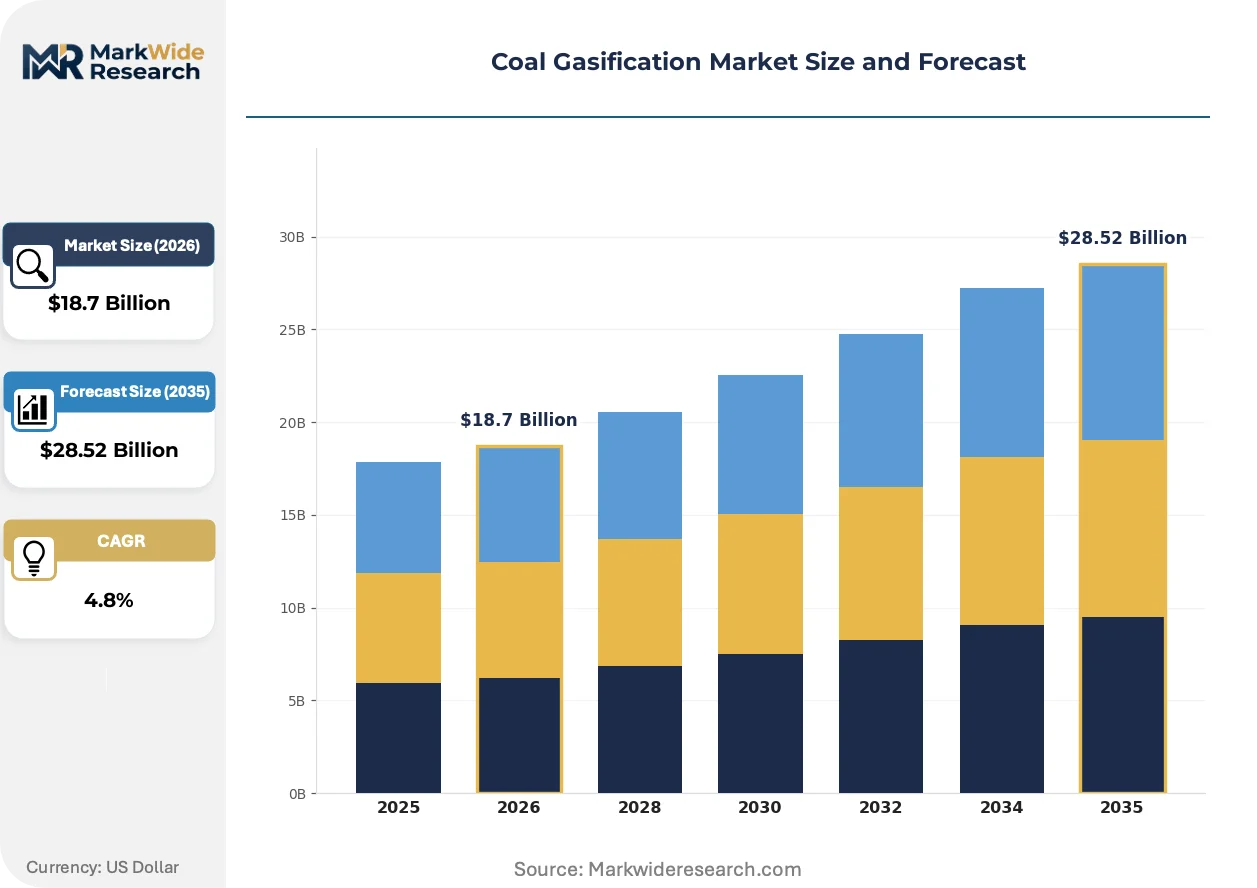
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed Bed, Fluidized Bed, Entrained Flow, Moving Bed Product Type: Synthesis Gas, Methanol, Hydrogen, Other Products Application: Power Generation, Chemical Feedstock, Transportation Fuels, Industrial Applications End User: Energy Sector, Chemicals Industry, Transportation Sector, Others |
| Companies Covered | Shell, Air Products and Chemicals Inc., Sasol Ltd., Mitsubishi Heavy Industries Ltd., Siemens AG, KBR Inc., thyssenkrupp AG, Air Liquide SA, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Gasification Market Emerging Trajectories
Technology convergence between entrained flow gasification and carbon capture systems is redefining project economics, while regulatory pressure on scope-three emissions reshapes buyer procurement criteria across chemical and refining value chains.
Membrane-based water-gas shift reactors are unifying hydrogen separation and CO2 capture in single-unit operations. Refinery operators in Singapore and Rotterdam are piloting these compact configurations to reduce footprint and steam demand. This unifying architecture compresses the capital differential between gray and blue hydrogen production pathways.
China's MEE enforcement of dual carbon goals is tightening emission benchmarks for coal-to-chemical approvals while grandfathering existing complexes under intensified monitoring. Project developers in Shanxi and Inner Mongolia now embed pre-combustion capture in front-end engineering to secure operating permits. The ammonia and methanol segments face the steepest compliance cost escalation.
Buyer procurement criteria now embed scope-three emission thresholds that disqualify unabated syngas suppliers. European chemical distributors and Japanese trading houses are consolidating supplier panels around CCS-certified gasification assets. This concentration is most visible in ammonia procurement for marine fuel and power-to-X applications.
Coal Gasification Market Segmentation
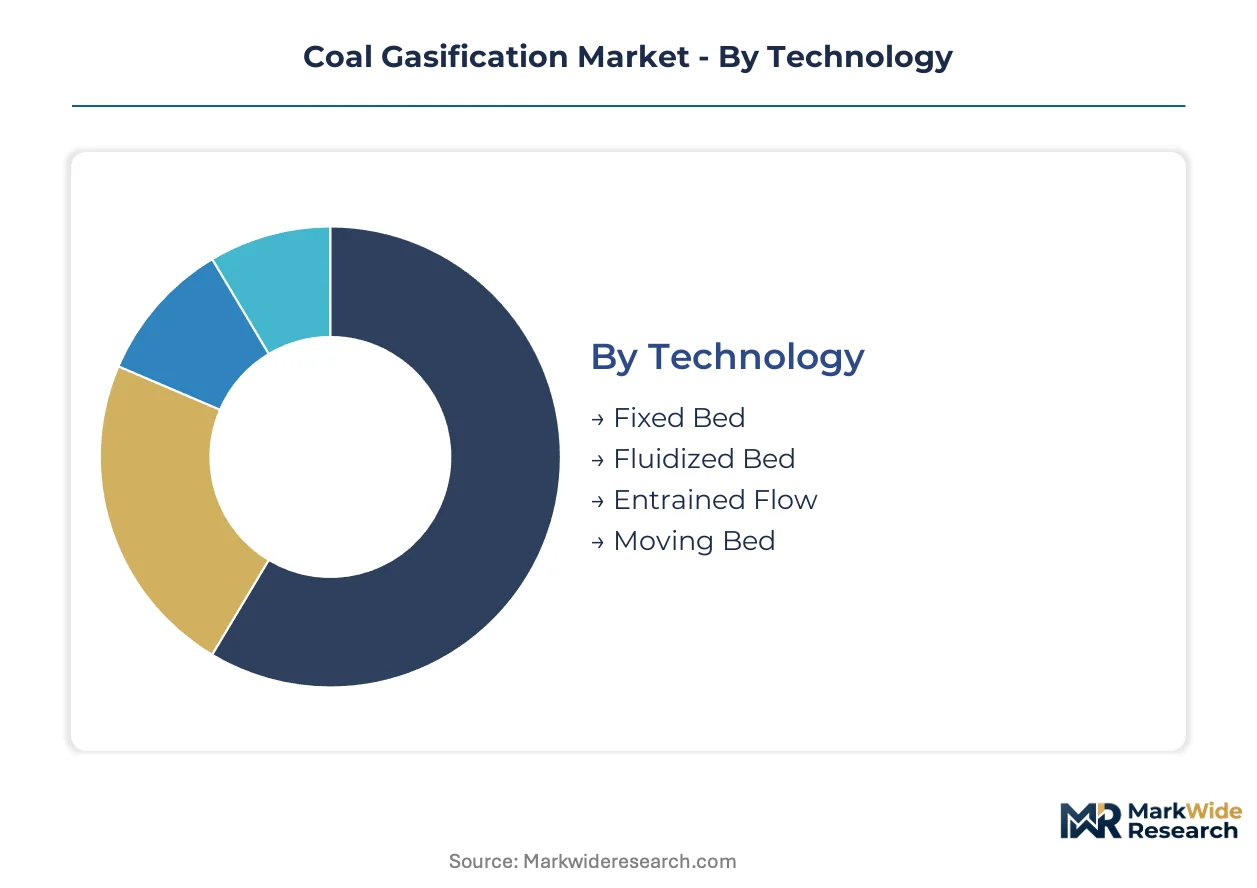
Technology choice dictates carbon conversion efficiency and feedstock tolerance, determining project viability across high-ash domestic coals versus imported bituminous supplies. End-user procurement criteria now embed scope-three emission thresholds that reshape competitive positioning across each segment boundary.
Technology:
Buyers weigh capital intensity against feedstock flexibility when selecting reactor configurations for stranded coal reserves.
- Entrained Flow:Operates at 1400–1600°C with pulverized coal injection to achieve carbon conversion above 99% and eliminate tar formation. Demand concentrates in Shanxi province where high-ash domestic coals require superior slagging tolerance to meet chemical-grade syngas specifications.
- Fluidized Bed:Maintains 800–1000°C through circulating bed material that enables uniform temperature distribution and moderate feedstock flexibility. Operators in Inner Mongolia favor this configuration for captive power-chemical integration where scale economics outweigh absolute syngas purity requirements.
- Fixed Bed:Counter-current gasification at 800–1100°C suits lump coal feedstocks with established reactor designs.
- Moving Bed:Continuous ash removal enables sustained operation with high-ash coals in legacy industrial clusters.
Volume sits with Entrained Flow; growth tilts toward Fluidized Bed.
Product Type:
Downstream offtake contracts determine product slate optimization, with hydrogen corridors reshaping investment priorities.
- Hydrogen:Water-gas shift reactors upgrade syngas to hydrogen-rich streams for ammonia synthesis and refinery hydrotreating. Rotterdam and Singapore refineries are contracting blue hydrogen offtake from gasification-plus-CCS configurations ahead of EU CBAM implementation.
- Synthesis Gas:The H2-CO mixture serves Fischer-Tropsch synthesis and chemical manufacturing with adjustable ratios through shift reactors. China's coal-to-chemical complexes in Ningxia and Shaanxi anchor regional demand as MEE emission benchmarks tighten.
- Methanol:Direct syngas conversion to methanol for olefins production and marine fuel blending.
- Other Products:Includes substitute natural gas and ammonia derivatives for specialized chemical applications.
Synthesis Gas commands installed capacity; hydrogen climbs the fastest on decarbonization mandates.
Application:
Carbon border adjustment mechanisms are redirecting procurement toward certified low-carbon syngas pathways.
- Chemical Feedstock:Syngas-derived methanol, ammonia, and olefins supply polymer and fertilizer value chains. European chemical distributors are consolidating supplier panels around CCS-certified assets as scope-three thresholds harden in procurement criteria.
- Power Generation:Integrated gasification combined cycle configurations convert syngas to electricity with lower emissions than pulverized coal plants. Stranded coal reserves in South Africa and Indonesia anchor captive power for remote industrial facilities.
- Transportation Fuels:Fischer-Tropsch synthesis produces diesel and jet fuel substitutes for military and aviation offtake.
- Industrial Applications:Direct reduction iron and cement kiln fuel substitution in carbon-intensive manufacturing.
Chemical Feedstock dominates revenue; Power Generation gains share fastest on stranded asset utilization.
End User:
Credit-worthy counterparty pools thin outside state-backed majors, constraining gasification-as-a-service contract structures.
- Chemicals Industry:Ammonia, methanol, and olefins producers purchase syngas under long-term offtake agreements. India's PLI scheme for clean hydrogen creates indirect pressure that accelerates coal gasification-to-hydrogen economics in refinery and fertilizer applications.
- Energy Sector:Utilities and independent power producers deploy IGCC for baseload generation with carbon capture retrofits. China's state-owned power generators dominate project development as dual carbon goals constrain private capital entry.
- Transportation Sector:Aviation and marine fuel offtakers seek synthetic fuels from Fischer-Tropsch integration.
- Others:Includes steel and cement producers testing syngas for process heat decarbonization.
Chemicals Industry anchors contract volumes; Energy Sector shows steepest expansion trajectory on CCS integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coal-to-chemical demand concentrates in Shanxi and Inner Mongolia where integrated gasification complexes anchor regional industrial clusters. Project developers embed carbon capture systems to satisfy tightening emission benchmarks. The regulatory landscape diverges sharply across major economies.
China
Shanxi province operators deploy entrained flow reactors to process high-ash domestic coals for chemical-grade syngas. MEE enforcement of dual carbon goals constrains new approvals while grandfathering existing complexes under intensified monitoring. Ningxia and Shaanxi coal-to-chemical hubs face the steepest compliance cost escalation as pre-combustion capture becomes mandatory for permit renewal.
United States
Gulf Coast refineries contract blue hydrogen offtake from gasification-plus-CCS configurations ahead of potential carbon border adjustments. EPA emission standards broaden the cost-of-entry calculus for new coal-to-chemical investments. Wyoming and North Dakota stranded coal reserves anchor pilot projects for substitute natural gas and power-chemical integration.
India
PLI scheme subsidies for clean hydrogen production create indirect pressure that accelerates coal gasification-to-hydrogen economics in ammonia and refinery applications. CEA mandates on captive power emissions push operators toward IGCC retrofits. Odisha and Jharkhand industrial corridors host the most advanced project pipelines for Fischer-Tropsch fuel synthesis.
Germany
EU F-Gas Regulation and REACH framework restrict certain syngas-derived fluorinated product pathways, redirecting demand toward lower-emission hydrogen alternatives. CBAM phased implementation from 2026 creates a window for CCS-certified syngas exports. Rotterdam-adjacent chemical distributors consolidate supplier panels around certified low-carbon assets.
South Africa
Sasol-operated Fischer-Tropsch complexes in Secunda and Sasolburg represent the world's largest coal-to-liquids installation. National treasury carbon tax escalation forces catalyst deactivation management improvements and sulfur removal investments. Mpumalanga coal belt anchors captive power generation for remote mining and industrial facilities.
Coal Gasification Market Vendor Landscape
Chinese state-backed producers anchor one tier; European and Japanese technology specialists hold licensing and equipment supply positions. The vendor base separates into integrated project developers, technology licensors, and gasification-as-a-service operators. Three archetypes dominate: state-owned chemical majors with captive coal reserves, engineering conglomerates with proprietary reactor designs, and industrial gas suppliers with hydrogen corridor strategies. Competitive moves concentrate on carbon capture retrofits and long-term offtake contract structuring.
Within the technology licensor tier, Shell and Mitsubishi Heavy Industries occupy positions defined by entrained flow reactor deployments across Asian project sites. Sasol Ltd. exemplifies the integrated operator archetype through deep operational experience in Fischer-Tropsch synthesis integration. Air Products and Chemicals Inc. represents the service-model vector via gasification-as-a-service contracting and hydrogen infrastructure development.
| Leading Market Players |
|---|
| Shell |
| Air Products and Chemicals Inc. |
| Sasol Ltd. |
| Mitsubishi Heavy Industries Ltd. |
| Siemens AG |
| KBR Inc. |
| thyssenkrupp AG |
| Air Liquide SA |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Captive integration of coal reserves with gasification complexes anchors supply positions and pricing power for state-backed operators in Shanxi and Inner Mongolia. This vertical control over feedstock insulates project developers from seaborne coal volatility while compressing syngas cost curves for downstream chemical offtake.
Pricing Analysis
Volume contracts dominate the premium tier while spot transactions concentrate in the economy segment. Price differentiation rests on CCS certification grade and offtake duration, with Rotterdam refineries paying premiums for blue hydrogen credentials. Cost compression in the standard tier is intensifying because green electrolyzer learning curves in China narrow feedstock cost gaps. State-backed chemical majors exhibit lowest price sensitivity; independent ammonia producers face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with Chinese refractory suppliers for entrained flow reactor linings. Manufacturing concentrates in China, Germany, and Japan for gasification reactor vessels, syngas compressors, and water-gas shift catalysts. Raw material dependencies draw from South African cobalt for Fischer-Tropsch catalysts, Mongolian coking coal for feedstock blending, and Qatari helium for instrumentation. Tariff exposure on alloy steel imports threatens project timelines. Distribution runs through EPC-led turnkey contracting with state-backed offtake guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coal gasification sector occupies a technology-transition phase as entrained flow gasification-plus-CCS configurations displace unabated steam methane reforming for blue hydrogen production.
For Market Incumbents: Extend entrained flow technology leadership through carbon capture retrofit bundling in Shanxi and Ningxia complexes. Deepen operational experience in Fischer-Tropsch catalyst management to defend against electrolytic hydrogen cost curves. Secure long-term syngas offtake with European chemical distributors ahead of EU CBAM implementation. For New Entrants and Emerging Players: The premium-to-economy price-point gap in hydrogen offtake contracts creates entry space for modular gasification-as-a-service operators. Target India's refinery hydrogen corridors where PLI-subsidized electrolyzers have not yet achieved scale. Pursue joint development agreements with stranded coal asset holders in Indonesia and South Africa. For Investors and Strategic Acquirers: Exit pathways concentrate in technology licensing to state-backed EPC consortia rather than asset-heavy project ownership. Five-to-ten year viability hinges on carbon border adjustment mechanism enforcement timing and green hydrogen cost parity trajectories. Acquire engineering firms with proprietary entrained flow designs and Asian project reference lists. Watch EU CBAM compliance cost pass-through rates as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Bundling | Pre-combustion capture integration with entrained flow reactors satisfies MEE permit requirements in Shanxi province. |
| Backward Integration into Coal Reserves | Captive Mongolian and Indonesian coal supply hedges against seaborne price volatility for IGCC operators. |
| Hydrogen Corridor Development | Pipeline networks from Rotterdam gasification hubs connect refinery offtakers with CCS-certified blue hydrogen. |
| Fischer-Tropsch Catalyst R&D Partnership | Cobalt catalyst poisoning resistance improvements extend reactor turnaround intervals at Sasol Secunda complexes. |
| Long-term Syngas Offtake Agreements | European chemical distributors consolidate supplier panels around CCS-certified assets for ammonia procurement. |
Methodological Framework
Trade databases, EIA energy outlooks, and SEC filings from engineering conglomerates formed the secondary backbone for demand modeling and competitive positioning. Primary interviews with gasification plant managers, downstream chemical procurement leads, EPC contractors, and hydrogen corridor developers validated capacity utilization assumptions and technology adoption timelines. Bottom-up and top-down triangulation reconciled project-level capex disclosures with national production statistics.
Bottom-up modeling aggregated individual project pipelines across Shanxi, Inner Mongolia, Ningxia, and Shaanxi provinces while top-down analysis tracked national coal-to-chemical capacity targets under China's dual carbon goals. Segmentation dimensions spanned reactor technology type, product slate optimization, end-use industry vertical, and regional regulatory framework clusters. CAGRs were derived from fitted growth curves against historical capacity commissioning rates and policy enforcement intensity. Forecast inputs included MEE emission benchmark trajectories and EU CBAM phased implementation schedules.
Inputs from Chinese provincial DRCs and European chemical industry associations were available through the study window; gaps in private EPC contract terms introduce uncertainty bands around project timing assumptions. Forecasts reflect documented assumptions on carbon capture cost curves and hydrogen offtake contract durations. Green electrolyzer learning rates, carbon border adjustment enforcement delays, and Fischer-Tropsch catalyst breakthroughs could materially revise trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Butane Gas Cartridges Market
Fuels
Biobutanol Market
Fuels
Storage Tank Market
Fuels
Diesel Fuel Market
Fuels
Aviation Fuel Additives Market
Fuels
Charcoal Briquette Market
Fuels
Mobile Fuel Delivery Market
Fuels
Fuel Grinder Market
Fuels
Solid Fuel Tablet Market
Fuels
LNG As a Fuel Market
Fuels
Diesel Fuel Water Separator Market
Fuels
India Petrol Station Market
Fuels
Smart Gas Solutions Market
Fuels
Global Methane Hydrate Market
Fuels
Smart Gas Market
Fuels
Europe Wood Pellet Market