
 India Retail Fuel Market | 2026-2036
India Retail Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
India Retail Fuel Market Foresight
The FAME India scheme and state-level EV mandates is rebalancing fuel station economics toward dual-energy retail formats. Indian Oil Corporation Ltd anchors the national network through its extensive pipeline-fed outlet infrastructure. Nayara Energy Limited competes on the west coast with import-terminal proximity and premium branding. Jio-bp differentiates through digital payment integration and loyalty-linked fuel pricing at select urban locations.
India retail fuel encompasses the downstream sale of refined petroleum products and compressed gases through dedicated dispensing infrastructure, with octane ratings for petrol typically spanning 87 to 99 and diesel graded by cetane number and sulfur content for emission compliance. The primary commercial purpose is to power internal combustion engines across passenger, commercial, and agricultural machinery. Diesel retains structural dominance in tonne-kilometer economics for long-haul trucking, while CNG segments expand fastest along urban bus and three-wheeler corridors where piped distribution exists. Fleet operators as a customer type concentrate margin pools through negotiated bulk contracts and captive bunkering arrangements.
The Petroleum and Natural Gas Regulatory Board governs city gas distribution licensing, while the Central Pollution Control Board enforces Bharat Stage VI emission standards that constrain sulfur levels in retail fuels. BIS certification mandates product quality at the nozzle, shaping refinery upgrade cycles and import sourcing decisions. Stakeholders must monitor state-level EV penetration targets and CNG network buildouts to calibrate capital allocation between conventional pumps and alternative fuel dispensers.
Market Dynamics
Fleet operators are consolidating fuel procurement around highway corridors and logistics hubs, compressing margins for standalone retail outlets while rewarding integrated bunkering networks with volume guarantees and captive demand.
Growth Catalysts
- FAME India scheme:State-level EV mandates are forcing fuel retailers to reconfigure forecourts for dual-energy dispensing, expanding addressable service per square meter of real estate.
- Maharashtra-Gujarat-Tamil Nadu corridor:Refinery infrastructure density and urban vehicle concentration create self-reinforcing demand pools that attract downstream capital allocation.
- Compressed natural gas:City gas distribution licensing under PNGRB is extending piped networks along urban bus and three-wheeler routes, opening new dispenser economics.
Market Restraints
- Crude import dependency:Indian refiners source over 80% of feedstock from Middle Eastern and African suppliers, exposing retail margins to currency volatility and freight cost spikes.
- Bharat Stage VI compliance:Sulfur content ceilings at 10 ppm for diesel require continuous refinery hydrotreater investment, elevating working capital intensity for smaller market participants.
- Electric two-wheelers:Battery swapping networks and state subsidy stacks are eroding petrol demand in urban last-mile delivery, the highest-frequency fuel purchase segment.
Strategic Opportunities
- Eastern and northeastern states:Pipeline-fed retail infrastructure remains underdeveloped in Bihar, Odisha, and Assam, creating first-mover advantages for network builders.
- PLI scheme for alternative fuels:Production-linked incentives for green hydrogen and ethanol blending are redirecting capex toward biofuel dispensing and flex-fuel compatibility.
- Digital payment-loyalty convergence:Real-time pricing linked to consumer data platforms enables dynamic margin management and cross-sell penetration at urban forecourts.
Industry Challenges
- Hydrogen handling certification:Technician training and safety protocols for high-pressure gas dispensing lag behind infrastructure deployment timelines in pilot corridors.
- Legacy pump retrofit complexity:Underground tank compatibility with ethanol blends above E20 requires site-specific engineering assessments that delay rollout schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Retail Fuel Market |
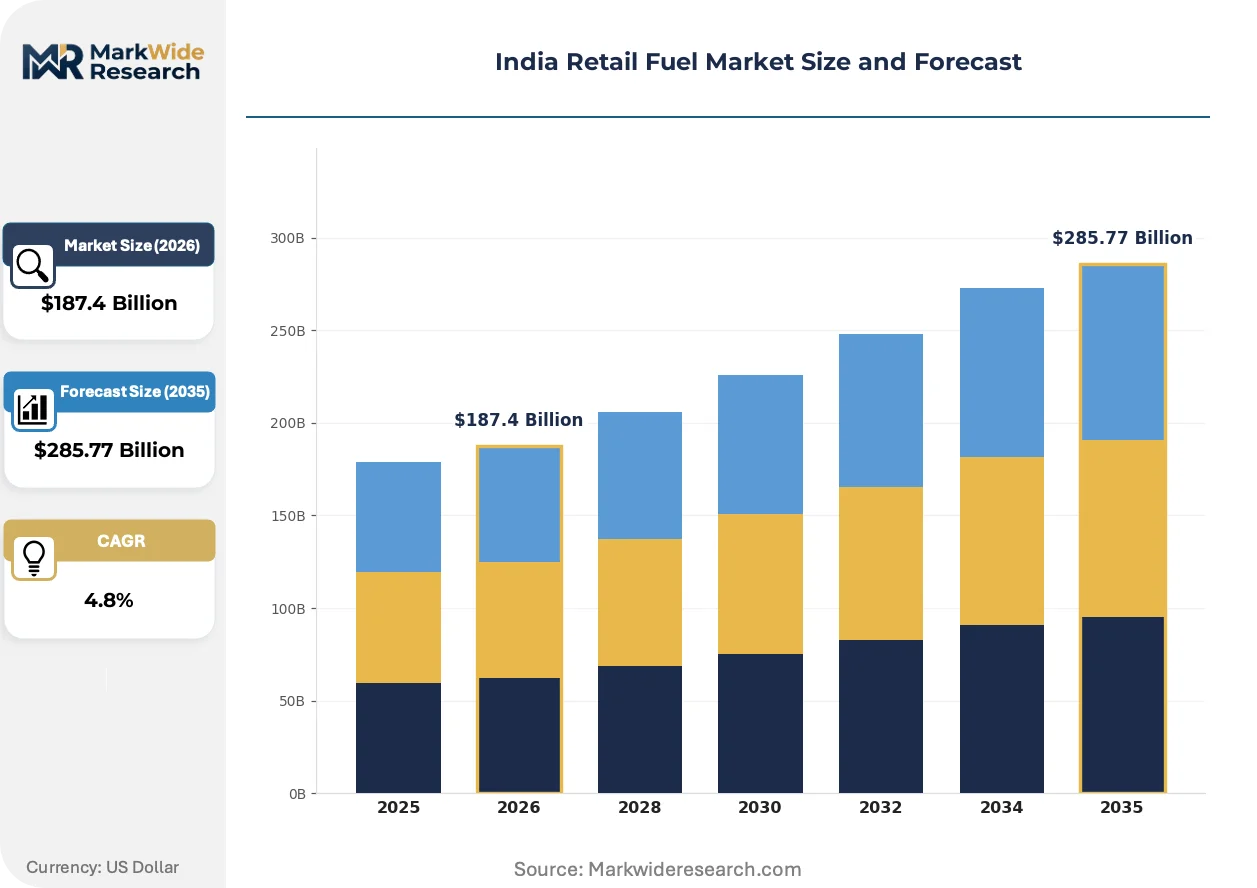
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Petrol, Diesel, LPG, CNG Customer Type: Individual Consumers, Fleet Operators, Commercial Users, Government Agencies Distribution Channel: Retail Outlets, Online Platforms, Mobile Stations, Bulk Supply Pricing Model: Fixed Pricing, Dynamic Pricing, Discounted Pricing, Subscription-Based |
| Companies Covered | Nayara Energy Limited, Shell PLC, Indian Oil Corporation Ltd, Jio-bp, TotalEnergies SA, Bharat Petroleum Corp Ltd, Reliance Industries Limited, Oil India Limited, Hindustan Petroleum Corporation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Retail Fuel Market Shifts & Advancements
Digital integration at the nozzle is compressing transaction friction and enabling real-time demand forecasting, while regulatory pressure on emissions intensifies product specification divergence across state boundaries.
Fast-charging infrastructure is overtaking conventional fuel dispensers in urban premium locations. Battery electric buses and fleet depots now anchor forecourt redesigns in Delhi and Bengaluru. This hardware shift is compressing petrol throughput per site and forcing retailers to reconceptualize revenue per customer visit.
BIS certification mandates for fuel quality at the nozzle are tightening testing protocols and documentation requirements. Refineries must maintain batch traceability from tank farm to retail outlet. Maharashtra and Gujarat outlets face the strictest enforcement, with quarterly sampling and penalty structures for sulfur or octane deviations.
Fleet procurement has moved toward annual volume contracts with price collars and guaranteed offtake minimums. Long-haul trucking cooperatives now negotiate directly with refinery-marketers, bypassing traditional dealer networks. This concentration is most visible along the Delhi-Mumbai Industrial Corridor, where dedicated bunkering agreements lock in multi-year supply relationships.
India Retail Fuel Market Segmentation
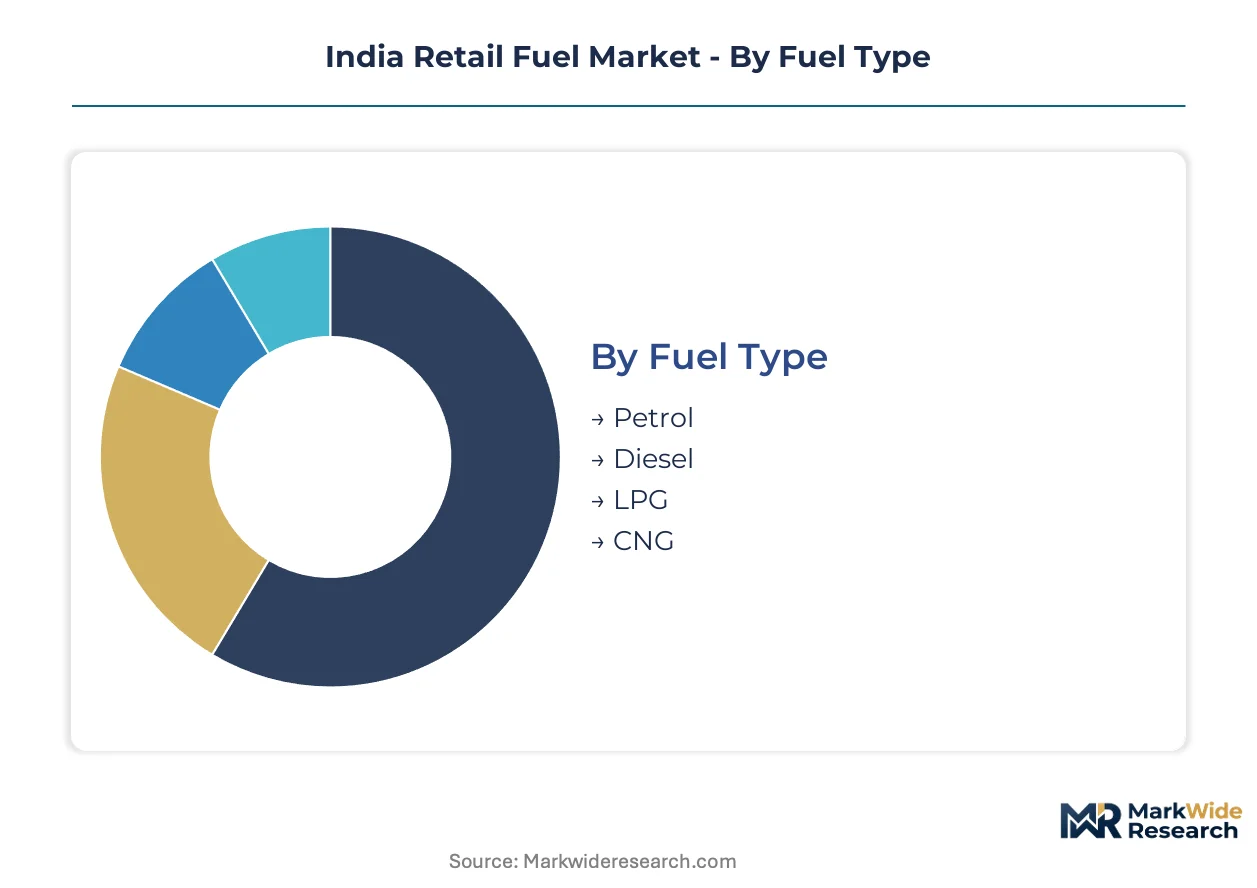
India's retail fuel market segments along fuel chemistry, procurement scale, and pricing mechanism. Each dimension shapes capital allocation decisions and margin architecture differently across the country's refining and distribution networks.
Fuel Type:
Diesel dominates volume throughput while petrol commands premium nozzle economics; the split between highway haulage demand and urban passenger mobility defines infrastructure investment priorities.
- Diesel:Graded by cetane number and sulfur content under BIS certification, with Bharat Stage VI mandating 10 ppm sulfur ceilings. Demand concentrates along the Delhi-Mumbai Industrial Corridor where long-haul trucking cooperatives negotiate annual volume contracts with price collars, compressing margins for standalone dealers while rewarding integrated bunkering networks with captive offtake.
- Petrol:Octane ratings span 87 to 99, with premium grades capturing higher per-liter margins at urban forecourts. Maharashtra and Gujarat outlets see the strictest BIS enforcement for octane deviations, with quarterly sampling protocols elevating compliance costs for smaller retailers.
- LPG:Cylindrical distribution through authorized dealers serves domestic cooking and small commercial applications; cylinder refill frequency tracks monsoon agricultural patterns and urban household density.
- CNG:Compressed natural gas dispensing expands fastest along urban bus and three-wheeler corridors where PNGRB-licensed city gas distribution networks provide piped feedstock.
Mature deployment sits with diesel and petrol. Newer deployment is concentrated in CNG along the Maharashtra-Gujarat-Tamil Nadu corridor where refinery infrastructure and urban vehicle density overlap.
Customer Type:
Procurement scale separates price-takers from price-makers; volume concentration rewrites the traditional dealer-retailer relationship.
- Fleet Operators:Long-haul trucking cooperatives and logistics companies now negotiate directly with refinery-marketers, bypassing dealer networks through dedicated bunkering agreements that lock in multi-year supply relationships with guaranteed offtake minimums.
- Individual Consumers:Fragmented demand across two-wheelers, passenger cars, and agricultural machinery produces the highest transaction frequency but lowest per-visit revenue; digital payment integration and loyalty-linked pricing targets this segment for cross-sell penetration.
- Commercial Users:Construction equipment, mining operations, and industrial generators require bulk diesel procurement with site-specific storage and dispensing infrastructure.
- Government Agencies:State transport undertakings and municipal bus fleets anchor CNG demand in Delhi and Bengaluru, driving forecourt redesigns around battery electric bus depot requirements.
Margin compression is deepest among individual consumers. Volume guarantees and captive demand cluster with fleet operators along highway logistics corridors.
Distribution Channel:
Physical infrastructure density versus digital reach creates divergent capital intensity models.
- Retail Outlets:Pipeline-fed outlet infrastructure anchors national network coverage; underground tank compatibility with ethanol blends above E20 requires site-specific engineering assessments that delay retrofit schedules.
- Bulk Supply:Direct refinery-to-fleet delivery eliminates forecourt overhead for high-volume purchasers with captive storage capacity.
- Online Platforms:Digital ordering with doorstep delivery targets urban last-mile segments where battery swapping networks are eroding traditional petrol demand.
- Mobile Stations:Deployable dispensing units serve construction sites, mining operations, and temporary logistics hubs without fixed infrastructure investment.
Fixed asset intensity peaks with retail outlets. Flexibility and speed of deployment concentrate in mobile stations serving project-based demand.
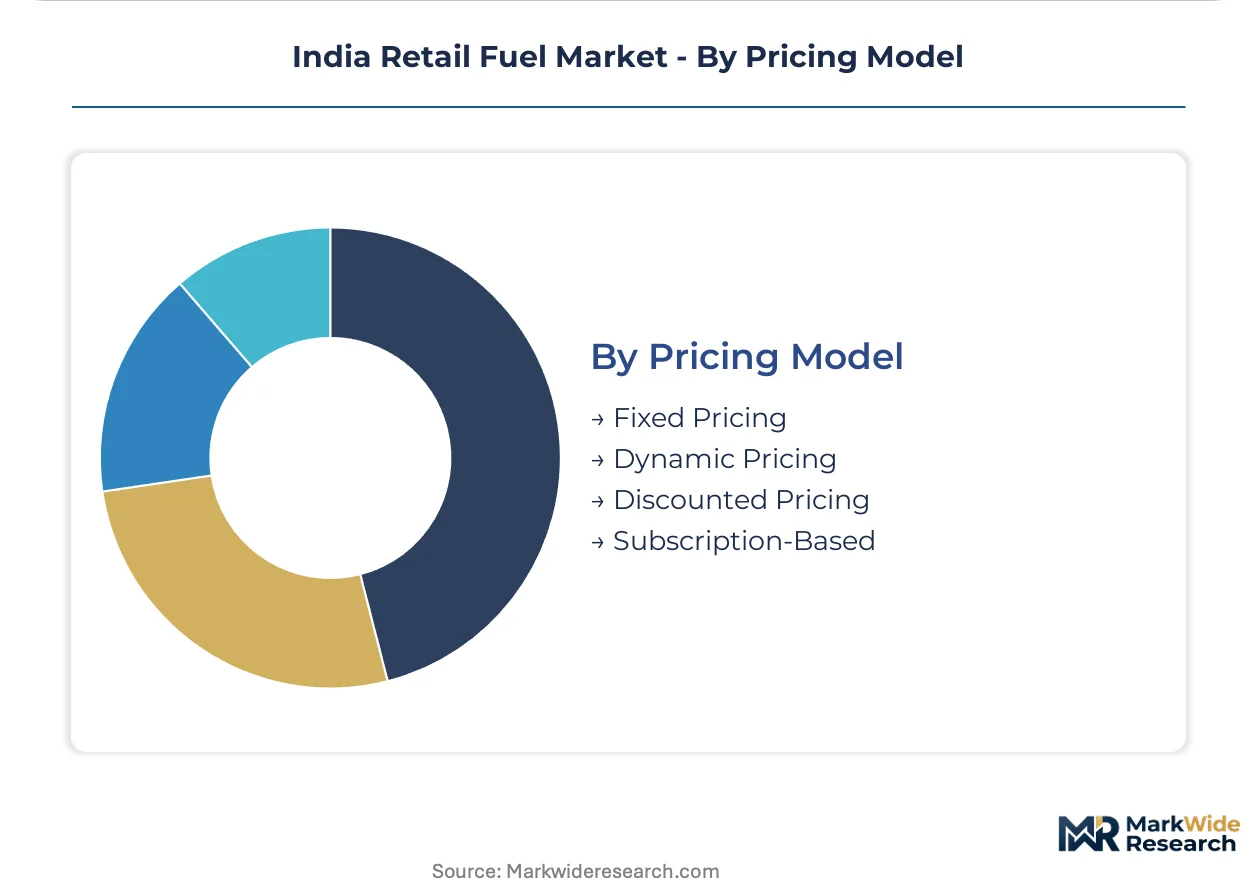
Pricing Model:
Transparency versus customization defines competitive positioning across customer relationships.
- Dynamic Pricing:Real-time adjustment linked to consumer data platforms enables margin management and demand forecasting at urban forecourts with digital payment integration.
- Fixed Pricing:Government-administered daily rates provide predictability for individual consumers and small dealers, though currency volatility in crude import costs compresses downstream margins.
- Discounted Pricing:Volume-linked reductions and loyalty program tiers target high-frequency purchasers in competitive urban catchments.
- Subscription-Based:Prepaid fuel packages with monthly caps appeal to gig economy delivery fleets with predictable route patterns.
Regulatory anchoring sits with fixed pricing. Experimentation and margin optimization are expanding most quickly through dynamic pricing at digitally integrated urban locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India refines more petroleum than it produces domestically, creating a coastal concentration of import terminals and processing capacity that shapes downstream retail geography. Consumption clusters along industrial corridors where manufacturing density intersects highway logistics networks.
Maharashtra
Mumbai-Pune industrial belt drives diesel demand from manufacturing clusters and port logistics. BIS certification enforcement is strictest here, with quarterly fuel quality sampling at retail outlets. Refinery infrastructure at Ratnagiri and pipeline-fed distribution anchor the state's bunkering dominance for long-haul trucking cooperatives.
Gujarat
Jamnagar refinery complex and Kandla port proximity create India's densest fuel logistics hub. The state's city gas distribution networks under PNGRB licensing extend CNG corridors along Ahmedabad-Surat industrial routes. Dahej and Hazira manufacturing zones concentrate bulk diesel procurement through direct refinery contracts.
Tamil Nadu
Chennai-Bengaluru industrial corridor and Ennore port traffic sustain high-throughput retail outlets. State transport undertakings anchor CNG demand through municipal bus fleet conversions. Coimbatore textile belt and Sriperumbudur automotive cluster generate captive commercial fuel requirements.
Delhi-NCR
Battery electric bus depot requirements and odd-even vehicle rationing policies compress petrol throughput at urban forecourts. Central Pollution Control Board enforcement of Bharat Stage VI emission standards is most visible here, with real-time air quality indexing linked to fuel quality inspections. Gurugram and Noida logistics hubs sustain fleet operator consolidation.
Karnataka
Bengaluru's technology corridor and last-mile delivery density accelerate EV penetration in two-wheeler segments. The state's ethanol procurement policies under central blending mandates redirect some retail infrastructure toward flex-fuel compatibility. Mangalore refinery feeds pipeline networks south toward Kerala border zones.
India Retail Fuel Market Competitive Landscape
The competitive structure tilts toward integrated refinery-marketers with captive pipeline networks and import terminal access. Standalone dealers face margin compression as fleet operators negotiate direct supply relationships. Three archetypes dominate: state-owned incumbents with national coverage, private refiners with coastal import advantages, and joint ventures combining retail technology with fuel supply. Competitive moves center on forecourt digitalization for payment integration and dual-energy infrastructure for EV-CNG compatibility.
Within the state-backed tier, Indian Oil Corporation Ltd anchors national network density through pipeline-fed outlet infrastructure. Nayara Energy Limited and Jio-bp occupy positions at the private and joint-venture ends respectively—Nayara leveraging west coast import terminal proximity, Jio-bp integrating digital payment platforms with loyalty-linked pricing at urban locations. These three exemplify the spectrum from volume-scale public sector coverage to technology-enabled retail differentiation.
| Leading Market Players |
|---|
| Nayara Energy Limited |
| Shell PLC |
| Indian Oil Corporation Ltd |
| Jio-bp |
| TotalEnergies SA |
| Bharat Petroleum Corp Ltd |
| Reliance Industries Limited |
| Oil India Limited |
| Hindustan Petroleum Corporation Limited |
| Others |
Supply & Pricing Matrix
Bharat Stage VI emission compliance gates both qualified supply and premium-tier pricing access, as BIS certification mandates for 10 ppm sulfur diesel and octane-verified petrol constrain which refineries can serve Maharashtra and Gujarat outlets while enabling certified marketers to capture margin premiums at urban forecourts.
Pricing Analysis
Throughput-linked annual volume contracts anchor value-based pricing for fleet operators along the Delhi-Mumbai Industrial Corridor, with long-haul trucking cooperatives negotiating price collars and guaranteed offtake minimums that compress margins for standalone dealers. Price differentiation rests on BIS certification tier and volume scale, with premium octane grades and bulk procurement tiers commanding favorable unit economics. Cost compression in the individual consumer segment intensifies as battery swapping networks erode petrol demand for urban last-mile delivery. Fleet operators exhibit lowest price sensitivity due to captive bunkering relationships, while gig economy two-wheeler riders face highest sensitivity amid subsidy-dependent EV alternatives.
Supply Chain Analysis
BIS certification and PNGRB city gas distribution licensing gate supply participation, restricting pipeline-fed outlet operation to integrated refinery-marketers with batch traceability systems from tank farm to retail nozzle. Feedstock draws from Middle Eastern and African crude suppliers, with Indian refiners sourcing over four-fifths of input barrels through long-haul maritime routes. Single-source vulnerability concentrates around Jamnagar and Ratnagiri refining complexes, where pipeline network disruptions would cascade to western state retail coverage. Distribution feeds from coastal import terminals through dedicated pipeline networks to inland depots, with final-mile delivery via tanker truck to retail outlets and direct refinery-to-fleet bulk supply for highway bunkering agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bharat Stage VI compliance operates as a cost-of-compliance moat, elevating working capital intensity for hydrotreater investments that smaller participants cannot absorb while rewarding integrated refinery-marketers with durable network access.
For Market Incumbents: Hedge against EV penetration by accelerating dual-energy forecourt retrofit schedules in Delhi-NCR and Bengaluru, where battery electric bus depot requirements are compressing petrol throughput. Secure captive demand through dedicated bunkering agreements with logistics cooperatives along the Delhi-Mumbai Industrial Corridor, locking in multi-year volume guarantees that insulate against margin erosion at standalone urban outlets. For New Entrants and Emerging Players: Begin with eastern and northeastern white-space territories—Bihar, Odisha, and Assam—where pipeline-fed infrastructure remains underdeveloped and first-mover network builders face limited incumbent density. Target city gas distribution corridors under fresh PNGRB licensing rounds, leveraging CNG dispenser economics along urban bus and three-wheeler routes as the most penetrable entry vector with regulatory tailwinds. For Investors and Strategic Acquirers: Fleet operator consolidation into direct refinery contracts is the leading indicator that integrated bunkering networks will command premium valuations over standalone retail portfolios. Position for five-to-ten year horizon viability by targeting acquisition candidates with pipeline-fed outlet density and active PNGRB city gas distribution licenses. Monitor state-level EV mandate acceleration as the critical inflection signal for conventional pump asset impairment risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Energy Forecourt Retrofit | BIS-certified outlets in Delhi-NCR capture EV-CNG compatibility premiums amid bus fleet electrification mandates. |
| Pipeline Network Expansion | Eastern state pipeline buildouts by Indian Oil Corporation lock in first-mover supply security for Bihar and Odisha. |
| Fleet Bunkering Integration | Direct refinery-to-cooperative contracts bypass dealer networks and anchor captive demand along logistics corridors. |
| Digital Payment-Loyalty Convergence | Jio-bp's real-time pricing platforms enable dynamic margin management at urban forecourts with high transaction frequency. |
| PLI-Aligned Biofuel Dispensing | Ethanol blend infrastructure above E20 captures production-linked incentive flows for flex-fuel compatibility investments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with Petroleum Federation of India throughput statistics, PNGRB licensing registers, and Central Pollution Control Board enforcement reports providing baseline volume and compliance verification. Primary interviews with refinery operations directors, fleet procurement managers at logistics cooperatives, and urban retail outlet dealers cross-checked secondary estimates against field-level margin and throughput dynamics. Bottom-up outlet count modeling and top-down refinery production allocation triangulated market sizing across fuel type and regional segments.
Data-stream reconciliation between refinery output disclosures, pipeline flow metering, and retail point-of-sale aggregation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include fuel chemistry tier, customer procurement scale, distribution channel format, and state-level regulatory cluster. CAGRs derived from historical throughput trajectories, refinery capacity expansion schedules, and EV penetration scenario overlays. City gas distribution licensing cadence and FAME India scheme disbursement velocity served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; diesel and petrol throughput carry tighter precision due to refinery reporting mandates, while CNG dispenser economics and EV charging substitution rates carry wider confidence intervals. Forecasts reflect assumptions regarding crude import cost trajectories, rupee volatility, and state-level EV mandate enforcement intensity. A model refresh is warranted upon material change in Bharat Stage VI compliance cost structures or PNGRB city gas distribution licensing velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Europe Bunker Fuel Market
Fuels
White Coal Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Pyrolysis Gas Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Solid Recovered Fuel Market
Fuels
City Gas Distribution Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
LNG Filling Station Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
North America Bunker Fuel Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
LPG Tanker Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
Fuel Analyzer Market