
 Aviation Fuel Market | 2026-2036
Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Fuel Market Analysis
Project finance structures for sustainable aviation fuel biorefineries are reshaping competitive entry in the aviation fuel sector, lowering the capital barrier for new renewable producers. Exxon Mobil Corporation leverages its integrated refining network to maintain conventional jet fuel scale while testing coprocessing pathways. Neste anchors European renewable supply through its Singapore and Rotterdam facilities, converting waste oils into certified drop-in product. BP plc competes via its partnership model with airlines, offering book-and-claim certificates that separate physical fuel from emissions credits.
Aviation fuel comprises refined petroleum products meeting strict energy density, freeze point, and flash point specifications for turbine and piston engines, with Jet A-1 dominating commercial operations due to its minus 47 degrees Celsius freeze point requirement. Jet A and Jet A-1 represent the mature volume base where margin pools have compressed, while sustainable variants certified under ASTM D7566 represent the fastest-growing certification tier as airlines seek scope 3 reductions. Military Operations demand concentrates in DEF STAN 91-91 certified product with longer procurement cycles and strategic stockpile obligations that buffer price volatility.
The US EPA administers renewable fuel standard obligations that create compliance value for SAF producers, while the EU Green Deal's ReFuelEU Aviation regulation mandates escalating blend percentages at EU airports. ASTM D1655 and DEF STAN 91-91 certification frameworks govern product interchangeability, with JIG 1 standards controlling into-plane handling quality. Stakeholders must monitor whether feedstock availability for hydroprocessed esters and fatty acids can scale ahead of airline offtake commitments without displacing food crop production.
Market Dynamics
The ReFuelEU Aviation mandate is compressing conventional fuel margins while redirecting capital toward hydroprocessed esters and fatty acids infrastructure, forcing incumbent refiners to choose between retrofitting existing assets or ceding renewable volume to specialized biorefiners.
Growth Catalysts
- EU Green Deal blending mandates:Escalating SAF percentage requirements at EU airports are pulling forward biorefinery construction timelines and locking in offtake contracts before facilities achieve mechanical completion.
- ASTM D7566 certification expansion:Wider approval of synthetic paraffinic kerosene pathways is enabling alcohol-to-jet and Fischer-Tropsch processes to compete with HEFA for airline procurement budgets.
- United States demand concentration:Major carriers have established long-term purchase commitments with domestic biorefineries, creating anchor demand that de-risks project finance for new renewable producers.
Market Restraints
- Feedstock cost volatility:Waste oil and animal fat prices fluctuate with biodiesel competition and rendering industry output, compressing HEFA margins when virgin vegetable oil markets spike.
- Biorefinery supply concentration:Neste's Singapore and Rotterdam facilities currently dominate certified renewable jet fuel volume, creating single-source risk for European airlines seeking scope 3 reductions.
- Jet A-1 infrastructure lock-in:Existing pipeline networks, storage terminals, and into-plane equipment at major airports are optimized for conventional specifications, slowing SAF physical blending rollout.
Strategic Opportunities
- Power-to-liquid pathway development:Electrofuel production using renewable hydrogen and captured CO2 offers a feedstock-agnostic route that avoids agricultural land use constraints entirely.
- Book-and-claim certificate markets:Physical fuel and emissions credit separation enables airlines without airport SAF access to meet voluntary targets through tradable certificate purchases.
- Coprocessing retrofit economics:Conventional refiners can blend renewable feedstocks into existing fluid catalytic crackers and hydrotreaters with minimal capital outlay versus greenfield biorefinery construction.
Industry Challenges
- ASTM D7566 batch certification timelines:Each new production pathway requires extensive engine testing and property validation, stretching time-to-market for novel conversion technologies beyond typical project finance patience.
- Scope 3 accounting complexity:Airlines struggle to verify lifecycle emissions reductions across fragmented supply chains where feedstock origin, processing energy source, and transport mode all affect final carbon intensity scores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Fuel Market |
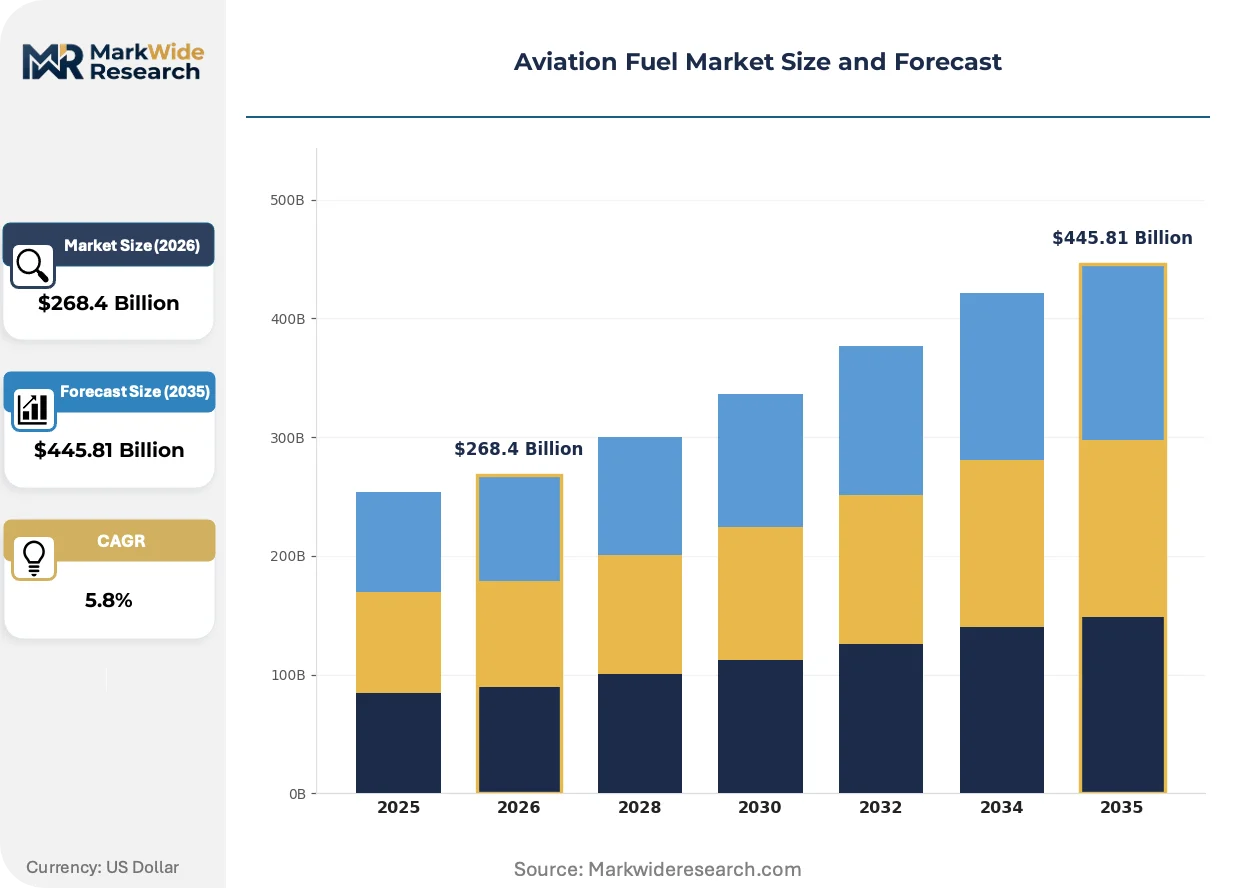
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $445.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, Avgas Distribution Channel: Direct, Retail, Online, Third-Party End User: Commercial Airlines, Private Jets, Cargo Services, Military Operations Certification: ASTM D1655, DEF STAN 91-91, JIG 1, Others |
| Companies Covered | Exxon Mobil Corporation, Chevron Corporation, BP plc, Shell, TotalEnergies, Valero Energy Corporation, Phillips 66, Marathon Petroleum Corporation, Neste, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Fuel Market Emerging Trajectories
Conversion technology diversification is fragmenting the renewable supply base as airlines seek feedstock flexibility beyond waste oils, while digital tracking systems emerge to verify chain-of-custody claims across complex supply networks.
Power-to-liquid synthesis is hybridizing renewable hydrogen production with direct air capture to create fully synthetic paraffinic kerosene without biological feedstock constraints. European carriers including Lufthansa and KLM have signed offtake agreements with pilot plants in Germany and the Netherlands. This technology is hybridizing the competitive landscape by enabling oil majors without agricultural supply chains to enter renewable aviation fuel production.
ReFuelEU Aviation's escalating blend mandates are forcing fuel suppliers to secure certified product years ahead of production capacity coming online. The regulation creates compliance liability for fuel suppliers who fail to meet annual percentage thresholds at EU airports. Network carriers with hub operations in Frankfurt, Amsterdam, and Paris are responding by pre-purchasing SAF volumes from multiple biorefineries to diversify supply risk.
Corporate travel procurement departments are embedding carbon intensity clauses into negotiated airline contracts, redirecting volume toward carriers with documented SAF consumption. Travel management companies are unbundling traditional commission structures to transparently price emissions separately from seat cost. This behavioral shift is most visible in transatlantic business travel corridors where Fortune 500 sustainability targets pressure travel policy compliance.
Aviation Fuel Market Segmentation
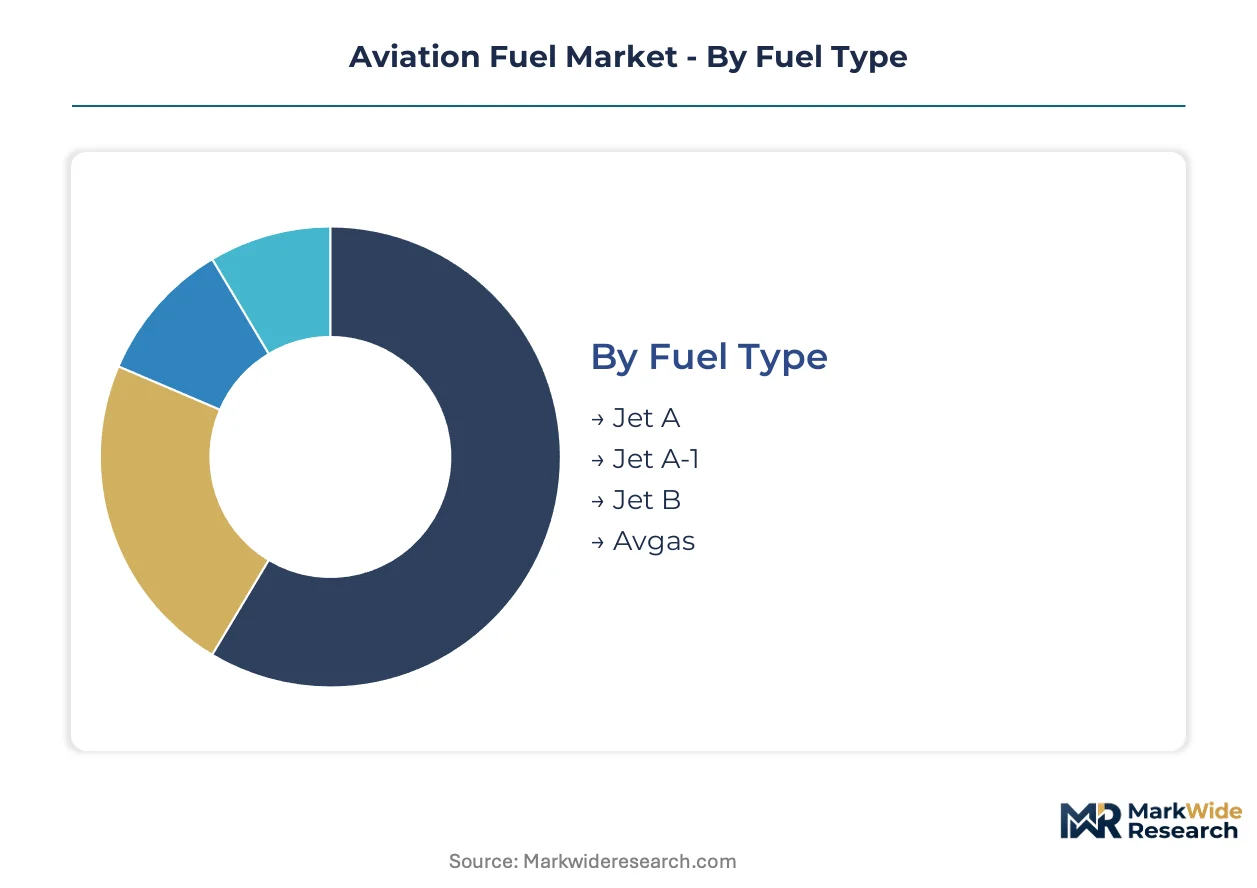
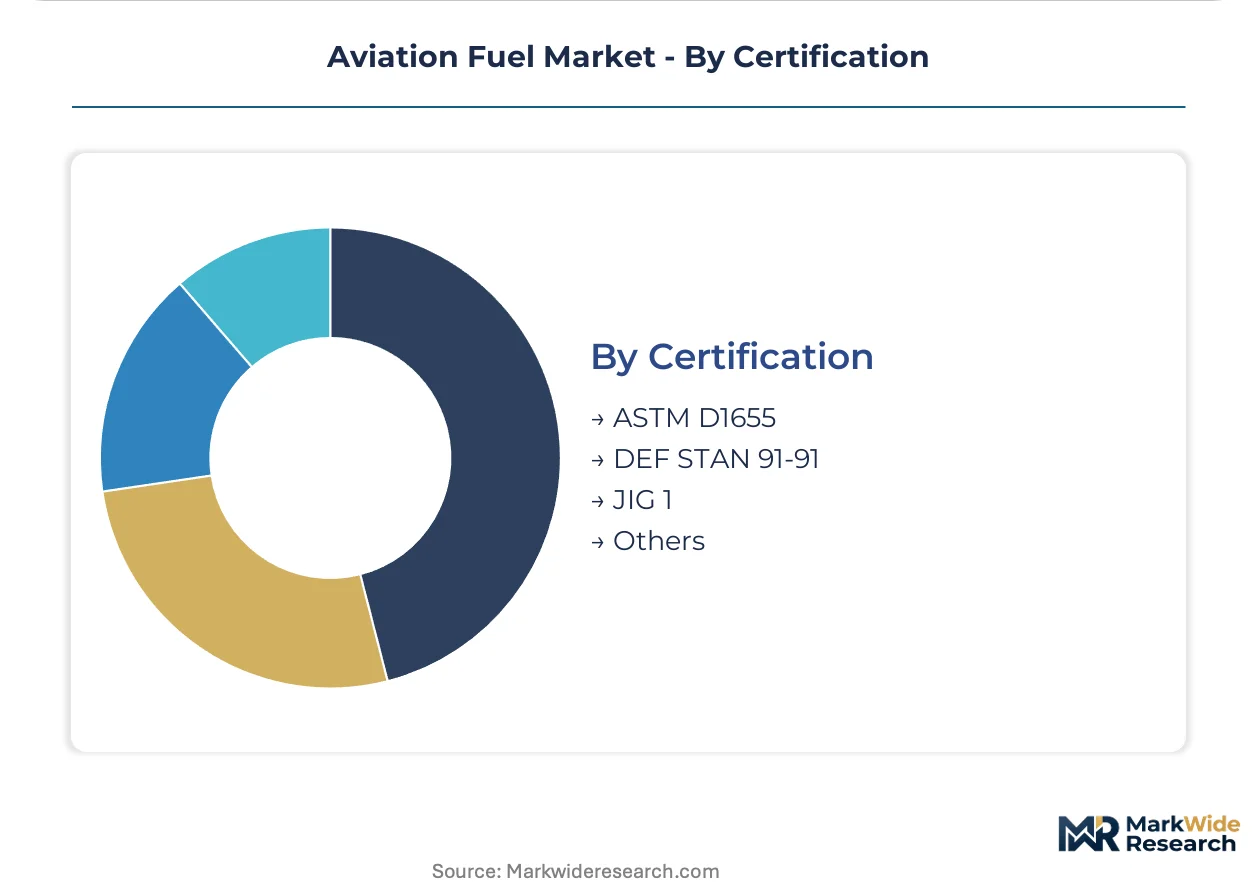
Fuel type determines infrastructure compatibility and operational envelope, while certification tiers separate conventional from sustainable supply. Distribution channel selection reflects volume scale and security requirements. End user segmentation concentrates procurement power among network carriers with long-term offtake strategies.
Fuel Type:
Energy density and freeze point specifications segment the market into turbine and piston engine categories, with military and polar routes demanding specialized performance envelopes.
- Jet A-1:Refined kerosene meeting minus 47 degrees Celsius freeze point requirements for commercial turbine operations. European carriers at Amsterdam and Frankfurt hubs concentrate procurement here as ReFuelEU Aviation mandates tighten blending thresholds.
- Jet A:Minus 40 degrees Celsius freeze point specification dominates US domestic operations where pipeline distribution from Gulf Coast refineries minimizes cold-weather exposure. ASTM D1655 certification governs interchangeability with Jet A-1 in most commercial applications.
- Jet B:Wide-cut naphtha-kerosene blend serving military and Arctic operations requiring minus 50 degrees Celsius performance.
- Avgas:High-octane gasoline for piston engines in general aviation and training fleets.
Jet A-1 commands the established base. The steepest expansion runs through Jet A as US carriers deepen domestic biorefinery commitments.
Distribution Channel:
Volume scale and supply security requirements fragment procurement pathways, with direct contracts capturing scheduled airline demand and spot markets serving irregular operators.
- Direct:Long-term supply agreements between refiners and major carriers, typically spanning five to ten years with indexed pricing. United States network carriers leverage direct channels to secure dedicated SAF volumes from domestic biorefineries before mechanical completion.
- Third-Party:Independent fuel suppliers managing into-plane logistics at airports without refiner-owned infrastructure. Third-party distributors at London Heathrow and Paris Charles de Gaulle aggregate SAF volumes from multiple producers to meet airline compliance pooling.
- Retail:Spot purchases for general aviation and fractional ownership fleets.
- Online:Digital procurement platforms emerging for carbon credit verification and book-and-claim certificate trading.
Direct channels anchor volume certainty. Third-party aggregation is gaining share fastest as SAF supply fragments across specialized biorefiners.
End User:
Operational scale and emissions reporting obligations concentrate sustainable fuel demand among scheduled carriers with scope 3 disclosure requirements.
- Commercial Airlines:Scheduled passenger operations consuming over three-quarters of global jet fuel volume. US majors including Delta and United have established multi-year SAF purchase commitments with domestic producers, creating anchor demand that de-risks project finance.
- Cargo Services:Integrated express carriers and dedicated freighter operators with hub-and-spoke networks. FedEx and UPS procurement teams embed carbon intensity clauses into fuel contracts, redirecting volume toward suppliers with certified renewable blends.
- Military Operations:Defense procurement with DEF STAN 91-91 certification requirements and strategic stockpile obligations.
- Private Jets:Fractional ownership and charter fleets with fragmented demand and limited SAF access at secondary airports.
Commercial airlines dominate volume absorption. Cargo services are expanding most quickly as e-commerce growth intensifies freighter utilization.
Certification:
Product interchangeability and lifecycle emissions verification segment supply into specification tiers with distinct compliance values.
- ASTM D1655:Conventional petroleum-derived jet fuel specification governing US commercial operations. The EPA administers renewable fuel standard obligations that create compliance value for SAF producers meeting ASTM D7566 drop-in requirements.
- ASTM D7566:Synthetic paraffinic kerosene certification for sustainable aviation fuel pathways including HEFA, alcohol-to-jet, and Fischer-Tropsch processes. ASTM D7566 expansion to new conversion technologies is accelerating airline procurement diversification.
- DEF STAN 91-91:UK military and allied defense procurement standard with longer qualification timelines.
- JIG 1:Into-plane handling and quality control standard for airport fueling operations.
ASTM D1655 retains the volume base. ASTM D7566 is climbing the fastest as ReFuelEU Aviation mandates escalate blend percentages at EU airports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across major aviation fuel markets. The United States maintains structural surplus through Gulf Coast refining capacity serving Atlantic and Pacific basin demand. European Union markets face widening import dependency as ReFuelEU Aviation mandates accelerate domestic refinery conversion or retirement.
United States
Gulf Coast refineries along the Houston Ship Channel and Port Arthur corridor process domestic crude into Jet A for domestic trunk routes and export markets. The EPA administers renewable fuel standard obligations that create compliance value for sustainable aviation fuel producers. Atlanta and Chicago O'Hare anchor concentrated airline procurement power, with major carriers securing dedicated SAF volumes from emerging biorefineries in the Midwest and Southeast.
Germany
Frankfurt and Munich hubs concentrate Lufthansa Group demand for Jet A-1 compliant with ReFuelEU Aviation escalating blend mandates. The EU Green Deal regulation creates compliance liability for fuel suppliers failing to meet annual percentage thresholds at German airports. Hamburg and the Rhineland industrial corridor host pilot power-to-liquid facilities producing synthetic paraffinic kerosene from renewable hydrogen.
Singapore
Changi Airport anchors Asia-Pacific jet fuel trading and physical blending operations serving connecting traffic between Europe and Southeast Asia. The Maritime and Port Authority coordinates bunker fuel standards that increasingly cross-reference aviation fuel quality protocols. Jurong Island refining complex processes regional crude streams while Neste's neighboring facility supplies certified renewable volumes to Singapore-based carriers.
Netherlands
Amsterdam Schiphol ranks among Europe's highest-volume jet fuel consumption points, with KLM and transiting network carriers driving procurement scale. ReFuelEU Aviation mandates apply directly at Dutch airports, forcing fuel suppliers to secure certified SAF volumes years ahead of production capacity completion. Rotterdam port infrastructure enables barge and pipeline distribution of both conventional and renewable product across the Rhine corridor into Germany.
United Kingdom
London Heathrow concentrates premium-route demand from British Airways and Virgin Atlantic, with third-party fuel suppliers aggregating SAF volumes from multiple biorefineries to meet airline compliance pooling. DEF STAN 91-91 certification governs military procurement with longer qualification timelines distinct from commercial ASTM frameworks. Scottish refinery capacity at Grangemouth supplies domestic routes while facing conversion pressure toward renewable production.
Aviation Fuel Market Vendor Landscape
On the supply side, the industry is consolidating around integrated oil majors with refining scale and emerging biorefinery specialists with pathway certification advantages. Incumbent petroleum refiners face strategic choice between retrofitting existing hydrotreaters for coprocessing or ceding renewable volume to purpose-built facilities. Three archetypes dominate: integrated majors leveraging distribution infrastructure, standalone renewable specialists securing airline offtake, and project-financed biorefineries scaling novel conversion technologies. Competitive intensity centers on securing long-term purchase commitments ahead of mechanical completion and achieving ASTM D7566 pathway approval.
Within the integrated major tier, Exxon Mobil Corporation and BP plc occupy positions defined by conventional refining scale and emerging renewable testing. Neste exemplifies the standalone renewable specialist archetype, anchoring European supply through certified drop-in production. These three entities represent distinct strategic postures: petroleum-derived volume defense, partnership-based certificate markets, and dedicated biorefinery expansion.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Chevron Corporation |
| BP plc |
| Shell |
| TotalEnergies |
| Valero Energy Corporation |
| Phillips 66 |
| Marathon Petroleum Corporation |
| Neste |
| Others |
Supply Flow & Price Mechanics
Gulf Coast refinery concentration around the Houston Ship Channel and Port Arthur corridor anchors margin capture downstream, with Jet A pricing power flowing to integrated majors who control pipeline distribution into Atlanta and Chicago O'Hare hubs. ReFuelEU Aviation compliance costs are reshaping where value accrues as European fuel suppliers absorb SAF blend premiums.
Pricing Analysis
Network carrier procurement teams anchor contract-based long-term offtake structures spanning five to ten years with indexed pricing. Price differentiation rests on ASTM D7566 certification tier and volume scale commitments, with SAF-certified product commanding premiums over conventional Jet A-1. Pricing pressure stems from feedstock cost volatility in waste oil and animal fat markets squeezing HEFA margins. Cargo services exhibit highest price sensitivity due to thin operating margins, while corporate travel procurement shows lowest sensitivity as sustainability clauses override cost optimization.
Supply Chain Analysis
Neste's Singapore and Rotterdam facilities hold dominant certified renewable capacity, with Exxon Mobil's Gulf Coast refineries and BP's European distribution network anchoring conventional supply. Geographic concentration centers on the United States, Singapore, and the Netherlands for refining and blending operations. Raw material dependencies include crude oil streams, waste oils, animal fats, and emerging renewable hydrogen feedstocks. Single-source vulnerability concentrates in HEFA pathway supply as Neste's facilities currently dominate certified renewable volume. Distribution runs through into-plane operators at major hubs, with third-party aggregators gaining share at London Heathrow and Paris Charles de Gaulle.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAF offtake agreement velocity signals early-cycle expansion as ReFuelEU Aviation mandates force pre-production procurement years ahead of biorefinery completion.
For Market Incumbents: Pre-empt renewable volume loss by retrofitting existing hydrotreaters for coprocessing rather than ceding market share to purpose-built biorefineries. Lock in long-term waste oil supply contracts before specialized renewable producers capture feedstock access. Defend against ASTM D7566 pathway specialists by accelerating certification investment in novel conversion technologies including alcohol-to-jet and Fischer-Tropsch processes. For New Entrants and Emerging Players: Mid-size European airports without major hub carrier concentration represent the most penetrable entry point for third-party SAF aggregation services. Power-to-liquid pilot scale partnerships with Lufthansa and KLM offer technology validation pathways before commercial scale commitment. Book-and-claim certificate platform development enables market entry without physical infrastructure investment, capturing value from airlines lacking airport SAF access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with project-financed biorefineries holding airline offtake but pre-revenue operations. Five-to-ten year viability hinges on ASTM D7566 pathway approval timelines and ReFuelEU Aviation compliance enforcement consistency. Monitor feedstock cost spreads between waste oils and virgin vegetable oils as margin sustainability indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Coprocessing Retrofit Deployment | Conventional refiners blend renewable feedstocks into existing hydrotreaters with minimal capital outlay versus greenfield construction. |
| Long-term SAF Offtake Agreement | United Airlines and Delta secure dedicated volumes from domestic biorefineries before mechanical completion de-risking project finance. |
| Power-to-Liquid Pilot Scale-up | Lufthansa and KLM partnerships with German and Dutch electrofuel facilities validate synthetic paraffinic kerosene pathways. |
| Book-and-Claim Platform Launch | BP's certificate markets separate physical fuel from emissions credits enabling voluntary target compliance without infrastructure. |
| Feedstock Supply Integration | Backward integration into waste oil collection and rendering operations secures HEFA margin against biodiesel competition. |
Methodological Framework
The analysis maps conventional refining, HEFA production, alcohol-to-jet pathways, and power-to-liquid synthesis, each validated through fuel procurement executives at network carriers, biorefinery project developers, and into-plane operators. Primary interviews with EPA compliance officers, EU Green Deal implementation leads, and ASTM certification specialists combined with secondary validation from EIA data, IEA aviation reports, FERC filings, and customs trade records. Bottom-up biorefinery capacity buildouts triangulate against top-down airline offtake commitment aggregation.
Assumptions held fixed include ReFuelEU Aviation mandate enforcement timelines and ASTM D7566 pathway approval schedules, while feedstock cost trajectories and renewable hydrogen production scale varied across sensitivity scenarios. Segmentation dimensions modeled include fuel type, certification tier, distribution channel, and end-user operational scale. CAGRs derive from production capacity commissioning schedules against airline procurement volume commitments. Industry-specific inputs include HEFA yield rates, coprocessing blend limits, and power-to-liquid energy efficiency benchmarks.
Macroeconomic conditions sit as an overlay; deviation in crude oil price bands, carbon credit market liquidity, or sustainable aviation fuel tax credit durability would shift the trajectory. Forecasts reflect assumptions regarding biorefinery construction timelines and airline fleet renewal rates. Quarterly review of ASTM D7566 batch certification progress and ReFuelEU Aviation compliance pooling arrangements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Fuel Conditioning System Market
Fuels
Refuse Derived Fuel Market
Fuels
High-Temperature Industrial Burner Market
Fuels
India Petrol Station Market
Fuels
India Bunker Fuel Market
Fuels
Anthracite Coal Mining Market
Fuels
Gas Feed System Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Hydrogen Fuel Tanks Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Canada Bunker Fuel Market
Fuels
Underground Coal Gasification Market
Fuels
Global Charcoal Market
Fuels
Caribbean Islands Bunker Fuel Market
Fuels
Commercial Aircraft Aviation Fuel Market