
 Coal Briquettes Market | 2026-2036
Coal Briquettes Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Briquettes Market Outlook
Premium-grade smokeless briquettes is bifurcating the competitive landscape as emission standards tighten across industrial buyers. Coal India Limited leverages its captive mining infrastructure to anchor domestic supply chains across power and heating segments. Peabody Energy Corporation competes through specialized metallurgical briquette exports to Asian steelmakers. China Shenhua Energy Company Limited controls integrated coal-to-briquette conversion capacity, sustaining cost advantages in bulk industrial contracts.
Coal briquettes are compressed blocks of pulverized coal, coal dust, or coal fines bound with starch, molasses, or pitch, typically engineered to 15-25% ash content and calorific values exceeding 4,000 kcal/kg for industrial grades. Their primary purpose is to convert coal waste streams into uniform, transportable fuel units that improve combustion efficiency and reduce particulate emissions relative to raw coal lump. Smokeless coal briquettes command widening margin pools as municipal air quality ordinances restrict residential and commercial burning of high-sulfur alternatives. Industrial heating applications dominate volume absorption, while BBQ-grade charcoal briquettes occupy specialty retail channels with distinct seasonal demand curves. Round briquettes sustain leadership in automatic stoker systems, though hexagonal geometries are gaining traction in artisanal export markets for extended burn duration.
EPA emission thresholds under the Clean Air Act shape product certification requirements for US-bound industrial briquettes, while China's MEE enforces dual carbon goals that constrain new coal conversion permits and favor lower-carbon binder technologies. India's CEA mandates beneficiated coal use in designated thermal plants, directly stimulating demand for washed-coal briquettes with reduced ash burden. Stakeholders must monitor evolving national carbon accounting rules that could reclassify briquette-derived emissions and redirect procurement toward biomass-coal blends or fully synthetic alternatives.
Market Dynamics
China's dual carbon goals under MEE supervision are compressing new coal conversion permits while simultaneously mandating lower-carbon binder technologies, forcing briquette manufacturers to reengineer production lines or exit entirely.
Growth Catalysts
- Industrial Beneficiation Mandates:India's CEA requires washed-coal briquettes in designated thermal plants, directly stimulating demand for reduced-ash formulations across power generation infrastructure.
- Steel Sector Densification:Metallurgical briquettes with calorific values exceeding 4,500 kcal/kg are displacing raw coke in Asian blast furnace operations seeking combustion efficiency gains.
- Residential Smokeless Transition:China's GB standards on particulate emissions are accelerating municipal bans on high-sulfur lump coal, redirecting household heating budgets toward certified smokeless alternatives.
Market Restraints
- Feedstock Cost Volatility:Thermal coal fines and coal dust prices fluctuate with mining output cycles, compressing margin predictability for independent briquette processors without captive supply.
- Permit Constriction:China's MEE has frozen new coal-to-briquette conversion licenses in multiple provinces, capping domestic capacity expansion regardless of underlying demand.
- Biomass Substitution Pressure:Agricultural residue pellets and torrefied biomass briquettes are capturing carbon-conscious procurement budgets in European industrial heating contracts.
Strategic Opportunities
- Rural Electrification Gaps:India's unelectrified districts in Bihar and Uttar Pradesh sustain residential briquette demand for cooking and heating where LPG distribution remains sparse.
- Carbon Accounting Reclassification:Evolving national greenhouse gas inventory rules may credit briquette-derived emissions reductions against coal baseline calculations, favoring early adopters of certified low-carbon binders.
- Artisanal Export Channels:Hexagonal briquette geometries with extended burn duration are penetrating specialty BBQ retail in Japan and South Korea through direct-to-hotel supply arrangements.
Industry Challenges
- Binder Chemistry Expertise Scarcity:Formulation chemists capable of optimizing starch-molasses-pitch blends for specific ash fusion temperatures remain concentrated at legacy state-owned coal research institutes.
- Emissions Certification Timeline Compression:EPA Clean Air Act thresholds for US-bound industrial briquettes require third-party testing cycles that lag behind contract bidding windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Briquettes Market |
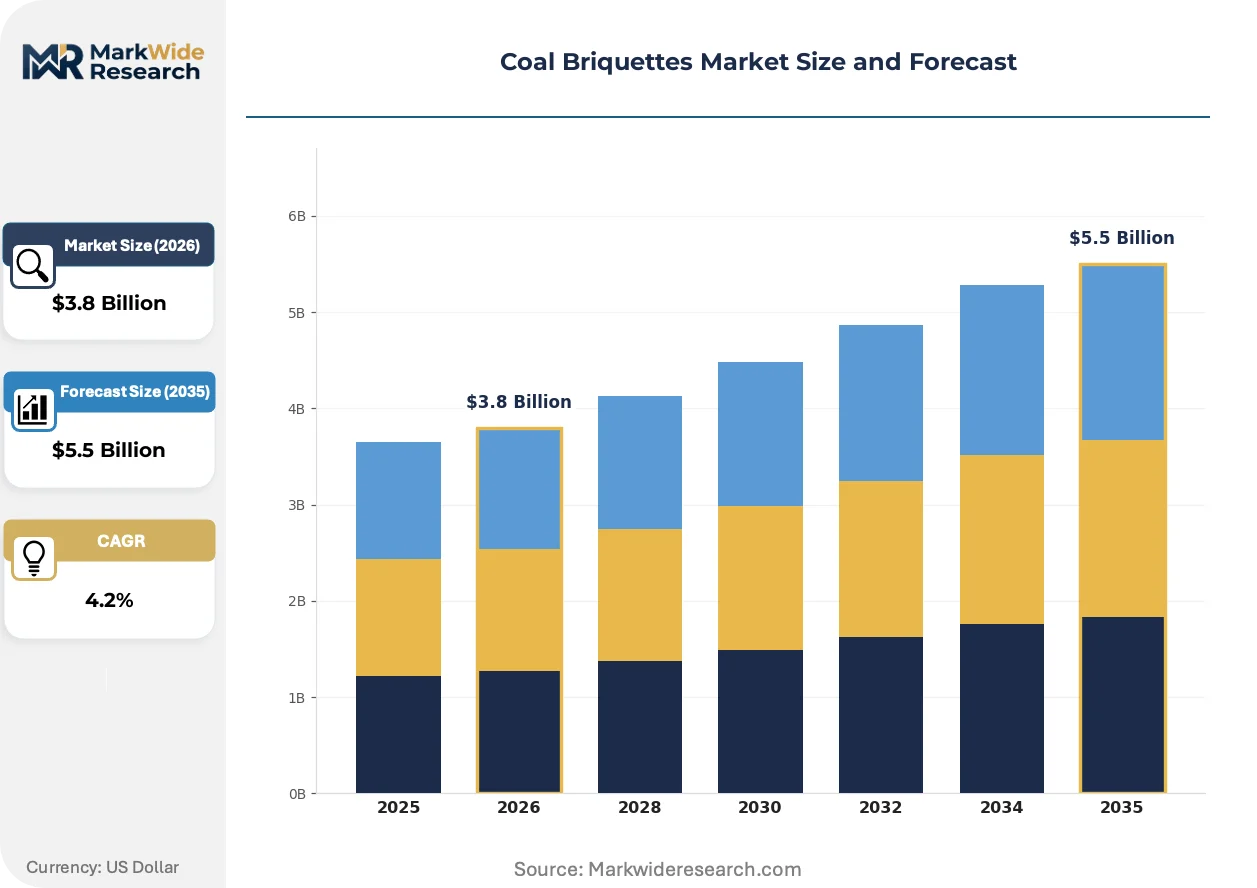
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Coal, Black Coal, Smokeless Coal, Charcoal End Use Industry: Power Generation, Industrial Heating, Residential Heating, BBQ Form Factor: Round Briquettes, Square Briquettes, Pillow Briquettes, Hexagonal Briquettes Distribution Channel: Direct Sales, Retail, Wholesale, E-commerce |
| Companies Covered | Coal India Limited, Peabody Energy Corporation, Arch Resources, Inc., Adaro Energy Tbk, Shaanxi Coal and Chemical Industry Group, Yanzhou Coal Mining Company Limited, China Shenhua Energy Company Limited, BHP Group, ITO Global Trading Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Briquettes Market Strategic Shifts
Coal briquette manufacturing is undergoing simultaneous pressure from binder chemistry advances and regulatory carbon accounting, with production technology and procurement patterns diverging across industrial and residential segments.
Cold briquetting using organic binders like modified starch and lignosulfonate is displacing traditional hot-pressing with pitch binders in European and North American facilities. Steelmakers in Germany and Poland are adopting these formulations to meet EU Green Deal procurement criteria. The shift is compressing demand for petroleum-derived binders while elevating agricultural waste valorization partnerships.
REACH regulations in Europe are tightening registration requirements for coal-based solid fuels, forcing exporters to document full substance inventories and safe-use instructions. Industrial buyers in Belgium and the Netherlands are now rejecting shipments lacking SCIP database entries. The compliance burden is filtering smaller traders from premium industrial supply chains while consolidating volume with integrated producers possessing in-house regulatory affairs capacity.
Long-term offtake agreements with fixed calorific value specifications are replacing spot-market purchasing across Asian cement and steel plants. Buyers in Vietnam and Indonesia are locking in eighteen-month contracts with penalty clauses for ash content deviation. The contractual shift is visible most acutely in bulk industrial segments where fuel quality consistency directly affects kiln operational stability.
Coal Briquettes Market Segmentation
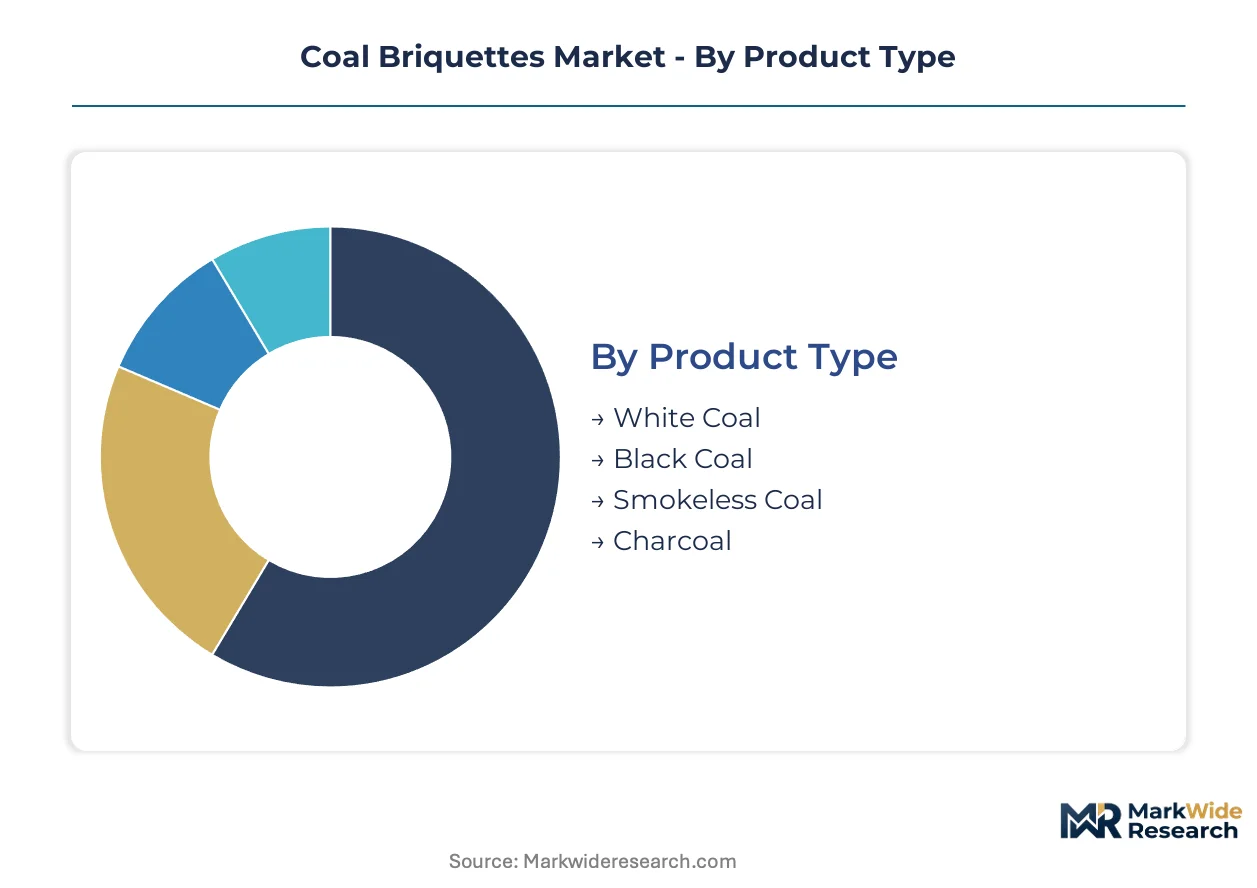
Coal briquette manufacturers engineer product specifications around combustion efficiency targets and emissions profiles that vary sharply across industrial boilers, residential stoves, and specialty retail channels. Each segment carries distinct binder chemistry requirements and regulatory certification burdens that reshape procurement patterns and margin structures.
Product Type:
Biomass-coal blends and synthetic solid fuels are exerting substitution pressure most acutely on high-sulfur black coal formulations, while smokeless variants capture defensive demand from tightening municipal air quality ordinances.
- Smokeless Coal:Formulated with low-volatile bituminous fines and modified starch binders to achieve particulate emissions below GB standard thresholds. Municipal heating contracts in Chinese provinces with active MEE enforcement are concentrating procurement here, though binder cost premiums compress margins versus conventional grades.
- Black Coal:Standard bituminous briquettes bound with molasses or pitch, typically 15-25% ash content and 4,000-4,500 kcal/kg calorific value. India's CEA-mandated beneficiation requirements for designated thermal plants are redirecting volume toward washed-coal variants with reduced ash burden.
- White Coal:Agglomerated biomass-coal blends with elevated fixed carbon content, positioned as transitional fuel for EU Green Deal procurement criteria.
- Charcoal:Carbonized wood-coal composites for specialty BBQ retail, commanding seasonal demand curves in Japan and South Korea.
Black coal retains volume leadership across bulk industrial contracts; smokeless coal holds the steepest expansion curve as emission standards tighten.
End Use Industry:
Cost tier stratification separates commodity fuel buyers seeking calorific consistency from premium segments paying for certification and burn-duration specifications.
- Industrial Heating:Metallurgical and cement kiln applications demanding 4,500+ kcal/kg density and sub-12% ash content for operational stability. Vietnamese and Indonesian steelmakers are locking in eighteen-month offtake agreements with penalty clauses for specification deviation.
- Power Generation:Washed-coal briquettes feeding CEA-designated thermal plants in India, where beneficiation mandates stimulate demand for reduced-ash formulations.
- Residential Heating:Municipal bans on high-sulfur lump coal in Chinese cities redirect household budgets toward certified smokeless alternatives.
- BBQ:Specialty retail channel with distinct seasonal patterns, hexagonal geometries penetrating direct-to-hotel supply in East Asian markets.
Industrial heating commands the dominant revenue tier; BBQ applications are climbing the fastest on per-unit margin expansion.
Form Factor:
Geographic clustering of stoker technology standards shapes form factor adoption, with automatic feed systems favoring uniform geometries and artisanal markets rewarding extended burn duration.
- Round Briquettes:Engineered for automatic stoker systems in European and North American industrial boilers, uniform dimensions ensuring consistent feed rates. German and Polish steelmakers adopting cold-briquetting formulations specify round geometries for compatibility with existing handling infrastructure.
- Hexagonal Briquettes:Extended surface area-to-volume ratios enable longer burn duration, penetrating specialty BBQ retail in Japan and South Korea through direct-to-hotel supply arrangements.
- Square Briquettes:Stackable geometry optimizing bulk transport density for power plant procurement.
- Pillow Briquettes:Interlocking shape for manual-feed residential stoves, prevalent in rural Indian districts with sparse LPG distribution.
Round briquettes retain volume leadership in automated industrial systems; hexagonal variants are expanding most quickly in premium export channels.
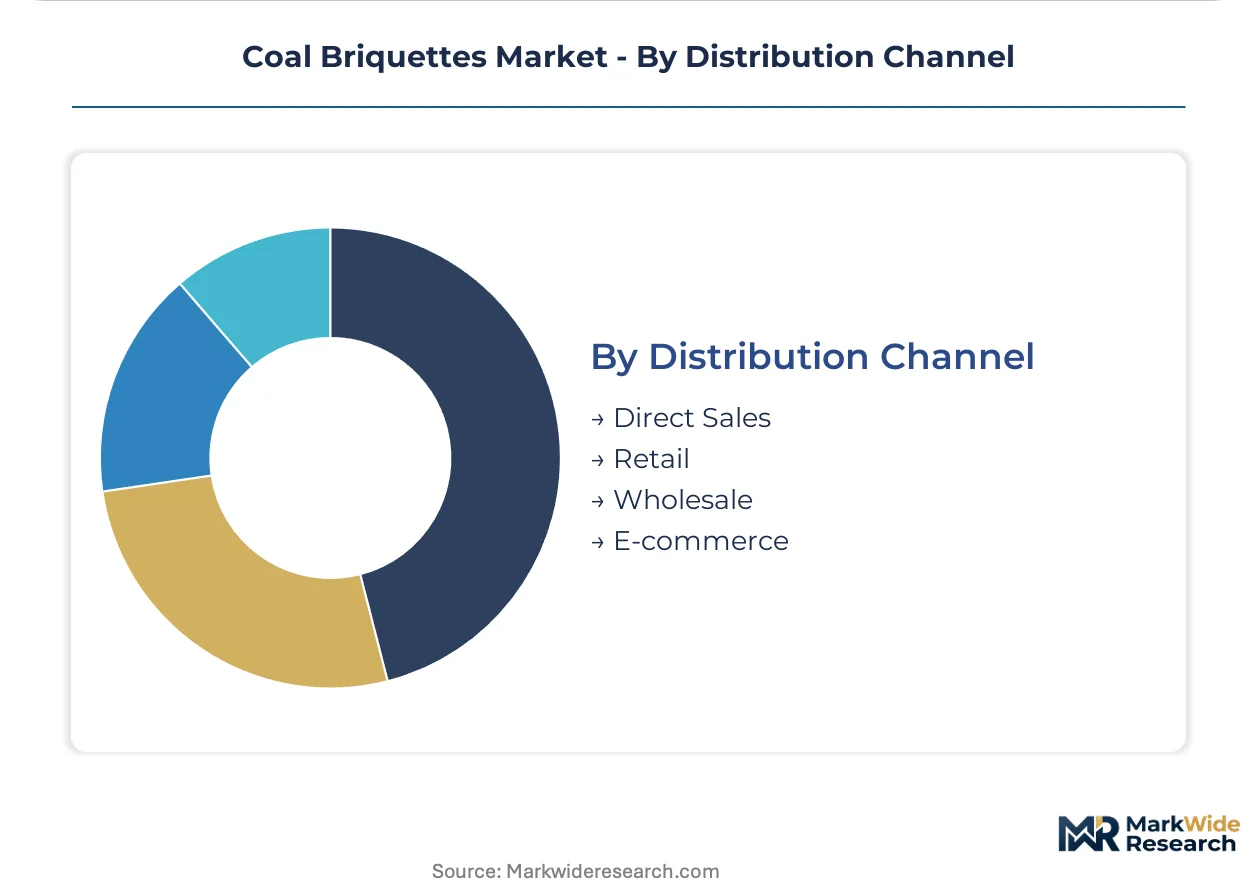
Distribution Channel:
Customer type fragmentation separates bulk industrial buyers seeking contractual certainty from fragmented residential procurement through retail and digital channels.
- Direct Sales:Long-term offtake agreements with fixed calorific specifications replacing spot-market purchasing across Asian cement and steel plants. Integrated producers leverage in-house regulatory affairs capacity to satisfy REACH documentation requirements for EU-bound shipments.
- Wholesale:Aggregated procurement for municipal heating authorities and rural electrification programs, Coal India Limited's captive mining infrastructure anchoring domestic supply chains.
- Retail:Seasonal BBQ-grade charcoal through specialty fuel merchants, compliance burden filtering smaller traders from premium industrial supply chains.
- E-commerce:Emerging channel for certified smokeless briquettes in urban Chinese markets with active MEE enforcement.
Direct sales retains volume leadership across bulk industrial segments; e-commerce is gaining share fastest in residential smokeless transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coal briquette production clusters where mining infrastructure meets conversion capacity, with regulatory pressure reshaping geographic competitiveness across major supply basins.
China
Steel and cement plants in Hebei and Shandong provinces absorb metallurgical briquette volumes as MEE enforcement tightens particulate thresholds. Dual carbon goals freeze new coal-to-briquette permits in multiple provinces, capping domestic expansion regardless of demand. The Yangtze River Delta industrial corridor sustains bulk contracts through integrated coal-to-briquette conversion facilities.
India
Power generation and rural residential segments drive volume through Coal India Limited's captive mining infrastructure. CEA mandates for beneficiated coal in designated thermal plants stimulate washed-coal briquette demand across Maharashtra and Gujarat. Bihar and Uttar Pradesh sustain cooking fuel demand where LPG distribution remains sparse.
United States
Metallurgical export contracts to Asian steelmakers anchor specialized briquette production from Appalachian coal basins. EPA Clean Air Act thresholds require third-party emissions certification for industrial shipments. The Ohio River Valley concentrates conversion capacity serving domestic steel and foundry applications.
Germany
Steelmakers in the Ruhr and Saarland adopt cold-briquetting formulations to satisfy EU Green Deal procurement criteria. REACH regulations tighten registration requirements for coal-based solid fuels, filtering smaller traders from premium supply chains. Polish border regions receive cross-border volumes for industrial boiler applications.
Indonesia
Cement and steel plants in Java lock in eighteen-month offtake agreements with penalty clauses for ash content deviation. Adaro Energy Tbk leverages mining infrastructure to supply domestic industrial heating contracts. Kalimantan mining regions feed export-oriented briquette production for Vietnamese and Thai buyers.
Coal Briquettes Market Competitive Environment
Concentration sits with integrated mining conglomerates possessing captive coal supply and in-house conversion infrastructure. State-owned enterprises anchor domestic supply chains through vertical control from extraction to distribution. Three archetypes dominate: mining-integrated producers with cost advantages, specialized metallurgical exporters serving Asian steelmakers, and regional processors dependent on spot-market feedstock procurement. Competitive moves center on securing long-term offtake agreements with fixed calorific specifications and building regulatory affairs capacity to satisfy REACH documentation requirements for EU-bound shipments.
Among mining-integrated conglomerates, Coal India Limited and China Shenhua Energy Company Limited exemplify the state-backed archetype with captive infrastructure spanning extraction through distribution. Peabody Energy Corporation occupies a position among specialized exporters targeting metallurgical segments. These three entities represent the competitive spectrum from domestic supply chain anchoring to premium export specialization.
| Leading Market Players |
|---|
| Coal India Limited |
| Peabody Energy Corporation |
| Arch Resources, Inc. |
| Adaro Energy Tbk |
| Shaanxi Coal and Chemical Industry Group |
| Yanzhou Coal Mining Company Limited |
| China Shenhua Energy Company Limited |
| BHP Group |
| ITO Global Trading Company |
| Others |
Value Chain & Pricing Dynamics
REACH registration requirements gate both European market access and price stratification across certification tiers. Industrial buyers in Belgium and the Netherlands now reject shipments lacking SCIP database entries, filtering smaller traders from premium supply chains while consolidating volume with integrated producers possessing in-house regulatory affairs capacity.
Pricing Analysis
EPA Clean Air Act thresholds dictate the pricing tier structure across US-bound industrial shipments. Three-tier pricing structure across premium, standard, and economy levels separates certified smokeless formulations with third-party emissions testing from conventional grades and spot-market commodities. Cost compression in standard black coal tiers is intensifying because feedstock volatility erodes margin predictability for independent processors without captive mining supply. Power generation buyers exhibit highest price sensitivity due to volumetric procurement scale, while specialty BBQ channels in East Asian markets absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Binder chemistry expertise scarcity at legacy state-owned coal research institutes creates a chokepoint constraining formulation optimization for specific ash fusion temperatures. Raw material procurement draws from thermal coal fines in China, India, and Indonesia, with modified starch and lignosulfonate binders increasingly sourced from agricultural waste valorization partnerships. Single-source vulnerability concentrates in petroleum-derived pitch supply for traditional hot-pressing operations. Distribution runs through direct sales channels for bulk industrial offtake agreements, with wholesale aggregating municipal heating contracts and e-commerce penetrating urban Chinese residential markets under active MEE enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemists capable of optimizing starch-molasses-pitch blends remain concentrated at diminishing state-owned research institutes, creating a bottleneck that constrains product development velocity across independent processors.
For Market Incumbents: Shield margin pools by securing long-term offtake agreements with fixed calorific specifications before biomass substitution pressure intensifies in European procurement. Deepen captive mining infrastructure to anchor domestic supply chains against feedstock cost volatility. Prioritize in-house regulatory affairs capacity to satisfy REACH documentation requirements and filter smaller competitors from premium industrial channels. For New Entrants and Emerging Players: Certification service gaps in emissions testing and third-party validation present white-space targets where integrated incumbents under-serve smaller municipal heating authorities. Rural electrification districts in Bihar and Uttar Pradesh offer the most penetrable geography given sparse LPG distribution and sustained cooking fuel demand. Pursue direct-to-hotel supply arrangements for hexagonal BBQ-grade briquettes as a differentiated go-to-market angle in East Asian specialty retail. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned mining conglomerates divesting non-core conversion assets under dual carbon policy pressure. Long-term viability hinges on positioning for carbon accounting reclassification that may credit briquette-derived emissions reductions against coal baseline calculations. Watch for MEE permit relaxation signals in Chinese provinces as inflection indicators for domestic capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Supply | Agricultural waste valorization partnerships with starch and lignosulfonate producers reduce petroleum-derived input dependency. |
| Long-term Supply Agreement | Eighteen-month offtake contracts with penalty clauses for ash content deviation lock in Vietnamese and Indonesian steelmaker demand. |
| Green Certification Program | SCIP database entries and REACH compliance documentation filter smaller traders from premium EU-bound industrial supply chains. |
| Capacity Expansion | Integrated coal-to-briquette conversion facilities in the Yangtze River Delta sustain bulk contracts despite MEE permit freezes elsewhere. |
| Joint Venture | Partnerships with legacy state-owned coal research institutes access scarce formulation chemists for ash fusion temperature optimization. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with plant managers at cement and steel facilities, procurement leads at thermal power generators, distribution channel partners in municipal heating authorities, and technical R&D directors at binder suppliers contributing operational perspectives. Secondary validation drew from customs and trade data, SEC 10-K filings of listed mining conglomerates, CEA regulatory notifications, and MEE policy circulars. Bottom-up volume modeling across production facilities triangulated with top-down demand aggregation across end-use segments to reconcile market sizing estimates.
Across the analysis window, the forecasting framework modeled product type stratification, end-use industry absorption patterns, form factor adoption by stoker technology standards, and distribution channel evolution by customer type fragmentation. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory trajectory assumptions. Forecast inputs incorporated MEE permit issuance patterns, CEA beneficiation mandate enforcement timelines, and EU Green Deal procurement criteria adoption curves.
Underlying assumptions cover sustained MEE enforcement of dual carbon goals, stable CEA mandate continuity for washed-coal briquettes in designated Indian thermal plants, and REACH registration burden persistence for EU-bound shipments, with deviation risk concentrated in carbon accounting reclassification rules that could redirect procurement toward biomass-coal blends. Practitioners should keep alternative scenarios live as national greenhouse gas inventory methodologies and municipal air quality ordinances evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Chafing Fuel Market
Fuels
Global Charcoal Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
India Coal Market
Fuels
Briquette Market
Fuels
LPG Vaporizer Market
Fuels
Global Industrial Burner Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Global Gas Treatment Market
Fuels
India Petrol Station Market
Fuels
No.2 Diesel Fuel Market
Fuels
Gas Feed System Market
Fuels
High Octane Racing Fuel Market
Fuels
Underground Coal Gasification Market
Fuels
Aviation Fuel Market