
 South America Aviation Fuel Market | 2026-2036
South America Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
South America Aviation Fuel Market Analytics
Sustainable aviation fuel is hardening as the primary cost and compliance variable for regional refiners. Petroleo Brasileiro S.A. leverages its integrated upstream-downstream structure to control domestic feedstock supply for conventional jet production. Shell PLC sustains blending infrastructure investments across Brazilian coastal terminals to position for ANP-mandated SAF thresholds. TotalEnergies SE anchors its regional competitiveness through specialized logistics partnerships with Colombian and Peruvian airport authorities.
South America aviation fuel encompasses refined petroleum products and emerging bio-derived alternatives formulated to meet turbine engine combustion specifications, with Jet A-1 dominating commercial operations due to its minus 47 degrees Celsius freeze point and 38 degrees Celsius flash point requirements. The fuel type dimension shows Jet A-1 occupying the mature volume base while SAF blends represent the fastest-growing margin pool as certification pathways expand. Delivery mode segmentation reveals trucks controlling last-mile airport distribution across the Andean ridge, whereas pipelines dominate Brazilian coastal refining corridors where Petrobras maintains infrastructure density.
ANP blending regulations, Colombia's Ministry of Mines and Energy decarbonization frameworks, and Argentina's Secretariat of Energy import substitution policies collectively reshape product standards and market access conditions across the region. ICAO Carbon Offsetting and Reduction Scheme for International Aviation compliance deadlines tighten specification requirements for cross-border carriers operating São Paulo-Guarulhos and El Dorado International hubs. Stakeholders must monitor feedstock availability for domestic SAF production versus import dependency as the decisive structural variable for regional supply security.
Market Dynamics
The ANP biofuel blending mandate is compressing conventional jet margins while forcing refiners to reconfigure feedstock procurement toward domestic soybean and animal fat supply chains. This regulatory pressure is concentrating capital allocation decisions among integrated oil majors with captive agriculture partnerships.
Growth Catalysts
- Fleet utilization recovery:Brazilian commercial airlines are expanding flight frequencies across São Paulo-Guarulhos, Rio de Janeiro-Galeão, and Belo Horizonte-Confins corridors as passenger volumes normalize post-pandemic.
- ANP Resolution 893:Brazil's mandatory SAF blending thresholds are creating guaranteed offtake volumes for domestic biofuel producers with approved certification pathways.
- Feedstock proximity:Argentina's soybean crushing infrastructure positions regional refiners to source fatty acid methyl ester precursors at lower logistics cost than Asian or North American alternatives.
Market Restraints
- Crude import dependency:Colombia and Chile lack sufficient domestic crude production, exposing refiners to Brent-linked price volatility and foreign exchange risk.
- SAF certification bottlenecks:ASTM D7566 and CAACI approval timelines for novel feedstocks extend 18-36 months, freezing investment in second-generation pathway development.
- Pipeline infrastructure gaps:Andean topography forces reliance on truck distribution across Peru, Ecuador, and Bolivia, elevating delivered fuel costs versus coastal Brazilian terminals.
Strategic Opportunities
- Colombian Pacific corridor:Buenaventura port expansion and Cali-Alfonso Bonilla Aragón Airport cargo growth create underpenetrated demand nodes for integrated logistics providers.
- HEFA-SPK pathway scale-up:Convergence of used cooking oil collection networks with hydrotreating capacity at existing Brazilian refineries enables cost-competitive SAF production.
- ICAO CORSIA compliance services:Carbon accounting and verification bundling with fuel supply contracts offers margin expansion for traders serving international carriers at El Dorado International.
Industry Challenges
- Specialized technician scarcity:SAF blending, storage, and quality control operations require personnel trained on ASTM D1655 variant testing protocols that conventional petroleum laboratories rarely maintain.
- Legacy tankage retrofit costs:Existing airport fuel farms across Argentina and Uruguay require corrosion-resistant lining upgrades to handle elevated fatty acid content in SAF blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Aviation Fuel Market |
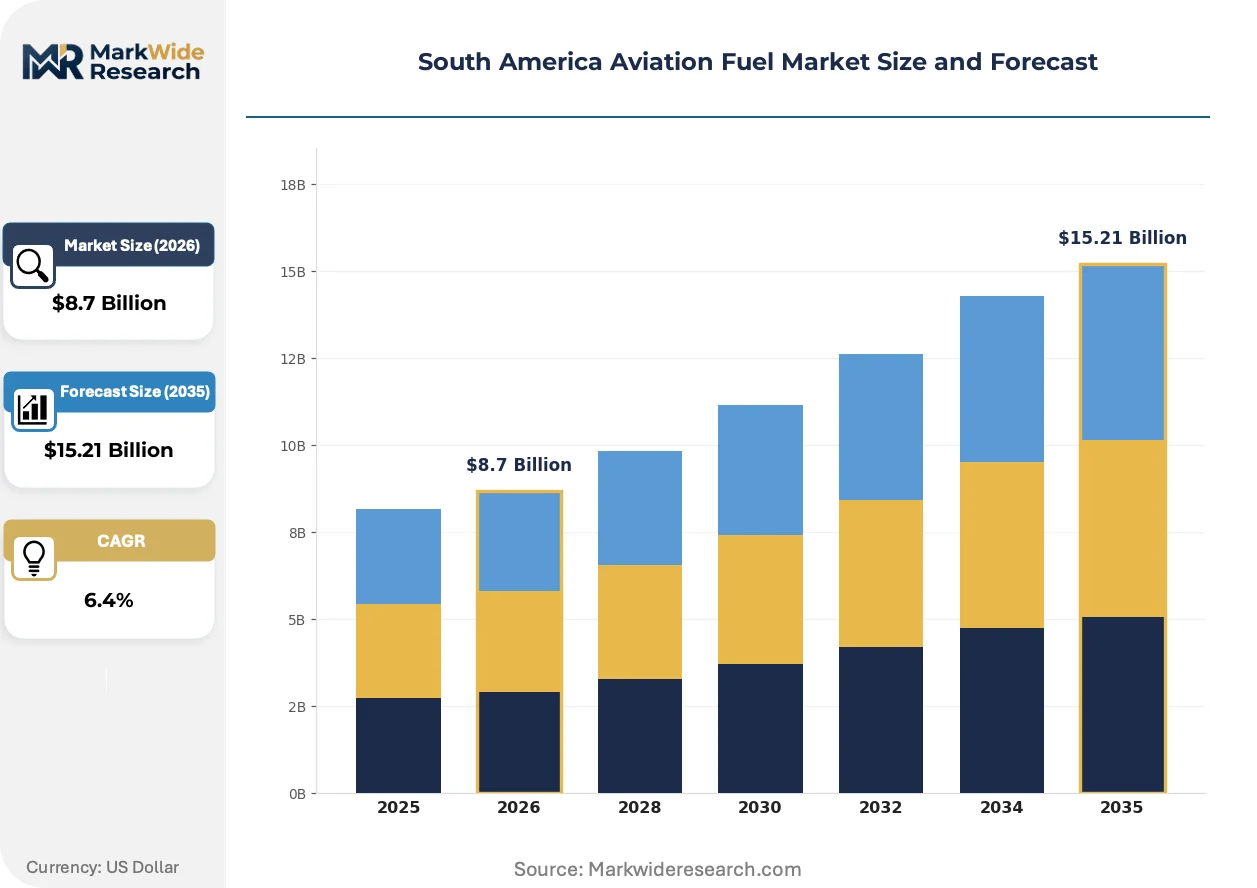
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Avgas, Others Delivery Mode: Pipelines, Tankers, Trucks, Rail End User: Commercial Airlines, Cargo Operators, Military Aviation, Private Jets Usage Scenario: Domestic Flights, International Flights, Cargo Transport, Training Flights |
| Companies Covered | Petroleo Brasileiro S.A., Shell PLC, BP PLC, TotalEnergies SE, Repsol SA, ExxonMobil Corporation, Pan American Energy SL, Allied Aviation Services Inc, YPF, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Aviation Fuel Market Evolving Landscape
Electrification of ground support equipment and auxiliary power units is reshaping airport energy demand patterns, compressing traditional jet fuel consumption per aircraft turnaround while opening adjacent revenue streams for integrated energy suppliers.
Hydrotreated esters and fatty acids (HEFA) is electrifying the SAF production landscape by converting waste oils and animal fats into drop-in jet fuel molecules. Brazilian refiners with existing hydrotreating capacity are retrofitting units faster than greenfield construction timelines allow. This technology is electrifying competitive positioning by rewarding incumbents with stranded asset utilization over pure-play biofuel startups.
ANP Resolution 893 and Colombia's Ministry of Mines and Energy decarbonization frameworks are mandating progressive SAF blend rates through 2035. Refiners must secure certified feedstock contracts three to five years forward to guarantee compliance volumes. Brazilian coastal terminals are responding by consolidating blending infrastructure investments at Santos and Paranaguá to capture economies of scale.
Airline procurement departments are consolidating fuel purchasing through multiyear offtake agreements with price collars indexed to soybean oil futures. This behavior is displacing spot market dominance at major hubs and transferring volume risk to suppliers with balance sheet capacity. The shift is most visible at São Paulo-Guarulhos, where LATAM and Gol have structured integrated supply contracts covering 70 percent of forecast consumption.
South America Aviation Fuel Market Segmentation
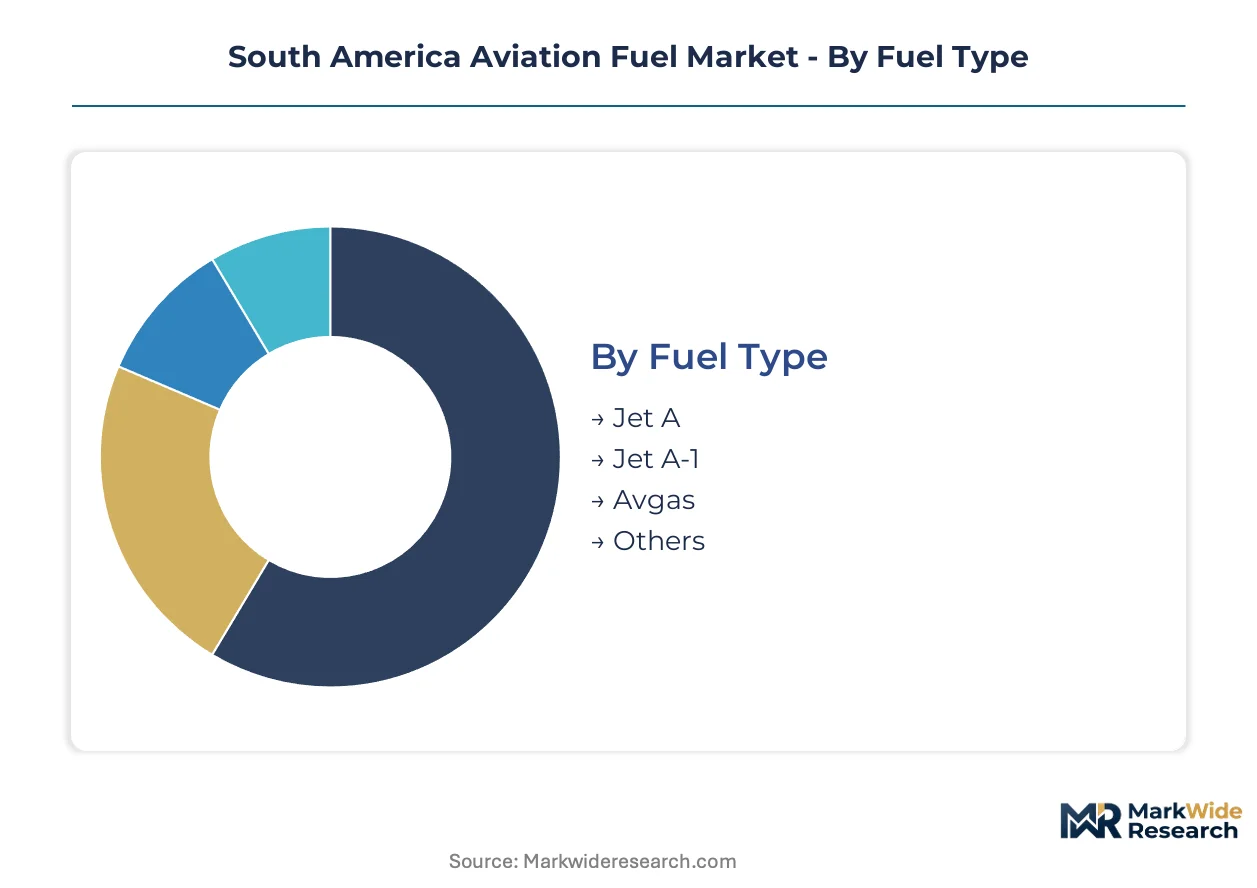
Fuel specifications, delivery infrastructure, and operational use cases each impose distinct procurement and margin structures on South American suppliers. Understanding where segments intersect with regulatory mandates and logistics constraints clarifies where capital deployment yields competitive advantage.
Fuel Type:
Standalone fuel specifications dominate commercial aviation procurement, while blended alternatives require embedded certification pathways to access airport fuel farms.
- Jet A:Formulated with a minus 40 degrees Celsius freeze point and 38 degrees Celsius minimum flash point, this kerosene-grade fuel serves turbine engines in warmer climates. Brazilian carriers operating northern domestic routes favor Jet A for its slightly lower refining cost versus Jet A-1, though cold-weather restrictions limit deployment to equatorial corridors.
- Jet A-1:The minus 47 degrees Celsius freeze point specification enables high-altitude operations across Andean crossings and southern cone winter conditions. Demand concentrates at São Paulo-Guarulhos, El Dorado International, and Santiago-Arturo Merino Benítez as international carriers standardize on this grade for fleet interoperability.
- Avgas:High-octane aviation gasoline formulated for piston-engine aircraft with leaded and unleaded variants. Brazilian flight training schools and agricultural aviation operators in Mato Grosso and São Paulo states anchor regional consumption.
- Others:Emerging sustainable aviation fuel blends and military-grade JP-8 derivatives requiring specialized handling protocols. ANP certification pathways currently restrict commercial volumes to test programs at Santos and Rio de Janeiro-Galeão.
Jet A-1 leads volumes today; SAF-compatible blends are gaining share fastest.
Delivery Mode:
Cost tiers separate coastal pipeline corridors from Andean truck-reliant distribution, with infrastructure maturity determining delivered fuel economics.
- Pipelines:Dedicated aviation fuel pipelines connect Petrobras refineries at Paulínia and Capuava to São Paulo-Guarulhos and Viracopos airports. This mode captures economies of scale on Brazil's southeastern corridor where throughput justifies dedicated infrastructure investment.
- Tankers:Coastal marine terminals at Santos, Paranaguá, and Buenaventura receive imported jet fuel for redistribution. Colombian Pacific ports rely on tanker discharge where pipeline connectivity to interior airports remains undeveloped.
- Trucks:Road tankers dominate last-mile delivery across Peru, Ecuador, and Bolivia where Andean topography blocks pipeline construction. Elevated per-liter logistics costs compress refiner margins on these routes.
- Rail:Limited deployment on Brazilian bulk fuel corridors connecting interior terminals to coastal refining centers. Rail's share remains constrained by loading infrastructure gaps at airport fuel farms.
Pipelines dominate value throughput; trucks handle the widest geographic spread.
End User:
Customer type determines contract structure, with scheduled carriers anchoring long-term offtake agreements and fragmented operators relying on spot procurement.
- Commercial Airlines:LATAM, Gol, and Avianca consolidate procurement through multiyear supply contracts with price collars indexed to commodity benchmarks. These carriers drive SAF blend mandate compliance through volume commitments.
- Cargo Operators:Dedicated freighter fleets at El Dorado International and Viracopos prioritize fuel availability over price optimization given tight turnaround schedules. Amazon Air and LATAM Cargo expansion is expanding this segment's share.
- Military Aviation:Brazilian Air Force and Colombian Aerospace Force operations require JP-8 and F-24 specifications with national security procurement protocols. State-controlled supply chains limit private sector participation.
- Private Jets:Fractional ownership and charter operators at São Paulo-Congonhas and Buenos Aires-Aeroparque purchase through fuel card networks. Price sensitivity is lower than commercial carriers but volumes are fragmented across numerous handlers.
Commercial airlines anchor contract volumes; cargo operators are expanding most quickly.
Usage Scenario:
Application context shapes fuel quality requirements and regulatory exposure, with international operations facing stricter carbon accounting obligations.
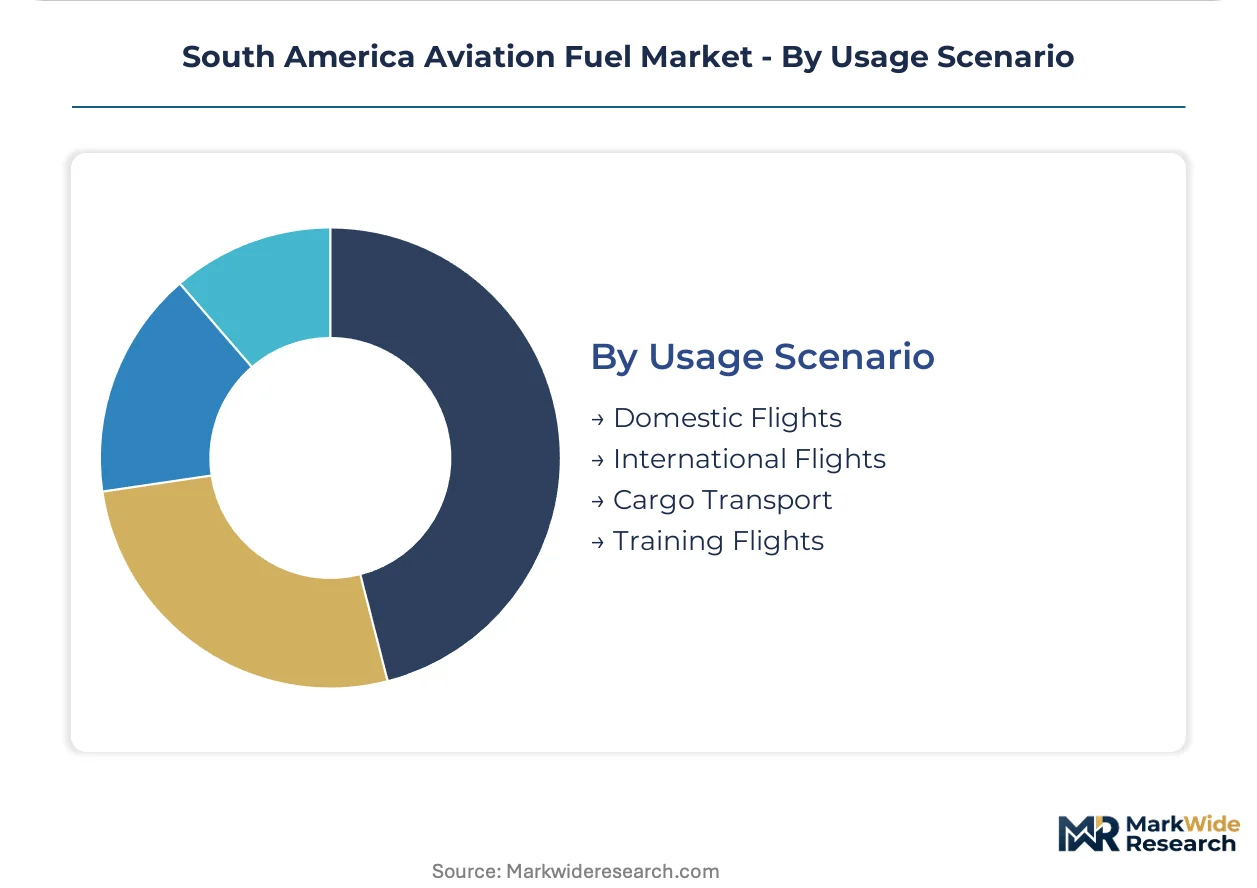
- Domestic Flights:Intra-Brazilian and intra-Argentine routes operate under national regulatory frameworks with ANP and Secretariat of Energy jurisdiction. These flights currently face lighter SAF mandate compliance timelines than international services.
- International Flights:Cross-border services from São Paulo-Guarulhos and El Dorado International fall under ICAO CORSIA carbon offsetting requirements. Fuel suppliers must bundle emissions verification with physical delivery to serve these carriers.
- Cargo Transport:Dedicated freighter operations prioritize high-density fuel loading and rapid refueling turnaround. Colombian flower export corridors from Rionegro and Bogotá drive concentrated demand on specific trunk routes.
- Training Flights:Flight schools and military academies consume Avgas and Jet A-1 in high-frequency, low-altitude patterns. Brazilian ANAC-certified training centers in São Paulo state represent the regional demand anchor.
Domestic flights handle the largest volume base; international flights face the steepest compliance cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern aviation corridor connecting São Paulo, Rio de Janeiro, and Belo Horizonte anchors South American jet fuel demand. Brazil's refining infrastructure density and ANP regulatory mandates concentrate capital allocation decisions among integrated suppliers. Argentina, Colombia, Chile, and Peru each present distinct feedstock, logistics, and compliance configurations.
Brazil
Fleet utilization recovery at São Paulo-Guarulhos and Rio de Janeiro-Galeão drives volume growth for LATAM and Gol. ANP Resolution 893 mandates progressive SAF blending thresholds through 2035. Petrobras maintains dedicated aviation fuel pipelines from Paulínia and Capuava refineries to Viracopos and Guarulhos terminals.
Argentina
Soybean crushing infrastructure in the Pampas region positions domestic refiners to source HEFA precursors at lower logistics cost than import alternatives. The Secretariat of Energy promotes import substitution policies favoring domestic biofuel production. Buenos Aires-Aeroparque and Ezeiza International serve as demand anchors for Aerolineas Argentinas and private aviation operators.
Colombia
Cargo expansion at El Dorado International and Cali-Alfonso Bonilla Aragón creates concentrated demand nodes for integrated logistics providers. The Ministry of Mines and Energy decarbonization frameworks tighten specification requirements for cross-border carriers. Buenaventura port expansion on the Pacific coast enables tanker-reliant supply chains where pipeline connectivity remains undeveloped.
Chile
Crude import dependency exposes refiners to Brent-linked price volatility and foreign exchange risk at Santiago-Arturo Merino Benítez. The national petroleum regulator enforces sulfur content specifications aligned with ICAO CORSIA compliance timelines. Andean topography forces reliance on truck distribution to interior airports, elevating delivered fuel costs versus coastal terminals.
Peru
Domestic flight networks from Lima-Jorge Chávez International operate under lighter SAF mandate timelines than international services. The country's energy ministry oversees quality control protocols for imported jet fuel discharged at Callao port. Road tankers dominate last-mile delivery across the Andean ridge where pipeline construction remains economically unviable.
South America Aviation Fuel Market Competitive Landscape
Capacity expansion dominates the current landscape as refiners retrofit hydrotreating units for HEFA-SPK production faster than greenfield construction allows. The market structure concentrates among integrated oil majors with captive agriculture partnerships and captive feedstock supply chains. Three archetypes define competitive positioning: state-controlled upstream-downstream integrators, multinational traders with blending infrastructure, and regional independents with specialized logistics partnerships. Strategic moves center on backward integration into domestic soybean and animal fat supply chains, plus consolidation of blending infrastructure at coastal terminals to capture economies of scale.
Among state-controlled upstream integrators, Petroleo Brasileiro S.A. exemplifies the archetype leveraging refining infrastructure density across Brazil's southeastern corridor. Shell PLC and TotalEnergies SE occupy positions within the multinational trader tier, with the former sustaining coastal terminal investments and the latter anchoring regional competitiveness through airport authority partnerships. These three entities represent distinct strategic postures: captive feedstock control, blending infrastructure scale, and specialized logistics access.
| Leading Market Players |
|---|
| Petroleo Brasileiro S.A. |
| Shell PLC |
| BP PLC |
| TotalEnergies SE |
| Repsol SA |
| ExxonMobil Corporation |
| Pan American Energy SL |
| Allied Aviation Services Inc |
| YPF |
| Others |
Value Network & Pricing Analysis
Soybean oil futures volatility cascades from Argentine crushing facilities through Brazilian refinery gate pricing into long-term offtake contracts at São Paulo-Guarulhos, with ANP-mandated SAF blend rates forcing buyers into premium-tier procurement indexed to agricultural commodity benchmarks rather than conventional Brent-linked structures.
Pricing Analysis
Input-cost pass-through from fatty acid methyl ester precursors dominates contract structures, with HEFA-SPK pathways commanding premium spreads over conventional Jet A-1 due to ASTM D7566 certification requirements. Price differentiation rests on feedstock provenance and carbon intensity scores, with Brazilian coastal terminals extracting margin from domestic soybean supply chains while Andean buyers absorb elevated logistics costs. Pricing pressure stems from ANP Resolution 893 compliance deadlines compressing conventional jet margins. Cargo operators at El Dorado International show lowest price sensitivity given tight turnaround schedules, whereas flight training schools in Mato Grosso operate on thin fuel card spreads.
Supply Chain Analysis
Dual-sourcing requirements from LATAM and Gol procurement departments mandate qualified suppliers across both Petrobras pipeline corridors and coastal tanker terminals, forcing traders to maintain redundant inventory positions. Supply concentration centers on Brazil, Argentina, and Colombia, with each jurisdiction anchoring distinct feedstock advantages. Raw material dependencies span domestic soybean oil, imported crude, and used cooking oil collection networks. Supply chain risk crystallizes around pipeline infrastructure gaps across Andean topography that elevate truck-reliant delivery costs. Distribution runs through dedicated aviation fuel pipelines on Brazil's southeastern corridor, with tanker discharge at Pacific ports serving Colombian Pacific demand nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in SAF blending infrastructure and captive feedstock control, with HEFA pathway economics improving as Brazilian refiners retrofit stranded hydrotreating capacity.
For Market Incumbents: Deploy backward integration into domestic soybean crushing partnerships to secure ANP-mandated SAF volumes at cost structures below import alternatives. Consolidate blending infrastructure at Santos and Paranaguá terminals to capture economies of scale against fragmented Andean truck-reliant competitors. Defensive positioning requires corrosion-resistant tankage upgrades at Argentine airport fuel farms before fatty acid content thresholds rise. For New Entrants and Emerging Players: Enter via specialized logistics partnerships with Colombian and Peruvian airport authorities where pipeline gaps create service-based differentiation opportunities. White-space targets include Buenaventura port expansion corridors and Cali-Alfonso Bonilla Aragón cargo growth nodes. Go-to-market positioning should bundle ICAO CORSIA carbon accounting verification with physical fuel delivery to capture international carrier procurement consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where balance sheet capacity determines ability to underwrite multiyear offtake agreements with agricultural commodity price collars. Long-term viability favors integrated suppliers with captive upstream feedstock rather than pure-play blending operations exposed to soybean oil volatility. Acquisition target archetypes include regional independents with specialized airport authority relationships. The signal to watch is ASTM D7566 approval timelines for novel feedstocks, which would unlock second-generation pathway investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive soybean and animal fat sourcing locks in ANP compliance margins against volatile agricultural commodity markets. |
| Coastal Terminal Blending Consolidation | Santos and Paranaguá infrastructure scale captures economies denied to fragmented Andean truck-reliant competitors. |
| HEFA-SPK Pathway Certification | ASTM D7566 approval unlocks guaranteed offtake volumes under Brazil's mandatory SAF blending thresholds. |
| Airport Authority Logistics Partnerships | Specialized access agreements at El Dorado International and Viracopos secure last-mile distribution control. |
| CORSIA Compliance Service Bundling | Carbon accounting verification integration captures LATAM and Gol procurement consolidation toward integrated suppliers. |
Research Methodology
Coverage spans Brazil, Argentina, Colombia, Chile, and Peru, with primary inputs from each market's refining, airline procurement, and regulatory enforcement stakeholders. Primary interviews engaged aviation fuel supply managers at major carriers, refinery operations directors, ANP certification specialists, and airport fuel farm operators. Secondary validation drew from ANP regulatory filings, Colombian Ministry of Mines and Energy decarbonization frameworks, ICAO CORSIA implementation documents, and customs trade data on jet fuel imports. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Granularity-level modeling operated at fuel type, delivery mode, end user, and usage scenario dimensions, with SAF blend rate trajectories tracked separately under ANP Resolution 893 compliance pathways. CAGRs were derived from fleet utilization recovery curves and regulatory mandate phase-in schedules across the analysis window. Industry-specific forecast inputs included LATAM and Gol published capacity expansion plans, Petrobras refinery retrofit timelines, and Argentine Secretariat of Energy biofuel production targets.
Inputs from ANP, Colombian Ministry of Mines and Energy, and Argentine Secretariat of Energy were available through the study window; gaps in real-time SAF certification approval timelines introduce uncertainty bands around HEFA-SPK production ramp assumptions. Deviation in ASTM D7566 pathway approvals or soybean oil futures volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Oil Dispenser Market
Fuels
India LNG Market
Fuels
LPG Tanker Market
Fuels
Germany Bunker Fuel Market
Fuels
Aviation Fuel Market
Fuels
India Retail Fuel Market
Fuels
Europe Gas Market
Fuels
Gas Pooling Mechanism Market
Fuels
China LNG Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Global Gas Treatment Market
Fuels
No.4 Fuel Oil Market
Fuels
Global Methane Hydrate Market
Fuels
Marine Fuel Filter Market
Fuels
Tire Derived Fuel Market
Fuels
Emulsified Fuel Market