
 CNG Dispenser Market | 2026-2036
CNG Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
CNG Dispenser Market Analysis
Asset-light leasing models for refueling infrastructure are rewriting competitive entry barriers in the CNG dispenser sector. Dover Fueling Solutions leverages its service-network density to anchor long-term station contracts in mature markets. Censtar Science & Technology competes on manufacturing scale, supplying cost-optimized units across Asia-Pacific corridors. Kraus Global specializes in cold-climate dispenser engineering, extending operational viability into northern latitudes where conventional units falter.
A CNG dispenser is a pressurized fuel-transfer system engineered to meter and deliver compressed natural gas at operating pressures up to 250 bar through a sealed nozzle-vehicle receptacle interface. Coriolis mass-flow meters with temperature-compensated density correction have become the dominant metrology standard, replacing mechanical displacement systems that suffered from gas-compressibility measurement errors. Digital dispenser architectures now command the technology margin pool, integrating contactless payment, fleet-card authentication, and remote diagnostics through embedded cellular modems. Public transportation end-users drive the fastest-growing installation category, as municipal bus operators and intercity coach fleets convert diesel assets under emissions-mandated procurement rules.
EPA emission standards for medium- and heavy-duty vehicles, India's CEA grid-interconnection mandates for station power, and the EU F-Gas Regulation on compressor-sealed systems collectively shape product-certification requirements and market-access timelines. BIS certification for pressure equipment and metrological accuracy remains mandatory for India-bound dispenser shipments, filtering out uncertified suppliers. Stakeholders must monitor how hydrogen-blending ratios in existing CNG pipelines force recalibration of dispenser flow-control algorithms and safety-cutoff thresholds.
Market Dynamics
The CNG dispenser sector is reconfiguring around digital metrology architectures that compress maintenance cycles and enable predictive service models. This structural shift from mechanical to solid-state flow measurement is redistributing margin pools toward software-integrated hardware suppliers.
Growth Catalysts
- India's PLI scheme for alternative fuels:Public transportation agencies are accelerating fleet conversions under production-linked incentives, anchoring dispenser demand in Gujarat's industrial corridor and Maharashtra's urban transit networks.
- Coriolis mass-flow meters with temperature-compensated density correction:This metrology standard eliminates gas-compressibility measurement errors that plagued mechanical displacement systems, improving custody-transfer accuracy for fleet operators.
- EU F-Gas Regulation on compressor-sealed systems:Refrigerant containment mandates are driving replacement cycles across European refueling infrastructure, creating certified-upgrade demand for sealed-dispenser architectures.
Market Restraints
- Stainless steel and high-pressure valve assembly costs:Raw material volatility in specialty alloys constrains margin flexibility for dispenser manufacturers serving price-sensitive municipal procurement.
- BIS certification bottlenecks:Pressure equipment and metrological accuracy approvals for India-bound shipments filter out uncertified suppliers, concentrating import access among pre-qualified vendors.
- Electrification substitution in urban bus fleets:Battery-electric transit buses are capturing procurement share in European and Chinese municipalities, compressing CNG conversion timelines in dense urban service routes.
Strategic Opportunities
- Hydrogen blending in existing CNG pipelines:Dispenser flow-control algorithms and safety-cutoff thresholds require recalibration, creating upgrade service revenue for installed-base operators.
- Remote diagnostics through embedded cellular modems:Fleet-card authentication and contactless payment integration are enabling subscription-based service contracts that extend customer lifetime value.
- CEA grid-interconnection mandates for station power:Indian stations must install grid-synchronized electrical infrastructure, opening bundled power-dispenser procurement packages.
Industry Challenges
- Coriolis meter calibration technician scarcity:Solid-state metrology systems require specialized field-service expertise that outstrips current training pipeline output in emerging markets.
- Legacy mechanical meter retrofit complexity:Existing station infrastructure often requires foundation and electrical rework to accommodate digital dispenser architectures, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNG Dispenser Market |
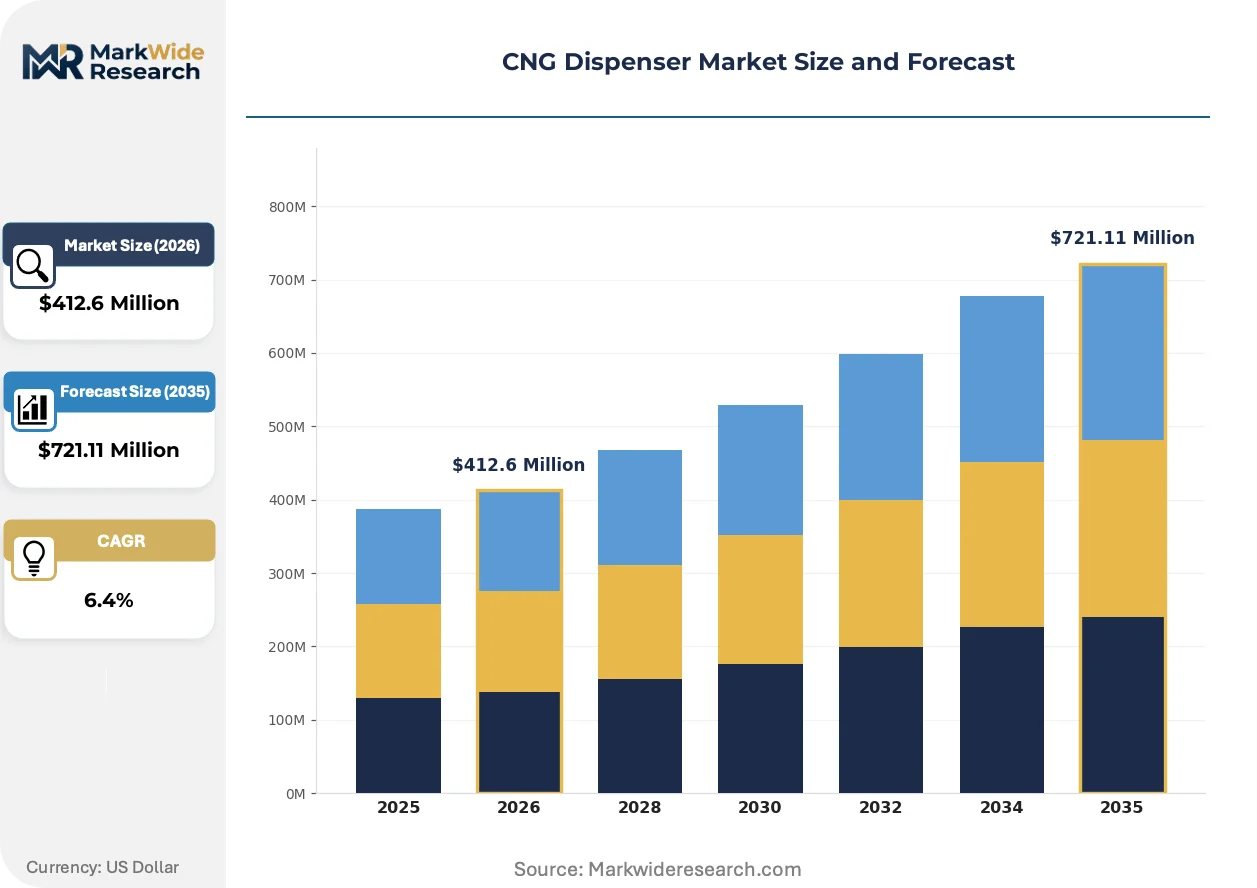
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $721.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Dispenser, Digital Dispenser, Mobile Dispenser, Automated Dispenser End User: Commercial Fleets, Public Transportation, Refueling Stations, Agricultural Vehicles Installation Type: Above Ground, Below Ground, Portable, Permanent Distribution Channel: Direct Sales, Distributors, Online Sales, Resellers |
| Companies Covered | Gilbarco Veeder-Root, Dover Fueling Solutions, Bennett Pump Company, Censtar Science & Technology, FTI International Group, Kraus Global, Lanfeng Machinery, Tatsuno Corporation, Scheidt & Bachmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNG Dispenser Market Emerging Trajectories
Digital architectures are virtualizing the physical layer of fuel-transfer systems, collapsing the distinction between metering hardware and fleet-management software. This convergence is redistributing competitive advantage toward platforms that integrate payment, authentication, and predictive maintenance.
Coriolis mass-flow measurement with embedded temperature compensation is virtualizing the traditional mechanical meter's function. Municipal bus operators and intercity coach fleets are adopting these solid-state systems at replacement-cycle velocity. The technology is virtualizing maintenance schedules by enabling remote diagnostic access that compresses field-service dispatch requirements.
The EU F-Gas Regulation on sealed compressor systems is accelerating refrigerant-containment compliance across European refueling corridors. Industrial consequence includes forced replacement of legacy open-loop cooling architectures in high-throughput stations. Northern European operators are responding with pre-emptive upgrade programs to avoid operational interruption during enforcement windows.
Fleet procurement is consolidating around outcome-based service contracts that bundle dispenser hardware with guaranteed uptime performance. Traditional equipment-sale channels are ceding ground to integrated service providers in India's Gujarat industrial belt. Municipal transit authorities there are piloting availability-based payment structures that align vendor incentives with operational continuity.
CNG Dispenser Market Segmentation
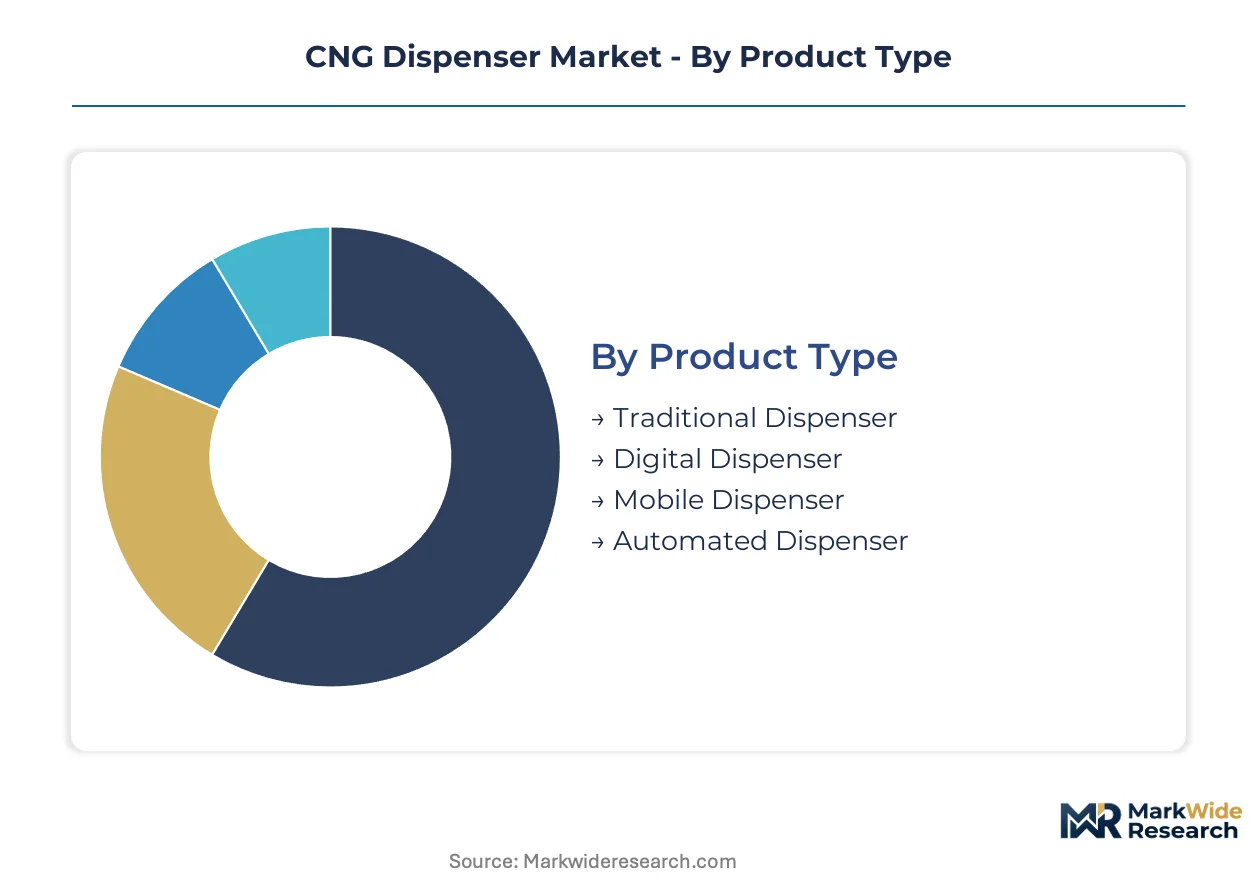
CNG dispenser segmentation reveals how technology maturity, infrastructure constraints, and fleet procurement patterns fragment demand across incompatible hardware configurations. Each dimension—product architecture, end-use intensity, installation environment, and procurement channel—creates distinct margin pools and competitive entry points.
Product Type:
The use-case spectrum spans legacy mechanical metering through fully automated fuel-transfer systems, with digital architectures displacing incumbent technologies at replacement velocity.
- Digital Dispenser:Coriolis mass-flow meters with temperature-compensated density correction anchor custody-transfer accuracy. Municipal bus operators in Gujarat and Maharashtra specify these units under PLI-linked fleet procurement, prioritizing remote diagnostics and fleet-card authentication integration.
- Traditional Dispenser:Mechanical displacement systems with gas-compressibility measurement limitations persist in price-sensitive secondary markets. Existing installed base in India's tier-2 cities generates spare-part revenue streams rather than new-unit demand.
- Mobile Dispenser:Trailer-mounted compressed natural gas delivery systems serve temporary construction fleets and emergency pipeline-interruption coverage.
- Automated Dispenser:Unattended fuel-transfer architectures with contactless payment and robotic nozzle positioning target high-throughput fleet depots.
Established volume favors Traditional Dispensers; emerging adoption favors Digital Dispensers.
End User:
Customer-type concentration determines flow-rate specifications, payment-system requirements, and service-contract structures across the value chain.
- Public Transportation:Municipal bus operators and intercity coach fleets drive specification standards for high-cycle durability and integrated fleet-management software. India's CEA grid-interconnection mandates for station power bundle electrical infrastructure with dispenser procurement in Gujarat's industrial belt.
- Commercial Fleets:Logistics operators and goods carriers prioritize throughput velocity and multi-nozzle configurations for simultaneous vehicle refueling.
- Refueling Stations:Retail-oriented installations balance consumer-payment convenience with regulatory metrology certification.
- Agricultural Vehicles:Tractor and harvester conversions in India's grain-producing states generate seasonal demand spikes tied to harvest financing cycles.
Public Transportation commands the steepest expansion trajectory; Commercial Fleets anchor current revenue concentration.
Installation Type:
Physical deployment constraints dictate foundation requirements, safety-perimeter regulations, and climate-resilience engineering specifications.
- Above Ground:Standard elevated dispenser housings with weatherproof enclosures dominate temperate-climate installations. European operators under EU F-Gas Regulation on sealed compressor systems specify these configurations for refrigerant-containment compliance.
- Below Ground:Subsurface dispenser vaults with frost-protection and flood-resistance engineering serve northern European and high-altitude corridors where conventional units face operational failure.
- Portable:Rapid-deployment skid-mounted systems enable temporary refueling during infrastructure construction or emergency response.
- Permanent:Fixed concrete-pad installations with integrated electrical and communication infrastructure anchor long-term station economics.
Permanent installations dominate asset-base valuation; Portable configurations gain share in contingency-planning procurement.
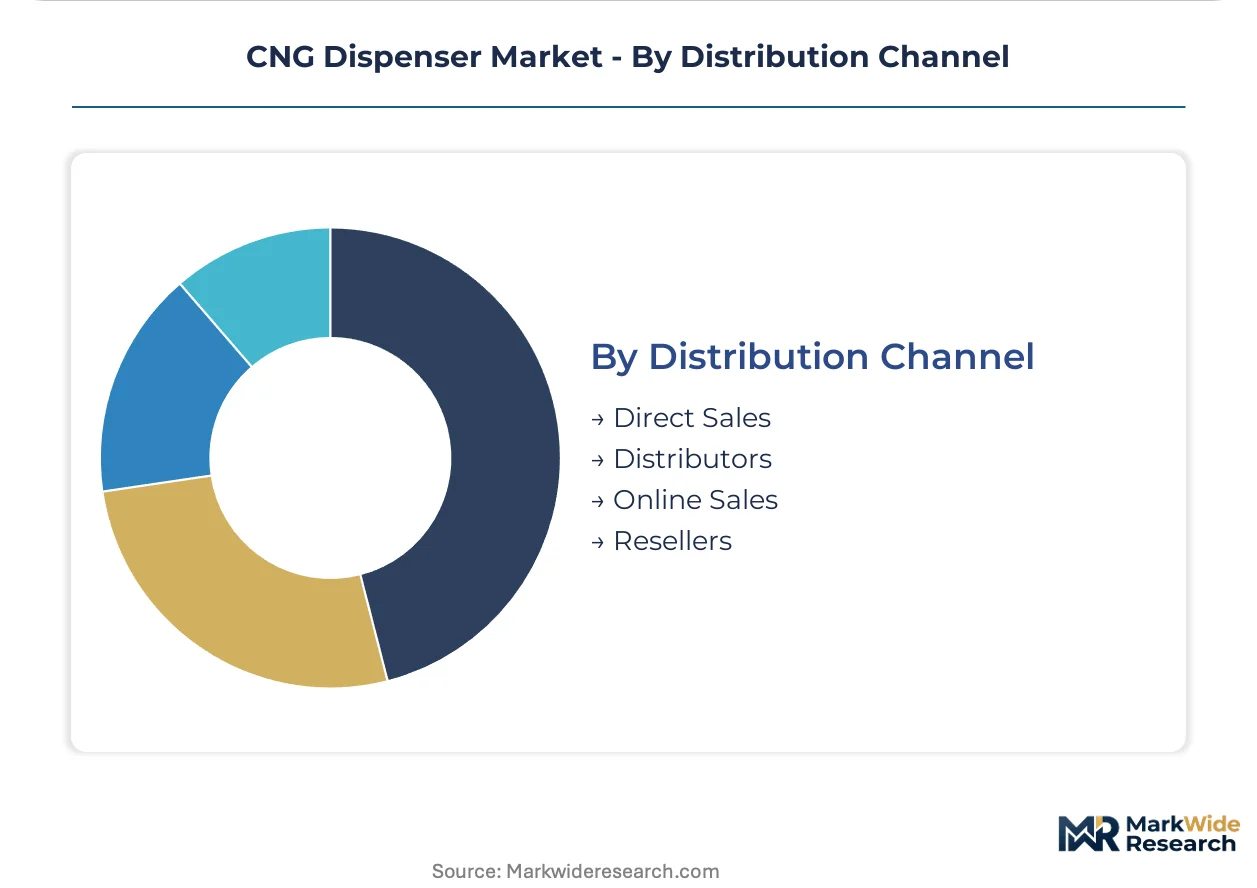
Distribution Channel:
Procurement-pathway selection reflects project scale, technical-complexity tolerance, and vendor-relationship maturity in regional markets.
- Direct Sales:Manufacturer-direct contracting for large fleet operators and municipal transit authorities. Dover Fueling Solutions and Censtar Science & Technology anchor long-term station contracts through service-network density commitments.
- Distributors:Regional stocking distributors with local language support and spare-part inventory serve mid-scale independent station operators across Asia-Pacific corridors.
- Resellers:Value-added resellers bundle dispenser hardware with installation and certification services for fragmented end-user bases.
- Online Sales:Digital procurement platforms with specification-comparison tools target standardized replacement units for existing infrastructure.
Direct Sales capture premium-margin bundled contracts; Distributors penetrate price-sensitive geographic expansion markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese precision-engineering corridors where metrology certification commands 15-20% hardware premiums, while Indian manufacturing zones compete on unit economics at 40% below those benchmarks. This asymmetry fragments procurement patterns across fleet conversion timelines.
India
Maharashtra's municipal bus operators and Gujarat's industrial logistics fleets anchor Asia-Pacific dispenser procurement under the PLI scheme for alternative fuels. The CEA mandates grid-interconnected electrical infrastructure at all new stations, bundling power systems with dispenser procurement. Ahmedabad's pipeline-connected CNG corridor generates the densest station deployment in the subcontinent.
Germany
The EU F-Gas Regulation on sealed compressor systems forces refrigerant-containment upgrades across legacy refueling infrastructure. KBA vehicle-type approval requirements for CNG commercial vehicles standardize nozzle-receptacle interfaces. The Rhine-Ruhr industrial belt hosts pre-emptive station modernization programs ahead of enforcement windows.
United States
EPA emission standards for medium- and heavy-duty vehicles compress diesel-to-CNG conversion timelines for municipal fleets. California Air Resources Board zero-emission mandates create hybrid procurement rules favoring near-zero natural gas engines. The Central Valley agricultural corridor generates seasonal demand spikes from harvest fleet conversions.
Japan
METI hydrogen-blending roadmaps force recalibration investments across existing CNG pipeline networks. JIS pressure-equipment standards filter import access to pre-certified dispenser architectures. The Nagoya-Tokyo industrial corridor pilots hydrogen-adaptive dispenser installations at integrated energy stations.
China
MIIT dual carbon goals accelerate fleet electrification while preserving CNG as bridge fuel for heavy-duty logistics. GB standards for compressed natural gas fueling equipment mandate domestic metrology certification. The Sichuan-Chongqing shale gas basin anchors pipeline-connected station economics with sub-$3/MMBtu feedstock costs.
CNG Dispenser Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on flow-meter and valve assembly supply. The vendor base stratifies between full-service station contractors and modular hardware fabricators. Two archetypes dominate: service-network anchors leveraging long-term maintenance contracts, and manufacturing-scale suppliers optimizing unit costs for price-sensitive procurement. Competitive moves center on predictive-service subscription models and backward integration into Coriolis meter production.
Among North American platform integrators, Dover Fueling Solutions and Gilbarco Veeder-Root represent the service-density archetype, anchoring multi-year station contracts through maintenance-network reach. Censtar Science & Technology exemplifies the manufacturing-scale tier, occupying a position optimized for high-volume Asia-Pacific corridor supply. These three sit within distinct competitive vectors rather than direct overlap.
| Leading Market Players |
|---|
| Gilbarco Veeder-Root |
| Dover Fueling Solutions |
| Bennett Pump Company |
| Censtar Science & Technology |
| FTI International Group |
| Kraus Global |
| Lanfeng Machinery |
| Tatsuno Corporation |
| Scheidt & Bachmann |
| Others |
Supply Flow & Price Mechanics
Gujarat's specialty stainless steel foundries and high-pressure valve assembly clusters anchor upstream supply concentration, feeding margin pools downstream toward Coriolis meter integrators and digital architecture suppliers who capture technology premiums.
Pricing Analysis
Configured-to-order pricing for Coriolis-integrated digital dispensers commands substantial premiums over standard mechanical-meter units. Three-tier pricing structure across premium, standard, and economy levels stratifies by metrology certification grade and after-sales service bundling. Cost compression in municipal procurement tiers is intensifying because India's BIS certification bottlenecks filter access to pre-qualified vendors. Public transportation agencies exhibit highest price sensitivity; integrated fleet-management platforms with predictive maintenance show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from Indian distributor networks and supply-chain finance facilities at Asia-Pacific stocking partners ease working capital constraints for mid-scale fabricators. Manufacturing concentration draws from Germany, Japan, and China for precision flow-meter components, with India emerging for final assembly. Stainless steel bar stock, ceramic pressure sensors, and high-pressure sealing elastomers constitute critical input dependencies. Single-source vulnerability sits with Coriolis meter calibration equipment suppliers. Distribution runs through manufacturer-direct contracting for large fleets and regional distributors for independent stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as hydrogen-blending roadmaps force recalibration investments across installed CNG infrastructure, extending replacement timelines and upgrade service revenue.
For Market Incumbents: Entrench service-network density through predictive-maintenance subscription contracts that lock in fleet-card authentication integration. Deepen backward integration into Coriolis meter production to defend against component-supplier margin capture. Battery-electric bus procurement in European municipalities threatens CNG conversion velocity; anchor long-term station contracts with availability-based payment structures in India's Gujarat industrial belt.
For New Entrants and Emerging Players: Build out mobile and portable dispenser configurations for temporary construction fleets and emergency pipeline-interruption coverage where incumbent presence remains thin. Agricultural vehicle conversions in India's grain-producing states offer penetrable white-space with seasonal demand spikes tied to harvest financing. Pursue value-added reseller partnerships that bundle installation and BIS certification services.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed service-network anchors holding long-term municipal maintenance contracts but lacking digital architecture capabilities. Five-to-ten year viability hinges on hydrogen-adaptive dispenser technology positioning. Monitor METI hydrogen-blending ratio announcements and CEA grid-interconnection enforcement timelines as inflection indicators for upgrade-cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Coriolis Meter Backward Integration | Captive supply of temperature-compensated density sensors reduces reliance on German and Japanese precision-engineering corridors. |
| Hydrogen-Adaptive Flow-Control Development | Recalibrated algorithms and safety-cutoff thresholds position vendors for METI pipeline-blending roadmaps in Japan. |
| Predictive Maintenance Platform Launch | Remote diagnostics through embedded cellular modems enable subscription-based service contracts extending customer lifetime value. |
| CEA Grid-Interconnection Bundling | Power-dispenser procurement packages capture Indian station electrification mandates under integrated infrastructure contracts. |
| Cold-Climate Engineering Specialization | Frost-protection and flood-resistance specifications extend operational viability into northern European and high-altitude corridors. |
Methodological Framework
The analysis maps digital dispenser architectures, traditional mechanical systems, mobile configurations, and automated fuel-transfer platforms, each validated through station operators, fleet procurement managers, and aftermarket service heads. Primary interviews with municipal transit authority engineers, CNG station developers, and Coriolis meter calibration technicians combined with secondary validation from EPA emission standard filings, BIS certification registries, EU F-Gas Regulation compliance databases, and CEA grid-interconnection records. Bottom-up unit shipment tallies triangulate against top-down infrastructure investment flows.
Assumption sets held India's PLI scheme incentive levels and EU F-Gas enforcement windows fixed while varying hydrogen-blending adoption curves and battery-electric bus penetration rates. Segmentation dimensions modeled include product architecture, end-use intensity, installation environment, and procurement channel across the projection horizon. CAGRs derive from replacement-cycle velocity analysis and fleet conversion pipeline tracking. Industry-specific inputs incorporate CEA mandate compliance timelines and METI hydrogen roadmap milestones.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric platform vendors or hydrogen-dedicated infrastructure developers would shift outcomes. Macroeconomic deviation in stainless steel pricing, regulatory acceleration in F-Gas enforcement, or breakthroughs in solid-state hydrogen storage would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Coal Liquefaction Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
United States LNG Bunkering Market
Fuels
Hydrogen Cylinder Market
Fuels
High Octane Racing Fuel Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Methane Market
Fuels
Germany Bunker Fuel Market
Fuels
Storage Tank Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
South America Aviation Fuel Market
Fuels
North America Wood Pellet Market