
 Alcohol-To-Jet (ATJ) Fuel Market | 2026-2036
Alcohol-To-Jet (ATJ) Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol-To-Jet (ATJ) Fuel Market Outlook
Modular offtake contracts bundled with carbon intensity guarantees is recalibrating how airlines evaluate fuel procurement. LanzaJet leverages its integrated alcohol-to-jet technology platform to capture early-mover advantages in commercial-scale production. Gevo sustains a differentiated position through its focus on farm-to-flight supply chain control and lower-carbon corn ethanol feedstock. Honeywell UOP anchors the technology licensing segment with its proprietary catalytic conversion processes deployed across multiple continents.
Alcohol-to-jet fuel denotes a synthetic paraffinic kerosene produced via dehydration, oligomerization, and hydrotreating of alcohol feedstocks, meeting ASTM D7566 Annex A5 specifications for aviation turbine fuel blending. The process converts ethanol or other alcohols into drop-in hydrocarbons functionally identical to conventional jet fuel, enabling direct use in existing aircraft engines and infrastructure without modification. Ethanol feedstock dominates current production economics due to established agricultural supply chains, though butanol pathways attract R&D investment for superior energy density and cold-flow properties. Catalytic conversion technology leads commercial deployment, while hydrothermal liquefaction remains an emerging pathway with potential for lignocellulosic feedstock flexibility. Aviation fuel application commands the value pool, with marine fuel emerging as a secondary addressable market as International Maritime Organization regulations tighten.
The US Environmental Protection Agency administers renewable volume obligations under the Renewable Fuel Standard, while California's Air Resources Board enforces the Low Carbon Fuel Standard with declining carbon intensity benchmarks. The European Union's ReFuelEU Aviation mandate establishes binding sustainable aviation fuel blending requirements, creating cross-border compliance complexity for multinational carriers. ASTM International's D7566 standard and the Roundtable on Sustainable Biomaterials certification govern product quality and feedstock traceability, respectively. Stakeholders must monitor regulatory fragmentation between jurisdictions with divergent carbon accounting methodologies and certification schemes.
Market Dynamics
ASTM D7566 Annex A5 certification is compressing the commercialization timeline for alcohol-to-jet pathways, forcing producers to front-load capital deployment before offtake contracts mature.
Growth Catalysts
- California's Low Carbon Fuel Standard:Declining carbon intensity benchmarks create guaranteed premium pricing for certified ATJ producers serving West Coast aviation hubs.
- Ethanol supply chain density:Established corn ethanol infrastructure in the US Midwest reduces feedstock logistics costs for first-generation ATJ facilities.
- Commercial airline fleet renewal cycles:Major carriers are embedding sustainable aviation fuel commitments into new aircraft procurement specifications.
Market Restraints
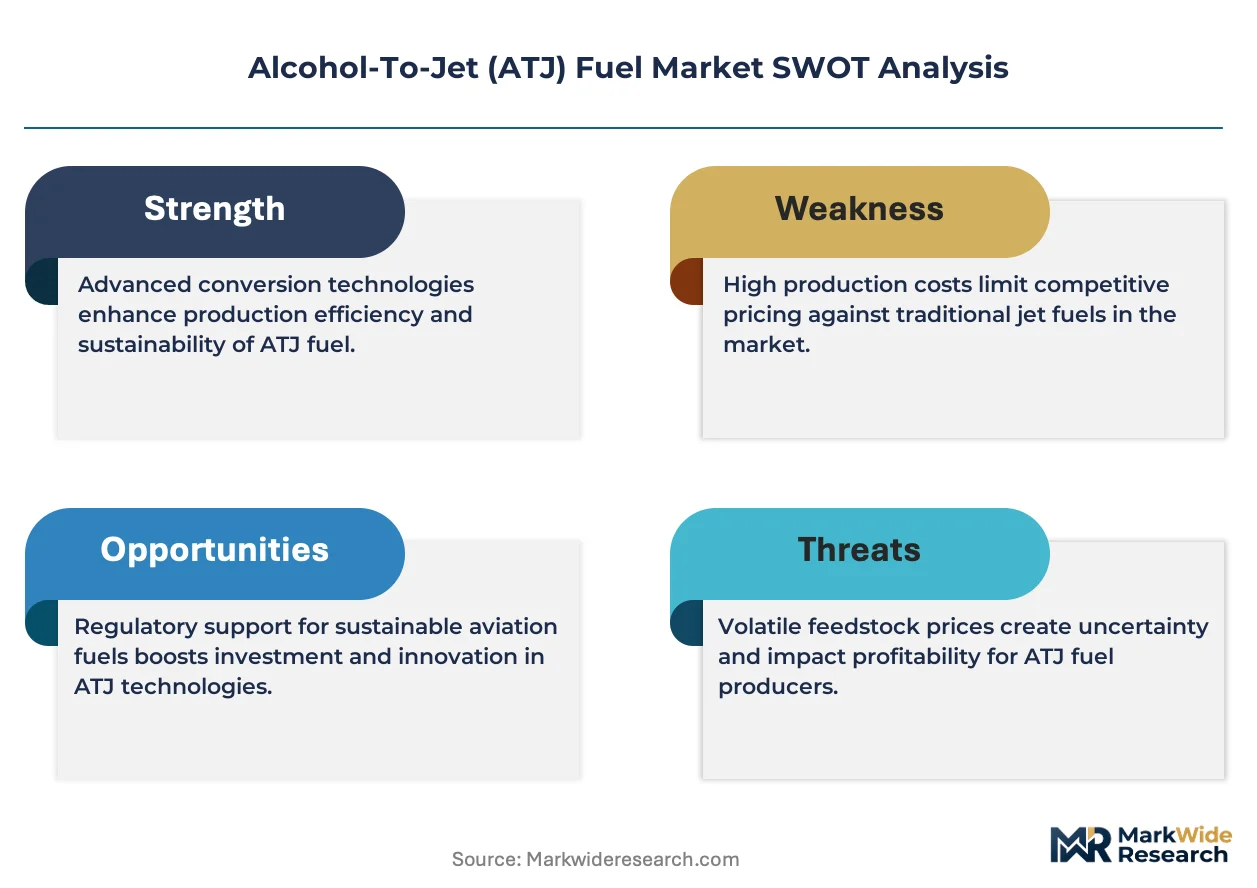
- Feedstock price volatility:Corn ethanol margins fluctuate with agricultural commodity cycles, compressing ATJ production economics during drought periods.
- Catalytic technology concentration:Proprietary hydroprocessing catalysts remain controlled by a limited pool of specialty chemical licensors.
- Hydrogen supply bottlenecks:Renewable hydrogen for hydrotreating stages faces production deficits in regions without electrolyzer infrastructure.
Strategic Opportunities
- Butanol pathway development:Superior cold-flow properties open military aviation and Arctic cargo routes currently inaccessible to ethanol-derived fuels.
- EU ReFuelEU Aviation mandate:Binding SAF blending requirements from 2025 create import demand for certified US production exceeding domestic European supply.
- Marine fuel co-production:IMO 2023 carbon intensity regulations position residual ATJ fractions as compliant bunker fuel for container shipping.
Industry Challenges
- ASTM certification timelines:Annex A5 qualification requires 12-18 months of engine testing, delaying revenue generation for new production facilities.
- Alcohol purification standards:Jet-grade specifications demand water content below 50 ppm, necessitating capital-intensive molecular sieve systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol-To-Jet (ATJ) Fuel Market |
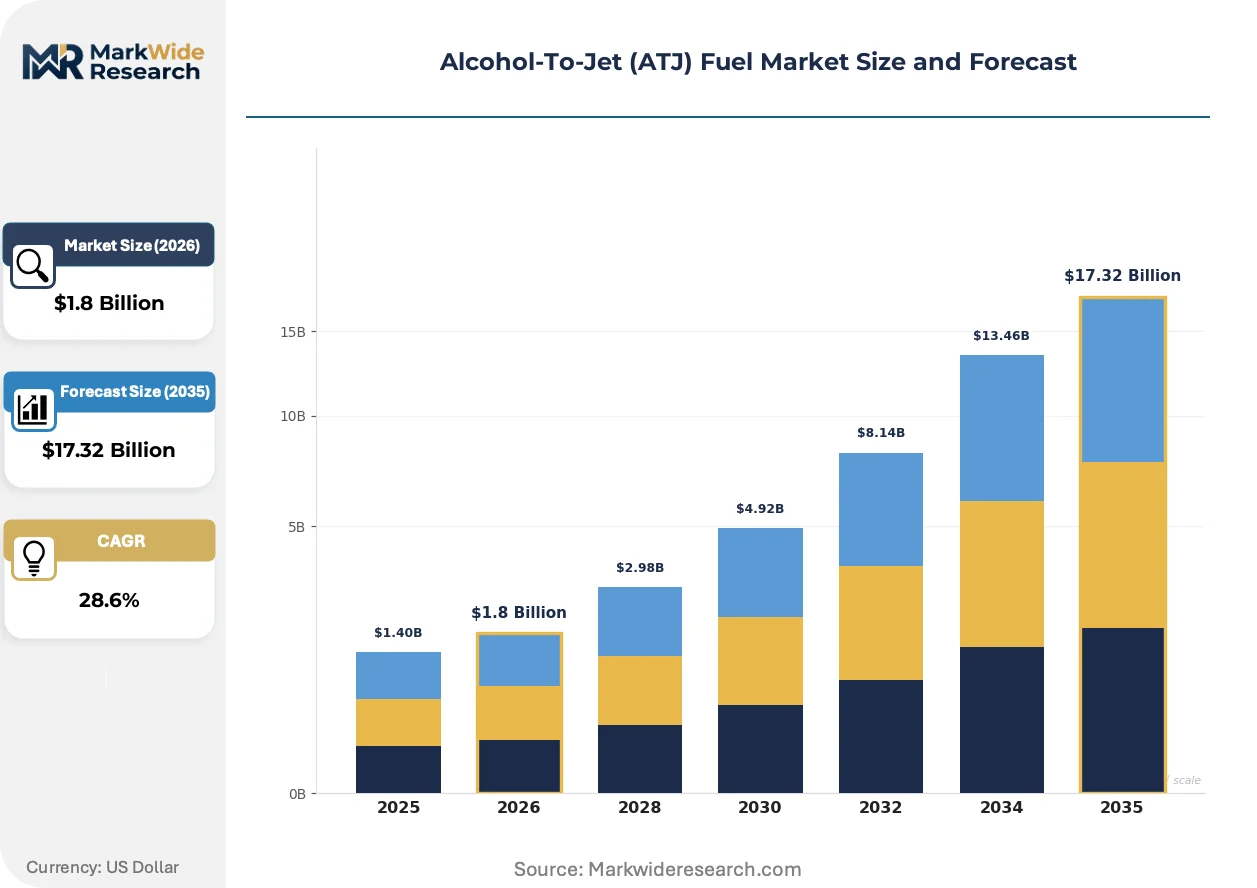
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Ethanol, Butanol, Methanol, Propanol Production Technology: Catalytic Conversion, Fermentation, Gasification, Hydrothermal Liquefaction Application: Aviation Fuel, Marine Fuel, Ground Transportation, Power Generation Distribution Channel: Direct Supply, Wholesale, Partnerships, Online Sales |
| Companies Covered | LanzaJet, Gevo, Honeywell UOP, SkyNRG, TotalEnergies, ExxonMobil, Neste, Fulcrum BioEnergy, Byogy Renewables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol-To-Jet (ATJ) Fuel Market Strategic Shifts
Process intensification and modular reactor designs are collapsing the minimum efficient scale for ATJ production, enabling distributed manufacturing at smaller ethanol hub locations.
Catalytic membrane reactors are electrifying the dehydration-oligomerization sequence by integrating electrochemical hydrogen management with traditional thermochemical conversion. LanzaJet's Freedom Pines facility is deploying this hybrid architecture to reduce external hydrogen dependency. The technology is compressing capital intensity per barrel of installed capacity by eliminating standalone hydrogen production units.
The US Environmental Protection Agency's renewable volume obligation pathways for cellulosic biofuel are tightening eligibility criteria for ethanol feedstocks. Producers must now demonstrate greenhouse gas reductions exceeding 60% versus petroleum baseline to qualify for premium credit generation. This is forcing ATJ developers toward corn kernel fiber and agricultural residue inputs rather than starch-based ethanol.
Airline procurement departments are consolidating fuel purchasing through multi-year offtake agreements bundled with carbon intensity guarantees. These contracts displace spot-market buying at major hub airports and transfer price volatility risk to fuel producers. The shift is most visible among US network carriers operating transcontinental routes subject to California's LCFS compliance obligations.
Alcohol-To-Jet (ATJ) Fuel Market Segmentation
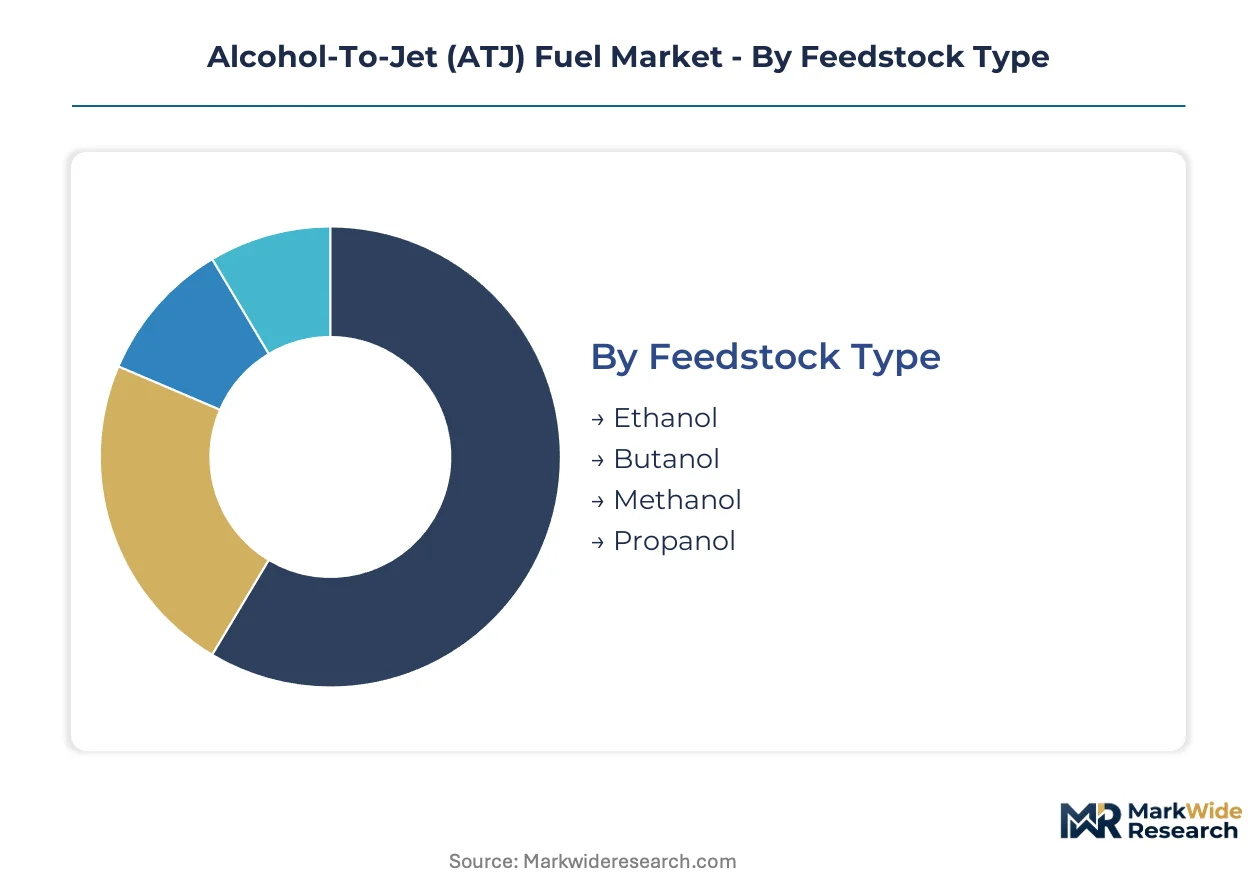
ATJ fuel segmentation reveals how feedstock economics, conversion technology maturity, and end-use certification requirements stratify commercial opportunity. Producers must align segment-specific production configurations with distinct regulatory pathways and offtake contract structures.
Feedstock Type:
Volume concentration favors established agricultural supply chains, while premium pricing attaches to lower-carbon intensity alternatives.
- Ethanol:Corn-derived ethanol dominates current production economics through established Midwest supply infrastructure. ASTM D7566 Annex A5 certification timelines align with ethanol pathway commercialization, anchoring demand at US aviation hubs subject to California LCFS compliance.
- Butanol:Superior energy density and cold-flow properties enable military aviation and Arctic route applications inaccessible to ethanol-derived fuels. Cellulosic butanol pathways attract R&D investment for 60% GHG reduction thresholds under EPA renewable volume obligations.
- Methanol:Coal-to-methanol and biomass gasification routes serve Chinese domestic SAF pilots under dual carbon policy frameworks.
- Propanol:Niche fermentation pathways from sugarcane residues concentrate in Brazilian biofuel clusters seeking ANP aviation certification.
Mature deployment sits with ethanol. Newer deployment is concentrated in butanol.
Production Technology:
Technology selection determines capital intensity, hydrogen integration requirements, and feedstock flexibility boundaries.
- Catalytic Conversion:Proprietary hydroprocessing and oligomerization catalysts from Honeywell UOP and Axens dominate commercial-scale deployment. Dehydration-oligomerization-hydrotreating sequences achieve ASTM D7566 compliance with established process guarantees.
- Hydrothermal Liquefaction:Wet biomass processing avoids drying costs for lignocellulosic feedstocks. Pilot facilities in the Netherlands and Canada test agricultural residue conversion at sub-commercial scales.
- Fermentation:Engineered yeast strains convert sugars to longer-chain alcohols for direct catalytic upgrading. Gevo's South Dakota facility integrates fermentation with proprietary separation technology.
- Gasification:Syngas-to-alcohol routes enable municipal solid waste and forestry residue feedstocks. Commercial viability depends on carbon capture integration for negative-emission fuel claims.
Commercial maturity clusters with catalytic conversion. Technology diversification is accelerating in hydrothermal liquefaction.
Application:
End-use certification requirements and carbon accounting methodologies segment addressable value pools.
- Aviation Fuel:Drop-in synthetic paraffinic kerosene meets ASTM D7566 blending specifications for commercial turbine engines. US network carriers embed multi-year offtake agreements into fleet renewal procurement.
- Marine Fuel:Residual ATJ fractions serve IMO 2023 carbon intensity regulations for container shipping. Rotterdam and Singapore bunkering hubs test alcohol-derived marine gasoil acceptance.
- Ground Transportation:Heavy-duty trucking trials in California evaluate ATJ as renewable diesel alternative under LCFS credit generation.
- Power Generation:Turbine combustion testing for grid-balancing peaker plants explores alcohol-derived distillate compatibility.
Revenue concentration remains with aviation fuel. Regulatory momentum is building fastest in marine applications.
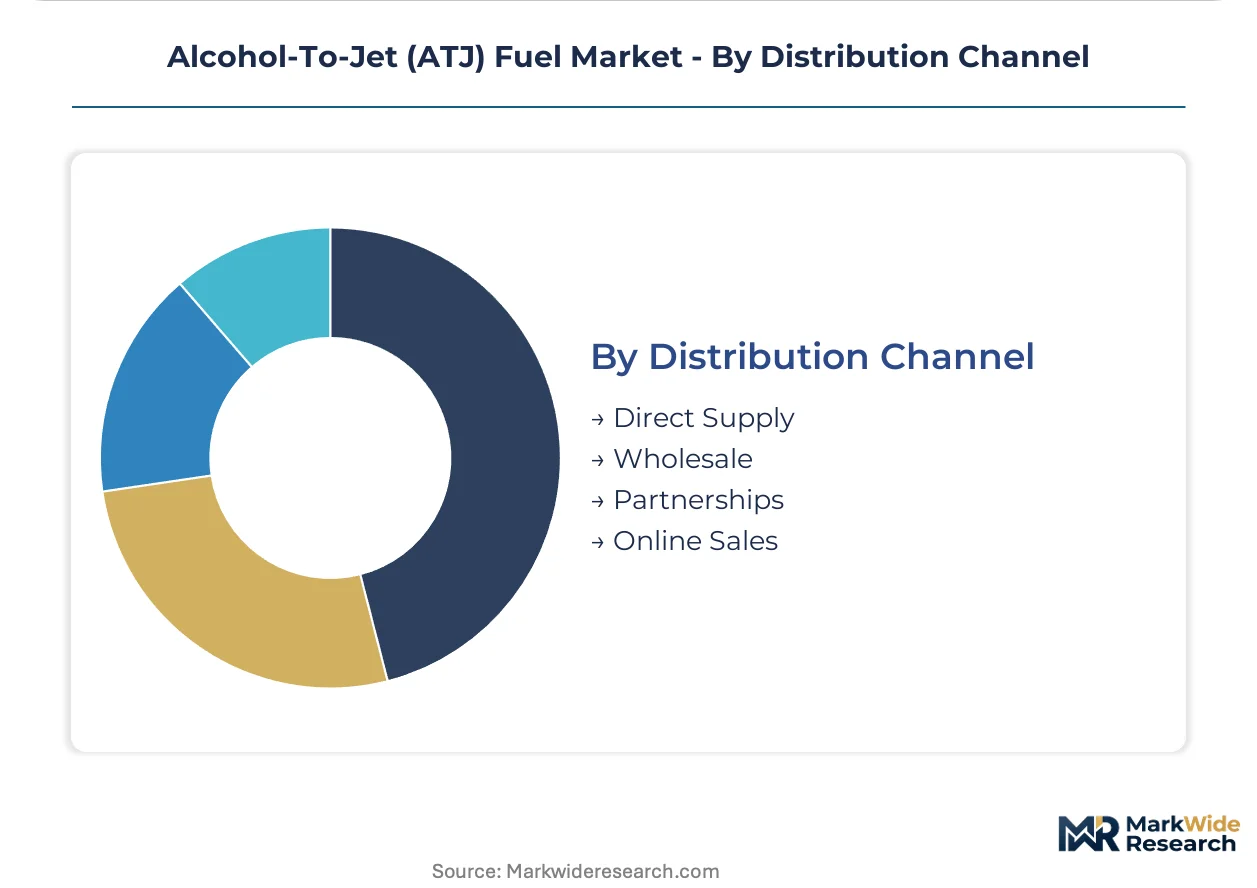
Distribution Channel:
Contract structure and price risk allocation differentiate channel economics for producers and buyers.
- Direct Supply:Integrated offtake agreements between ATJ producers and individual airlines transfer price volatility risk to fuel suppliers. United Airlines and Delta Air Lines have executed 10-20 year purchase commitments with carbon intensity guarantees.
- Partnerships:Strategic alliances with oil majors leverage existing jet fuel logistics infrastructure and airport hydrant systems. Shell and BP partnerships enable ATJ injection into conventional supply chains without dedicated handling equipment.
- Wholesale:Spot market intermediation serves regional carriers and cargo operators with variable volume requirements.
- Online Sales:Digital procurement platforms facilitate small-volume transactions for corporate aviation and private jet operators seeking voluntary carbon reduction claims.
Contract maturity concentrates in direct supply. Channel experimentation is expanding through partnership structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in the United States while consumption demand spreads across jurisdictions with binding sustainable aviation fuel mandates. This geographic disconnect is reshaping trade flows and certification requirements for alcohol-to-jet fuel suppliers.
United States
Commercial airlines at Los Angeles and San Francisco international airports anchor procurement volumes under California's Low Carbon Fuel Standard. The EPA's renewable volume obligations for cellulosic biofuel tighten feedstock eligibility criteria nationwide. LanzaJet's Freedom Pines Fuels facility in Georgia represents the first commercial-scale ATJ production site serving domestic aviation hubs.
Netherlands
Rotterdam's bunkering infrastructure positions the port as a testing ground for alcohol-to-jet marine fuel applications under International Maritime Organization regulations. The EU's ReFuelEU Aviation mandate creates import demand for certified US production exceeding domestic European supply. Shell's partnership structures enable ATJ injection into conventional jet fuel logistics at Schiphol Airport.
United Kingdom
Heathrow and Gatwick airports drive SAF procurement specifications among British Airways and Virgin Atlantic fleet operators. The UK Jet Zero Council coordinates blending mandate timelines with ASTM D7566 certification requirements. Oxfordshire-based research clusters test catalytic membrane reactor technologies for distributed production economics.
Japan
Tokyo's Haneda and Narita airports face supply security pressures under the country's dual carbon policy framework. METI coordinates demonstration projects linking domestic ethanol producers with international technology licensors. Osaka-based engineering groups evaluate butanol pathway development for military aviation cold-flow requirements.
Brazil
Sugarcane ethanol clusters in São Paulo state seek ANP aviation certification for propanol pathway commercialization. Embraer's regional jet manufacturing base creates captive demand for drop-in synthetic paraffinic kerosene testing. The country's national biofuel regulator evaluates ASTM alignment for export market access.
Alcohol-To-Jet (ATJ) Fuel Market Competitive Environment
The competitive structure tilts toward integrated technology-platform operators rather than pure-play fuel merchants. Proprietary catalytic conversion capabilities and multi-year airline offtake contracts define tier differentiation. Three archetypes dominate: ethanol-to-jet specialists with farm-to-flight supply chain control, technology licensors monetizing hydroprocessing catalysts, and oil majors leveraging existing jet fuel infrastructure. Capacity expansion and strategic partnerships with airport logistics operators represent the dominant competitive moves.
Among technology-integrated developers, LanzaJet, Gevo, and Honeywell UOP anchor distinct positioning vectors. LanzaJet exemplifies the commercial-scale production archetype through its integrated alcohol-to-jet platform. Gevo occupies a position emphasizing feedstock supply chain control and lower-carbon intensity corn ethanol pathways. Honeywell UOP represents the technology licensing tier with proprietary catalytic processes deployed across multiple continents. These three entities collectively illustrate how competitive advantage in ATJ fuel concentrates at the intersection of feedstock security, conversion technology ownership, and certification timeline acceleration.
| Leading Market Players |
|---|
| LanzaJet |
| Gevo |
| Honeywell UOP |
| SkyNRG |
| TotalEnergies |
| ExxonMobil |
| Neste |
| Fulcrum BioEnergy |
| Byogy Renewables |
| Others |
Value Chain & Pricing Dynamics
Catalytic membrane reactor deployment at LanzaJet's Freedom Pines facility is collapsing hydrogen integration costs while concentrating production capacity in the US Southeast. This technology shift simultaneously reduces per-barrel capital intensity and reinforces geographic supply clustering around established ethanol hub infrastructure.
Pricing Analysis
Cost-down pressure on ethanol-derived ATJ accelerates because EPA renewable volume obligations now demand 60% GHG reduction thresholds for premium credit generation. Three-tier pricing structure across certified low-carbon, standard corn ethanol, and transitional feedstock tiers reflects carbon intensity scoring and ASTM D7566 Annex A5 qualification status. Price differentiation hinges on LCFS credit stacking eligibility in California and offtake contract duration. Regional carriers with spot-market exposure exhibit highest price sensitivity, while network carriers with multi-year carbon-intensity-guaranteed contracts absorb premiums.
Supply Chain Analysis
California's Low Carbon Fuel Standard and EU ReFuelEU Aviation mandates are reshaping feedstock sourcing toward domestic-content-compliant agricultural residues. Supply concentrates in the United States, Brazil, and the Netherlands, with corn ethanol infrastructure anchoring US Midwest feedstock security. Proprietary hydroprocessing catalysts from Honeywell UOP and Axens, renewable hydrogen for hydrotreating stages, and ASTM-certified molecular sieve purification systems constitute critical input dependencies. Single-source vulnerability sits with specialty catalyst licensors controlling oligomerization-hydrotreating sequences. Distribution runs through integrated offtake agreements with major airlines and oil-major partnership structures leveraging existing airport hydrant systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alcohol-to-jet fuel markets are transitioning from pilot-scale fermentation pathways to commercial catalytic conversion platforms, with membrane reactor electrification displacing standalone hydrogen production units.
For Market Incumbents: Deepen captive ethanol supply control through corn kernel fiber processing investments that secure EPA cellulosic biofuel credit eligibility. Accelerate ASTM D7566 Annex A5 certification timelines to lock in multi-year offtake contracts before butanol pathway competitors achieve cold-flow property parity. Threat concentration sits with emerging hydrothermal liquefaction developers accessing lignocellulosic feedstocks outside established agricultural commodity cycles. For New Entrants and Emerging Players: Military aviation operators requiring Arctic route cold-flow performance represent an underserved buyer archetype currently dependent on petroleum-derived Jet A-1 with additives. Cellulosic butanol pathways targeting 60% GHG reduction thresholds open procurement channels at USAF and NATO fuel specifications inaccessible to ethanol-derived competitors. Marine fuel bunkering at Rotterdam and Singapore offers secondary market entry with lower certification barriers than commercial aviation. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-platform acquisitions by oil majors seeking integrated SAF production capabilities rather than pure-play fuel merchants. Long-term viability favors developers with simultaneous feedstock security, proprietary catalytic conversion ownership, and contracted offtake coverage exceeding facility nameplate capacity. Watch for EPA renewable volume obligation pathway revisions tightening corn starch eligibility as inflection signal for cellulosic feedstock valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | LanzaJet's Freedom Pines expansion anchors US domestic ATJ production scale. |
| Backward Integration | Gevo's farm-to-flight corn supply control secures LCFS credit generation eligibility. |
| Technology Licensing | Honeywell UOP's catalytic process deployment spans multiple continental production sites. |
| Long-term Supply Agreement | United and Delta offtake contracts transfer price volatility risk to fuel producers. |
| Green Certification Program | RSB certification enables EU ReFuelEU Aviation mandate compliance for US exports. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with ATJ production facility managers, airline fuel procurement directors, EPA renewable fuel standard compliance officers, and oil-major partnership executives combined with FAA certification tracking, EPA renewable volume obligation pathway documentation, EIA biofuel production statistics, and ASTM International standards databases. Bottom-up facility capacity modeling and top-down mandate-driven demand estimation provided triangulation validation.
Segment-level granularity modeled feedstock type, production technology, and application dimensions across the projection horizon. Catalytic conversion deployment rates, ethanol hub infrastructure proximity, and LCFS credit price trajectories informed volume and value outputs. CAGRs derived from facility commissioning timelines, airline fleet renewal cycles, and regulatory mandate phase-in schedules. Hydrogen supply constraints and ASTM certification queue durations represented key forecast sensitivity inputs.
Revisions become necessary when EPA renewable volume obligation eligibility criteria tighten beyond current cellulosic thresholds, when EU ReFuelEU Aviation import acceptance rules diverge from ASTM D7566 frameworks, or when catalytic membrane reactor scale-up encounters unanticipated hydrogen management inefficiencies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Singapore Bunker Fuel Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Fuel Oil Market
Fuels
Underground Coal Gasification Market
Fuels
Europe Bunker Fuel Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
India LNG Market
Fuels
City Gas Distribution Market
Fuels
Diesel Fuel Water Separator Market
Fuels
LPG Tanker Market
Fuels
Tire Derived Fuel Market
Fuels
Oil & Gas Lubricants Market
Fuels
North America Wood Pellet Market
Fuels
Global Industrial Burner Market
Fuels
India Liquified Petroleum Gas (LPG) Market