
 Solid Fuel Tablet Market | 2026-2036
Solid Fuel Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Fuel Tablet Market Insights
Outdoor recreation enthusiasts are redrawing demand patterns in the solid fuel tablet landscape. Esbit leverages its German manufacturing heritage to sustain premium positioning across European camping channels. Coghlan's Ltd. competes aggressively in North American retail through mass-market distribution partnerships. Hexamine Chemical Company anchors industrial-grade supply relationships with defense contractors requiring consistent burn-rate specifications.
Solid fuel tablets are compressed combustible blocks formulated from hexamine, naphthalene, or biomass derivatives, engineered to deliver controlled thermal output without liquid fuel spillage risks. Wood-based formulations currently dominate consumer retail shelves due to perceived environmental compatibility and lower particulate emissions during combustion. Military applications command premium pricing tiers because defense procurement mandates exacting ignition reliability and storage stability under extreme climates. Synthetic variants represent the fastest-growing product category as manufacturers reformulate to meet tightening volatile organic compound restrictions across multiple jurisdictions.
EPA standards govern permissible emissions from camping and heating fuels sold in the United States, while REACH regulates chemical substance registration and hazard communication throughout European supply chains. The EU F-Gas Regulation indirectly pressures solid fuel alternatives by restricting fluorinated greenhouse gases in comparable heating applications. Stakeholders must monitor evolving combustion emissions thresholds and material safety data sheet requirements to preserve market access across jurisdictions.
Market Dynamics
REACH and EPA emissions mandates are compressing permissible chemical formulations while NATO defense procurement sustains premium demand for hexamine-based tablets with exacting burn-rate specifications.
Growth Catalysts
- Military Field Operations:Defense procurement agencies across NATO member states are expanding stockpiles of hexamine-based solid fuel tablets for expeditionary missions requiring ignition reliability in extreme climates.
- REACH Chemical Reformulation:European manufacturers are accelerating R&D into low-VOC synthetic variants to preserve market access under tightening ECHA hazard communication requirements.
- Wood-Based Biomass Derivatives:Outdoor retailers are expanding shelf space for compressed cellulose formulations as campers prioritize perceived environmental compatibility over synthetic alternatives.
Market Restraints
- Hexamine Feedstock Concentration:Industrial-grade hexamine supply concentrates among a limited cohort of chemical manufacturers, exposing procurement costs to input volatility and single-source risk.
- Biomass Combustion Efficiency Gap:Wood-based tablets exhibit lower thermal output density and inconsistent ignition performance compared to synthetic hexamine formulations, limiting substitution in technical applications.
- EPA Volatile Organic Compound Limits:United States emissions standards for camping fuels are tightening permissible chemical compositions, forcing reformulation investments that compress margins on legacy product lines.
Strategic Opportunities
- Carbon-Neutral Certification Pathways:EU Green Deal procurement incentives are creating preferential purchasing channels for solid fuel tablets with verified lifecycle carbon accounting and sustainable sourcing documentation.
- Emergency Preparedness Retail:Disaster relief agencies and civilian preparedness retailers represent an underpenetrated channel for long-shelf-life fuel tablet stockpiles beyond traditional camping and military segments.
- Biomass-Synthetic Hybrid Formulations:Converging compression technologies and binding agents are enabling next-generation tablets that combine wood-based feedstocks with controlled burn-rate additives.
Industry Challenges
- Combustion Chemist Talent Scarcity:Formulation expertise spanning both traditional hexamine chemistry and emerging biomass pyrolysis remains concentrated among a narrow cohort of specialists, constraining R&D velocity.
- REACH Registration Timelines:Novel chemical binders and ignition accelerants face multi-year ECHA evaluation periods that delay product commercialization and compress competitive windows.
- Defense Specification Integration:Meeting NATO STANAG requirements for storage stability and climatic performance demands capital-intensive testing infrastructure that smaller manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Fuel Tablet Market |
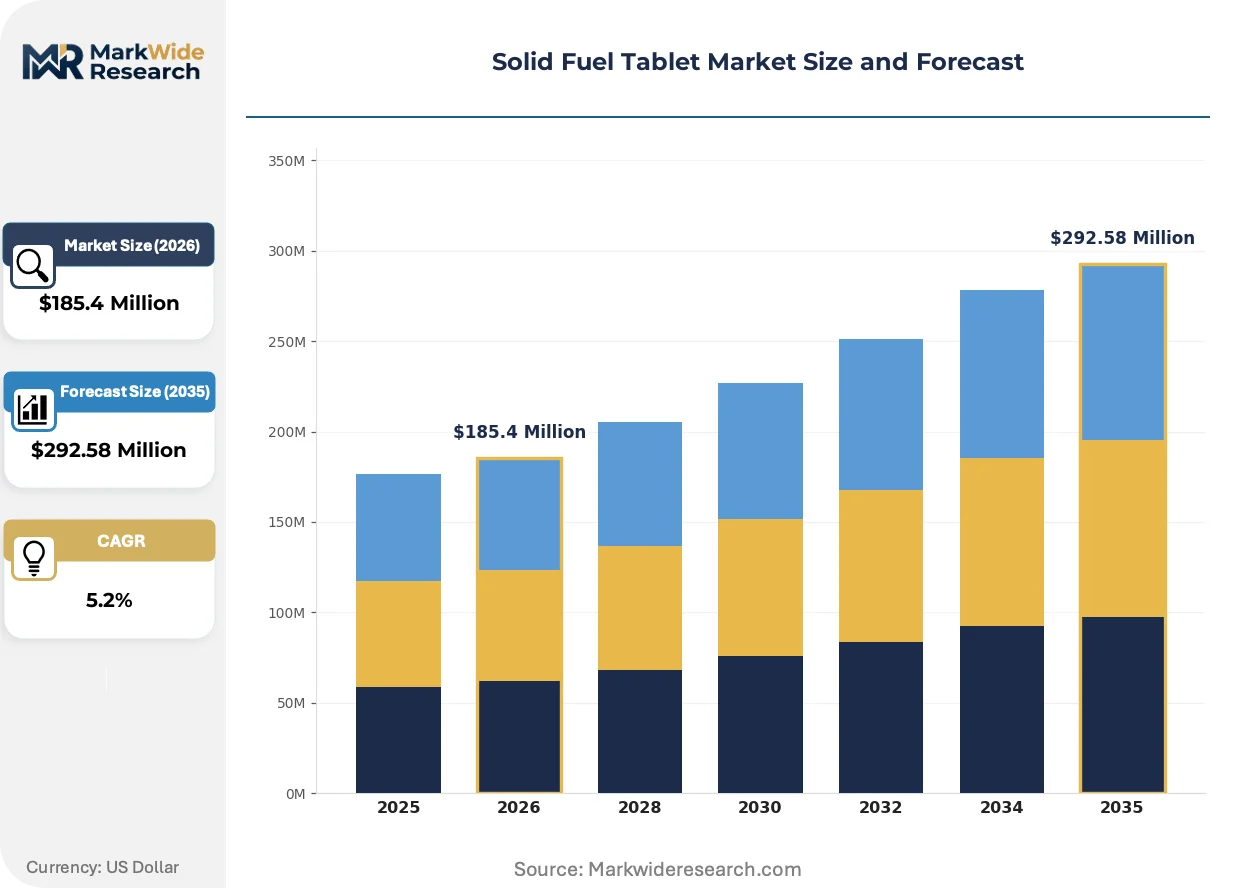
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $292.58 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood-Based, Biofuels, Coal, Synthetic Application: Camping, Cooking, Heating, Military End User: Household, Commercial, Industrial, Outdoor Recreation Packaging Type: Boxes, Pouches, Tubs, Bulk |
| Companies Covered | Esbit, Coghlan's Ltd., Hexamine Chemical Company, Eveready, Falcon Safety Products, Cyalume Technologies, Royal Wick, Strike First, Ti-Union Solid Fuel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Fuel Tablet Market Trends and Innovations
Formulation chemistry and procurement specifications are diverging sharply as regulatory pressure on synthetic compounds accelerates parallel innovation in biomass-derived alternatives and hybrid compression techniques.
Biomass pyrolysis residue formulations are supplanting naphthalene-based tablets in European consumer channels. Outdoor retailers in Germany and Scandinavia are rotating inventory toward compressed wood-derived blocks with certified lower particulate emissions. This transition is compressing shelf space for legacy synthetic variants while rewarding manufacturers with established cellulose supply chains.
EPA emissions standards for camping and heating fuels are tightening testing protocols for volatile organic compound release during combustion. United States distributors are demanding reformulated product lines with documented compliance certificates before renewing annual supply agreements. Military procurement remains partially exempt from these thresholds, preserving a bifurcated regulatory environment.
Defense agencies are consolidating volume commitments under multi-year framework contracts rather than spot purchasing. Bundeswehr procurement offices in Germany are negotiating captive supply arrangements directly with manufacturers possessing NATO qualification status. This concentration is visible across NATO member states and is compressing competitive access for non-qualified suppliers.
Solid Fuel Tablet Market Segmentation
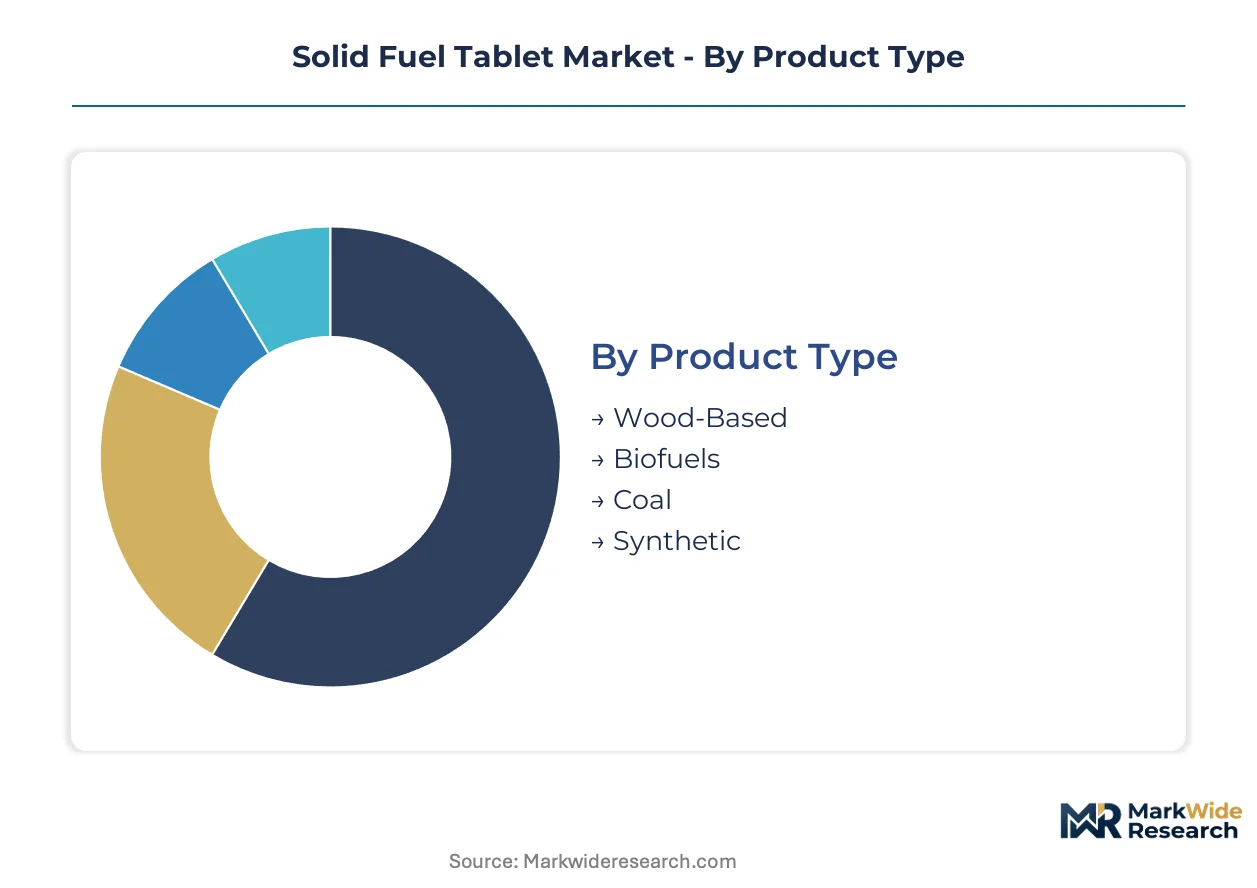
Solid fuel tablet manufacturers navigate divergent technical specifications across defense procurement, consumer retail, and industrial heat applications. Segmentation reveals how formulation chemistry and packaging economics partition competitive access across these channels.
Product Type:
REACH and EPA emissions thresholds are fragmenting permissible chemistries, compressing synthetic formulations while elevating biomass alternatives in regulated jurisdictions.
- Wood-Based:Compressed cellulose blocks derived from sawdust and lignin binders deliver moderate thermal output with lower particulate emissions. German and Scandinavian outdoor retailers are rotating inventory toward these formulations as campers prioritize environmental compatibility and ECHA hazard communication compliance.
- Synthetic:Hexamine-based tablets engineered for exacting ignition reliability and storage stability command premium pricing tiers. NATO defense procurement mandates these specifications for expeditionary missions, insulating this segment from consumer-facing emissions restrictions.
- Biofuels:Pyrolysis residue and agricultural waste derivatives.
- Coal:Anthracite-based compressed blocks for industrial heat applications.
Synthetic formulations handle the majority of defense throughput; wood-based alternatives are climbing the fastest on retail share.
Application:
Volume concentration diverges sharply between civilian recreation and institutional procurement channels with incompatible performance requirements.
- Military:Expeditionary fuel tablets must satisfy NATO STANAG climatic performance standards and multi-year shelf-life specifications. Bundeswehr procurement offices negotiate captive supply arrangements directly with qualified manufacturers, compressing competitive access for non-certified suppliers.
- Camping:Recreational users prioritize portability and ease-of-ignition over thermal precision. North American mass-market retailers are expanding private-label shelf space for wood-based tablets as EPA volatile organic compound testing protocols tighten.
- Cooking:Emergency preparedness and humanitarian relief applications.
- Heating:Supplementary warmth in off-grid and disaster scenarios.
Military applications dominate value capture; camping represents the steepest expansion trajectory in unit volume.
End User:
Customer procurement sophistication ranges from spot retail purchases to multi-year framework contracts with embedded qualification requirements.
- Outdoor Recreation:Individual campers and backpacking enthusiasts purchase through specialty retailers and e-commerce channels. Demand concentrates in Germany and Scandinavia where environmental certification influences purchasing decisions.
- Industrial:Heat-treatment and foundry operations requiring consistent burn-rate specifications.
- Household:Emergency preparedness stockpiling and supplementary heating.
- Commercial:Restaurants, catering, and hospitality applications.
Outdoor recreation channels move the highest unit volumes; industrial procurement delivers the most stable contract terms.
Packaging Type:
Logistics economics and shelf-life requirements dictate format selection across distribution tiers with varying moisture protection needs.
- Boxes:Cardboard packaging with foil-lined compartments dominates European retail. Esbit's German manufacturing heritage leverages this format for premium positioning across camping channels.
- Bulk:Defense agencies and disaster relief organizations procure palletized quantities without retail packaging. NATO framework contracts specify vacuum-sealed bulk configurations with humidity indicators.
- Pouches:Lightweight flexible packaging for backpacking applications.
- Tubs:Reusable plastic containers for household emergency stockpiles.
Bulk packaging handles institutional procurement volume; pouches are gaining share fastest in ultralight recreation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for solid fuel tablets, handling bulk hexamine feedstock shipments and finished product exports to NATO defense networks across the continent.
Germany
Bundeswehr procurement offices in Koblenz and Berlin drive institutional demand through multi-year framework contracts. ECHA REACH registration requirements force domestic manufacturers to maintain exhaustive material safety documentation. Esbit's headquarters in Hamburg secures captive supply arrangements with defense agencies while distributing premium camping formulations through specialty retailers nationwide.
United States
EPA volatile organic compound testing protocols are compressing permissible chemical compositions for consumer-facing products. The Department of Defense maintains partial exemption from emissions thresholds, preserving bifurcated regulatory treatment. Wisconsin-based mass-market distributors are rotating inventory toward wood-based tablets as private-label shelf space expands.
United Kingdom
Ministry of Defence procurement through Defence Equipment and Support sustains premium demand for NATO-qualified hexamine tablets. The UK's post-Brexit chemicals regulatory framework retains REACH alignment through retained EU law. Coghlan's distribution partnerships with major outdoor retailers concentrate demand in the Southeast and Midlands camping corridors.
China
Ti-Union Solid Fuel and domestic chemical manufacturers supply industrial-grade hexamine to global defense contractors. GB standards for chemical product safety govern export certification requirements. Manufacturing clusters in Zhejiang and Shandong provinces handle compression and packaging for international private-label contracts.
France
ANSM and CNIL oversight of chemical hazard communication adds compliance layers for imported tablet formulations. The Direction Générale de l'Armement procures expeditionary fuel stocks for African and Middle Eastern deployments. Lyon-based outdoor retailers are expanding biomass tablet shelf space ahead of stricter EU Green Deal procurement incentives.
Solid Fuel Tablet Market Competitive Landscape
Listed leaders compete with private specialists across qualification status and channel access. The vendor base concentrates among German heritage manufacturers, North American mass-market distributors, and Chinese industrial chemical suppliers. Three archetypes dominate: NATO-certified defense contractors, premium outdoor heritage brands, and private-label industrial formulators. Consolidation is accelerating through captive supply arrangements and multi-year framework contract concentration.
Within the heritage manufacturer tier, Esbit exemplifies premium positioning anchored in German manufacturing lineage. Coghlan's Ltd. occupies the mass-market distribution archetype through North American retail partnerships. Hexamine Chemical Company represents the industrial-grade supplier category with defense contractor relationships. These three entities illustrate how qualification status, channel strategy, and feedstock control separate competitive positions in a market where regulatory compliance and procurement relationships matter more than price.
| Leading Market Players |
|---|
| Esbit |
| Coghlan's Ltd. |
| Hexamine Chemical Company |
| Eveready |
| Falcon Safety Products |
| Cyalume Technologies |
| Royal Wick |
| Strike First |
| Ti-Union Solid Fuel |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at German hexamine production facilities shapes both procurement cost floors and supplier bargaining power across NATO defense contracts. Scale economies in synthetic formulation compress unit economics for qualified manufacturers while biomass alternatives face feedstock fragmentation that elevates price variability at lower volumes.
Pricing Analysis
Volume-discount tiering separates NATO framework contracts from spot retail purchases with pronounced margin differentiation. Pricing stratifies across military-grade hexamine, certified camping formulations, and unbranded biomass tablets based on burn-rate certification and shelf-life guarantees. Cost compression in consumer-facing synthetic lines is intensifying because EPA volatile organic compound testing demands reformulation investments. Mass-market outdoor retailers exhibit highest price sensitivity; defense procurement offices prioritize performance consistency over unit cost.
Supply Chain Analysis
Germany and China anchor hexamine feedstock production and tablet compression manufacturing respectively. Industrial-grade hexamine supply draws from Zhejiang and Shandong province chemical clusters while German facilities handle NATO-qualified finishing and packaging. Single-source vulnerability concentrates in hexamine precursor supply among a limited cohort of chemical manufacturers. Distribution runs through Hamburg for European defense networks and Wisconsin-based mass-market distributors for North American retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid fuel tablet demand sits in early-cycle expansion as emergency preparedness stockpiling penetrates civilian households beyond traditional camping and military segments.
For Market Incumbents: Shield market position through captive supply arrangements with Bundeswehr procurement offices and accelerated REACH registration for novel low-VOC binders. Backward integration into hexamine precursor production mitigates feedstock concentration risk from Chinese chemical manufacturers. Certification investment in NATO STANAG qualification preserves defense channel access against emerging biomass-synthetic hybrid competitors. For New Entrants and Emerging Players: Anchor in emergency preparedness retail as the most penetrable white-space channel beyond saturated camping and defense segments. Civilian disaster relief agencies and preparedness retailers represent underexploited demand for long-shelf-life stockpiles. Direct-to-consumer e-commerce with carbon-neutral certification documentation offers a defensible go-to-market angle against entrenched heritage brands. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among NATO-qualified defense contractors with multi-year framework contracts and captive supply arrangements. Long-term viability favors manufacturers with dual-track capabilities spanning both synthetic hexamine and biomass-derived formulations. Watch for REACH registration timeline acceleration as the inflection signal indicating regulatory clarity that unlocks R&D commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Acceleration | ECHA approval for novel binders preserves market access under tightening emissions thresholds. |
| Backward Integration into Hexamine | In-house precursor production reduces exposure to Chinese chemical manufacturer concentration. |
| NATO STANAG Qualification Investment | Defense certification unlocks multi-year framework contracts with premium pricing tiers. |
| Biomass-Synthetic Hybrid Development | Converging compression technologies address both EPA limits and thermal performance gaps. |
| Emergency Preparedness Channel Expansion | Disaster relief procurement diversifies revenue beyond cyclical camping demand. |
Research Methodology
Desk research of customs trade data, ECHA registration databases, and defense procurement disclosures preceded structured interviews with Bundeswehr procurement officers, camping retail category managers, and hexamine chemical plant managers. Secondary validation drew from NATO STANAG documentation, EPA emissions testing protocols, and EU Green Deal procurement incentive frameworks. Bottom-up demand modeling triangulated against top-down production capacity estimates across German and Chinese manufacturing clusters.
Variance decomposition across product type, application, and end-user segments shaped analytical framework construction throughout the forecast period. Modeled dimensions included formulation chemistry tier, procurement channel structure, packaging format, and regional regulatory cluster. CAGRs were derived from segment-level volume trajectories weighted by pricing tier contributions. Forecast inputs incorporated REACH registration pipeline velocity and defense framework contract renewal cycles.
Material uncertainties — regulatory timeline slippage, hexamine feedstock price volatility, and biomass combustion performance gaps — sit outside the modeled envelope. Forecasts reflect assumptions regarding ECHA evaluation period durations and NATO procurement continuity. Recalibration cycles align with material shifts in emissions threshold announcements and defense budget allocation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Bunker Fuel Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Australia Coal Market
Fuels
Bituminous Coal Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Europe Coal Market
Fuels
Mobile Fuel Delivery Market
Fuels
Hydrogen Fuel Tanks Market
Fuels
LPG Gas Cylinder Market
Fuels
Hydrogen Cylinder Market
Fuels
White Coal Market
Fuels
North America LNG Bunkering Market
Fuels
Underground Coal Gasification Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Gasoline Market
Fuels
LPG Tanker Market