
 Europe Proton Therapy Market | 2026-2036
Europe Proton Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Proton Therapy Market Insights
France is fragmenting proton therapy capacity across multiple public hospital clusters rather than concentrating installations in single national centers. IBA Worldwide leverages its cyclotron manufacturing base in Louvain-la-Neuve to sustain equipment supply chains across the continent. Elekta AB competes through software-integrated treatment planning systems that anchor multi-vendor proton sites. Varian Medical Systems differentiates via rotating gantry architectures that dominate new European installations.
Proton therapy delivers precisely targeted radiation using accelerated proton beams that deposit maximum energy at the Bragg peak, sparing adjacent healthy tissue during cancer treatment. The clinical purpose centers on treating pediatric cancers, ocular tumors, and skull-base lesions where photon toxicity risks exceed therapeutic margins. Synchrotron-based systems occupy the premium tier due to beam energy flexibility, while cyclotron configurations lead installation volume across mid-sized European centers. Active scanning delivery modes are displacing passive scattering as the default clinical standard, concentrating margin pools in pencil-beam scanning software and real-time imaging integration.
EMA oversight of proton therapy devices intersects with national health technology assessment bodies in France, Germany, and Italy to shape reimbursement and market access timelines. The EU MDR and CE marking requirements are forcing extended conformity documentation for particle beam systems, extending procurement cycles for hospital buyers. Stakeholders must monitor HTA divergence between European markets to anticipate which proton center business models achieve sustainable reimbursement.
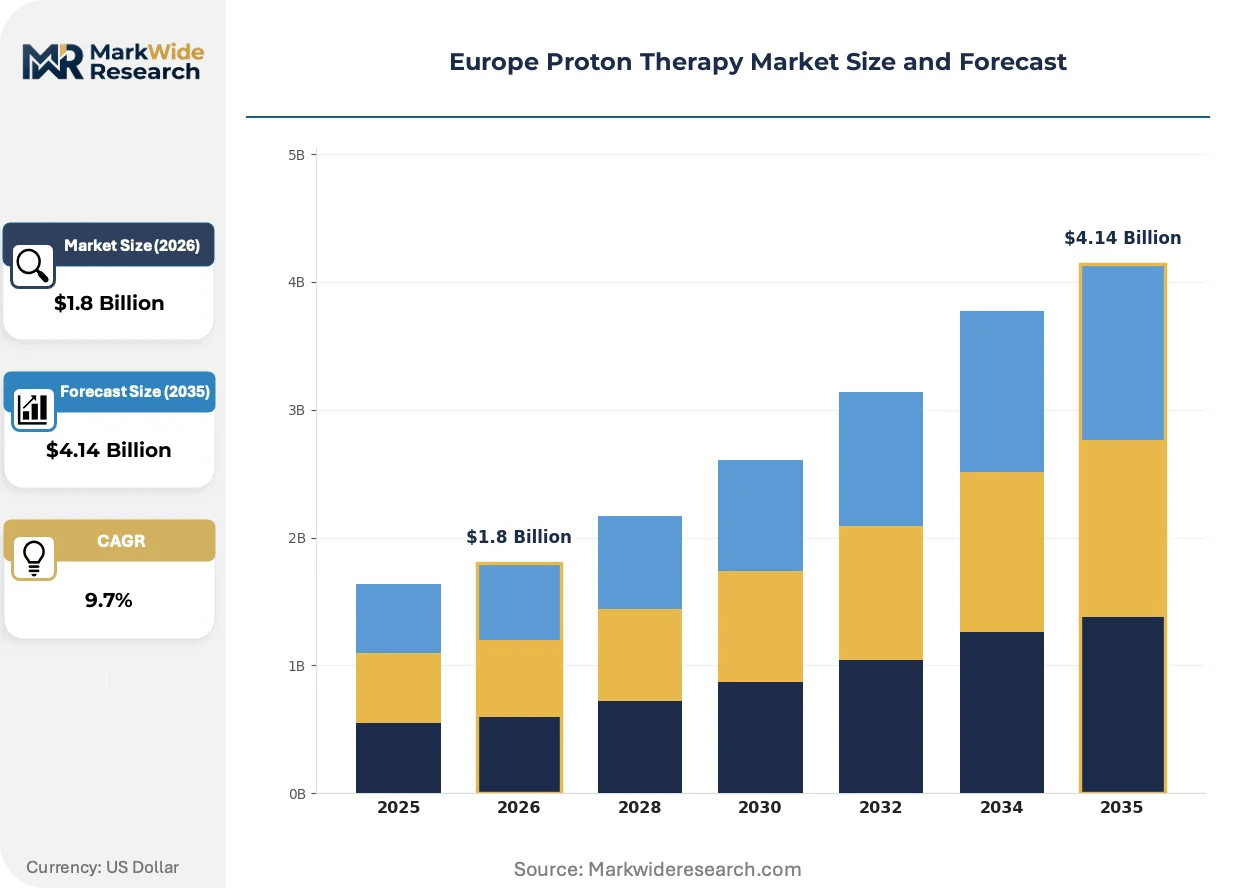
Market Dynamics
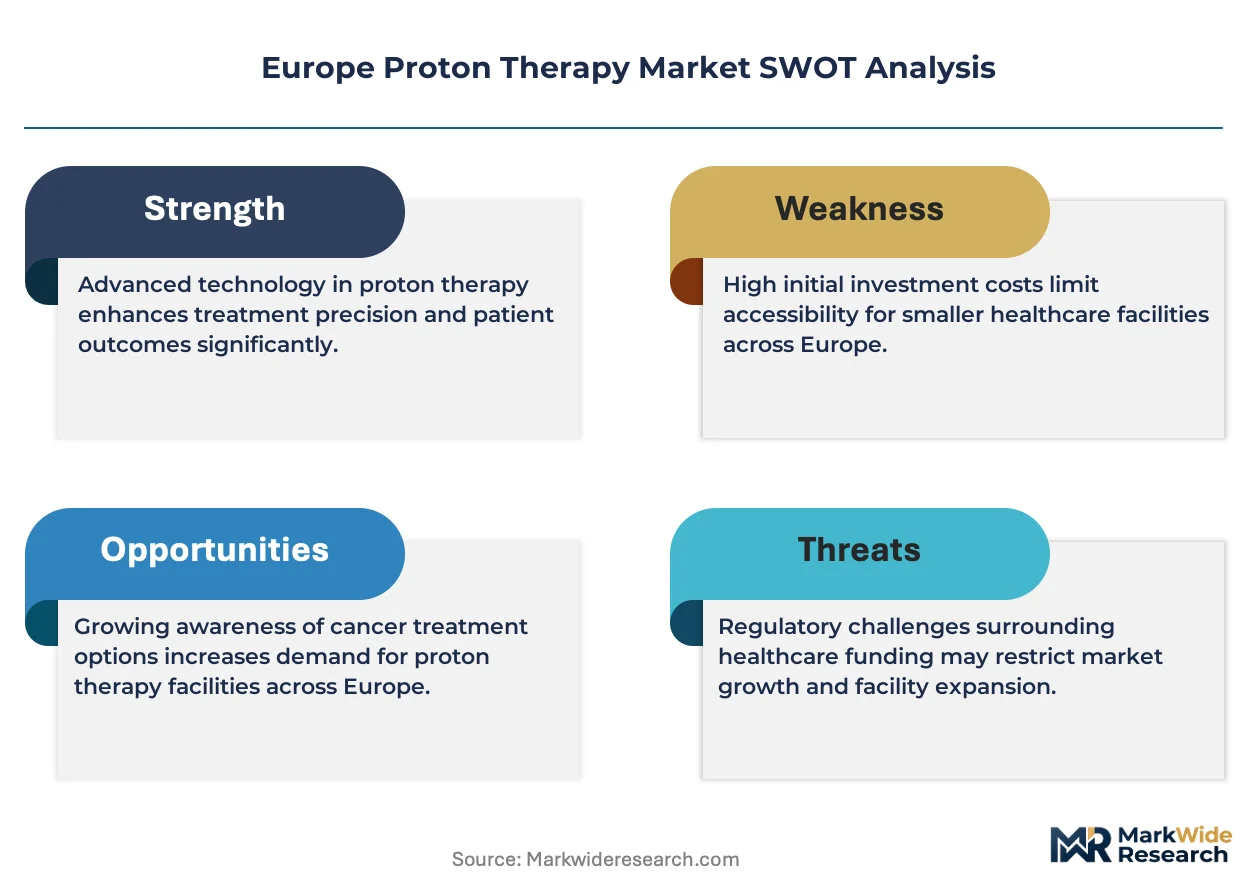
The EU MDR is compressing proton therapy equipment procurement timelines as hospitals navigate extended CE marking documentation for particle beam systems, forcing vendors to front-load regulatory investment before commercial deployment.
Growth Catalysts
- Bragg peak precision:Pediatric oncology departments across Germany and France are prioritizing proton protocols for craniospinal treatments where photon scatter risks permanent cognitive damage in developing tissue.
- Active scanning displacement:Pencil-beam scanning software is displacing passive scattering as the default clinical standard, concentrating investment in real-time imaging integration and motion management systems.
- EMA-HTA convergence:France's HAS and Germany's IQWiG are aligning evidence requirements for proton reimbursement, reducing duplicative clinical trials for cross-border patient access.
Market Restraints
- Synchrotron cost concentration:Premium-tier beam energy flexibility requires superconducting magnet supply chains concentrated in Swiss and German specialty manufacturers, creating input bottlenecks.
- Site preparation intensity:Concrete shielding specifications for gantry vaults demand 3-meter-thick walls that extend hospital construction timelines beyond typical radiation oncology buildouts.
- Cyclotron footprint rigidity:Fixed-energy beam delivery limits treatment protocol expansion compared to synchrotron alternatives, constraining mid-sized centers to narrower indication sets.
Strategic Opportunities
- Italian network gaps:Milan and Rome hospital clusters lack proton capacity relative to cancer incidence density, creating first-mover positioning for equipment vendors with established EMA device files.
- Ocular melanoma protocols:Dedicated eye treatment lines using horizontal fixed beams are penetrating Dutch and Belgian centers where patient volumes justify specialized workflow investments.
- Carbon ion convergence:Heidelberg's dual proton-carbon facility is demonstrating technical pathways for cyclotron vendors to expand beam species without full synchrotron replacement.
Industry Challenges
- Medical physics workforce gaps:Commissioning proton centers requires certified clinical physicists with particle beam dosimetry training, a specialization scarce outside Heidelberg, Manchester, and Paris training pipelines.
- Legacy linac integration:Proton vaults must interoperate with existing photon treatment planning networks, forcing middleware development for multi-vendor software environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Proton Therapy Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Cyclotron, Synchrotron, Beamline, Treatment Planning System Application: Cancer, Benign Tumors, Pediatric, Neurological Disorders End User: Hospitals, Research Institutes, Cancer Treatment Centers, Specialty Clinics Delivery Mode: Passive Scattering, Active Scanning, Fixed Beam, Rotating Gantry |
| Companies Covered | IBA Worldwide, Advanced Oncotherapy plc, Elekta AB, Hitachi Ltd., Mevion Medical Systems, Varian Medical Systems, Sumitomo Heavy Industries Ltd., Optivus Proton Therapy, ProNova Solutions, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Proton Therapy Market Trends and Innovations
Digital twin architectures are virtualizing treatment delivery verification, compressing the gap between simulated dose distributions and actual patient outcomes across European proton networks.
Adaptive planning software is virtualizing the traditional fraction-by-fraction static protocol. University hospitals in Munich and Groningen are deploying daily CT-guided replanning for head-and-neck cases where tumor shrinkage alters beam paths mid-treatment. This capability is compressing margin expansion practices that previously compensated for anatomical uncertainty.
The EU MDR's clinical evaluation requirements are forcing particle therapy vendors to maintain post-market surveillance registries that track real-world device performance. Manufacturers must now submit periodic safety updates to EMA-notified bodies, extending quality management system obligations across the full equipment lifecycle. German university hospitals are responding by consolidating vendor contracts with suppliers demonstrating established MDR technical documentation.
Hospital procurement departments are unbundling equipment purchase from long-term service agreements, separating capital expenditure approval from operational maintenance budgeting. This pattern is visible in French public hospital clusters where regional purchasing cooperatives negotiate cyclotron supply independently from multi-year software support contracts. The shift is compressing vendor margin structures while accelerating competitive bidding for aftermarket services.
Europe Proton Therapy Market Segmentation
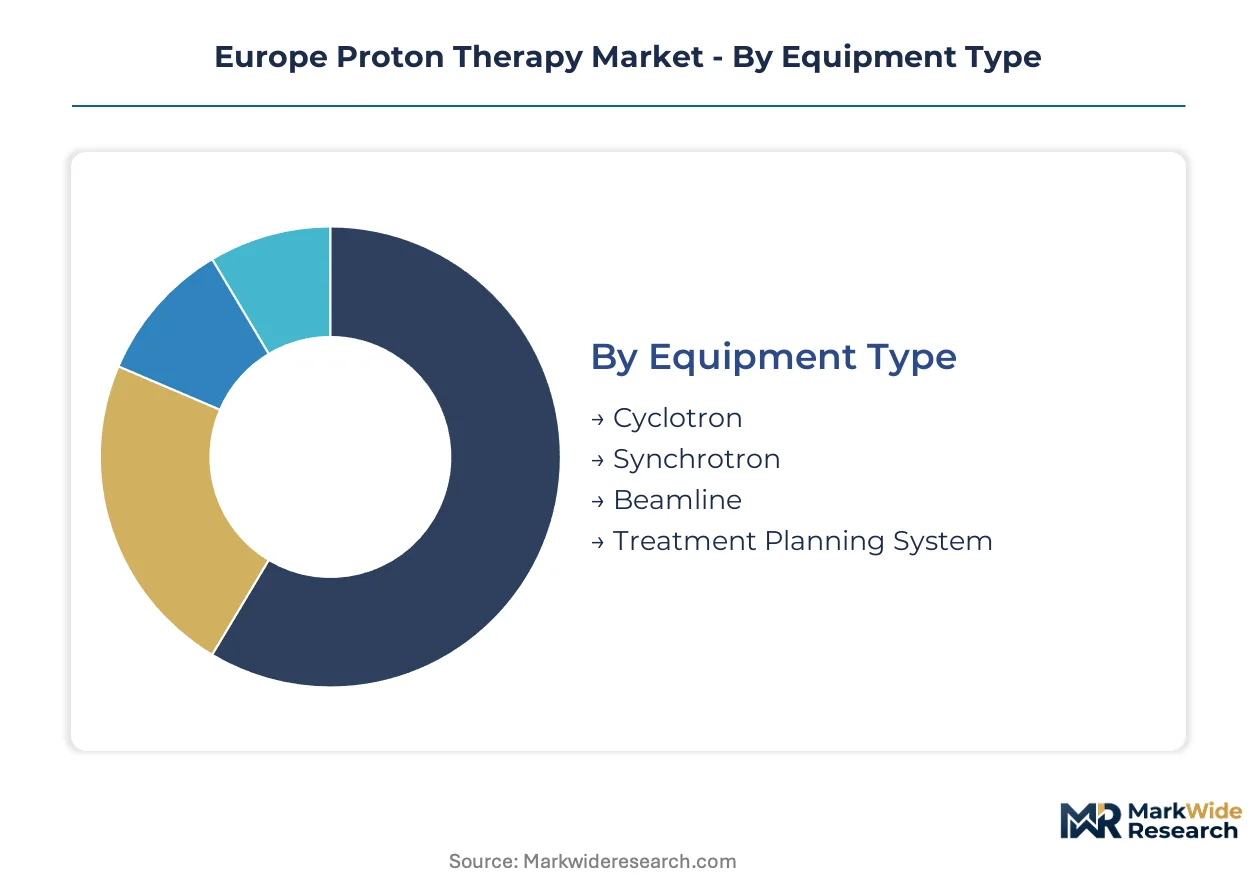
Proton therapy market segmentation reveals how clinical requirements, infrastructure constraints, and reimbursement pathways shape purchasing decisions across European healthcare systems. Equipment configurations and delivery modes determine center capabilities, while application focus dictates referral patterns and revenue sustainability.
Equipment Type:
Equipment configurations span the full use-case spectrum from compact single-room installations to multi-gantry academic medical centers serving complex protocols.
- Cyclotron:Fixed-energy proton acceleration systems dominate mid-sized European hospital installations due to footprint efficiency and lower shielding requirements. Demand concentrates in French and Italian regional cancer centers where IQWiG-style cost-effectiveness thresholds constrain capital budgets, though beam energy rigidity limits expansion into ocular melanoma protocols requiring horizontal fixed beams.
- Synchrotron:Variable-energy beam delivery enables full-spectrum treatment protocols including carbon ion expansion. Heidelberg and Manchester university hospitals anchor demand for superconducting magnet configurations, though Swiss and German specialty manufacturer bottlenecks extend procurement timelines beyond cyclotron alternatives.
- Beamline:Transport optics and energy selection systems connect acceleration sources to treatment delivery nozzles.
- Treatment Planning System:Software platforms integrating CT/MRI simulation with Monte Carlo dose calculation anchor vendor differentiation in multi-equipment environments.
The dominant share belongs to Cyclotron, while Synchrotron is closing the gap fastest as carbon ion capabilities expand.
Application:
Clinical indication focus determines reimbursement coding, referral network design, and required beam delivery specifications across European markets.
- Cancer:Solid tumor protocols in head-and-neck, lung, and gastrointestinal malignancies constitute the volume base for operational sustainability. German oncology departments prioritize craniospinal treatments where Bragg peak precision reduces secondary malignancy risk in long-term survivors.
- Pediatric:Developing tissue sensitivity to photon scatter drives proton prioritization for craniospinal irradiation and medulloblastoma protocols. HAS in France and IQWiG in Germany have aligned evidence requirements, accelerating cross-border patient access for cases where cognitive preservation outweighs cost differentials.
- Benign Tumors:Arteriovenous malformations and acoustic neuromas in skull-base locations benefit from steep dose gradients.
- Neurological Disorders:Epilepsy and functional targets require sub-millimeter precision achievable with active scanning integration.
Cancer commands the installed base, though Pediatric is expanding most quickly as national reimbursement frameworks mature.
End User:
Facility type determines capital allocation authority, patient volume assumptions, and integration requirements with existing radiation oncology infrastructure.
- Hospitals:University medical centers in Munich, Groningen, and Paris coordinate proton programs with comprehensive cancer center designation, leveraging EMA-aligned HTA pathways for device procurement. These institutions anchor multi-gantry installations serving both clinical trials and routine care.
- Cancer Treatment Centers:Dedicated oncology facilities concentrate proton capacity in high-incidence regions without full academic medical center overhead.
- Research Institutes:Beamline access for radiobiology and detector development supports clinical translation pipelines.
- Specialty Clinics:Ocular-focused centers in Dutch and Belgian markets deploy horizontal fixed beams for uveal melanoma.
Hospitals retain the dominant position, while Cancer Treatment Centers are gaining share fastest as regional networks proliferate.
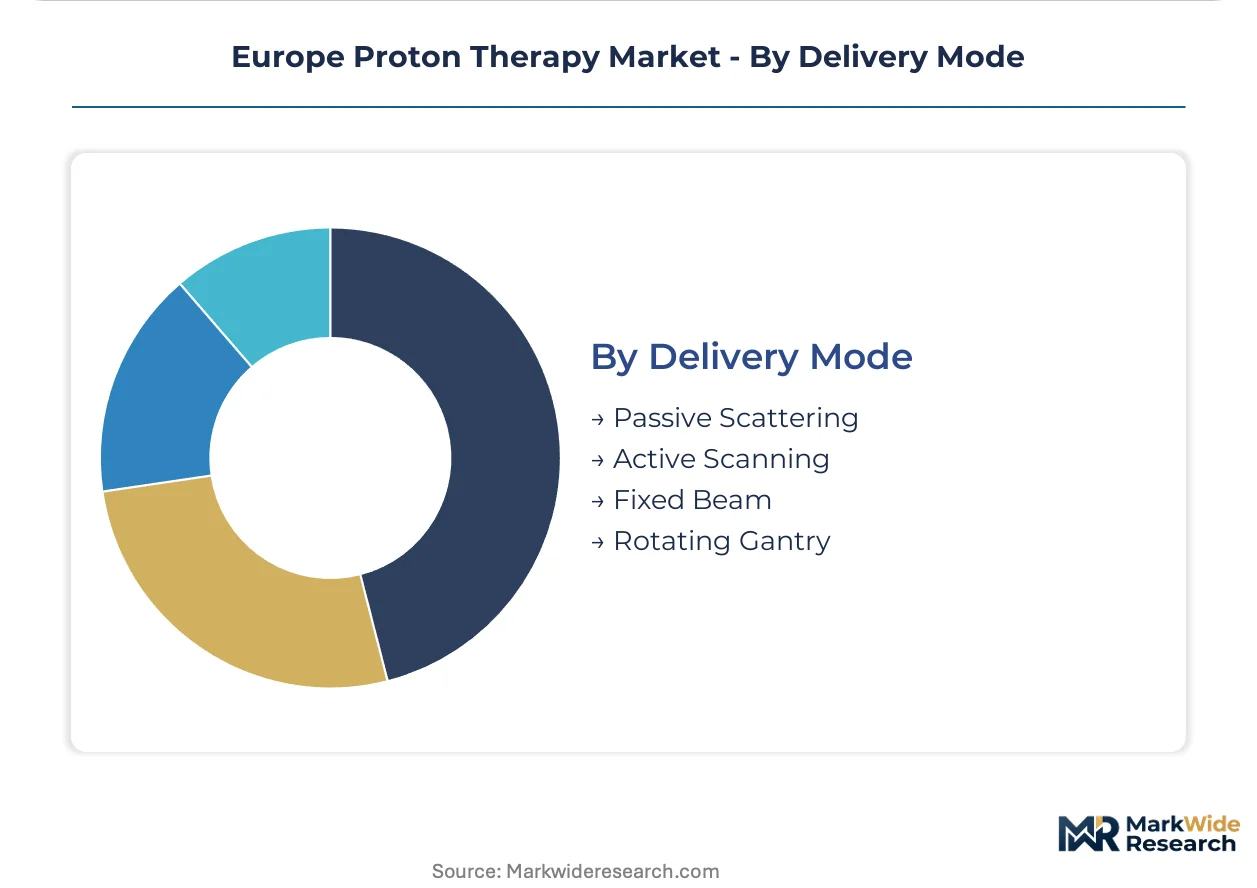
Delivery Mode:
Beam application methods determine dose conformity, treatment time, and compatibility with motion management for thoracic and abdominal targets.
- Active Scanning:Pencil-beam scanning with real-time imaging integration enables intensity-modulated proton therapy with superior conformality to complex tumor geometries. Munich and Groningen university hospitals are deploying daily CT-guided replanning capabilities that compress margin expansion practices.
- Rotating Gantry:Isocentric beam delivery from multiple angles reduces skin entrance dose and enables non-coplanar treatment arrangements.
- Passive Scattering:Historical default using modulator wheels and compensators retains installed base in early-adopter centers.
- Fixed Beam:Horizontal and vertical room configurations serve ocular, cranial, and research applications with mechanical simplicity.
Active Scanning leads new installations, while Rotating Gantry shows the steepest expansion trajectory as vault construction standardizes around 360-degree access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA oversight anchors proton therapy expansion across European markets, with national health technology assessment bodies determining reimbursement velocity for particle beam installations. University hospital clusters in Germany, France, and Italy coordinate procurement through CE marking pathways under the EU MDR framework.
Germany
IQWiG evidence requirements shape proton reimbursement for pediatric craniospinal protocols where Bragg peak precision reduces cognitive damage risk. The EU MDR extends conformity documentation timelines for Heidelberg and Munich university hospitals commissioning multi-gantry synchrotron facilities. Bavaria anchors clinical networks serving cross-border patients from Austria and Switzerland.
France
HAS alignment with German evidence standards accelerates cross-border access for pediatric oncology cases requiring proton prioritization. The EU MDR tightens post-market surveillance obligations for cyclotron vendors supplying regional cancer centers. Public hospital clusters in Paris and Lyon fragment capacity across multiple installations rather than concentrating in single national centers.
Italy
Milan and Rome hospital clusters exhibit proton capacity gaps relative to cancer incidence density, creating positioning opportunities for vendors with established EMA device files. Italy's national pharmaceutical regulator evaluates proton therapy within existing radiation oncology reimbursement frameworks. Northern Italian centers in Lombardy and Emilia-Romagna concentrate early adoption momentum.
Netherlands
Dedicated ocular treatment lines using horizontal fixed beams penetrate Dutch centers where uveal melanoma volumes justify specialized workflow investments. The EU MDR CE marking requirements extend procurement cycles for Amsterdam and Rotterdam university medical centers. Groningen anchors active scanning deployment with daily CT-guided replanning capabilities.
United Kingdom
NHS England commissioning frameworks restrict proton therapy to designated supra-regional centers in Manchester and London. The Medicines and Healthcare products Regulatory Agency enforces EU MDR-aligned conformity assessment for particle beam systems. Manchester University NHS Foundation Trust anchors the national proton program serving pediatric referrals from across England and Wales.
Europe Proton Therapy Market Competitive Landscape
Capability concentration sits with synchrotron specialists; scale advantage sits with cyclotron manufacturers serving mid-sized European centers. The vendor base organizes around three strategic archetypes: integrated equipment-service providers, software-anchored multi-vendor platforms, and compact system specialists targeting regional cancer networks. Competitive moves center on unbundling equipment purchase from long-term service agreements and consolidating MDR technical documentation capabilities.
Within the integrated equipment tier, IBA Worldwide leverages its Louvain-la-Neuve cyclotron manufacturing base to sustain supply chains across the continent. Elekta AB occupies a position anchoring software-integrated treatment planning systems for multi-vendor proton sites. Varian Medical Systems exemplifies the rotating gantry architecture approach that dominates new European installations.
| Leading Market Players |
|---|
| IBA Worldwide |
| Advanced Oncotherapy plc |
| Elekta AB |
| Hitachi Ltd. |
| Mevion Medical Systems |
| Varian Medical Systems |
| Sumitomo Heavy Industries Ltd. |
| Optivus Proton Therapy |
| ProNova Solutions |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Italian proton centers relative to cancer incidence density is compressing vendor pricing power while extending procurement timelines for beamline equipment. German university hospitals exploit this supply-demand asymmetry to negotiate unbundled service contracts that separate cyclotron capital expenditure from multi-year software maintenance budgets.
Pricing Analysis
Price spreads between German university medical centers and French regional hospital clusters reflect divergent HTA enforcement intensity, with IQWiG-style cost-effectiveness thresholds in Bavaria driving harder capital equipment negotiations than HAS-guided procurement in Paris public hospital networks. Three-tier pricing structure across premium synchrotron, standard cyclotron, and compact single-room installations stratifies by beam energy flexibility and gantry configuration. Cost compression in mid-sized cyclotron segments is intensifying because French regional purchasing cooperatives are consolidating vendor contracts around MDR technical documentation capabilities. Community cancer centers exhibit highest price sensitivity due to constrained capital budgets, while Heidelberg-style academic proton networks prioritize clinical protocol breadth over unit economics.
Supply Chain Analysis
Extended payment terms from Swiss and German superconducting magnet manufacturers are straining cyclotron vendor working capital cycles as hospital buyers defer commissioning milestones. Beamline optics concentrate in Swiss precision engineering clusters and German specialty manufacturers, while treatment planning software development anchors in Belgian and Swedish R&D centers. Superconducting magnet supply draws from niobium-titanium alloy feedstocks and cryogenic cooling system components concentrated in European precision manufacturing networks. Single-source vulnerability in superconducting coil winding capacity creates procurement bottlenecks for synchrotron facilities. Distribution runs through direct vendor-hospital contracting with EMA-notified body certification gates, bypassing traditional medical device distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from pencil-beam scanning software subscriptions and real-time imaging integration is expanding faster than hardware installation cycles, repositioning vendor economics toward recurring-revenue models. This structural shift favors players with established MDR technical documentation and post-market surveillance registry capabilities.
For Market Incumbents: Build regulatory documentation moats by front-loading EU MDR conformity investment for particle beam systems before commercial deployment. Consolidate vendor contracts with German university hospitals demonstrating established multi-year software support capabilities. Defend against emerging compact system specialists by anchoring multi-gantry academic medical center relationships that constrain mid-tier competitor access to high-volume referral networks. For New Entrants and Emerging Players: Establish a beachhead in Italian regional cancer centers where proton capacity gaps relative to cancer incidence density create first-mover positioning for vendors with EMA device files. Target Milan and Rome hospital clusters lacking synchrotron infrastructure. Penetrate through horizontal fixed beam configurations for ocular melanoma protocols, leveraging lower shielding requirements and faster site preparation timelines than full gantry installations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-anchored multi-vendor platform providers integrating Monte Carlo dose calculation with pencil-beam scanning delivery. Long-term viability over the projection horizon hinges on carbon ion expansion capabilities and adaptive planning software deployment. Acquisition focus should center on cyclotron manufacturers with established Louvain-la-Neuve-style manufacturing bases and EMA-aligned HTA pathways. Watch for inflection signals in Italian national reimbursement framework finalization for proton therapy.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Consolidation | Front-loaded regulatory investment accelerates CE marking timelines for particle beam systems across German procurement cycles. |
| Software-Integrated Treatment Planning | Monte Carlo dose calculation platforms anchor vendor differentiation in multi-equipment European proton environments. |
| Carbon Ion Capability Expansion | Heidelberg-style dual proton-carbon facilities demonstrate technical pathways for cyclotron vendors without full synchrotron replacement. |
| Regional Hospital Cluster Partnership | French public hospital cooperative purchasing fragments capacity across multiple installations, creating distributed demand pools. |
| Adaptive Planning Software Deployment | Daily CT-guided replanning capabilities in Munich and Groningen compress margin expansion practices for head-and-neck cases. |
Research Methodology
A standing panel of proton center medical physicists, hospital procurement committee chairs, EMA regulatory affairs specialists, and cyclotron vendor commercial directors provided ongoing calibration across primary interview cycles. This practitioner input combined with secondary validation from EU MDR notified body guidance documents, HAS and IQWiG health technology assessment rulings, hospital procurement database records, and GPO contract filings. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure analysis were triangulated to anchor market sizing.
Scenario bracketing around EMA-HTA convergence velocity and Italian reimbursement framework finalization shaped projection sensitivity bands across the modeling period. Segmentation dimensions spanned equipment type, delivery mode, application focus, and end-user facility tier. CAGRs were derived from installed base expansion rates weighted by regional HTA pathway maturity. Forecast inputs incorporated superconducting magnet supply chain lead times and clinical physicist training pipeline capacity constraints.
Stress conditions across EMA MDR enforcement intensity, superconducting magnet supply bottlenecks, and cross-border patient referral volume were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement alignment and procurement cycle normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Precision Oncology Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Ovarian Cancer Market
Oncology
North America Kidney Cancer Therapeutics and Diagnostics Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Global Cancer Profiling Market
Oncology
America Cancer Immunotherapy Market
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Angiosarcomas Treatment Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
North America Proton Therapy Market
Oncology
Thymus Cancer Market
Oncology
US Radiation Oncology Market
Oncology
Bone Cancer Treatment Market
Oncology
Tumor Ablation Market