
 Global Cancer Profiling Market | 2026-2036
Global Cancer Profiling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Profiling Market Foresight
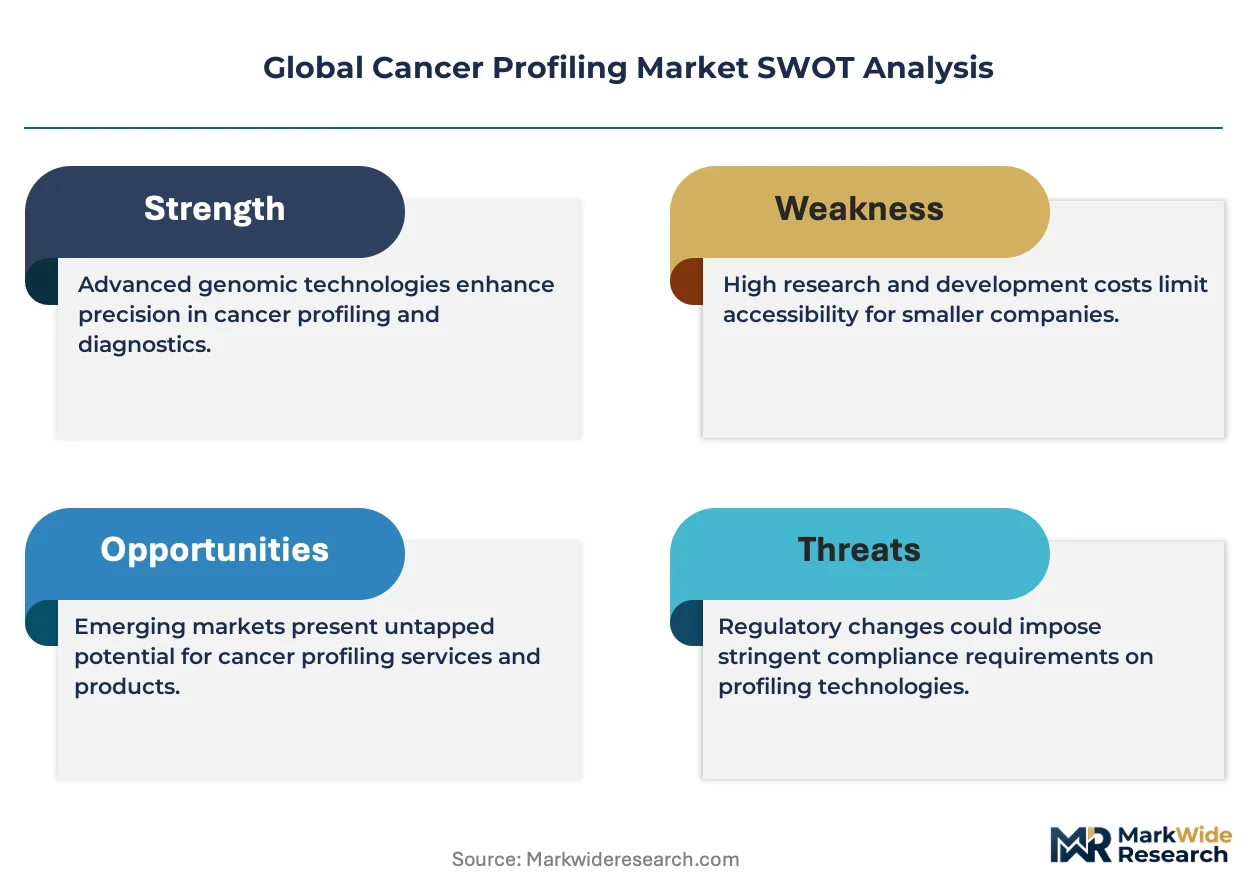
Comprehensive genomic profiling is reorganizing competitive dynamics across cancer diagnostics. Illumina, Inc. leverages its installed base of sequencing platforms to dominate instrument placement in clinical laboratories. QIAGEN sustains a differentiated position through sample-to-insight workflow integration spanning nucleic acid extraction through bioinformatics interpretation. Thermo Fisher Scientific Inc. anchors its presence through end-to-end reagent and service portfolios that span research use through regulated clinical applications.
Cancer profiling encompasses the systematic molecular characterization of tumors through analysis of DNA, RNA, proteins, and metabolites to identify actionable alterations guiding therapeutic selection and prognostic stratification, typically requiring sample inputs of nanogram-scale nucleic acid quantities and analytical sensitivity thresholds detecting variants at allele frequencies below five percent. Genomic profiling leads in commercial maturity and reimbursement capture, while transcriptomic profiling represents the fastest-expanding segment as RNA-based signatures gain traction in immuno-oncology patient selection. Next-generation sequencing technology commands the largest revenue pool, though PCR-based assays retain margin strength in targeted hotspot testing where turnaround time and cost efficiency outweigh breadth of analysis.
The FDA regulates cancer profiling assays as in vitro diagnostics or laboratory-developed tests depending on commercial distribution model, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for companion diagnostic claims across European markets. ISO 15189 accreditation and CAP laboratory certification shape operational standards for clinical validity and quality management. Stakeholders must monitor evolving payer evidence requirements for whole-exome versus gene-panel coverage as health technology assessment frameworks tighten reimbursement conditions for molecular diagnostics.
Market Dynamics
The FDA's expanded approval pathways for companion diagnostics are compressing commercialization timelines, forcing incumbent instrument vendors to reconfigure service models around rapid assay validation rather than platform placement alone.
Growth Catalysts
- Expanded Payer Coverage:United States commercial insurers and Medicare Advantage plans are broadening reimbursement for comprehensive genomic profiling, removing prior authorization barriers that previously restricted patient access to molecular testing.
- EMA In Vitro Diagnostic Regulation:Stricter clinical evidence requirements for companion diagnostic claims across European markets are elevating quality standards and favoring laboratories with robust quality management systems.
- Immuno-oncology Pipeline Expansion:RNA-based transcriptomic signatures are gaining traction in patient selection for checkpoint inhibitor therapies, driving demand for multi-omic profiling platforms.
Market Restraints
- Input Cost Volatility:Nanogram-scale nucleic acid extraction reagents and certified reference materials face supply concentration among limited qualified suppliers, creating margin pressure for high-throughput laboratories.
- Analytical Sensitivity Thresholds:Detection of variants at allele frequencies below five percent requires specialized library preparation chemistries and bioinformatics pipelines that extend turnaround times beyond clinically actionable windows.
- Regulatory Fragmentation:Divergent classification frameworks between FDA in vitro diagnostic pathways and laboratory-developed test enforcement create compliance complexity for multi-jurisdictional assay deployment.
Strategic Opportunities
- India's Diagnostic Infrastructure:The country's central drug regulator is streamlining molecular diagnostic approvals under revised medical device rules, creating entry pathways for reference laboratories in Mumbai, Delhi, and Bangalore.
- Liquid Biopsy Integration:Circulating tumor DNA analysis is converging with tissue-based profiling to enable serial monitoring, opening service contracts for longitudinal patient management.
- ISO 15189 Accreditation Mandates:National health systems in Germany, France, and Switzerland are tightening laboratory certification requirements, favoring accredited providers with integrated sample-to-insight workflows.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories face acute shortages of variant scientists capable of interpreting complex genomic alterations under CAP proficiency testing requirements.
- Legacy System Integration:Electronic health record interoperability with molecular diagnostic reporting platforms remains technically demanding, delaying implementation at community oncology practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Profiling Market |
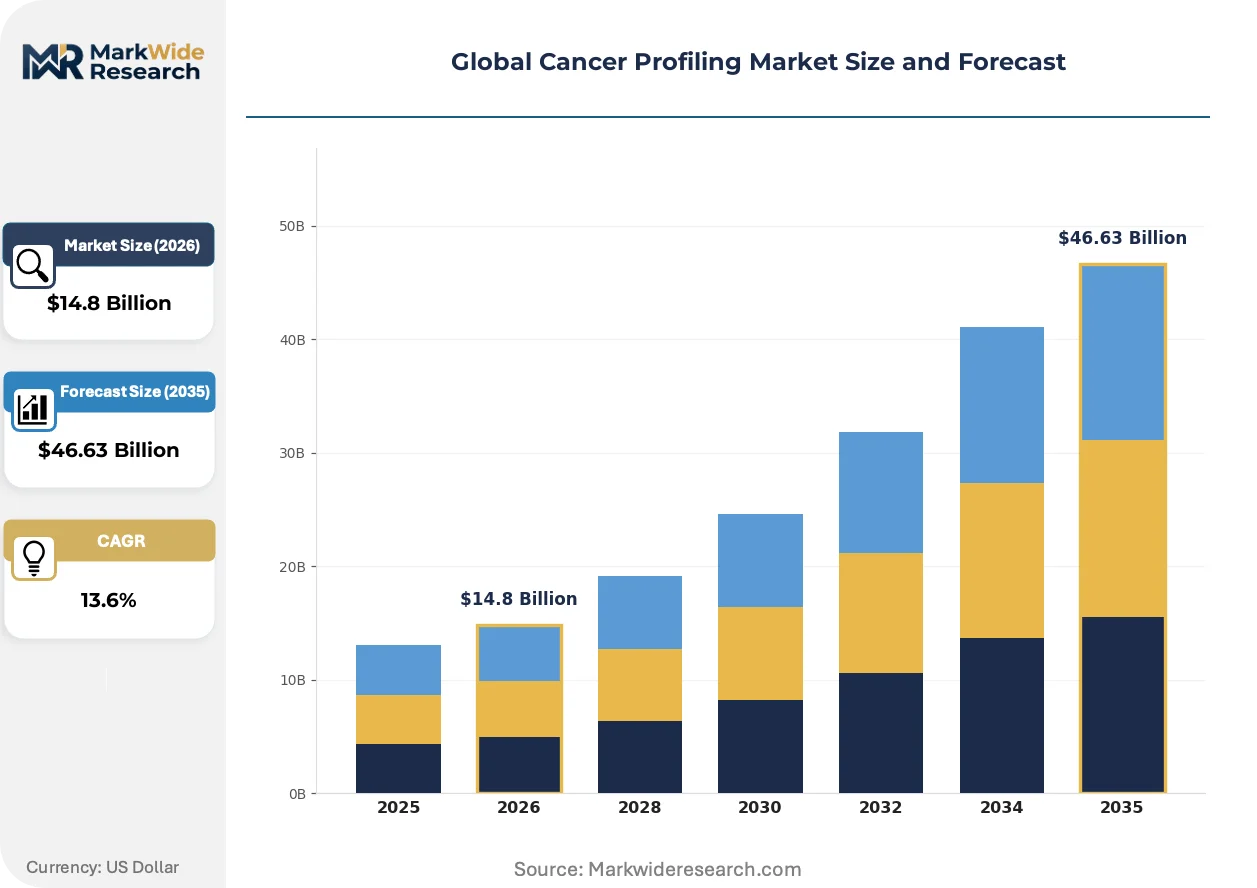
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genomic Profiling, Proteomic Profiling, Transcriptomic Profiling, Epigenomic Profiling, Metabolomic Profiling Application: Early Detection, Precision Medicine, Drug Development, Prognosis Assessment, Disease Monitoring End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Biotech Firms, Academic Centers Technology: Next-Generation Sequencing, Microarray, Mass Spectrometry, PCR-Based Assays, Immunohistochemistry |
| Companies Covered | Illumina, Inc., QIAGEN, Thermo Fisher Scientific Inc., NeoGenomics Laboratories, Guardant Health, Caris Life Sciences, F. Hoffmann-La Roche Ltd., Sysmex Corporation, HTG Molecular Diagnostics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Profiling Market Shifts & Advancements
Multi-omic profiling platforms are collapsing the historical separation between genomic, transcriptomic, and proteomic analysis, enabling simultaneous biomarker discovery across molecular layers.
Single-cell sequencing technology is decomposing bulk tumor analysis into clonal resolution maps. Academic medical centers in Boston, Heidelberg, and Singapore are adopting these platforms for minimal residual disease monitoring. This granularity is compressing the relevance of population-averaged biomarker signatures in clinical trial design.
Japan's PMDA has issued guidance harmonizing companion diagnostic approval with oncology drug licensing, eliminating sequential review delays that previously extended market entry timelines. Pharmaceutical sponsors now coordinate evidentiary packages across therapeutic and diagnostic submissions. This regulatory synchronization most benefits immuno-oncology programs targeting Japan's aging lung cancer population.
Hospital procurement committees are unbundling instrument, reagent, and informatics contracts that previously locked laboratories into multi-year exclusive arrangements. Independent reference laboratories in Texas, Bavaria, and Ontario are negotiating modular service agreements with specialized bioinformatics vendors. This disaggregation is most advanced in community oncology networks lacking in-house variant interpretation capacity.
Global Cancer Profiling Market Segmentation
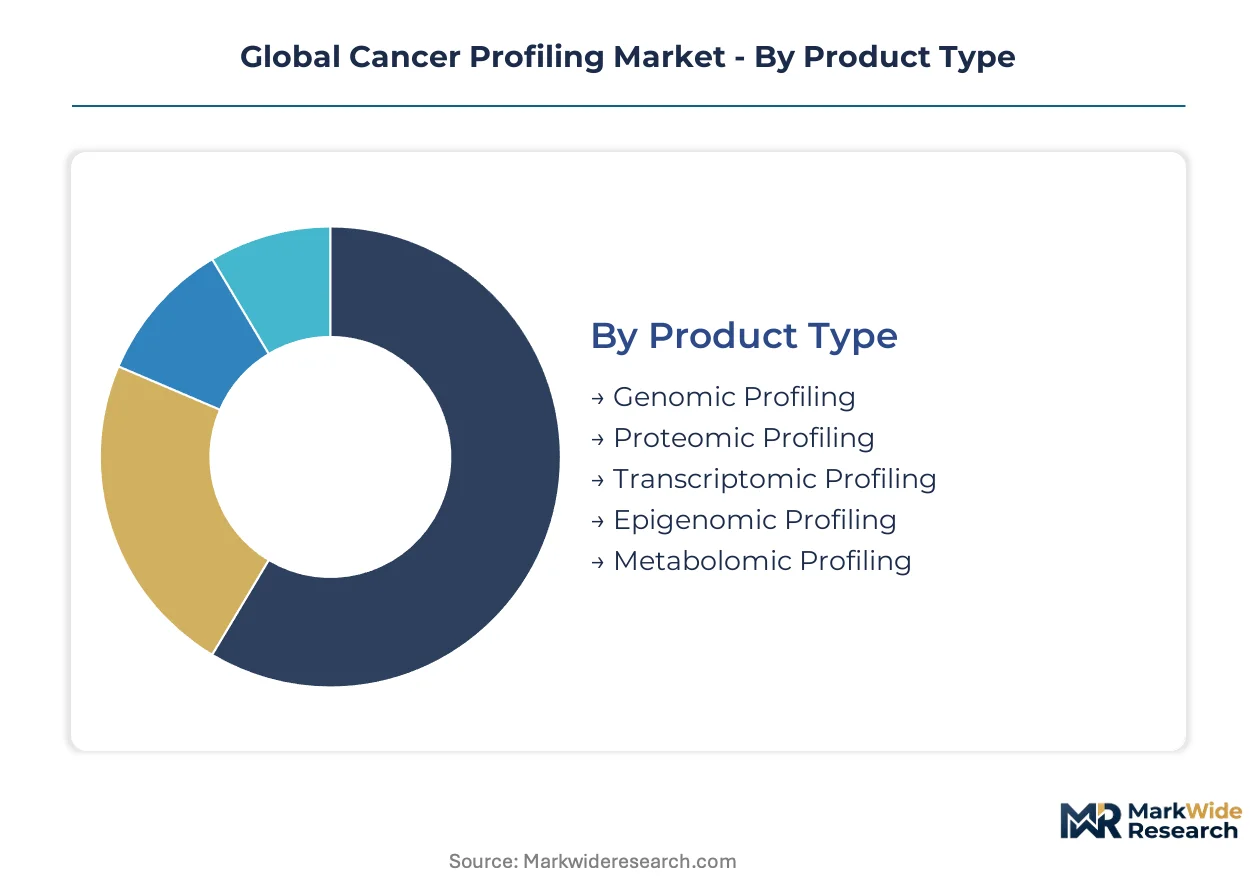
Cancer profiling segments align with distinct regulatory pathways and reimbursement frameworks. Product type determines FDA in vitro diagnostic classification, while technology choice shapes laboratory certification requirements under CAP and ISO 15189 standards.
Product Type:
FDA approval pathways diverge sharply across molecular layers, with genomic assays facing the most mature precedent while metabolomic platforms navigate novel qualification standards.
- Genomic Profiling:DNA sequence analysis detecting somatic mutations, copy number alterations, and structural variants at allele frequencies below five percent. United States commercial insurers and Medicare Advantage plans are broadening reimbursement for comprehensive genomic profiling, removing prior authorization barriers that previously restricted patient access.
- Transcriptomic Profiling:RNA-based expression signatures quantifying gene activity levels and fusion transcripts. RNA-based signatures are gaining traction in immuno-oncology patient selection for checkpoint inhibitor therapies across academic medical centers in Boston, Heidelberg, and Singapore.
- Proteomic Profiling:Protein expression and post-translational modification analysis using antibody-based detection methods.
- Epigenomic Profiling:DNA methylation patterns and histone modification mapping for lineage tracing applications.
- Metabolomic Profiling:Small-molecule metabolite quantification reflecting tumor metabolic state.
Genomic profiling handles the majority of throughput; transcriptomic profiling is the fastest mover on share.
Application:
Clinical utility evidence requirements vary by intended use, with precision medicine applications commanding the most stringent companion diagnostic validation standards.
- Precision Medicine:Therapeutic selection based on actionable molecular alterations matched to targeted agents. Pharmaceutical sponsors now coordinate evidentiary packages across therapeutic and diagnostic submissions under Japan's PMDA harmonized guidance.
- Early Detection:Screening asymptomatic populations for molecular signatures of malignancy. Liquid biopsy integration with circulating tumor DNA analysis is converging with tissue-based profiling to enable serial monitoring.
- Drug Development:Biomarker discovery and patient stratification in clinical trials.
- Prognosis Assessment:Risk stratification for disease recurrence and survival outcomes.
- Disease Monitoring:Longitudinal tracking of treatment response and resistance mechanisms.
Precision medicine commands the dominant revenue position; early detection is climbing the fastest as screening applications mature.
End User:
Procurement authority and technical infrastructure capacity segment the customer base into centralized reference laboratories versus distributed hospital networks.
- Diagnostic Laboratories:High-throughput clinical testing facilities processing thousands of specimens annually. Hospital procurement committees in Texas, Bavaria, and Ontario are unbundling instrument, reagent, and informatics contracts that previously locked laboratories into multi-year exclusive arrangements.
- Academic Centers:Research-intensive institutions with integrated clinical and discovery programs. Academic medical centers in Boston, Heidelberg, and Singapore are adopting single-cell sequencing platforms for minimal residual disease monitoring.
- Research Institutes:Dedicated discovery organizations without clinical diagnostic accreditation.
- Pharmaceutical Companies:Drug developers requiring companion diagnostic co-development partnerships.
- Biotech Firms:Emerging therapeutic developers outsourcing molecular characterization.
Diagnostic laboratories handle the majority of throughput; academic centers are gaining share fastest through technology translation programs.
Technology:
Capital intensity and turnaround time requirements create distinct competitive positions for platform vendors serving different testing volumes.
- Next-Generation Sequencing:Massively parallel DNA and RNA analysis delivering comprehensive genomic profiles. Illumina leverages its installed base of sequencing platforms to dominate instrument placement in clinical laboratories.
- PCR-Based Assays:Targeted amplification methods for rapid hotspot mutation detection. PCR-based assays retain margin strength in targeted hotspot testing where turnaround time and cost efficiency outweigh breadth of analysis.
- Microarray:Hybridization-based detection of copy number variations and single nucleotide polymorphisms.
- Mass Spectrometry:Proteomic and metabolomic quantification through ion detection.
- Immunohistochemistry:Protein localization in tissue sections using antibody staining.
Next-generation sequencing handles the majority of throughput; PCR-based assays are expanding most quickly in community oncology settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reagent exports from Germany's specialty chemical manufacturers supply clinical laboratories across France, Switzerland, and the Netherlands. This trade corridor feeds molecular diagnostic infrastructure where ISO 15189 accreditation mandates are tightening.
United States
Medicare Advantage plans and commercial insurers are removing prior authorization barriers for comprehensive genomic profiling. The FDA's expanded approval pathways for companion diagnostics compress commercialization timelines for assay developers. Boston's academic medical centers anchor single-cell sequencing adoption for minimal residual disease monitoring.
Germany
Hospital procurement committees in Bavaria and North Rhine-Westphalia are unbundling instrument-reagent-informatics contracts that previously locked laboratories into exclusive arrangements. ISO 15189 accreditation mandates from national health systems elevate quality management requirements. Heidelberg's university hospital cluster leads transcriptomic signature validation for immuno-oncology programs.
Japan
PMDA guidance harmonizing companion diagnostic approval with oncology drug licensing eliminates sequential review delays. METI standards support quality infrastructure for molecular diagnostic manufacturing. Tokyo-Osaka corridor laboratories are adopting multi-omic platforms for aging lung cancer population management.
India
Central drug regulator CDSCO is streamlining molecular diagnostic approvals under revised medical device rules. Mumbai, Delhi, and Bangalore reference laboratories are expanding nucleic acid extraction capacity. Maharashtra's diagnostic infrastructure attracts reagent distributors serving South Asian markets.
Switzerland
Swissmedic oversight of in vitro diagnostics aligns with EMA quality standards while maintaining separate authorization pathways. ISO 15189 laboratory certification requirements tighten under federal health system reforms. Basel-Zurich corridor anchors proteomic profiling capabilities for pharmaceutical co-development partnerships.
Global Cancer Profiling Market Competitive Landscape
Listed leaders compete with private specialists across platform placement and service contract models. The vendor base separates into instrument manufacturers, integrated workflow providers, and independent reference laboratories. Three archetypes dominate: sequencing platform incumbents leveraging installed bases, sample-to-insight integrators spanning extraction through interpretation, and liquid biopsy specialists capturing serial monitoring contracts. Competitive moves concentrate on unbundling multi-year exclusive arrangements and negotiating modular bioinformatics service agreements.
Within the platform-domination tier, Illumina, Inc. and Thermo Fisher Scientific Inc. exemplify scale-driven positioning through end-to-end reagent and instrument portfolios. QIAGEN occupies a differentiated position representing workflow integration specialists that bridge nucleic acid extraction with clinical interpretation. These three companies anchor competitive dynamics as hospital procurement committees disaggregate previously bundled contracts across Texas, Bavaria, and Ontario community oncology networks.
| Leading Market Players |
|---|
| Illumina, Inc. |
| QIAGEN |
| Thermo Fisher Scientific Inc. |
| NeoGenomics Laboratories |
| Guardant Health |
| Caris Life Sciences |
| F. Hoffmann-La Roche Ltd. |
| Sysmex Corporation |
| HTG Molecular Diagnostics, Inc. |
| Others |
Supply & Pricing Matrix
Sequencing platform scale economies concentrate manufacturing among three dominant instrument vendors, compressing per-run cost floors for clinical laboratories while elevating switching costs for buyers locked into reagent ecosystems. Capacity utilization at high-throughput centers in Boston, Heidelberg, and Singapore shapes spot pricing for reference materials, with ISO 15189-accredited facilities commanding premium positioning over non-certified competitors.
Pricing Analysis
Next-generation sequencing platforms carry three-generation pricing stratification: prior-generation instruments trade at depreciation-adjusted rates in secondary markets, current-generation systems anchor contract pricing through bundled reagent commitments, and emerging single-cell platforms command prototype premiums from academic medical centers. Three-tier pricing structure across premium, standard, and economy levels differentiates by CAP certification status and bioinformatics interpretation depth. Cost compression in economy-tier PCR-based assays is intensifying because hospital procurement committees in Texas and Bavaria are unbundling previously exclusive multi-year contracts. Community oncology networks exhibit highest price sensitivity, while pharmaceutical companion diagnostic co-development programs demonstrate lowest sensitivity due to regulatory timeline premiums.
Supply Chain Analysis
Nanogram-scale nucleic acid extraction reagent manufacturing concentrates in Germany, the United States, and Japan, creating single-source vulnerability for clinical laboratories dependent on qualified suppliers meeting FDA and EMA quality standards. Certified reference materials draw from synthetic biology foundries in Switzerland and Singapore, with histopathology-grade formalin supply anchored in Chinese chemical manufacturing. Tariff exposure on Chinese-sourced library preparation chemistries threatens margin structures for European reference laboratories. Distribution runs through specialty cold-chain logistics providers serving hospital networks and independent diagnostic facilities across North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in cancer profiling are approaching an interoperability inflection as hospital procurement committees disaggregate instrument-reagent-informatics bundles, fragmenting vendor lock-in and opening modular service contracts for specialized bioinformatics providers.
For Market Incumbents: Fortify installed-base retention by embedding variant interpretation software deeper into electronic health record workflows, addressing the legacy system integration delays plaguing community oncology practices. Backward integration into certified reference material production reduces exposure to nanogram-scale reagent supply concentration among limited qualified suppliers. Prioritize CAP laboratory certification investments as ISO 15189 mandates tighten across German, French, and Swiss national health systems. For New Entrants and Emerging Players: Bioinformatics talent scarcity in clinical variant interpretation represents the most penetrable service-layer gap, with acute shortages of qualified scientists under CAP proficiency testing requirements. Target longitudinal patient management contracts in liquid biopsy serial monitoring, where circulating tumor DNA analysis convergence with tissue-based profiling creates recurring revenue potential. Pursue modular service agreements with independent reference laboratories in Texas, Bavaria, and Ontario that lack in-house interpretation capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sample-to-insight workflow integrators spanning nucleic acid extraction through clinical interpretation, with reagent rental models outperforming instrument sales on cash-flow stability. Long-term viability over the coming decade hinges on multi-omic platform capabilities collapsing historical separations between genomic, transcriptomic, and proteomic analysis. Monitor Japan's PMDA harmonization guidance as the signal indicating regulatory synchronization momentum across companion diagnostic approval pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Broadening Medicare Advantage coverage for comprehensive genomic profiling accelerates patient access expansion. |
| Regulatory Approval Pathway | FDA expanded companion diagnostic pathways compress commercialization timelines for assay developers. |
| Platform Integration | Multi-omic profiling convergence collapses separation between genomic, transcriptomic, and proteomic analysis layers. |
| Hospital System Partnership | Unbundled instrument-reagent-informatics contracts open procurement opportunities for modular bioinformatics vendors. |
| Software Companion Development | Electronic health record interoperability with molecular diagnostic reporting platforms addresses implementation delays. |
Research Methodology
A spread of perspectives from clinical laboratory directors, regulatory affairs specialists at companion diagnostic developers, payer access managers at commercial insurers, and biomedical engineers at academic medical centers converged on the working assumptions underpinning this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, CMS Medicare coverage determinations, and hospital procurement database records. Bottom-up testing volume estimates triangulated against top-down instrument placement data across CAP-accredited facilities.
Segmentation dimensions modeled span product type, application, end user, technology, and regional regulatory cluster across the projection horizon. CAGRs were derived from testing volume trajectories, reimbursement expansion timelines, and instrument replacement cycles rather than simple extrapolation. Forecast inputs incorporated immuno-oncology pipeline expansion rates, liquid biopsy clinical validation milestones, and ISO 15189 accreditation mandate implementation schedules.
Forecasts assume regulatory continuity in FDA in vitro diagnostic classification and EMA companion diagnostic evidence requirements; material policy shifts would require re-modeling. Specific risk factors include divergent laboratory-developed test enforcement actions, payer coverage reversals for whole-exome versus gene-panel testing, and supply disruptions in qualified nucleic acid extraction reagent manufacturing. Practitioners should keep alternative scenarios live as health technology assessment frameworks for molecular diagnostics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Thyroid Cancer Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Tumor Infiltrating Lymphocytes Market
Oncology
Laser Cancer Therapy Market
Oncology
Gynecological Cancers Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
North America Bone Metastasis Market
Oncology
Tumor Ablation Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
America Cancer Immunotherapy Market
Oncology
US Veterinary Oncology Market