
 BRCA Mutation-Positive Ovarian Cancer Market | 2026-2036
BRCA Mutation-Positive Ovarian Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
BRCA Mutation-Positive Ovarian Cancer Market Outlook
Next-generation PARP inhibitor formulations with improved bioavailability and reduced hematologic toxicity profiles are redrawing competitive boundaries in BRCA-positive ovarian cancer. AstraZeneca leverages its first-mover position in combination regimens to sustain prescriber loyalty across major oncology centers. Merck differentiates through its immuno-oncology portfolio by anchoring combination trials with PD-1 inhibitors in platinum-sensitive populations.
BRCA mutation-positive ovarian cancer comprises epithelial malignancies harboring pathogenic variants in BRCA1 or BRCA2 tumor suppressor genes, detected through next-generation sequencing assays with variant allele frequency thresholds typically below 5 percent, and treated primarily with platinum-based chemotherapy and PARP inhibitor maintenance to exploit synthetic lethality in homologous recombination-deficient cells. PARP inhibitors within the drug class dimension command the dominant margin pool as maintenance therapy following platinum response, while intravenous delivery modes retain hospital-centric control despite oral formulations gaining traction in homecare settings for patient convenience.
FDA accelerated approval designations and EMA conditional marketing authorizations compress development timelines for targeted therapies in this indication, while the EU AI Act and FDA guidance on real-world evidence increasingly shape post-market commitment requirements and label expansion strategies. Stakeholders must monitor evolving biomarker testing reimbursement policies and companion diagnostic co-development mandates to secure market access for novel agents.
Market Dynamics
PARP inhibitor maintenance protocols are compressing treatment timelines and concentrating prescribing authority within hospital oncology departments, while companion diagnostic mandates from FDA and EMA are restructuring market access requirements for new molecular entities.
Growth Catalysts
- EMA conditional marketing authorization pathways:These accelerated frameworks compress development timelines for targeted therapies, enabling earlier patient access to novel agents in platinum-sensitive populations.
- Next-generation sequencing penetration:Tumor profiling adoption in community oncology practices is expanding the addressable patient pool beyond academic medical centers.
- Homologous recombination deficiency biomarker expansion:Testing protocols now capture BRCA-mutant and BRCA-like phenotypes, broadening the eligible maintenance population.
Market Restraints
- Platinum supply concentration:Hospital pharmacy procurement depends on concentrated cisplatin and carboplatin manufacturers, creating vulnerability to shortages that disrupt combination regimens.
- Myelodysplastic syndrome risk accumulation:Long-term PARP inhibitor exposure carries hematologic malignancy signals that limit treatment duration in responding patients.
- Companion diagnostic co-development costs:Synchronous FDA approval requirements for test and drug impose capital barriers for emerging therapeutic developers.
Strategic Opportunities
- Japan's aging ovarian cancer population:PMDA reimbursement incentives for biomarker-driven therapies create favorable access conditions for maintenance PARP inhibitors.
- Real-world evidence integration:FDA guidance on RWE submissions for label expansion enables post-market commitment strategies that accelerate indication broadening.
- Oral formulation homecare transition:Dispensing shifts from infusion centers to specialty pharmacy channels reduce hospital capacity constraints and patient travel burden.
Industry Challenges
- Variant interpretation expertise scarcity:Pathology departments lack sufficient molecular tumor board capacity to adjudicate BRCA1/2 variants of uncertain significance at required velocity.
- Cross-border diagnostic harmonization:Discordant EMA-FDA variant allele frequency thresholds complicate multinational trial design and regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRCA Mutation-Positive Ovarian Cancer Market |
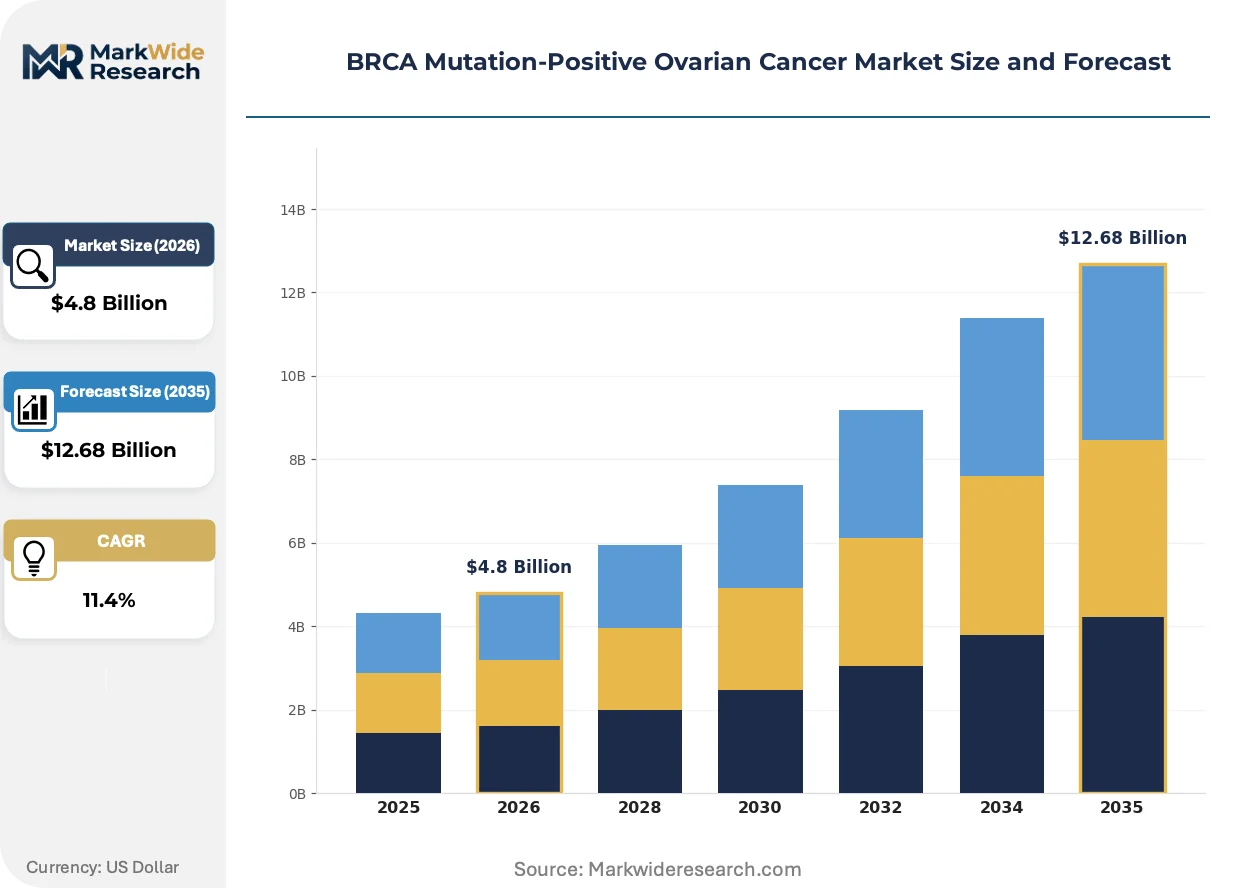
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Research Institutions, Homecare Drug Class: PARP Inhibitors, Antineoplastics, Monoclonal Antibodies, Others |
| Companies Covered | AstraZeneca, Pfizer, GlaxoSmithKline, Roche, Clovis Oncology, Merck, Johnson & Johnson, Genentech, Myriad Genetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRCA Mutation-Positive Ovarian Cancer Market Strategic Shifts
Liquid biopsy surveillance and adaptive trial designs are restructuring how therapeutic efficacy is measured and commercialized in BRCA-positive ovarian cancer, with implications for prescriber education and payer contract structures.
Next-generation PARP inhibitors with improved central nervous system penetration are displacing first-generation agents in patients with leptomeningeal disease or brain metastases. Neuro-oncology centers in Germany and the United States are adopting these agents ahead of formal label expansion. The displacement is compressing the commercial runway for legacy molecules in high-unmet-need subpopulations.
EU AI Act requirements for algorithmic transparency are reshaping how next-generation sequencing platforms validate variant calling pipelines. Laboratory-developed test providers must now document training data provenance and performance across ancestry groups. German and French reference laboratories are investing in compliance infrastructure ahead of 2025 enforcement timelines.
Specialty pharmacy direct-to-patient distribution is eroding traditional hospital outpatient department dispensing in platinum-sensitive maintenance settings. United States payers are steering oral oncology fills toward limited networks with enhanced adherence monitoring. This channel migration concentrates volume with vertically integrated pharmacy benefit managers and reduces prescriber control over treatment initiation timing.
BRCA Mutation-Positive Ovarian Cancer Market Segmentation
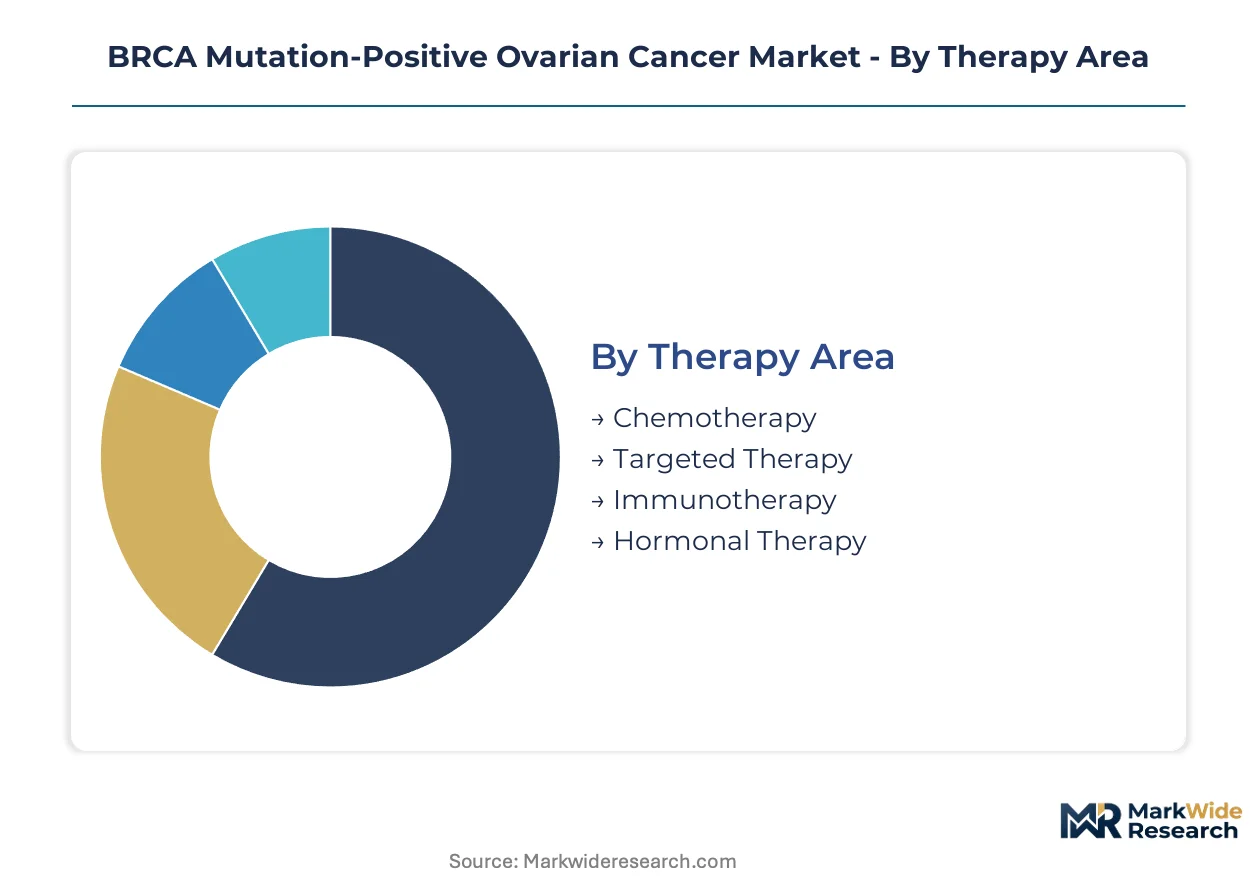
Segmentation in BRCA mutation-positive ovarian cancer reveals how regulatory pathways and reimbursement policies concentrate commercial activity across distinct therapeutic modalities and care settings. Treatment selection depends on biomarker status, platinum sensitivity, and institutional capacity for molecular tumor board review.
Therapy Area:
FDA accelerated approval and EMA conditional marketing authorization pathways create divergent access timelines across therapeutic categories, with oncology departments prioritizing agents that align with companion diagnostic mandates.
- Chemotherapy:Platinum-based regimens remain the backbone of first-line treatment, with cisplatin and carboplatin protocols dominating hospital infusion centers in the United States and Germany. Demand concentrates in academic medical centers with centralized pharmacy procurement, though platinum supply concentration creates vulnerability to shortage-driven treatment interruptions.
- Targeted Therapy:PARP inhibitors exploit synthetic lethality in homologous recombination-deficient cells, with maintenance dosing protocols compressing treatment timelines and shifting prescribing authority toward specialized gynecologic oncology units. United States and Japanese reimbursement frameworks favor biomarker-driven maintenance strategies.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors show activity in microsatellite instability-high subpopulations, though ovarian cancer remains less responsive than other solid tumors.
- Hormonal Therapy:Aromatase inhibitors and selective estrogen receptor modulators occupy niche roles in low-grade serous histologies with endocrine sensitivity.
Targeted therapy handles the majority of throughput; immunotherapy is the fastest mover on share.
Delivery Mode:
Cost tier differentiation separates hospital-centric infusion services from patient-convenient oral dispensing, with specialty pharmacy networks capturing margin from channel migration.
- Intravenous:Hospital outpatient departments retain control over platinum-based induction regimens, with infusion scheduling dictating prescriber visit frequency and ancillary revenue capture. German and United States oncology centers maintain capacity constraints that limit patient throughput.
- Oral:PARP inhibitor tablets enable homecare transition, with United States payers steering fills toward limited specialty pharmacy networks. PMDA reimbursement incentives in Japan accelerate adoption of oral maintenance protocols for aging patient populations.
- Subcutaneous:Emerging formulations promise reduced administration burden for monoclonal antibody classes.
- Topical:No established role in systemic ovarian cancer management.
Intravenous retains the highest absolute volume; oral formulations are expanding most quickly.
End User:
Customer type segmentation reflects where molecular testing infrastructure and treatment authorization concentrate, with academic centers maintaining gatekeeper status for novel agent access.
- Hospitals:Tertiary care centers with embedded next-generation sequencing laboratories and molecular tumor boards control initial diagnosis and treatment selection. United States National Cancer Institute-designated centers and German comprehensive cancer centers anchor clinical trial enrollment.
- Clinics:Community oncology practices expand biomarker testing penetration but rely on external reference laboratories for variant interpretation.
- Research Institutions:Academic medical centers with phase I units drive early-stage combination protocol development.
- Homecare:Specialty pharmacy dispensing and remote patient monitoring support oral maintenance therapy outside institutional settings.
Hospitals handle the majority of throughput; homecare is climbing the fastest.
Drug Class:
Margin concentration follows mechanism of action differentiation, with synthetic lethality-targeted agents commanding premium pricing over cytotoxic backbones.
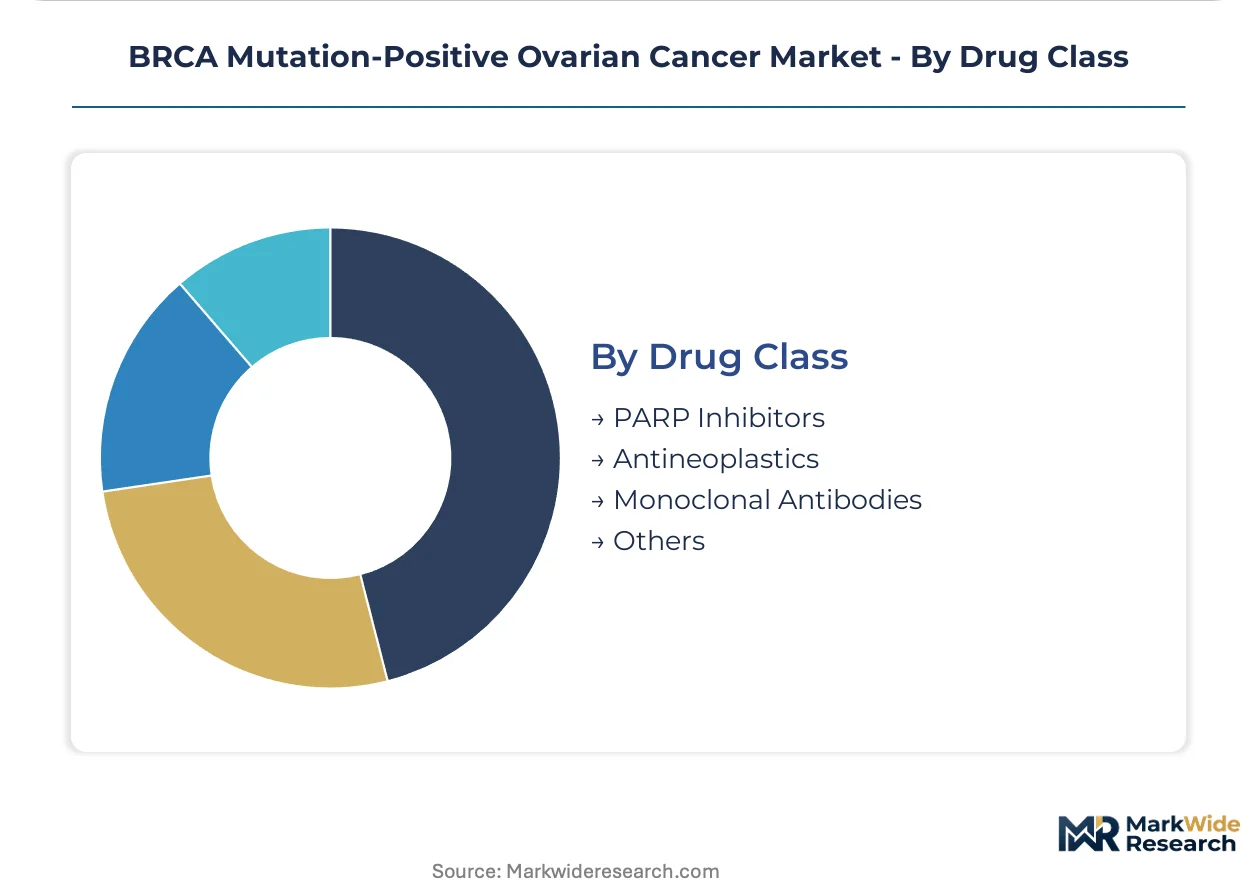
- PARP Inhibitors:Maintenance therapy following platinum response generates dominant commercial returns, with first-mover agents establishing prescriber loyalty through combination regimen data. EMA and FDA synchronous approval requirements for companion diagnostics structure competitive entry barriers.
- Antineoplastics:Platinum compounds and taxanes constitute essential induction components, though generic availability compresses pricing power.
- Monoclonal Antibodies:Anti-angiogenic and immune checkpoint classes seek positioning in platinum-resistant populations.
- Others:Investigational agents targeting DNA damage response pathways beyond PARP occupy preclinical and early clinical stages.
PARP inhibitors handle the majority of throughput; monoclonal antibodies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across major markets. United States payers demand outcomes-based contracts for PARP inhibitors, while Japan's aging population accepts premium pricing for biomarker-driven maintenance therapy. Germany anchors European volume with centralized procurement, creating divergent access conditions.
United States
FDA accelerated approval pathways compress commercialization timelines for BRCA-targeted agents. Medicare reimbursement for companion diagnostics shapes testing penetration in community oncology practices. National Cancer Institute-designated centers in Boston and Houston anchor clinical trial enrollment for combination regimens.
Germany
EMA conditional marketing authorizations enable earlier patient access than standard pathways. The G-BA benefit assessment process determines reimbursement for biomarker-driven maintenance protocols. Comprehensive cancer centers in Munich and Heidelberg concentrate molecular tumor board capacity for variant interpretation.
Japan
PMDA reimbursement incentives for precision oncology accelerate adoption of oral PARP inhibitors in platinum-sensitive populations. The aging demographic expands the addressable patient pool for maintenance therapy. Tokyo and Osaka academic medical centers lead real-world evidence collection for post-market commitments.
United Kingdom
NICE technology appraisals create staged access for targeted therapies based on cost-effectiveness thresholds. NHS England's Cancer Drugs Fund enables provisional reimbursement pending mature survival data. The Manchester and London cancer research clusters drive early-phase combination protocol development.
Switzerland
Swissmedic streamlined procedures for targeted therapies align with EMA accelerated pathways. Cantonal hospital procurement federations negotiate pricing for biomarker-driven maintenance agents. The Basel and Zurich oncology networks concentrate prescriber expertise for homologous recombination deficiency testing.
BRCA Mutation-Positive Ovarian Cancer Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the BRCA-positive ovarian cancer market. Large pharmaceutical conglomerates with immuno-oncology portfolios dominate combination trial design, while specialized oncology biotechs concentrate on next-generation PARP inhibitor formulations. Three archetypes define competitive positioning: integrated pharma with diagnostic partnerships, precision medicine specialists with companion diagnostic co-development capabilities, and diversified oncology players leveraging cross-portfolio synergies. M&A activity targets synthetic lethality platforms, while strategic partnerships between drug developers and reference laboratories reshape testing infrastructure control.
Within the integrated pharmaceutical tier, AstraZeneca and Merck occupy positions defined by their therapeutic portfolio breadth. AstraZeneca exemplifies first-mover advantage in PARP inhibitor maintenance through combination regimen data generation. Merck represents the immuno-oncology anchoring strategy, positioning PD-1 inhibitors in platinum-sensitive populations. Pfizer sits within the diversified oncology archetype, leveraging scale across multiple solid tumor indications.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| GlaxoSmithKline |
| Roche |
| Clovis Oncology |
| Merck |
| Johnson & Johnson |
| Genentech |
| Myriad Genetics |
| Others |
Value Chain & Pricing Dynamics
FDA accelerated approval pathways and EMA conditional marketing authorizations simultaneously gate supply qualification for PARP inhibitors and enable tiered price positioning based on biomarker-driven indication breadth. These regulatory frameworks create dual barriers: manufacturers must synchronize companion diagnostic co-development while payers stratify reimbursement according to variant allele frequency thresholds and platinum sensitivity status.
Pricing Analysis
After-sales revenue from patient support programs and adherence monitoring services drives lifetime value for oral PARP inhibitors in maintenance settings. Three-tier pricing structure across premium, standard, and economy levels separates first-mover combination regimens from follow-on monotherapies and eventual generic entries. Cost compression in the standard tier is intensifying because PBM formulary exclusions favor vertically integrated pharmacy networks. Community oncology practices exhibit highest price sensitivity due to limited prior authorization staffing; academic medical centers with embedded specialty pharmacies demonstrate lowest sensitivity.
Supply Chain Analysis
Inventory lead times for platinum salts stretch 8-14 weeks due to concentrated API manufacturing in China and India. Active pharmaceutical ingredient synthesis for PARP inhibitors draws from specialized chemical intermediates produced in Switzerland, Germany, and the United States. Single-source vulnerability pervades the companion diagnostic reagent supply, where German and French reference laboratories control variant interpretation kits. Distribution runs through hospital outpatient departments for intravenous induction, then migrates to specialty pharmacy direct-to-patient channels for oral maintenance phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molecular tumor board capacity constraints and variant interpretation expertise gaps define competitive advantage in this indication. The scarcity of pathologists trained in homologous recombination deficiency adjudication creates bottlenecks that determine patient access velocity.
For Market Incumbents: Compound first-mover data advantages through combination regimen expansion into platinum-resistant populations. Defend prescriber loyalty by embedding next-generation sequencing platforms within National Cancer Institute-designated centers. Counter emerging entrants through companion diagnostic exclusivity arrangements that lock reference laboratory partnerships. For New Entrants and Emerging Players: Anchor in Japan's aging ovarian cancer population where PMDA reimbursement incentives favor biomarker-driven maintenance adoption. Target community oncology practices lacking molecular tumor board infrastructure with external variant interpretation services. Pursue white-label companion diagnostic partnerships with established reference laboratories to bypass synchronous FDA approval barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision medicine platforms possessing synthetic lethality pipelines beyond PARP. Five-to-ten year viability hinges on DNA damage response target diversification and blood-based surveillance integration. Monitor FDA real-world evidence guidance implementation as the inflection signal for label expansion velocity and post-market commitment restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Synchronous FDA approval with PARP inhibitors accelerates patient access in platinum-sensitive settings. |
| Real-World Evidence Infrastructure | Post-market commitment strategies leverage Japanese academic medical center data collection capabilities. |
| Specialty Pharmacy Network Integration | Limited PBM distribution channels capture oral maintenance volume and adherence monitoring revenue. |
| Next-Generation Sequencing Platform Partnership | Laboratory-developed test validation aligns with EU AI Act algorithmic transparency requirements. |
| Combination Regimen Clinical Advancement | PD-1 inhibitor anchoring in platinum-sensitive populations expands addressable patient pools. |
Study Parameters
Desk research of FDA accelerated approval designations, EMA conditional marketing authorization databases, and ClinicalTrials.gov protocol registries preceded structured interviews with gynecologic oncology department heads, formulary directors at United States payers, PMDA reimbursement specialists, and reference laboratory technical directors. Primary fieldwork captured prescribing protocol evolution and companion diagnostic procurement patterns. Secondary validation drew from SEC 10-K oncology segment disclosures, CMS Medicare Part B claims data, and Japanese Ministry of Health reimbursement bulletins. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Variance decomposition across treatment line, delivery mode, and regional regulatory cluster segmentation dimensions shaped the analytical framework. CAGRs were derived from patient incidence projections, biomarker testing penetration curves, and maintenance therapy duration assumptions. Modeled inputs included platinum sensitivity status distribution, PARP inhibitor discontinuation rates from myelodysplastic syndrome signals, and oral formulation adoption velocity in aging populations.
Decision-makers should treat outputs as directional under stable FDA-EMA regulatory harmonization assumptions; material deviation in companion diagnostic reimbursement policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Solid Tumor Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
Metastatic Melanoma Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Europe Radiotherapy Market
Oncology
Glottic Cancer Treatment Market
Oncology
Ovarian Cancer Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Gynecological Cancer Drugs Market
Oncology
America Cancer Immunotherapy Market
Oncology
Metastases Spinal Tumor Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Internal Radiation Therapy Market
Oncology
North America Bone Metastasis Market
Oncology
Adrenocortical Carcinoma Treatment Market