
 North America Kidney Cancer Therapeutics and Diagnostics Market | 2026-2036
North America Kidney Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Kidney Cancer Therapeutics and Diagnostics Market Analytics
The United States is tilting toward expanded biologics manufacturing capacity for renal oncology. Pfizer Inc anchors its position through integrated supply chains for targeted small molecules. Bristol Myers Squibb differentiates via checkpoint inhibitor portfolios in renal cell carcinoma. Exelixis specializes in tyrosine kinase inhibitors with concentrated FDA label expansions.
Kidney cancer therapeutics and diagnostics encompass systemic treatments and detection modalities directed at renal malignancies, including tyrosine kinase inhibitors, mTOR inhibitors, immune checkpoint inhibitors, PD-L1 assays, and contrast-enhanced imaging protocols designed to interrupt tumor angiogenesis or activate anti-tumor immunity. Immunotherapy commands the dominant share of new patient initiations across academic medical centers, while targeted therapy retains substantial volume in refractory populations. Oral delivery modes are gaining share against intravenous infusion as convenience protocols expand into community oncology settings.
FDA breakthrough therapy designation and the EMA's parallel access schemes govern product registration pace across North America, with Health Canada aligning its priority review framework to compress market entry timelines. The IRA's Medicare price negotiation provisions are reshaping revenue modeling for late-cycle oncology assets. Stakeholders must monitor how CMS coverage determination shifts affect site-of-care migration from hospitals to oncology clinics.
Market Dynamics
The IRA's Medicare price negotiation provisions are compressing revenue models for late-cycle oncology assets, forcing manufacturers to accelerate early-stage pipeline prioritization and site-of-care optimization strategies.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses commercialization timelines for renal cell carcinoma therapies, enabling earlier patient access and faster label expansions.
- Community Oncology Migration:Oral tyrosine kinase inhibitors are displacing intravenous infusion protocols, expanding treatment capacity beyond academic medical centers into regional cancer networks.
- Contrast-Enhanced Imaging:Advanced CT and MRI protocols with iodinated contrast agents are improving early-stage detection rates, expanding the addressable patient population for adjuvant therapy interventions.
Market Restraints
- Biologics Manufacturing Concentration:Active pharmaceutical ingredient production for checkpoint inhibitors concentrates in Puerto Rico and Massachusetts facilities, creating geographic supply vulnerability.
- Reimbursement Compression:CMS national coverage determinations for companion diagnostics are narrowing assay validation pathways, extending time-to-market for PD-L1 testing platforms.
- Clinical Trial Complexity:Combination therapy protocols require larger enrollment cohorts and longer follow-up periods, inflating development costs for immuno-oncology candidates.
Strategic Opportunities
- Mexico Regulatory Alignment:COFEPRIS is harmonizing bioequivalence standards with FDA guidelines, creating accelerated entry pathways for established targeted therapies.
- Minimal Residual Disease Testing:Circulating tumor DNA assays for post-nephrectomy monitoring represent an untapped adjacency with limited incumbent competition.
- Teleoncology Integration:Remote patient monitoring platforms are enabling rural site-of-care expansion, connecting community hospitals with academic subspecialty expertise.
Industry Challenges
- Biomarker Validation Bottlenecks:Analytical validation for predictive signatures in renal cell carcinoma subtypes requires multi-site prospective studies, stretching clinical affairs resources.
- Cold Chain Integrity:Temperature excursions during distribution of biologics from manufacturing sites to infusion centers risk product wastage and patient treatment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Kidney Cancer Therapeutics and Diagnostics Market |
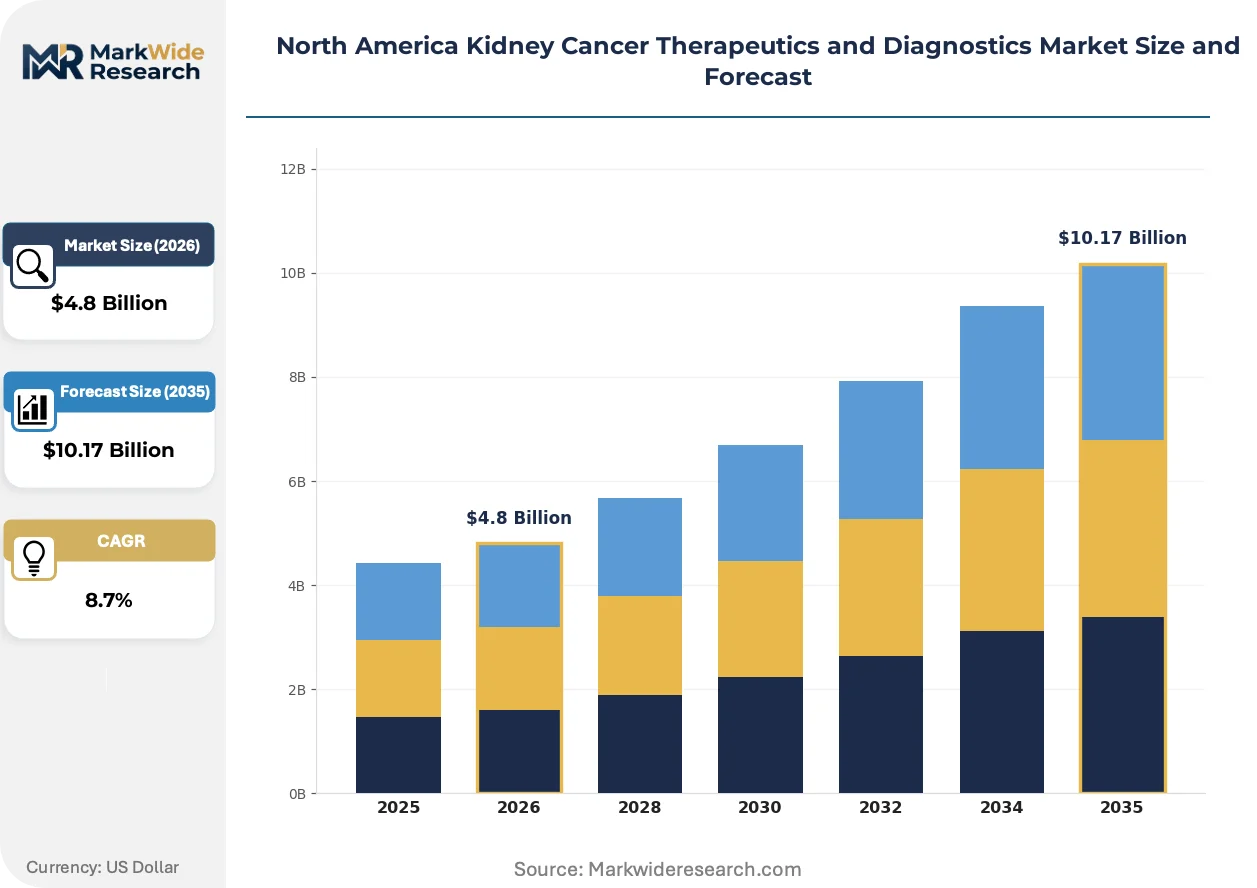
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiotherapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Oncology Clinics, Research Institutions, Home Care Indication: Localized Kidney Cancer, Advanced Renal Cell Carcinoma, Metastatic Kidney Cancer, Other |
| Companies Covered | Pfizer Inc, F. Hoffmann-La Roche Ltd, Bayer AG, Novartis AG, Amgen Inc, Bristol Myers Squibb, Abbott Laboratories, Exelixis, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Kidney Cancer Therapeutics and Diagnostics Market Evolving Landscape
Digital pathology and artificial intelligence are restructuring diagnostic workflows, while immuno-oncology combinations and precision biomarker strategies are redefining therapeutic sequencing across the care continuum.
Liquid biopsy platforms using cell-free DNA analysis are virtualizing tissue-based mutation profiling, enabling real-time genomic monitoring without repeat biopsies. Community oncology practices in Texas and Florida are adopting these platforms for treatment selection and resistance surveillance. This virtualization is compressing turnaround times from weeks to days, accelerating therapeutic pivots at progression.
The IRA's Medicare Drug Price Negotiation Program is mandating price concessions for selected oncology assets after nine years of market exclusivity, altering lifecycle management strategies for small-molecule inhibitors. Manufacturers are responding by front-loading indication expansions and prioritizing combination approvals that extend protected positioning.
Oncology clinics are consolidating purchasing decisions through group purchasing organizations, displacing hospital-centric procurement for oral oncolytics. This concentration is shifting inventory risk from health systems to specialty distributors. The pattern is most pronounced in the southeastern United States, where independent oncology practices dominate community care delivery.
North America Kidney Cancer Therapeutics and Diagnostics Market Segmentation
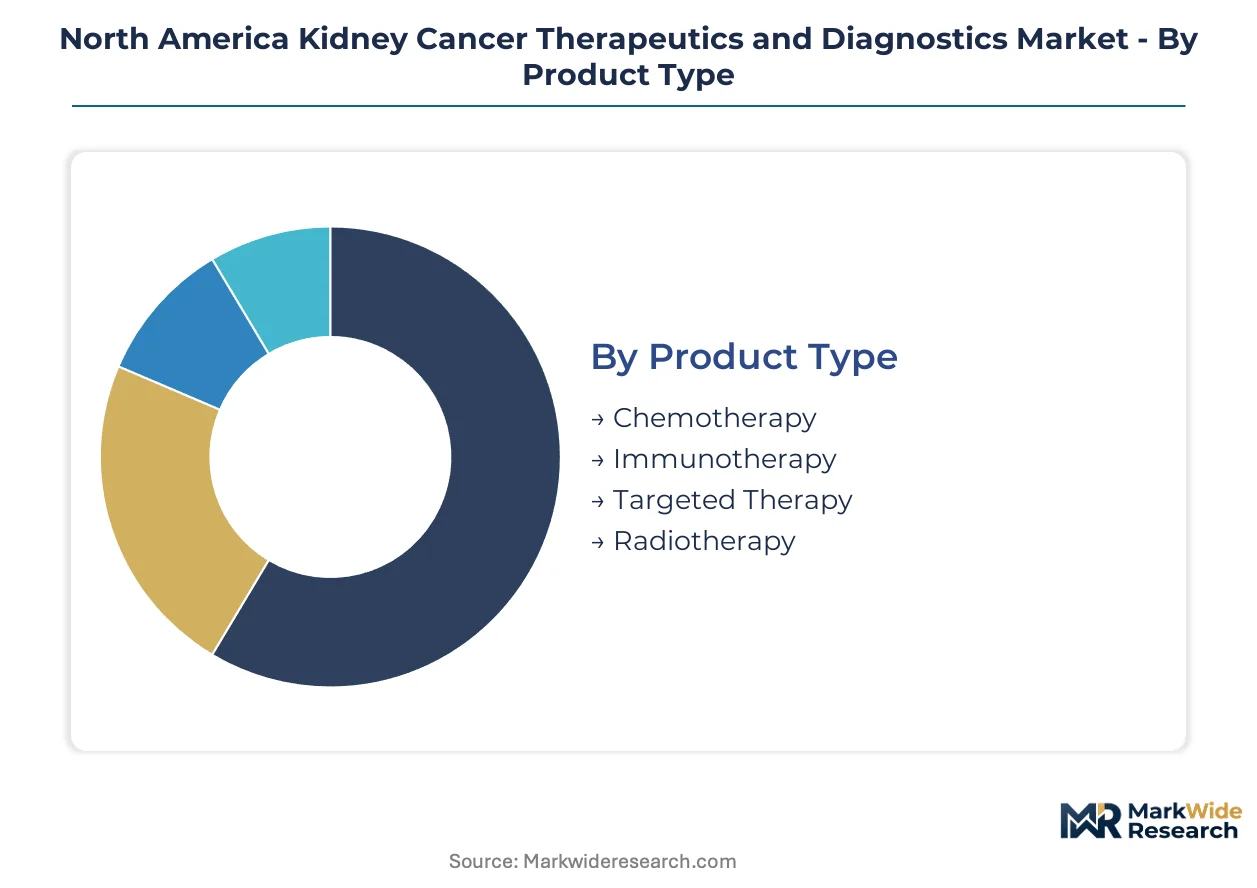
Precision in therapeutic categorization determines procurement patterns across North American oncology networks. Delivery mode selection directly shapes site-of-care economics and patient adherence protocols. End-user segmentation reveals how treatment administration migrates from inpatient to ambulatory settings.
Product Type:
After-sales service intensity varies sharply across therapeutic modalities, with biologics requiring cold chain monitoring and infusion support that small molecules do not demand.
- Immunotherapy:Checkpoint inhibitors and cytokine therapies activate anti-tumor immunity through PD-1/PD-L1 blockade or IL-2 pathways. Academic medical centers in the United States concentrate demand as infusion capacity and toxicity management expertise concentrate there. IRA price negotiation timelines compress revenue windows for established agents.
- Targeted Therapy:Tyrosine kinase inhibitors and mTOR inhibitors interrupt angiogenic signaling in renal cell carcinoma subtypes. Oral bioavailability drives community oncology adoption in Texas and Florida regional networks. Convenience protocols displace hospital-based infusion volumes.
- Chemotherapy:Cytotoxic agents retain niche utility in refractory or non-clear cell histologies. Demand concentrates in salvage settings where targeted options have failed.
- Radiotherapy:External beam and stereotactic ablative approaches address oligometastatic disease or palliative indications. Utilization clusters at comprehensive cancer centers with integrated multidisciplinary programs.
Immunotherapy holds the largest share; momentum sits with targeted therapy.
Delivery Mode:
Cost tier stratification separates hospital-administered biologics from self-administered oral agents, with reimbursement differentials driving site-of-care migration.
- Oral:Small-molecule inhibitors enable outpatient management without infusion infrastructure. Community oncology practices in the southeastern United States prioritize oral portfolios to minimize facility overhead and patient travel burden.
- Intravenous:Monoclonal antibodies and checkpoint inhibitors require controlled infusion environments with hypersensitivity monitoring. Hospital outpatient departments retain volume for toxicity-intensive regimens.
- Subcutaneous:Emerging formulations reduce administration time and facility dependency. Oncology clinics in Canada pilot subcutaneous checkpoint inhibitors to expand rural access.
- Topical:Limited applicability in renal malignancies; experimental protocols for cutaneous metastases occupy research settings only.
Intravenous delivery retains the largest share; oral administration is gaining share fastest.
End User:
Customer type determines purchasing concentration, with group purchasing organizations consolidating oral oncolytic procurement outside hospital systems.
- Hospitals:Academic medical centers anchor complex case management, nephrectomy integration, and clinical trial access. FDA breakthrough therapy initiations concentrate at NCI-designated comprehensive cancer centers.
- Oncology Clinics:Independent practices in Texas and Florida dominate oral targeted therapy administration. Inventory risk shifts from health systems to specialty distributors as GPO concentration accelerates.
- Research Institutions:Phase I/II trial sites drive pipeline exposure and biomarker validation. Early-stage immunotherapy combinations require dedicated pharmacovigilance infrastructure.
- Home Care:Remote patient monitoring platforms enable rural administration of oral regimens. Teleoncology integration connects home-based patients with academic subspecialty expertise.
Hospitals hold the largest share; oncology clinics show the steepest expansion trajectory.
Indication:
Maturity gradients separate established adjuvant protocols from emerging metastatic combination strategies, with development investment concentrating at advanced disease stages.
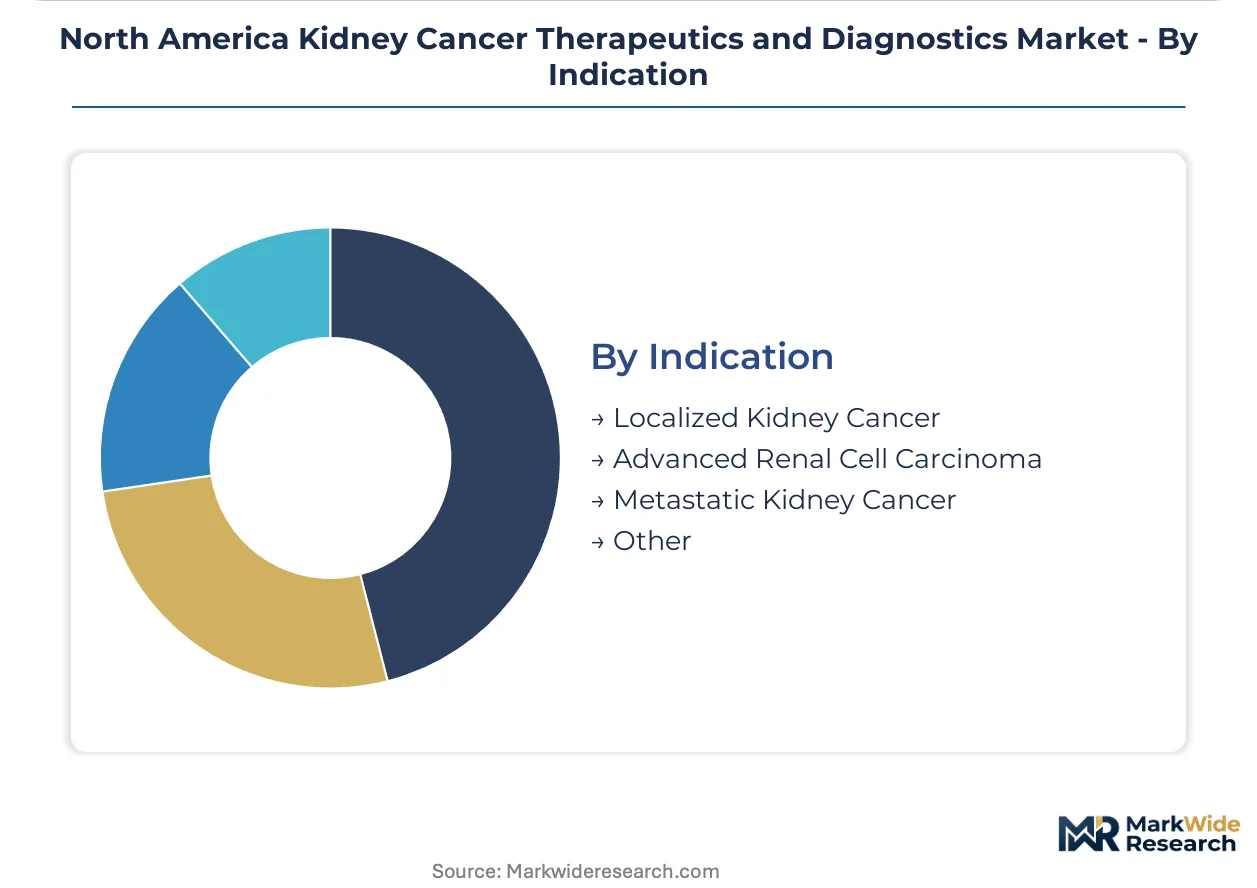
- Advanced Renal Cell Carcinoma:First-line immunotherapy combinations and subsequent targeted therapy sequences define the therapeutic paradigm. CMS coverage determinations shape access to PD-L1 companion diagnostics.
- Metastatic Kidney Cancer:Cabozantinib-nivolumab and similar combinations dominate treatment initiation. Clinical trial complexity inflates development costs for novel immuno-oncology candidates.
- Localized Kidney Cancer:Adjuvant pembrolizumab approval expanded addressable population post-nephrectomy. Minimal residual disease testing represents an untapped monitoring adjacency.
- Other:Non-clear cell histologies and rare renal malignancies lack established systemic options. Trial enrollment challenges limit evidence generation.
Advanced renal cell carcinoma holds the largest share; localized kidney cancer is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designations anchor therapeutic access across the United States, while Health Canada and COFEPRIS compress regulatory timelines for their respective markets. The IRA's Medicare price negotiation provisions reshape revenue modeling across all three jurisdictions.
United States
NCI-designated comprehensive cancer centers concentrate immunotherapy trial initiations and nephrectomy-integrated care pathways. The IRA's Medicare Drug Price Negotiation Program mandates price concessions after nine years of market exclusivity, compressing lifecycle windows for small-molecule inhibitors. Massachusetts and Puerto Rico anchor biologics manufacturing capacity for checkpoint inhibitors.
Canada
Health Canada's priority review framework aligns with FDA guidelines to accelerate market entry for renal cell carcinoma therapies. pCPA pan-Canadian Oncology Drug Review negotiations consolidate provincial purchasing power, creating price uniformity across Ontario, Quebec, and British Columbia. Ontario's Cancer Care Ontario network pilots subcutaneous checkpoint inhibitor administration to expand rural access.
Mexico
COFEPRIS bioequivalence harmonization with FDA standards creates accelerated pathways for established tyrosine kinase inhibitors. Seguro Popular expansion extends oncology coverage to previously uninsured populations, enlarging the addressable patient base. Mexico City Metro concentrates private hospital capacity for targeted therapy administration.
Texas
Independent oncology practices across Houston and Dallas-Fort Worth anchor oral targeted therapy adoption, displacing hospital-centric infusion volumes. Group purchasing organization consolidation shifts inventory risk to specialty distributors. The state's community cancer networks lead teleoncology integration for rural patient monitoring.
Florida
Southeastern oncology clinics prioritize oral small-molecule portfolios to minimize facility overhead and patient travel burden. Medicare Advantage penetration rates exceed national averages, altering reimbursement dynamics for adjuvant pembrolizumab protocols. Miami and Tampa Bay medical centers concentrate multidisciplinary renal malignancy programs.
North America Kidney Cancer Therapeutics and Diagnostics Market Competitive Landscape
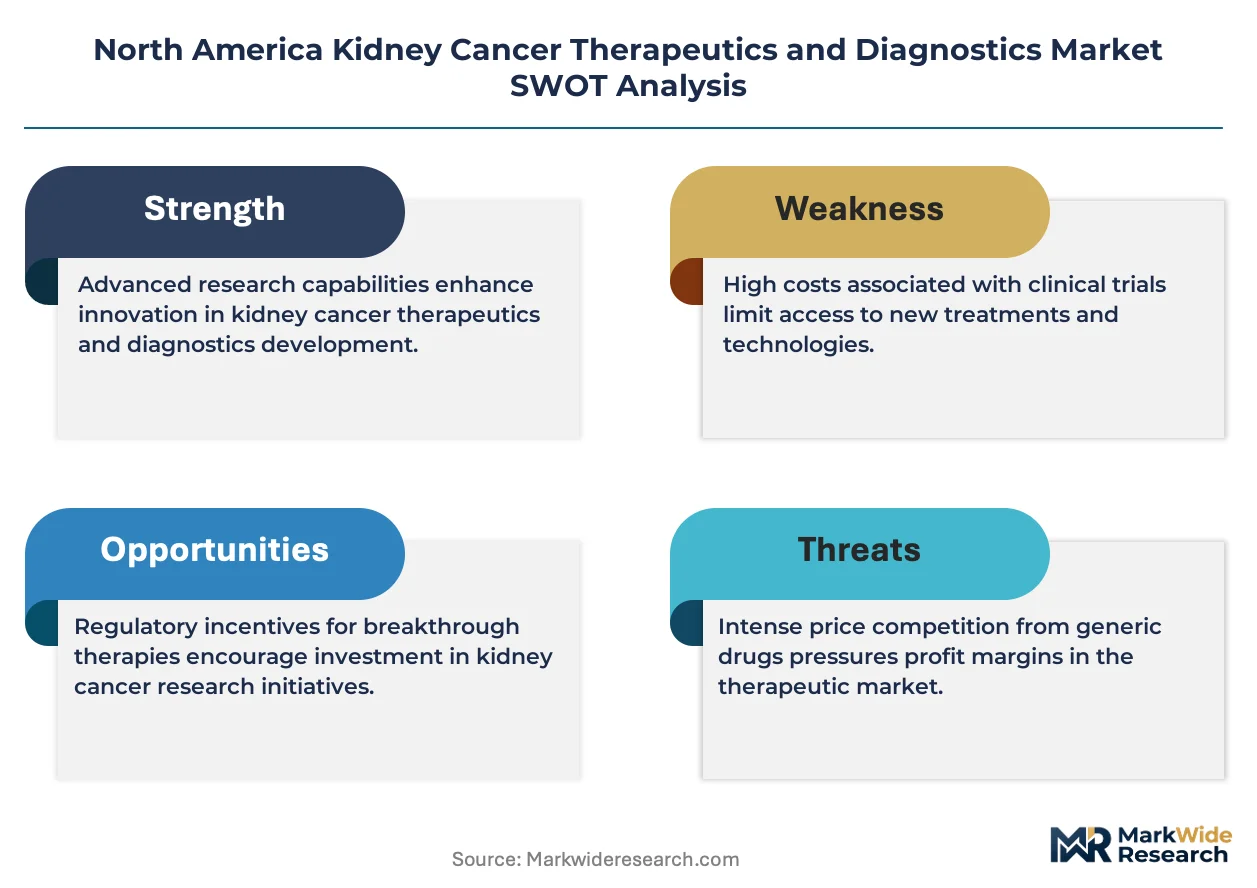
Capability concentration sits with integrated pharmaceutical conglomerates; scale advantage sits with specialized oncology biotechs. The market structures around three tiers: diversified majors with checkpoint inhibitor portfolios, targeted therapy specialists with concentrated FDA label expansions, and diagnostic platform developers with companion assay offerings. Dominant competitive moves include indication expansion front-loading to extend protected positioning, and site-of-care optimization strategies that shift volume toward community oncology networks.
Among diversified pharmaceutical conglomerates, Pfizer Inc and Bristol Myers Squibb exemplify the integrated-major archetype through established renal oncology franchises. Exelixis occupies a specialist position within the targeted therapy tier, representing concentrated focus on tyrosine kinase inhibitor development. These three entities anchor competitive positioning across the therapeutic continuum from first-line immunotherapy combinations to refractory small-molecule sequences.
| Leading Market Players |
|---|
| Pfizer Inc |
| F. Hoffmann-La Roche Ltd |
| Bayer AG |
| Novartis AG |
| Amgen Inc |
| Bristol Myers Squibb |
| Abbott Laboratories |
| Exelixis |
| Merck & Co. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Puerto Rico biologics manufacturing is intensifying contract-manufacturing premiums for checkpoint inhibitors, compressing margins for developers while concentrating pricing power among facilities with FDA-validated cold chain infrastructure. Massachusetts facilities face parallel utilization constraints, forcing manufacturers to absorb higher COGS or accelerate site-of-care migration toward oral agents that bypass infusion-dependent supply chains.
Pricing Analysis
Price spreads between United States academic medical centers and Mexico City private hospitals exceed threefold for identical checkpoint inhibitor regimens, reflecting reimbursement tiering and procurement concentration differentials. Three-tier pricing structure across premium, standard, and economy levels separates NCI-designated centers from community oncology networks and cash-pay Latin American markets. Pricing pressure stems from IRA Medicare negotiation timelines compressing exclusivity windows for small-molecule inhibitors. Community oncology practices in Texas and Florida exhibit highest price sensitivity, while academic centers prioritize clinical trial access over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentrates at Lonza Portsmouth, Fujifilm Diosynth Biotechnologies Texas, and Samsung Biologics for monoclonal antibody production, with Puerto Rico and Massachusetts anchoring fill-finish capacity. Active pharmaceutical ingredient sourcing draws from Ireland, Switzerland, and Singapore for high-potency oncology compounds. Single-source vulnerability concentrates in temperature-controlled distribution lanes between manufacturing sites and infusion centers. Distribution runs through specialty pharmaceutical distributors with dedicated oncology cold chain networks, displacing generalist wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where FDA breakthrough therapy designations create regulatory entrenchment, erecting switching costs that lock in prescriber behavior across treatment lines and resist generic displacement.
For Market Incumbents: Insulate market position through backward integration into biologics manufacturing capacity in Puerto Rico and Massachusetts, capturing margin otherwise lost to contract-manufacturing markups. Accelerate companion diagnostic co-development with PD-L1 assay platforms to tighten prescriber switching costs. Priority threat: biosimilar entrants targeting expiring checkpoint inhibitor patents. For New Entrants and Emerging Players: Build out circulating tumor DNA monitoring capabilities for post-nephrectomy minimal residual disease surveillance, the most penetrable adjacency with limited incumbent competition. Target Mexico regulatory pathways leveraging COFEPRIS-FDA harmonization for accelerated tyrosine kinase inhibitor entry. Go-to-market angle: teleoncology-integrated remote patient monitoring platforms enabling rural site-of-care expansion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across subcutaneous formulation development, as delivery innovation becomes the primary differentiation vector. Five-to-ten-year viability favors targeted therapy specialists with concentrated label expansion track records over diversified majors facing IRA price negotiation exposure. Acquisition target archetype: diagnostic platform developers with validated companion assays. Signal to watch: CMS national coverage determination shifts for liquid biopsy platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates FDA breakthrough therapy designation timelines for renal cell carcinoma combinations. |
| Manufacturing Scale-Up | Expands Puerto Rico biologics capacity to reduce contract-manufacturing dependency and COGS pressure. |
| Regulatory Approval Pathway | Aligns COFEPRIS submissions with FDA guidelines for accelerated Mexico market entry. |
| Pipeline Diversification | Builds minimal residual disease testing capabilities adjacent to core therapeutic franchises. |
| Licensing Agreement | Secures companion diagnostic partnerships that tighten PD-L1 testing integration with drug prescribing. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from FDA filings, ClinicalTrials.gov records, CMS Medicare coverage determinations, and hospital procurement database extracts. Bottom-up patient-flow modeling and top-down revenue triangulation anchored volume and value estimates.
Demand-supply balance dynamics across immunotherapy and targeted therapy segments structured the analytical framework over the projection horizon. Segmentation dimensions modeled include treatment line, administration route, site-of-care setting, and regional regulatory cluster. CAGRs derived from indication-specific patient incidence curves, therapy sequencing patterns, and pricing trajectory assumptions. Forecast inputs incorporated IRA negotiation timeline impacts and biosimilar entry probability assessments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by biosimilar developers or disruptive diagnostic entrants would shift outcomes beyond modeled ranges. Specific risk factors include CMS coverage reversals for companion diagnostics and cold chain integrity failures disrupting biologics distribution. Quarterly review of FDA approval velocity and Medicare national coverage determination timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Osteosarcoma Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Immuno-Oncology Clinical Trials Market
Oncology
Esophageal Cancer Market
Oncology
Vulvar Cancer Market
Oncology
Particle Therapy Systems Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Metastases Spinal Tumor Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Cancer Cachexia Market