
 Europe Radiotherapy Market | 2026-2036
Europe Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Radiotherapy Market Insights
Market Context with Strategic Players
The Europe radiotherapy equipment landscape is consolidating around a sharp split between premium proton and stereotactic systems and commodity linear accelerator replacements. Siemens Healthineers AG leverages its imaging-radiotherapy integration to dominate hybrid workflow installations across German university hospitals. Elekta AB sustains its position in digital linac upgrades through software-defined treatment planning. Ion Beam Applications SA anchors the proton therapy niche with specialized cyclotron supply to French and Belgian centers.
Technical Definition and Structural Segments
Radiotherapy employs ionizing radiation—photon, proton, or electron beams precisely targeted to tumor tissue with dose gradients measured in gray units—to destroy malignant cells while sparing surrounding healthy structures. External beam systems generate radiation via linear accelerators or cobalt-60 sources, with multi-leaf collimators shaping fields to sub-millimeter tolerances for curative and palliative oncology. External beam technology captures the largest installed base across Europe, yet proton therapy represents the fastest-expanding modality as centers in Italy and the Netherlands commission new gantry suites. Brachytherapy remains a mature margin pool concentrated in gynecological and prostate applications, while stereotactic radiosurgery grows fastest in neurosurgery departments seeking single-session alternatives to invasive cranial procedures.
Regulatory Frame and Forward-Looking Close
The EU Medical Device Regulation and CE marking framework enforce clinical evidence requirements and post-market surveillance that elevate barriers for new radiotherapy entrants across member states. EMA coordination with national competent authorities in France, Germany, and Italy shapes reimbursement pathways for advanced modalities. France's ANSM and Germany's BfArM apply additional scrutiny to software-as-medical-device components in treatment planning systems. Stakeholders must monitor how the EU AI Act classification rules affect machine-learning-driven dose optimization algorithms entering European clinical workflows.
Market Dynamics
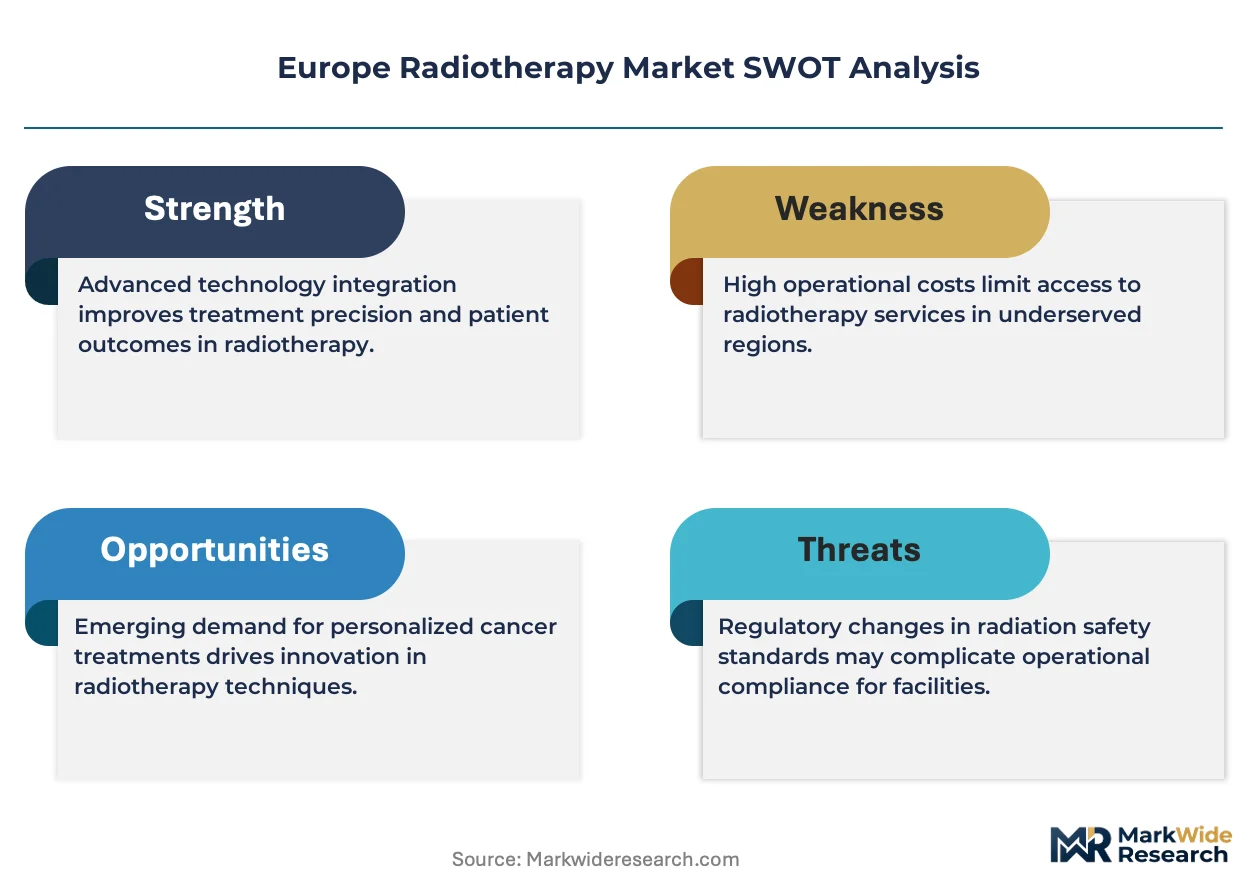
The EU Medical Device Regulation's clinical evidence requirements are compressing vendor margins while accelerating proton therapy adoption across French and German university hospitals seeking differentiated oncology service lines.
Growth Catalysts
- MDR Compliance Deadlines:The EU Medical Device Regulation's 2024-2026 transition window forces early certification of legacy linear accelerators, creating replacement demand cycles in Italian and Spanish oncology centers.
- Proton Therapy Infrastructure:National health technology assessment bodies in France and the Netherlands now reimburse proton treatments for pediatric and ocular malignancies, expanding addressable indications beyond research protocols.
- Hybrid Imaging Integration:MRI-guided radiotherapy systems combine real-time soft-tissue visualization with adaptive planning, attracting neuro-oncology departments in German university hospitals seeking sub-millimeter precision.
Market Restraints
- Isotope Supply Concentration:Cobalt-60 sourcing depends on aging Canadian and Russian nuclear reactors, exposing brachytherapy providers to radiochemical supply interruptions and price volatility.
- Proton Facility Economics:Cyclotron installations require EUR 150-200 million capital commitments and 4-5 year construction timelines, limiting deployment to national flagship centers in Paris, Heidelberg, and Milan.
- Software-as-Medical-Device Scrutiny:France's ANSM and Germany's BfArM apply divergent interpretive guidance to AI-driven dose optimization algorithms, fragmenting regulatory pathways for treatment planning vendors.
Strategic Opportunities
- Central European Expansion:Poland and Hungary maintain radiotherapy access gaps below EU average machine density, creating first-mover positioning for linac-as-a-service contracting models.
- Flash Radiotherapy Translation:Ultra-high dose rate electron and proton systems promise normal tissue sparing through oxygen depletion mechanisms, with clinical trials opening at Belgian and Dutch proton centers.
- EU AI Act Alignment:Machine learning classification rules for high-risk medical devices create compliance advisory demand, favoring vendors with pre-positioned clinical validation datasets across multiple member states.
Industry Challenges
- Medical Physics Workforce Scarcity:European training programs produce insufficient certified medical physicists to staff expanding proton and MR-linac installations, extending commissioning timelines.
- Interoperability Fragmentation:DICOM-RT and HL7 FHIR implementation varies across Elekta, Varian, and Siemens Healthineers ecosystems, complicating multi-vendor department workflows.
- Post-Market Surveillance Burden:MDR-mandated clinical follow-up registries for implanted fiducial markers and brachytherapy sources impose ongoing data collection costs on smaller national distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Radiotherapy Market |
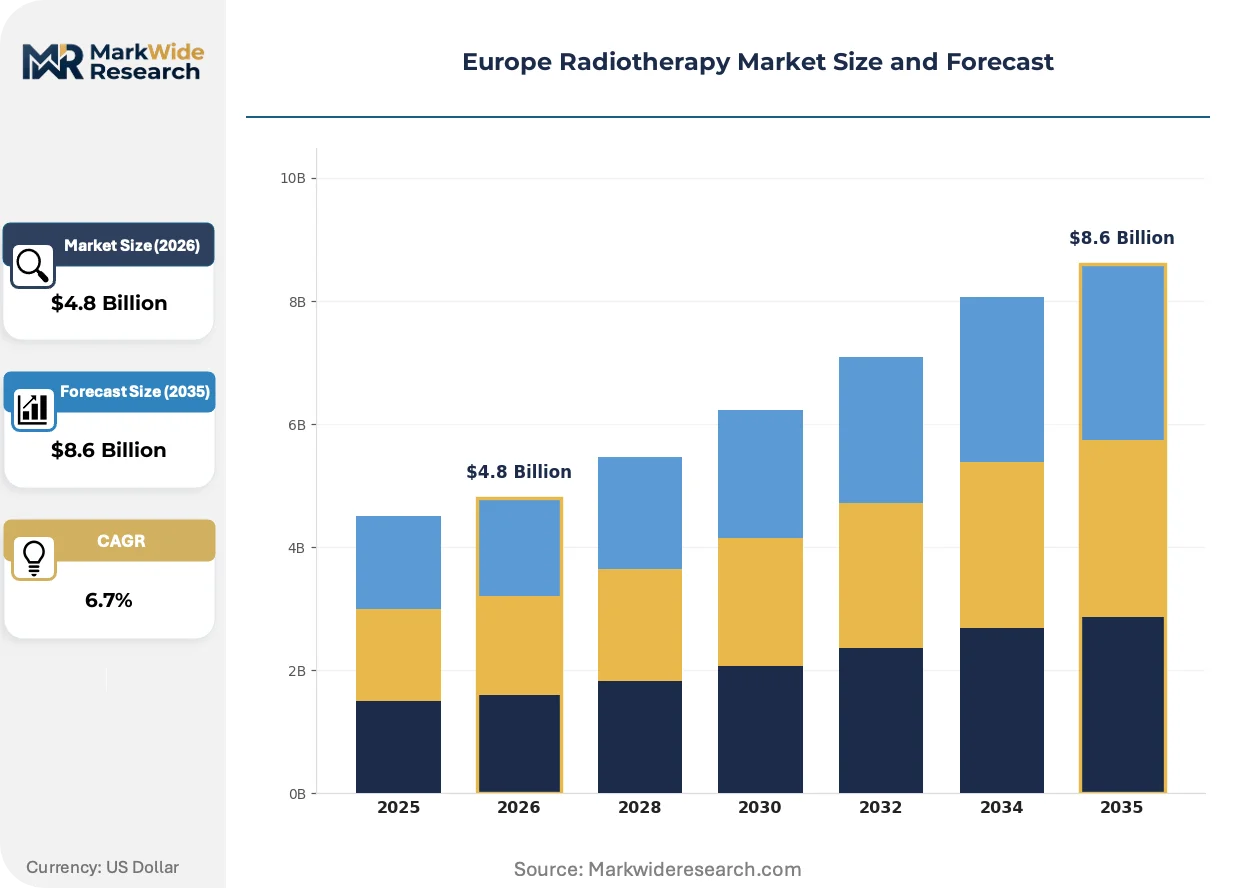
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Modality: External Beam, Brachytherapy, Stereotactic Radiosurgery, Proton Therapy End User: Hospitals, Cancer Clinics, Research Institutions, Academic Centers Technology Type: Traditional, Advanced, Digital, Hybrid Application Area: Oncology, Pediatrics, Neurosurgery, Palliative Care |
| Companies Covered | Varian Medical Systems Inc., Mevion Medical Systems, Siemens Healthineers AG, Nordion Inc., ViewRay Technologies Inc., Elekta AB, Ion Beam Applications SA, RaySearch Laboratories AB, Accuray Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Radiotherapy Market Trends and Innovations
Adaptive planning algorithms and real-time imaging feedback are compressing treatment margins while regulatory pressure on software validation accelerates vendor consolidation around integrated platform architectures.
MR-guided linear accelerator systems combine 1.5 Tesla diagnostic imaging with 6 MV photon delivery, enabling daily plan adaptation based on tumor and organ motion. Dutch and German head-and-neck oncology departments are adopting these platforms for oropharyngeal protocols where parotid sparing determines xerostomia outcomes. The technology is modularizing treatment workflows into distinct imaging, planning, and delivery components that hospitals can upgrade independently.
The EU AI Act's risk classification framework applies specific conformity assessment routes to machine learning algorithms embedded in treatment planning systems. France's ANSM has issued draft guidance distinguishing locked algorithms from continuously learning systems, creating divergent validation requirements. Vendors with static, pre-trained dose prediction models face lighter regulatory burdens than adaptive platforms, reshaping R&D prioritization across European development centers.
Hospital procurement departments are unbundling long-term service contracts from equipment financing, separating hardware lease arrangements from software maintenance and physicist support. French regional hospital groups and English NHS trusts now issue distinct tenders for linac hardware, treatment planning licenses, and clinical physics staffing. This disaggregation is most advanced in German university medicine clusters, where centralized procurement cooperatives negotiate multi-site framework agreements with modular component pricing.
Europe Radiotherapy Market Segmentation
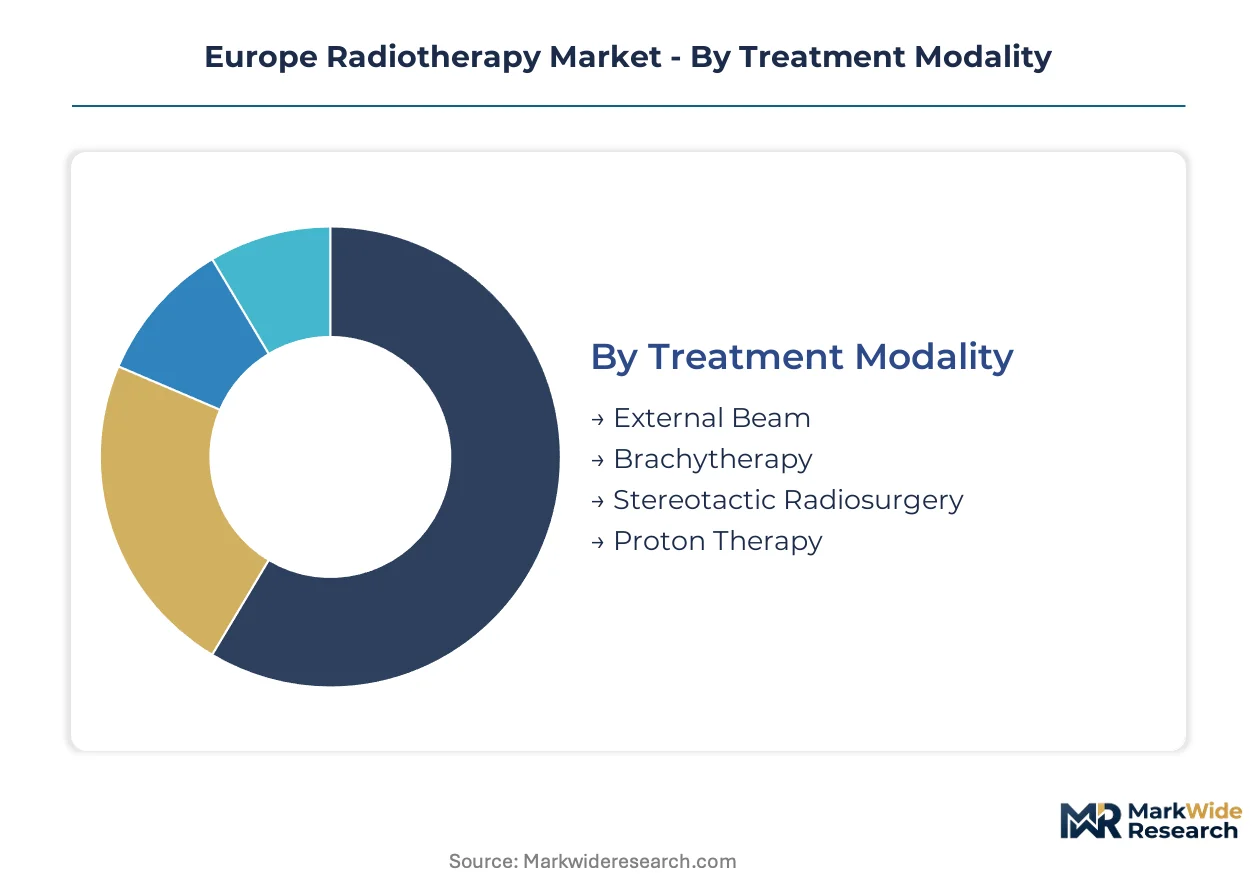
European radiotherapy procurement increasingly separates hardware, software, and service components into distinct purchasing decisions. Understanding how treatment modality, end user, technology type, and application area intersect reveals where upgrade cycles concentrate and which segments attract capital investment versus operational spending.
Treatment Modality:
Replacement cycles for aging cobalt-60 units and first-generation linear accelerators are synchronizing with MDR recertification deadlines, forcing modality-level portfolio decisions across hospital groups.
- External Beam:Linear accelerator systems delivering photon or electron beams via multi-leaf collimators dominate installed base across European oncology departments. German and Italian hospitals are prioritizing digital linac upgrades that integrate real-time imaging for adaptive workflows.
- Proton Therapy:Cyclotron-based proton beam systems deliver targeted dose with superior Bragg peak physics for pediatric and ocular malignancies. French and Dutch reimbursement authorities now cover proton treatments outside research protocols, accelerating gantry installations in Paris, Heidelberg, and Milan.
- Brachytherapy:Sealed radioactive source placement for gynecological and prostate applications maintains steady procedure volumes despite cobalt-60 supply volatility from aging reactor infrastructure.
- Stereotactic Radiosurgery:Single-session cranial ablation systems serve neurosurgery departments seeking non-invasive alternatives to tumor resection.
External Beam sits at the top of the volume ranking, with Proton Therapy climbing the fastest.
End User:
Procurement authority is fragmenting as regional hospital groups consolidate purchasing power while academic centers retain specialized technology selection autonomy.
- Hospitals:General acute care facilities with oncology departments represent the largest addressable base for standard linac replacements across France, Germany, and Italy.
- Cancer Clinics:Specialized outpatient facilities concentrate stereotactic and brachytherapy procedures in urban catchment areas with established referral networks.
- Research Institutions:National proton and heavy-ion centers in Belgium and the Netherlands host clinical trials for Flash radiotherapy and other experimental protocols.
- Academic Centers:University hospitals in Munich, Paris, and Rotterdam anchor hybrid imaging-radiotherapy integration with dedicated medical physics research programs.
Hospitals capture the largest procurement volume, though Academic Centers command the highest per-site technology investment.
Technology Type:
Software-defined functionality is displacing hardware-centric purchasing criteria as treatment planning algorithms become the primary differentiation point.
- Traditional:Cobalt-60 teletherapy and basic linear accelerator platforms without integrated imaging face accelerated retirement timelines under MDR clinical evidence requirements.
- Advanced:Image-guided and intensity-modulated systems with onboard cone-beam CT represent the current replacement standard for mid-tier European hospitals.
- Digital:Cloud-connected linacs with remote monitoring and automated quality assurance are penetrating German hospital networks seeking centralized fleet management.
- Hybrid:MRI-guided linear accelerator platforms combine 1.5 Tesla diagnostic imaging with photon delivery, enabling daily adaptive planning in Dutch and German head-and-neck oncology protocols.
Advanced technology holds the largest installed base, while Hybrid systems are expanding most quickly in university hospital settings.
Application Area:
Clinical indication specificity is driving modality selection as reimbursement pathways tighten around proven outcome metrics.
- Oncology:Solid tumor treatment across lung, breast, and prostate malignancies consumes the majority of external beam capacity in European cancer centers.
- Pediatrics:Proton therapy demand concentrates here due to reduced secondary malignancy risk and growing French and Dutch reimbursement coverage for childhood cancers.
- Neurosurgery:Stereotactic radiosurgery for brain metastases and arteriovenous malformations is displacing invasive cranial procedures in specialized centers.
- Palliative Care:Bone metastasis and symptomatic relief applications maintain steady linac utilization despite lower reimbursement rates.
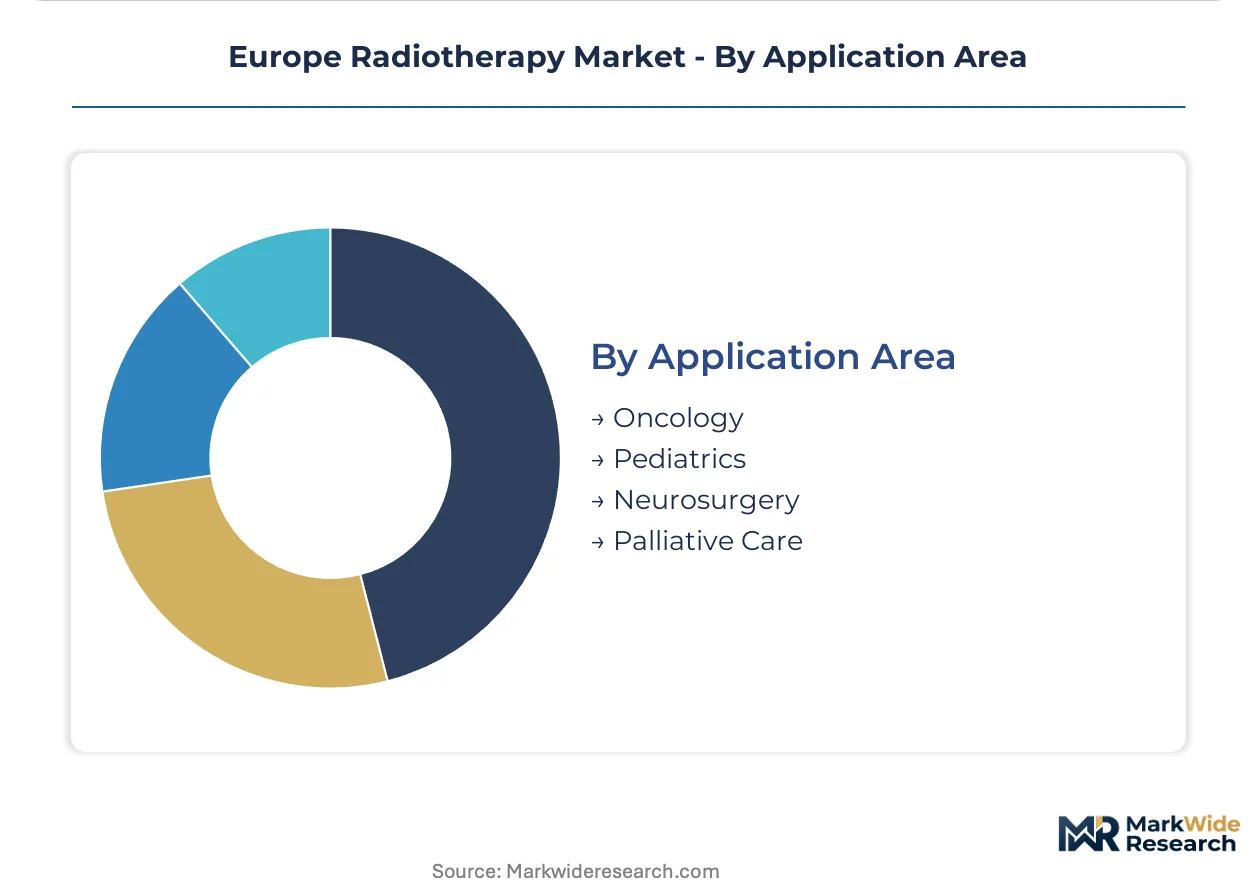
Oncology leads absolute procedure volume, with Pediatrics showing the steepest expansion trajectory as proton access broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical physicists and radiation oncologists concentrate in German university hospitals and French cancer centers, anchoring Europe's radiotherapy expertise. National reimbursement frameworks and EU regulatory harmonization shape where proton and hybrid imaging systems deploy. Country-level procurement patterns reveal divergent investment priorities across the continent.
Germany
University medicine clusters in Munich and Heidelberg drive demand for MRI-guided linear accelerators and proton therapy gantries. The BfArM applies stringent software-as-medical-device scrutiny to AI-driven dose optimization algorithms. The Heidelberg Ion-Beam Therapy Center anchors proton research and treats complex ocular and pediatric malignancies.
France
Regional hospital groups consolidate linac purchasing power while Parisian academic centers retain specialized technology autonomy. ANSM draft guidance distinguishes locked from continuously learning algorithms, fragmenting regulatory pathways for treatment planning vendors. The Institut Curie and Gustave Roussy anchor proton therapy expansion with new gantry installations.
Netherlands
Dutch health technology assessment bodies now reimburse proton treatments for pediatric cancers outside research protocols, expanding addressable indications. The Dutch Healthcare Authority shapes reimbursement pathways for advanced modalities through outcome-based contracting pilots. The proton center in Delft and Maastricht University Medical Center host Flash radiotherapy clinical trials.
Italy
Oncology departments in Milan and Rome synchronize linac replacement cycles with MDR recertification deadlines, forcing modality-level portfolio decisions. National competent authority coordination with EMA elevates clinical evidence requirements for new radiotherapy entrants. The Centro Nazionale di Adroterapia Oncologica in Pavia anchors proton therapy infrastructure development.
United Kingdom
NHS trusts unbundle long-term service contracts from equipment financing, issuing distinct tenders for linac hardware, planning licenses, and physics staffing. The Medicines and Healthcare products Regulatory Agency enforces MDR-aligned post-market surveillance for brachytherapy sources. The Christie Hospital in Manchester and University College London Hospitals anchor high-energy proton therapy capacity.
Europe Radiotherapy Market Competitive Landscape
Capital-heavy cyclotron manufacturers compete with asset-light treatment planning software developers for oncology department budgets. The vendor base concentrates around three tiers: integrated platform architects, modality-specific hardware specialists, and pure-play algorithm vendors. Elekta AB and Varian Medical Systems exemplify full-stack competitors, while RaySearch Laboratories and Ion Beam Applications occupy focused niches. Dominant competitive moves include M&A for software capabilities and strategic partnerships for proton center construction.
Within the integrated platform tier, Elekta AB and Varian Medical Systems occupy positions spanning linac hardware, treatment planning, and service contracts. Siemens Healthineers AG exemplifies the imaging-radiotherapy convergence archetype through its hybrid workflow installations. Ion Beam Applications SA anchors the proton therapy specialization segment with cyclotron supply to French and Belgian centers.
| Leading Market Players |
|---|
| Varian Medical Systems Inc. |
| Mevion Medical Systems |
| Siemens Healthineers AG |
| Nordion Inc. |
| ViewRay Technologies Inc. |
| Elekta AB |
| Ion Beam Applications SA |
| RaySearch Laboratories AB |
| Accuray Incorporated |
| Others |
Pricing and Supply Chain Analysis
EU MDR sustainability and circular economy mandates for medical device lifecycle documentation gate qualified supplier status and premium-tier pricing access for radiotherapy vendors serving French and German hospital networks. Compliance costs concentrate in software validation and post-market surveillance, forcing price stratification between certified and non-certified equipment tiers.
Pricing Analysis
The bundled-versus-unbundled service split distinguishes European radiotherapy procurement, with French regional hospital groups and English NHS trusts now separating hardware leases from software licenses and physicist support contracts. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier under MDR and after-sales service bundling. Cost compression in economy-tier linac replacements intensifies because Spanish and Italian oncology centers prioritize MDR recertification over feature upgrades. Academic centers in Heidelberg and Paris show least price sensitivity, while Polish and Hungarian regional hospitals exhibit highest sensitivity to upfront capital commitments.
Supply Chain Analysis
Logistics and freight costs for cobalt-60 isotope transport from Canadian and Russian reactor facilities impose radiochemical supply chain vulnerabilities on European brachytherapy providers. Cyclotron manufacturing concentrates in Belgium, Germany, and the United States, while multi-leaf collimator assemblies source from precision machining clusters in Switzerland and Germany. Supply chain risk centers on single-source vulnerability for superconducting magnet components in MRI-guided linac systems. Distribution runs through authorized national distributors holding BfArM and ANSM import licenses, with direct vendor relationships reserved for proton center megaprojects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's radiotherapy market functions as a stable compounder anchored by irreversible cancer incidence demographics and equipment replacement cycles synchronized to regulatory deadlines. MDR compliance creates predictable demand windows while proton therapy adoption opens premium expansion corridors.
For Market Incumbents: To counter software-as-a-service entrants disrupting treatment planning margins, Elekta and Varian should deepen backward integration into AI validation datasets across multiple member states while securing multi-site framework agreements with German university medicine clusters. Certification investment in EU AI Act conformity assessment routes protects installed base pricing power against algorithm-only competitors.
For New Entrants and Emerging Players: The price-point gap between premium MRI-guided systems and economy-tier digital linacs creates entry space for modular adaptive planning software targeting mid-tier Italian and Spanish hospitals. Poland and Hungary's radiotherapy access gaps below EU machine density represent the most penetrable geography. A linac-as-a-service contracting model with embedded physicist staffing bypasses capital-constrained procurement committees.
For Investors and Strategic Acquirers: Valuations sit cheapest among treatment planning software specialists lacking hardware integration, as MDR compliance costs compress pure-play algorithm margins. Long-term viability over the next decade rests on proton therapy cyclotron manufacturers with established French and Belgian reference sites. The signal to watch is Flash radiotherapy clinical trial readouts from Belgian and Dutch proton centers, which would trigger modality substitution investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway Acceleration | Early CE marking under tightened clinical evidence rules secures replacement cycle positioning in Italian and Spanish oncology centers. |
| Proton Center Construction Partnership | Cyclotron supply agreements with French and Belgian flagship hospitals anchor long-term service revenue streams. |
| EU AI Act Compliance Advisory | Pre-positioned clinical validation datasets across German and French regulatory jurisdictions differentiate machine learning vendors. |
| Hybrid Imaging Workflow Integration | MRI-linac platform penetration in Dutch and German head-and-neck departments captures adaptive planning upgrade cycles. |
| Central European Service Network Buildout | Localized physicist staffing and maintenance capabilities unlock Polish and Hungarian access-gap markets. |
Research Methodology
Bottom-up hospital and cancer clinic procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with radiation oncologists, medical physicists, hospital purchasing committee members, and GPO contracts managers informed equipment replacement timelines and budget allocation priorities. Secondary validation drew from EMA medical device registration databases, national competent authority reimbursement filings, hospital procurement registries, and vendor CE marking documentation. Cross-referencing manufacturer delivery schedules against national health technology assessment coverage decisions enabled installation base triangulation.
Historical trendline analysis of linear accelerator and proton therapy gantry deployments established baseline growth patterns across the projection horizon. The analytical framework segmented modeled outputs by treatment modality, technology tier, end-user institution type, and application area, with additional dimensioning by national reimbursement pathway. CAGRs were derived from fitted growth curves adjusted for MDR transition deadlines and proton therapy reimbursement expansion timelines. Forecast inputs incorporated health technology assessment body coverage decisions, cyclotron construction pipeline visibility, and medical physics workforce supply constraints.
The model assumes a particular technology adoption path; alternative pathways for Flash radiotherapy clinical translation would alter the outlook through accelerated proton center investment cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
US Radiation Oncology Market
Oncology
Triple-Negative Breast Cancer Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Metastatic Breast Cancer Market
Oncology
Metastatic Cancer Drug Market
Oncology
Europe Tumor Ablation Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Angiosarcomas Treatment Market
Oncology
Europe Proton Therapy Market
Oncology
Cancer/Tumor Profiling Market
Oncology
North America Bone Metastasis Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Epithelial Ovarian Cancer Market
Oncology
France Radiation Oncology Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market