
 Vulvar Cancer Market | 2026-2036
Vulvar Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Vulvar Cancer Market Outlook
Maintenance therapy subscriptions for post-surgical surveillance is consolidating as a distinct revenue layer in vulvar cancer care. Bristol-Myers Squibb Company leverages its immuno-oncology infrastructure to sustain presence in recurrent settings. Merck & Co., Inc. anchors the PD-1 inhibitor segment through established gynecologic indications. F. Hoffmann-La Roche Ltd differentiates with companion diagnostic integration that guides targeted therapy selection.
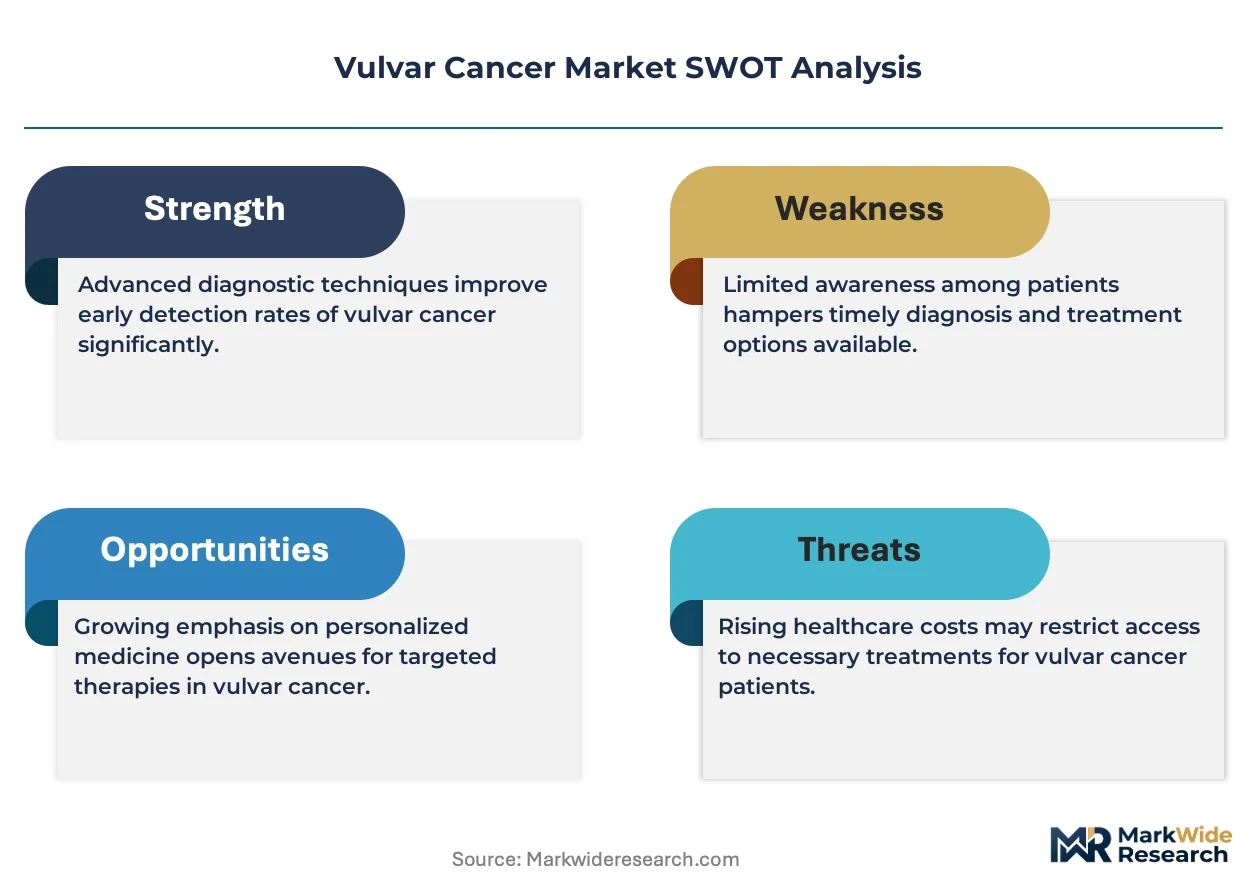
Vulvar cancer comprises malignant neoplasms arising from the external female genitalia, including squamous cell carcinomas, melanomas, and adenocarcinomas, with staging based on tumor size, nodal involvement, and metastatic spread per FIGO criteria. Treatment protocols integrate surgical excision with margin assessment, radiation therapy with brachytherapy boost capability, and systemic agents modulating immune checkpoint or angiogenic pathways. Chemotherapy retains the largest patient volume footprint due to neoadjuvant and palliative applications across stages. Targeted therapy captures the fastest expansion trajectory as biomarker-identified subsets gain reimbursable status. The hospitals end-user channel commands the deepest margin pools through bundled episode payments for radical procedures.
The FDA governs oncology drug approval through breakthrough and accelerated pathways, while the EMA's Committee for Medicinal Products for Human Use enforces centralized assessment for EU market access. ISO 14155 clinical investigation standards and ICH-GCP frameworks shape trial conduct across jurisdictions, directly influencing development timelines and evidence requirements for registrational studies. Stakeholders must monitor biomarker-driven label expansions and companion diagnostic co-development obligations as the competitive set evolves.
Market Dynamics
FDA accelerated approval pathways for oncology biologics are compressing development timelines and enabling earlier competitive entry in recurrent vulvar cancer settings. This regulatory velocity is reshaping how immuno-oncology assets reach post-surgical maintenance populations.
Growth Catalysts
- Companion diagnostic integration:Biomarker-guided patient selection for PD-1 inhibitors is expanding reimbursable indications in gynecologic oncology practices.
- Specialty clinic infrastructure:Dedicated gynecologic malignancy centers in the United States, Germany, and Japan are consolidating referral networks for complex cases.
- Brachytherapy capability expansion:Advanced radiation delivery systems are enabling curative-intent treatment for locally advanced disease previously managed with palliative intent.
Market Restraints
- Platinum agent supply concentration:Neoadjuvant chemotherapy protocols depend on carboplatin and paclitaxel inputs with limited qualified manufacturing sources.
- HPV vaccination penetration gaps:Uneven coverage rates in preventive programs sustain incident case volumes that could otherwise decline.
- FIGO staging complexity:Nodal assessment variability across pathology networks complicates trial endpoint standardization and cross-study comparison.
Strategic Opportunities
- Maintenance therapy subscription models:Post-surgical surveillance protocols present recurring revenue structures distinct from acute intervention billing.
- Angiogenesis inhibitor combinations:VEGF pathway modulation paired with checkpoint blockade offers mechanistic rationale for label expansion.
- Japan's geriatric oncology infrastructure:Aging demographics and established PMDA consultation frameworks support targeted development for elderly populations.
Industry Challenges
- Gynecologic pathology subspecialist scarcity:Accurate margin assessment and sentinel node evaluation require fellowship-trained practitioners concentrated at academic centers.
- ICH-GCP compliance burden:Multi-regional trials for rare malignancies face protocol harmonization costs across FDA and EMA jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vulvar Cancer Market |
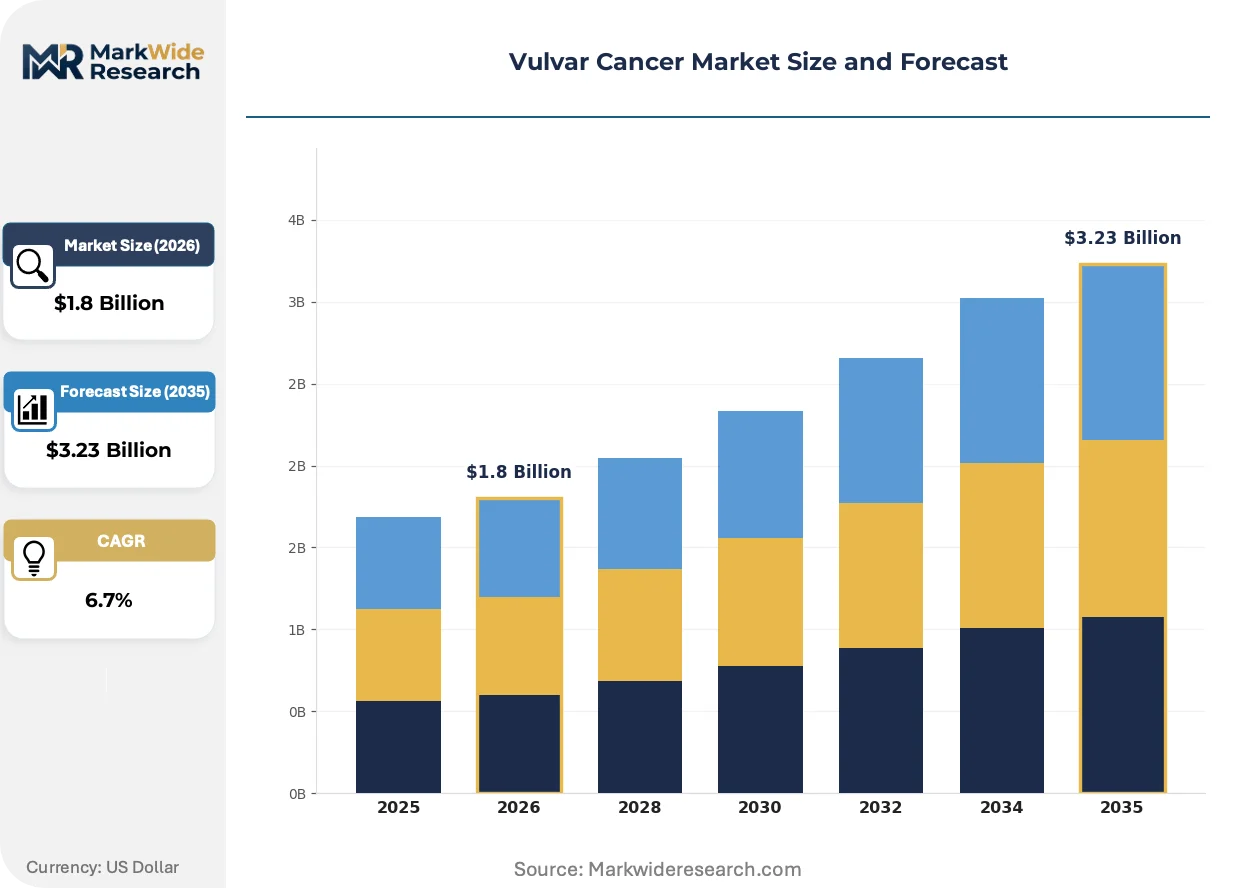
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiotherapy, Surgery, Targeted Therapy End User: Hospitals, Specialty Clinics, Research Institutions, Home Care Delivery Mode: Oral, Intravenous, Topical, Injectable Treatment Phase: Adjuvant, Neoadjuvant, Palliative, Curative |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Novartis AG, GlaxoSmithKline plc, AstraZeneca, Pfizer Inc., Sanofi, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vulvar Cancer Market Strategic Shifts
Immuno-oncology is displacing cytotoxic chemotherapy as the backbone of systemic therapy in recurrent settings. Three convergent developments are accelerating this transition.
Next-generation sequencing panels are expanding into routine vulvar cancer workups at comprehensive cancer centers in the United States and Germany. Pathology departments are adopting tumor mutational burden and microsatellite instability testing as standard-of-care prerequisites for checkpoint inhibitor authorization. This molecular infrastructure is expanding into community oncology practices previously limited to histologic diagnosis alone.
EMA's Committee for Medicinal Products for Human Use has tightened evidentiary standards for conditional marketing authorizations in gynecologic malignancies. The centralized assessment process now demands mature overall survival data rather than progression-free survival surrogates for full approval. European reference pricing systems are responding by delaying reimbursement until confirmatory trial readouts, compressing early-revenue windows for accelerated approvals.
Episode-based payment structures are consolidating surgical and radiation services at high-volume hospitals. Bundled reimbursement for radical vulvectomy with inguinal lymphadenectomy is concentrating cases at designated gynecologic oncology centers. Germany's Diagnosis-Related Group system and United States accountable care organization contracts are both reinforcing this site-of-care migration away from general gynecology practices.
Vulvar Cancer Market Segmentation
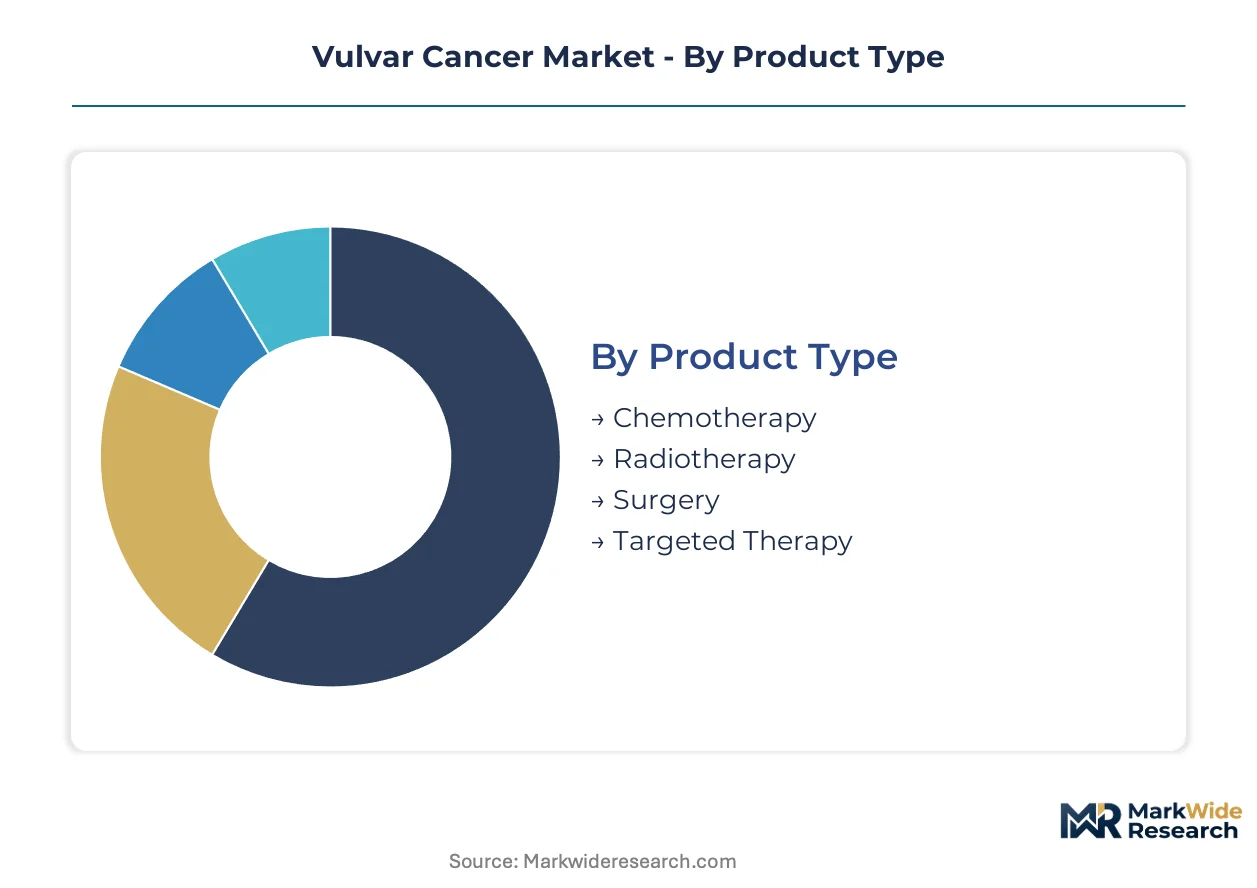
Vulvar cancer treatment pathways fragment across intervention modalities, care settings, and disease stages. Segmentation reveals where procurement budgets concentrate and which delivery formats command premium reimbursement.
Product Type:
Supply concentration for platinum agents and checkpoint inhibitors shapes competitive positioning across intervention categories.
- Chemotherapy:Carboplatin and paclitaxel combinations retain the broadest patient volume footprint across neoadjuvant and palliative protocols. Demand concentrates in United States academic medical centers and German university hospitals where gynecologic oncology fellowship programs sustain protocol adherence.
- Targeted Therapy:PD-1 inhibitors and angiogenesis modulators require companion diagnostic infrastructure for reimbursable deployment. United States comprehensive cancer centers and Japan's National Cancer Center network are consolidating adoption through biomarker-guided patient selection pathways.
- Radiotherapy:External beam delivery with brachytherapy boost capability enables curative-intent management of locally advanced disease.
- Surgery:Radical vulvectomy with inguinal lymphadenectomy remains the definitive intervention for early-stage presentations.
Chemotherapy absorbs the bulk of installed capacity; targeted therapy is expanding most quickly.
End User:
Margin structures vary sharply by site-of-care certification and episode bundling arrangements.
- Hospitals:Designated gynecologic oncology centers in the United States and Germany capture bundled episode payments for radical procedures. Accountable care organization contracts and Diagnosis-Related Group reimbursement concentrate complex cases at high-volume academic facilities.
- Specialty Clinics:Dedicated gynecologic malignancy centers in Japan and selected United States metropolitan markets are expanding maintenance therapy subscription models. Post-surgical surveillance protocols generate recurring revenue distinct from acute intervention billing.
- Research Institutions:Phase I and II trial enrollment concentrates at NCI-designated comprehensive cancer centers.
- Home Care:Oral checkpoint inhibitor formulations enable limited administration outside institutional settings.
Hospitals command the deepest margin pools; specialty clinics are climbing the fastest as referral networks consolidate.
Delivery Mode:
Formulation development costs and cold-chain requirements segment manufacturing economics.
- Intravenous:Checkpoint inhibitors and platinum agents require infusion center infrastructure with adverse event monitoring capability. United States hospital outpatient departments and German day-clinic networks dominate administration volume.
- Oral:PARP inhibitors and selected targeted agents enable patient-administered maintenance protocols. Japan's geriatric oncology infrastructure supports adherence monitoring for elderly populations.
- Injectable:Subcutaneous checkpoint inhibitor formulations reduce infusion chair time at specialty clinics.
- Topical:Limited to superficial lesion management and symptom palliation in home care settings.
Intravenous delivery retains the largest volume footprint; oral formulations are gaining share fastest through maintenance therapy expansion.
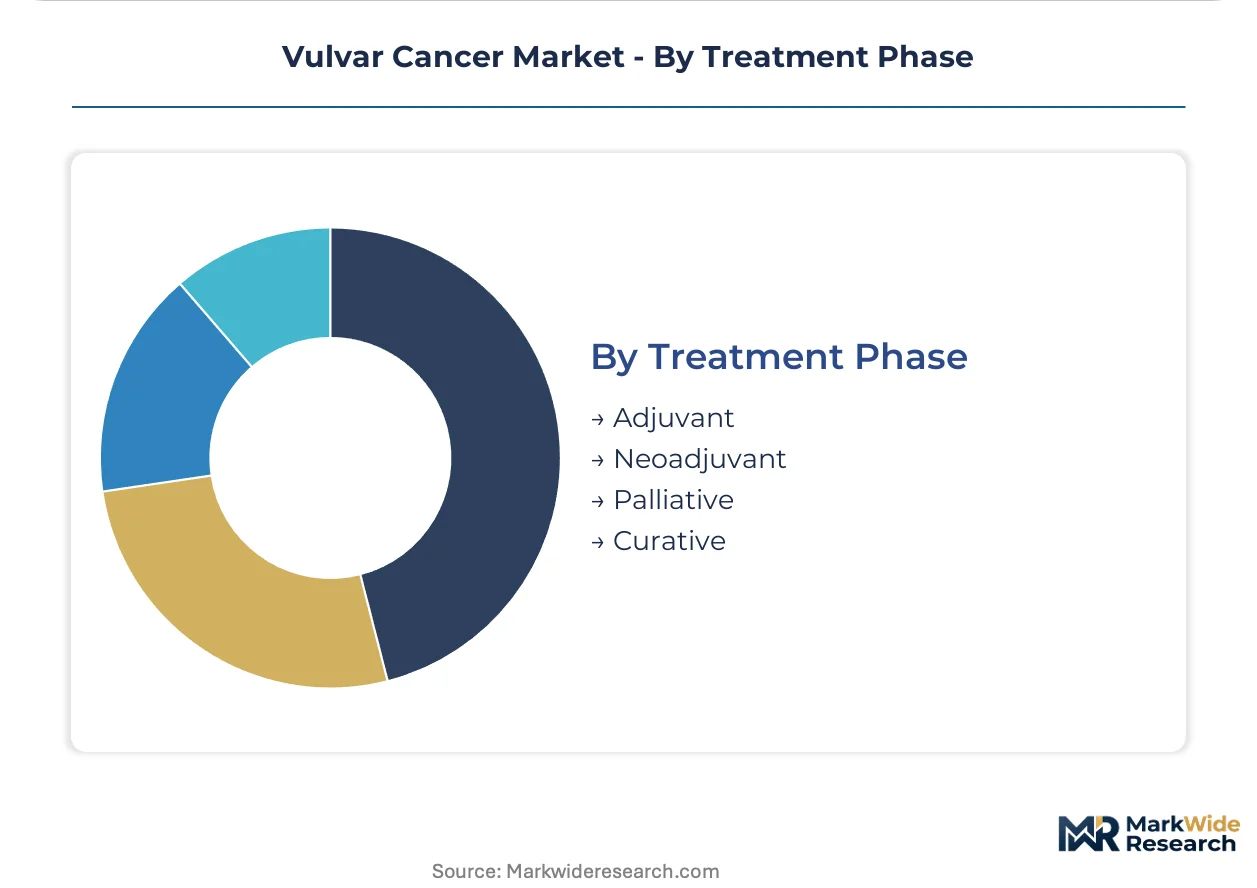
Treatment Phase:
Reimbursement timing and evidence requirements vary across curative and palliative intent designations.
- Neoadjuvant:Systemic therapy preceding surgical intervention aims to reduce tumor burden and enable organ-sparing approaches. United States and German academic centers are expanding protocol adoption for locally advanced presentations.
- Adjuvant:Post-surgical radiation or systemic therapy targets residual microscopic disease. Japan's PMDA consultation frameworks support targeted development for elderly adjuvant populations.
- Curative:Definitive intent protocols integrate surgery, radiation, and selected systemic agents.
- Palliative:Symptom-focused interventions concentrate at hospice-affiliated hospitals and selected home care programs.
Neoadjuvant protocols absorb expanding capacity as downstaging strategies proliferate; adjuvant applications show steepest expansion trajectory through maintenance therapy subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical trial infrastructure and reimbursement density separate consumption from manufacturing in oncology therapeutics. The United States absorbs the largest share of checkpoint inhibitor value despite API production concentrating in Switzerland and Ireland. Germany and Japan follow as distinct demand centers with divergent regulatory pacing.
United States
NCI-designated comprehensive cancer centers and accountable care organization contracts concentrate complex case management. FDA breakthrough therapy designation accelerates PD-1 inhibitor access for recurrent disease. The MD Anderson Cancer Center and Memorial Sloan Kettering Cancer Center anchor gynecologic oncology fellowship training that sustains protocol adherence.
Germany
Diagnosis-Related Group reimbursement for radical vulvectomy bundles concentrates surgical volume at university hospitals. EMA centralized assessment timelines delay full approval relative to FDA pathways. The Heidelberg and Munich metropolitan areas host gynecologic malignancy centers with integrated pathology subspecialist networks.
Japan
PMDA consultation frameworks support targeted development for elderly adjuvant populations where median age at diagnosis exceeds 70 years. National Health Insurance price listing requires domestic clinical trial participation. The National Cancer Center Hospital and Osaka International Cancer Institute drive biomarker-guided patient selection adoption.
United Kingdom
NHS England specialized commissioning concentrates vulvar cancer surgery at 19 designated gynecologic oncology centers. NICE technology appraisals impose cost-effectiveness thresholds that delay checkpoint inhibitor reimbursement relative to FDA approval. The Royal Marsden and Christie Hospital anchor molecular diagnostic infrastructure for trial enrollment.
Switzerland
Swissmedic parallel review with EMA enables rapid market access for oncology biologics manufactured domestically. High per-capita spending on cancer care supports early adoption of companion diagnostic platforms. Basel and Zurich host pharmaceutical manufacturing clusters that supply API for global checkpoint inhibitor production.
Vulvar Cancer Market Competitive Environment
Capital-heavy producers with integrated biologics manufacturing compete with asset-light developers licensing antibody platforms. The market structure consolidates around immuno-oncology franchises with established gynecologic indications. Three archetypes dominate: checkpoint inhibitor specialists with diagnostic partnerships, diversified oncology majors with radiation synergy portfolios, and biologics manufacturers with CMO relationships. Competitive moves center on companion diagnostic co-development obligations and maintenance therapy label expansions.
Within the checkpoint inhibitor tier, Merck & Co., Inc. and Bristol-Myers Squibb Company exemplify franchise defenders leveraging PD-1 infrastructure across gynecologic malignancies. F. Hoffmann-La Roche Ltd occupies a position bridging therapeutic and diagnostic capabilities through integrated biomarker platforms. These three entities represent distinct strategic postures: volume-driven standard-of-care establishment, combination regimen exploration, and personalized medicine architecture.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| GlaxoSmithKline plc |
| AstraZeneca |
| Pfizer Inc. |
| Sanofi |
| Johnson & Johnson Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
Checkpoint inhibitor manufacturing scale-up is compressing per-dose production economics while concentrating API sourcing among Swiss and Irish contract manufacturers. This dual shift simultaneously reduces marginal treatment costs and tightens supply control among biologics specialists with validated cold-chain infrastructure.
Pricing Analysis
Margin tightening in PD-1 inhibitor tiers reflects EMA's tightened evidentiary standards demanding mature overall survival data before full approval. Three-tier pricing structure across premium biologics, standard chemotherapy, and economy palliative protocols segments patient access by biomarker eligibility and reimbursement timing. Cost-down pressure on platinum agents accelerates because carboplatin supply concentrates among limited qualified manufacturers. Community oncology practices exhibit highest price sensitivity; NCI-designated centers command procurement leverage through volume commitments.
Supply Chain Analysis
Single-source vulnerability sits with platinum agent API manufacturing concentrated in Switzerland, Ireland, and selected United States facilities. Checkpoint inhibitor production draws from mammalian cell culture inputs, single-use bioreactor systems, and cold-chain logistics networks. Tariff exposure on Chinese-sourced raw materials presents structural risk to margin stability. Distribution runs through hospital outpatient departments and specialty clinic infusion centers with adverse event monitoring capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA accelerated approval pathways and EMA's tightened evidentiary standards create a cost-of-compliance moat favoring incumbents with established regulatory affairs infrastructure and companion diagnostic partnerships.
For Market Incumbents: Hedge against biosimilar entry by deepening biomarker-guided label expansions and securing exclusive pathology network contracts for companion diagnostic deployment. Threat vectors include emerging developers licensing antibody platforms and EMA's progression-free survival surrogate rejection. Priority levers center on vertical integration into diagnostic co-development and capacity addition in Basel-Zurich manufacturing clusters. For New Entrants and Emerging Players: Capture white-space in Japan's geriatric adjuvant populations and United States maintenance therapy subscription models where incumbent presence remains underdeveloped. The most penetrable segment sits with oral PARP inhibitor formulations enabling home-administered surveillance protocols. Go-to-market angles should emphasize PMDA consultation framework navigation and elderly adherence monitoring infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by checkpoint inhibitor specialists seeking biomarker platform augmentation or diversified oncology majors building radiation synergy portfolios. Long-term viability framing favors developers with integrated diagnostic-therapeutic capabilities over asset-light licensors. The signal to watch is FDA breakthrough therapy designation velocity for recurrent vulvar cancer indications as inflection indicator for valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Biomarker integration with PD-1 inhibitors expands reimbursable patient populations at United States comprehensive cancer centers. |
| Maintenance Therapy Label Expansion | Post-surgical surveillance protocols generate recurring revenue distinct from acute intervention billing at specialty clinics. |
| Japan PMDA Consultation Engagement | Geriatric oncology infrastructure supports targeted development for elderly populations where median diagnosis age exceeds 70 years. |
| Brachytherapy Capability Investment | Advanced radiation delivery systems enable curative-intent treatment for locally advanced disease previously managed palliatively. |
| Academic Center Pathology Network Contracts | Fellowship-trained gynecologic subspecialists at NCI-designated centers sustain protocol adherence and trial enrollment velocity. |
Study Parameters
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from SEC 10-K disclosures, CMS Medicare reimbursement data, and gynecologic oncology society treatment guidelines. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Cross-referencing historical approval timelines against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include treatment phase, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derived from therapeutic class adoption curves, biomarker penetration rates, and episode-based reimbursement expansion trajectories. Forecast inputs incorporated companion diagnostic authorization velocity and maintenance therapy protocol adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA evidentiary standard shifts, HPV vaccination penetration gaps, and platinum agent supply disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Pituitary Cancer Market
Oncology
Angiosarcomas Treatment Market
Oncology
North America Proton Therapy Market
Oncology
Particle Therapy Systems Market
Oncology
Paraneoplastic Syndromes Market
Oncology
Cancer API Market
Oncology
Global Cancer Profiling Market
Oncology
Global Cancer Treatment Market
Oncology
Gynecological Cancers Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Global Proton Therapy Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Head and Neck Cancer Market
Oncology
North America Bone Metastasis Market
Oncology
Global Metastatic Cancer Treatment Market