
 Pancreatic Cancer Market | 2026-2036
Pancreatic Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Pancreatic Cancer Market Intelligence
Buyer concentration among oncology centers is shifting as large hospital networks consolidate pancreatic cancer care into dedicated multidisciplinary programs. Pfizer Inc. leverages its broad oncology infrastructure to sustain clinical trial access across these consolidated centers. Bristol-Myers Squibb Company anchors immuno-oncology development through its checkpoint inhibitor portfolio. Eli Lilly and Company differentiates via targeted therapy pipelines addressing KRAS-mutant subpopulations.
Pancreatic cancer encompasses malignancies arising from exocrine or endocrine pancreatic tissue, characterized by dense desmoplastic stroma, late-stage detection, and reliance on CA 19-9 biomarker monitoring combined with cross-sectional imaging for diagnosis and staging. The disease demands systemic therapy integration with surgical resection where anatomically feasible. Immunotherapy agents represent the fastest-expanding product category as PD-1/PD-L1 combinations gain regulatory traction in frontline settings. Early-stage treatment commands premium pricing due to curative-intent surgical eligibility, while palliative care segments face margin compression from biosimilar chemotherapy entry. Delivery mode preferences increasingly favor intravenous injection for combination regimens requiring precise dosing control.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines for novel pancreatic cancer agents, while WHO essential medicines criteria influence national reimbursement decisions in lower-income markets. The EU AI Act and FDA software-as-medical-device guidance are reshaping computational diagnostic tools used in radiomic tumor characterization. Stakeholders must monitor evolving biomarker regulatory requirements to align pipeline investments with payer coverage thresholds.
Market Dynamics
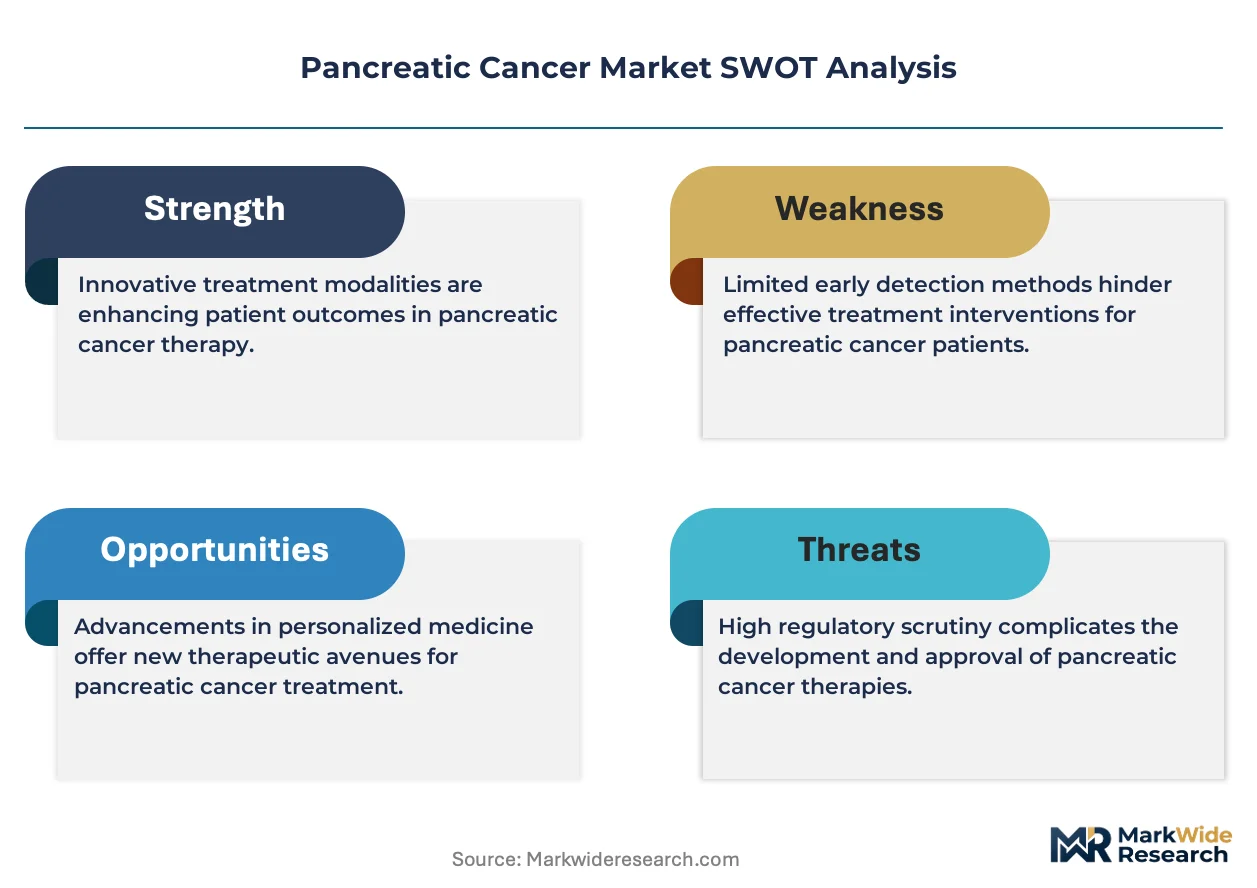
FDA breakthrough therapy designation and companion diagnostic mandates are compressing development timelines for novel pancreatic cancer agents, forcing pharmaceutical developers to restructure clinical trial protocols around biomarker-enriched patient populations rather than broad eligibility criteria.
Growth Catalysts
- EMA Priority Medicines Pathway:The European Medicines Agency's accelerated assessment mechanism shortens regulatory review periods for pancreatic cancer therapies addressing unmet medical need.
- Liquid Biopsy Adoption:Circulating tumor DNA testing is expanding into community oncology settings, enabling molecular profiling without invasive tissue sampling.
- Japan's Specialized Cancer Center Network:The concentration of pancreatic cancer expertise at designated national hospitals creates efficient trial recruitment infrastructure.
Market Restraints
- Desmoplastic Stroma Barrier:Dense fibrotic tissue surrounding pancreatic tumors physically impedes drug penetration, limiting systemic agent efficacy regardless of molecular target.
- Platinum Supply Concentration:Gemcitabine and FOLFIRINOX regimens depend on platinum-based compounds sourced from concentrated mining operations in South Africa and Russia.
- WHO Essential Medicines Criteria:Stringent cost-effectiveness thresholds for inclusion limit reimbursement access in lower-income health systems.
Strategic Opportunities
- India's PLI Scheme Expansion:Production-linked incentives for active pharmaceutical ingredients reduce import dependency for generic chemotherapy manufacturing.
- Radiomics-PD-L1 Convergence:Computational imaging analysis combined with immune checkpoint expression profiling enables non-invasive treatment response prediction.
- Direct-to-Patient Genetic Counseling:Telemedicine platforms bypass traditional hospital-based referral pathways for hereditary pancreatic cancer screening.
Industry Challenges
- Interventional Radiology Talent Pipeline:Shortage of physicians trained in endoscopic ultrasound-guided fine needle aspiration limits diagnostic throughput at high-volume centers.
- Multi-Omic Data Integration:Synthesizing genomic, transcriptomic, and proteomic datasets into clinically actionable formats requires specialized bioinformatics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancreatic Cancer Market |
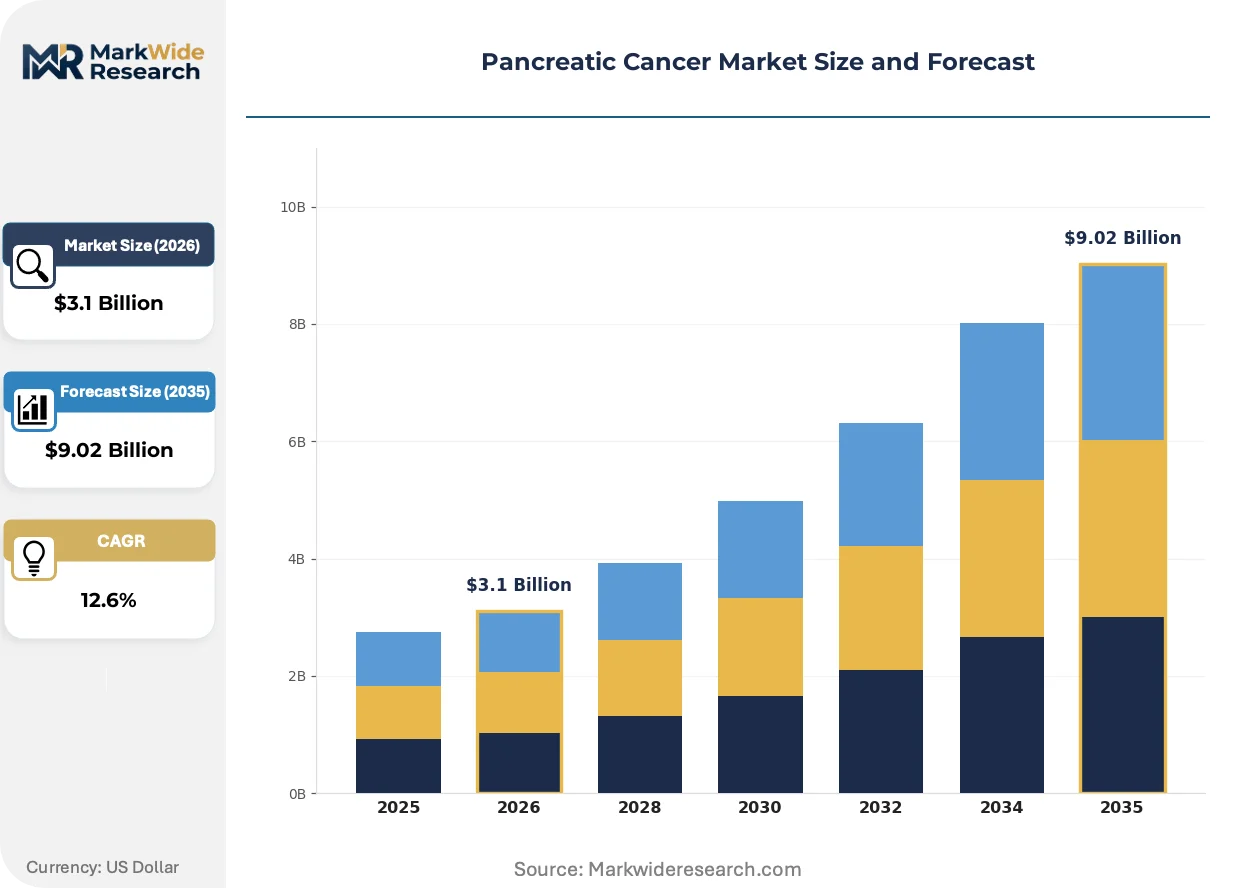
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $9.02 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Chemotherapy Drugs, Immunotherapy Agents, Targeted Therapy, Surgical Instruments Therapy Area: Early-Stage Treatment, Advanced-Stage Management, Palliative Care, Post-Surgical Recovery End User: Oncology Centers, Specialty Clinics, Research Institutes, Home Healthcare Providers Delivery Mode: Oral Administration, Intravenous Injection, Subcutaneous Injection, Implantable Devices |
| Companies Covered | Pfizer Inc., F. Hoffmann-La Roche Ltd, AstraZeneca, Novartis AG, Eli Lilly and Company, Bristol-Myers Squibb Company, Amgen Inc., Bayer AG, Teva Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancreatic Cancer Market Strategic Shifts & Innovations
Artificial intelligence is penetrating pancreatic cancer care through computational pathology and treatment response modeling, reshaping how multidisciplinary teams synthesize complex diagnostic information into therapeutic decisions.
Multiparametric MRI with radiomic feature extraction is integrating quantitative imaging biomarkers into routine staging protocols. Major academic medical centers in the United States and Germany are deploying these tools to predict surgical resectability before laparotomy. This technology is integrating preoperative decision-making with neoadjuvant chemotherapy sequencing, compressing the timeline between diagnosis and definitive intervention.
The EU AI Act's risk classification framework for medical device software is imposing conformity assessment requirements on radiomic tumor characterization tools. Developers must now demonstrate algorithmic transparency and clinical validation against retrospective cohorts. Pancreatic cancer imaging applications face heightened scrutiny given their role in irreversible treatment decisions, prompting vendors to establish quality management systems exceeding prior CE marking standards.
Consolidated hospital networks are unbundling molecular diagnostic services from traditional pathology departments. Specialized reference laboratories now contract directly with oncology centers for next-generation sequencing panels, displacing in-house testing infrastructure. This restructuring concentrates expertise at centralized facilities while reducing capital requirements for individual hospitals, particularly visible in the United States where independent laboratory networks serve dispersed community oncology practices.
Pancreatic Cancer Market Segmentation
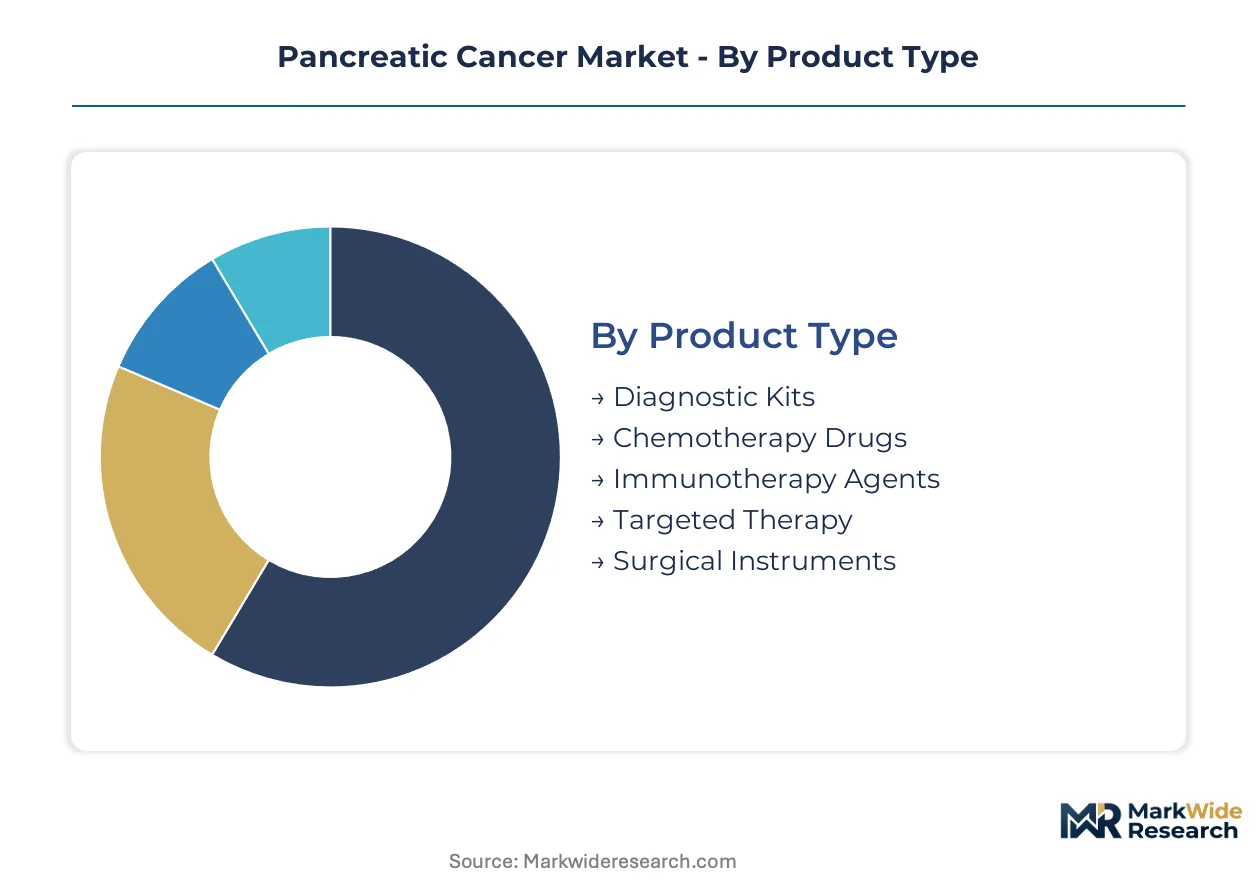
Pancreatic cancer market segmentation reflects divergent regulatory pathways and reimbursement thresholds across diagnostic, therapeutic, and surgical modalities. Each category carries distinct FDA, EMA, and national health technology assessment requirements that shape commercial strategy and portfolio prioritization.
Product Type:
Certification burdens vary sharply across this category: diagnostic kits face FDA 510(k) or PMA pathways plus CLIA laboratory regulations, chemotherapy drugs require full NDA approval with manufacturing GMP compliance, immunotherapy agents trigger breakthrough therapy designation protocols, targeted therapies mandate companion diagnostic co-development, and surgical instruments fall under MDR Class IIa/IIb CE marking in Europe.
- Diagnostic Kits:CA 19-9 immunoassays and next-generation sequencing panels detect molecular biomarkers from blood or tissue specimens. Demand concentrates at oncology centers in the United States and Germany where multidisciplinary tumor boards mandate upfront molecular profiling to guide therapy selection, constrained by reimbursement variability for liquid biopsy platforms.
- Immunotherapy Agents:PD-1 and PD-L1 checkpoint inhibitors administered as monotherapy or combination regimens. Demand concentrates in Japan's designated cancer center network where frontline immunotherapy protocols are expanding fastest, driven by PMDA accelerated approval pathways compressing time-to-market.
- Chemotherapy Drugs:Gemcitabine-based regimens and FOLFIRINOX combinations remain standard-of-care backbone therapies.
- Targeted Therapy:KRAS G12C inhibitors and PARP inhibitors address genetically defined subpopulations.
- Surgical Instruments:Specialized retractors, energy devices, and staplers optimized for pancreatic resection procedures.
Leading the category by volume: Chemotherapy Drugs. Growing fastest: Immunotherapy Agents.
Therapy Area:
Cost tiers stratify sharply across this category: early-stage treatment commands premium pricing for curative-intent surgical eligibility and neoadjuvant protocols, advanced-stage management occupies mid-tier reimbursement with combination therapy bundling, palliative care faces margin compression from biosimilar entry, and post-surgical recovery carries episodic payment structures.
- Early-Stage Treatment:Neoadjuvant chemotherapy, surgical resection, and adjuvant therapy for resectable or borderline resectable disease. Demand concentrates at high-volume academic medical centers in the United States where multiparametric MRI and EUS staging capabilities enable patient selection, driven by bundled payment models rewarding complete resection rates.
- Palliative Care:Pain management, biliary drainage procedures, and quality-of-life focused systemic therapy for metastatic disease. Demand concentrates in Germany's regional cancer networks where hospice-integrated pathways are standard, constrained by reference pricing for generic chemotherapy agents.
- Advanced-Stage Management:First-line and second-line systemic therapy for locally advanced or metastatic disease.
- Post-Surgical Recovery:Surveillance imaging, biomarker monitoring, and recurrence detection protocols.
Commanding highest price per patient: Early-Stage Treatment. Expanding most quickly: Palliative Care as population aging extends metastatic disease prevalence.
End User:
Customer types exhibit divergent procurement sophistication: oncology centers deploy centralized purchasing for high-cost biologics, specialty clinics rely on group purchasing organizations, research institutes access investigational agents through clinical trial frameworks, and home healthcare providers navigate limited infusion reimbursement.
- Oncology Centers:Comprehensive cancer centers and hospital-based oncology departments delivering integrated multidisciplinary care. Demand concentrates in the United States where NCI-designated centers anchor clinical trial networks, driven by Medicare reimbursement for hospital outpatient department administration of infused therapies.
- Research Institutes:Academic medical centers and contract research organizations conducting phase I-III clinical trials. Demand concentrates in Japan's national hospital organization where specialized pancreatic cancer expertise enables efficient patient recruitment, supported by METI funding for innovative drug development infrastructure.
- Specialty Clinics:Community oncology practices and gastrointestinal-focused ambulatory centers.
- Home Healthcare Providers:Infusion nursing services and palliative care agencies delivering subcutaneous or oral therapy in residential settings.
Capturing highest therapy revenue per patient: Oncology Centers. Gaining share fastest: Research Institutes as biomarker-enriched trial designs concentrate expertise.
Delivery Mode:
Supply concentration patterns differentiate this category: intravenous injection depends on hospital pharmacy compounding and infusion center capacity, oral administration leverages retail and specialty pharmacy distribution, subcutaneous injection bridges clinical and home settings, and implantable devices require interventional radiology placement.
- Intravenous Injection:Infusion of combination chemotherapy, immunotherapy, and supportive care agents requiring precise dosing control and monitoring. Demand concentrates in Germany's university hospital network where day-clinic infrastructure supports intensive regimens, driven by EMA guidelines mandating cardiac and hepatic monitoring for certain combinations.
- Oral Administration:Targeted therapy capsules and tablets enabling outpatient treatment without infusion infrastructure. Demand concentrates in the United States where specialty pharmacy distribution networks support patient adherence programs, constrained by Medicare Part D coverage gap implications for high-cost oral oncology drugs.
- Subcutaneous Injection:Growth factor support and selected biologic agents administered via prefilled syringes.
- Implantable Devices:Hepatic arterial infusion pumps and intrathecal drug delivery systems for selected indications.
Dominating current treatment volume: Intravenous Injection. Climbing the fastest: Oral Administration as fixed-dose combination targeted therapies advance through regulatory pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology centers cluster in the United States, Germany, and Japan where specialized pancreatic cancer expertise concentrates trial recruitment and biomarker-driven treatment adoption.
United States
NCI-designated comprehensive cancer centers anchor clinical trial networks and multidisciplinary tumor board infrastructure. FDA breakthrough therapy designation compresses development timelines for novel agents. The Greater Boston and San Francisco Bay Area biotech clusters host concentrated immuno-oncology development pipelines.
Germany
University hospital networks deliver integrated day-clinic chemotherapy infrastructure with cardiac and hepatic monitoring capabilities. EMA priority medicines pathways accelerate regulatory assessment for pancreatic cancer therapies. The Heidelberg and Munich metropolitan areas concentrate specialized pancreatic surgery expertise and reference laboratory capacity.
Japan
Designated national cancer centers create efficient patient recruitment infrastructure for biomarker-enriched trial designs. PMDA accelerated approval pathways expand frontline immunotherapy protocol adoption. The Tokyo and Osaka metropolitan clusters concentrate gastrointestinal oncology specialization and METI-funded drug development infrastructure.
United Kingdom
Regional cancer networks integrate hospice pathways with systemic therapy delivery for metastatic disease management. NICE technology appraisals shape reimbursement thresholds for novel agents. The London and Manchester metropolitan areas concentrate academic medical center capacity and early-phase trial units.
India
Production-linked incentive schemes for active pharmaceutical ingredients reduce import dependency for generic chemotherapy manufacturing. CDSCO regulatory pathways govern biosimilar approval timelines for gemcitabine-based regimens. The Mumbai-Pune and Hyderabad clusters concentrate contract manufacturing organization capacity for oncology APIs.
Pancreatic Cancer Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue radiomics-PD-L1 convergence and direct-to-patient genetic counseling platforms. The market structure consolidates around large pharmaceutical conglomerates with broad oncology infrastructure alongside specialized biotech developers targeting KRAS-mutant subpopulations. Three archetypes dominate: checkpoint inhibitor portfolio holders, targeted therapy pipeline developers, and molecular diagnostic platform builders. Competitive moves center on companion diagnostic co-development partnerships and consolidation of reference laboratory networks.
Within the large-cap pharmaceutical tier, Pfizer Inc. and Bristol-Myers Squibb Company occupy positions defined by immuno-oncology infrastructure scale. Eli Lilly and Company exemplifies the targeted therapy archetype through KRAS-focused development positioning. These three anchors represent distinct strategic vectors: broad clinical trial access, checkpoint inhibitor portfolio depth, and genetically defined subpopulation specialization.
| Leading Market Players |
|---|
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca |
| Novartis AG |
| Eli Lilly and Company |
| Bristol-Myers Squibb Company |
| Amgen Inc. |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd |
| Others |
Cost & Logistics Intelligence
WHO essential medicines criteria gate qualified supply access for pancreatic cancer chemotherapy agents while simultaneously compressing reimbursement thresholds in lower-income health systems, creating a bifurcated market where premium-tier immunotherapy pricing concentrates in OECD markets with established health technology assessment frameworks.
Pricing Analysis
Volume-margin splits sharply across the pancreatic cancer therapeutic portfolio: chemotherapy drugs dominate treatment volume but face accelerating biosimilar-driven price erosion, while immunotherapy agents command substantial per-patient premiums despite narrower eligible populations. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity—FDA breakthrough therapy designation and companion diagnostic co-development anchor premium positioning, WHO essential medicines listing enables standard-tier access, and unbranded generic gemcitabine occupies economy tiers. Pricing pressure stems from reference pricing mechanisms in Germany's regional cancer networks and NICE technology appraisals in the United Kingdom. Community oncology practices exhibit highest price sensitivity due to Medicare Part B reimbursement constraints, while NCI-designated centers demonstrate lowest sensitivity given bundled payment models and clinical trial revenue offsets.
Supply Chain Analysis
Single-source vulnerability sits with platinum compound mining operations concentrated in South Africa and Russia, which feed gemcitabine and FOLFIRINOX regimen manufacturing. Active pharmaceutical ingredient production draws from India's PLI scheme-supported clusters and China's bulk chemical manufacturing base, with formulation finishing occurring in Germany, the United States, and Japan. Tariff exposure on platinum-based inputs creates margin volatility for generic chemotherapy producers regardless of geographic manufacturing location. Distribution runs through hospital pharmacy compounding operations for intravenous infusion regimens, with specialty pharmacy networks handling oral targeted therapy fulfillment and cold-chain logistics for biologic agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pancreatic cancer market operates as a cost-of-compliance story where FDA companion diagnostic mandates and EMA priority medicines pathway requirements create substantial barrier-to-entry moats, favoring established players with integrated regulatory affairs infrastructure and punishing capital-constrained entrants lacking parallel diagnostic co-development capabilities.
For Market Incumbents: Hedge against biosimilar chemotherapy erosion by deepening companion diagnostic partnerships that lock in biomarker-enriched patient access for pipeline assets. Anchor capacity investments in Japan's designated cancer center network where PMDA accelerated approval pathways compress competitive response windows. Defensive consolidation of reference laboratory networks in the United States prevents emerging entrants from capturing molecular profiling relationships that gate therapy selection.
For New Entrants and Emerging Players: EU AI Act risk classification frameworks in Europe open a window for radiomic software developers capable of demonstrating algorithmic transparency and clinical validation against retrospective cohorts. White-space concentrates in direct-to-patient genetic counseling platforms bypassing traditional hospital-based referral pathways for hereditary pancreatic cancer screening. India's PLI scheme expansion offers the most penetrable geography for API manufacturing entry given production-linked incentive structures reducing import dependency. Go-to-market positioning should emphasize telemedicine-integrated screening protocols that circumvent entrenched oncology center gatekeeping.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation awards for pancreatic cancer indications are the leading indicator that biomarker-driven treatment pathways are achieving regulatory validation and payer coverage thresholds. Long-term viability favors developers with KRAS-mutant subpopulation specialization and integrated diagnostic capabilities over pure-play chemotherapy assets facing biosimilar displacement. Acquisition targets should display radiomics-PD-L1 convergence technology stacks or centralized reference laboratory infrastructure serving dispersed community oncology practices. Watch liquid biopsy platform reimbursement decisions by Medicare and major commercial payers as the critical inflection signal for molecular diagnostic market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA mandates for biomarker testing align therapy access with diagnostic platform control. |
| Radiomics Software Validation | EU AI Act conformity requirements exceed prior CE marking standards for tumor characterization tools. |
| Reference Laboratory Network Consolidation | Centralized molecular profiling expertise displaces in-hospital pathology infrastructure. |
| Japan Cancer Center Partnership | PMDA accelerated approval pathways reward concentrated patient recruitment infrastructure. |
| Liquid Biopsy Platform Expansion | Circulating tumor DNA testing enables community oncology molecular profiling without invasive sampling. |
Research Approach
Multi-period observation of FDA breakthrough therapy designation awards, EMA priority medicines pathway decisions, and PMDA accelerated approval timelines anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling across therapy lines and administration routes was triangulated against top-down pharmaceutical revenue segmentation.
Input-output matrix framing connected biomarker prevalence data, treatment protocol adoption curves, and reimbursement pathway status to project segment-level expansion across the analysis window. Segmentation dimensions modeled included product type, therapy area, end user category, and delivery mode, with geographic regulatory clusters treated as distinct demand environments. CAGRs were derived from spline-interpolated annual estimates accounting for pipeline transition probabilities and biosimilar entry timing assumptions. Forecast inputs incorporated platinum compound supply concentration risk and liquid biopsy platform reimbursement trajectory scenarios.
Caveats apply where WHO essential medicines criteria revisions, platinum supply disruptions, or AI Act enforcement intensity shifts could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Germany Radiotherapy Market
Oncology
Cancer API Market
Oncology
Global Proton Therapy Market
Oncology
North America Veterinary Oncology Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
US Radiation Oncology Market
Oncology
Immuno-Oncology Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Glioblastoma Market
Oncology
Ovarian Cancer Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Ustekinumab Market