
 Paranasal Sinus Cancer Market | 2026-2036
Paranasal Sinus Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Paranasal Sinus Cancer Market Outlook
Oncology clinics are reorganizing treatment pathways toward targeted therapy and multimodal regimens. AbbVie sustains R&D intensity in antibody-drug conjugates for rare head-and-neck indications. Pfizer anchors its position through broad-spectrum cytotoxic portfolios and radiotherapy adjuvant programs. Roche differentiates via companion diagnostics that pair with targeted therapy selection.
Paranasal sinus cancer comprises malignant neoplasms arising from the epithelial lining of the maxillary, ethmoid, frontal, and sphenoid sinuses, typically presenting as squamous cell carcinoma with local invasion patterns into the orbit and skull base; its primary clinical purpose centers on preserving critical functions (vision, olfaction, cranial nerve integrity) while achieving oncologic control. Surgery and targeted therapy capture concentrated margin pools where procedure complexity and biologic specificity command premium reimbursement. Diagnostic imaging and pharmaceuticals represent the fastest-growing product categories as molecular profiling becomes standard-of-care for recurrent-stage patients.
FDA orphan drug designations and EMA conditional marketing authorizations shape development incentives for rare sinus malignancies, while WHO classification updates for head-and-neck tumors drive diagnostic standardization. NMPA streamlined review channels for innovative oncology agents in China expand market access for multinational sponsors. Stakeholders must monitor evolving biomarker definitions and payer evidence requirements for targeted therapy coverage decisions.
Market Dynamics
Precision oncology protocols are reorganizing procurement priorities across academic medical centers, with FDA accelerated approval pathways for rare malignancies compressing clinical trial timelines and reshaping how head-and-neck centers of excellence anchor referral networks for complex sinus malignancies.
Growth Catalysts
- Orphan Drug Incentives:FDA orphan drug designations and EMA conditional marketing authorizations create development incentives for rare sinus malignancies, accelerating biologic therapy pipelines.
- Molecular Profiling Standardization:WHO classification updates for head-and-neck tumors drive diagnostic harmonization, expanding companion diagnostic pairing with targeted therapy selection.
- Streamlined Regulatory Channels:NMPA review pathways for innovative oncology agents in China expand multinational sponsor access to concentrated East Asian demand clusters.
Market Restraints
- Biomarker Definition Volatility:Evolving payer evidence requirements for targeted therapy coverage create reimbursement friction, delaying patient access to precision agents.
- Procedure Complexity Concentration:Skull-base and orbital preservation surgeries require subspecialized surgical oncologists, creating geographic supply bottlenecks outside major metropolitan clusters.
- Radiotherapy Adjuvant Cost Structure:Proton therapy and advanced radiotherapy modalities carry capital-intensive infrastructure requirements, limiting site-of-care expansion.
Strategic Opportunities
- Underpenetrated Biomarker Testing:Community oncology settings in Germany and Japan lack standardized molecular profiling workflows, creating white space for diagnostic platform deployment.
- Tumor-Agnostic Indication Expansion:Regulatory frameworks for histology-independent approvals enable therapy repositioning across rare head-and-neck subtypes previously excluded from trials.
- Telemedicine Referral Networks:Virtual tumor boards and remote pathology consultation compress referral delays, connecting peripheral centers to academic medical center expertise.
Industry Challenges
- Multidisciplinary Care Coordination:Integration of surgical oncology, radiation therapy, and medical oncology workflows requires specialized care navigators, stretching operational bandwidth.
- Clinical Trial Enrollment:Low incidence rates for paranasal sinus subtypes fragment eligible patient pools across dispersed geographic sites, prolonging recruitment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paranasal Sinus Cancer Market |
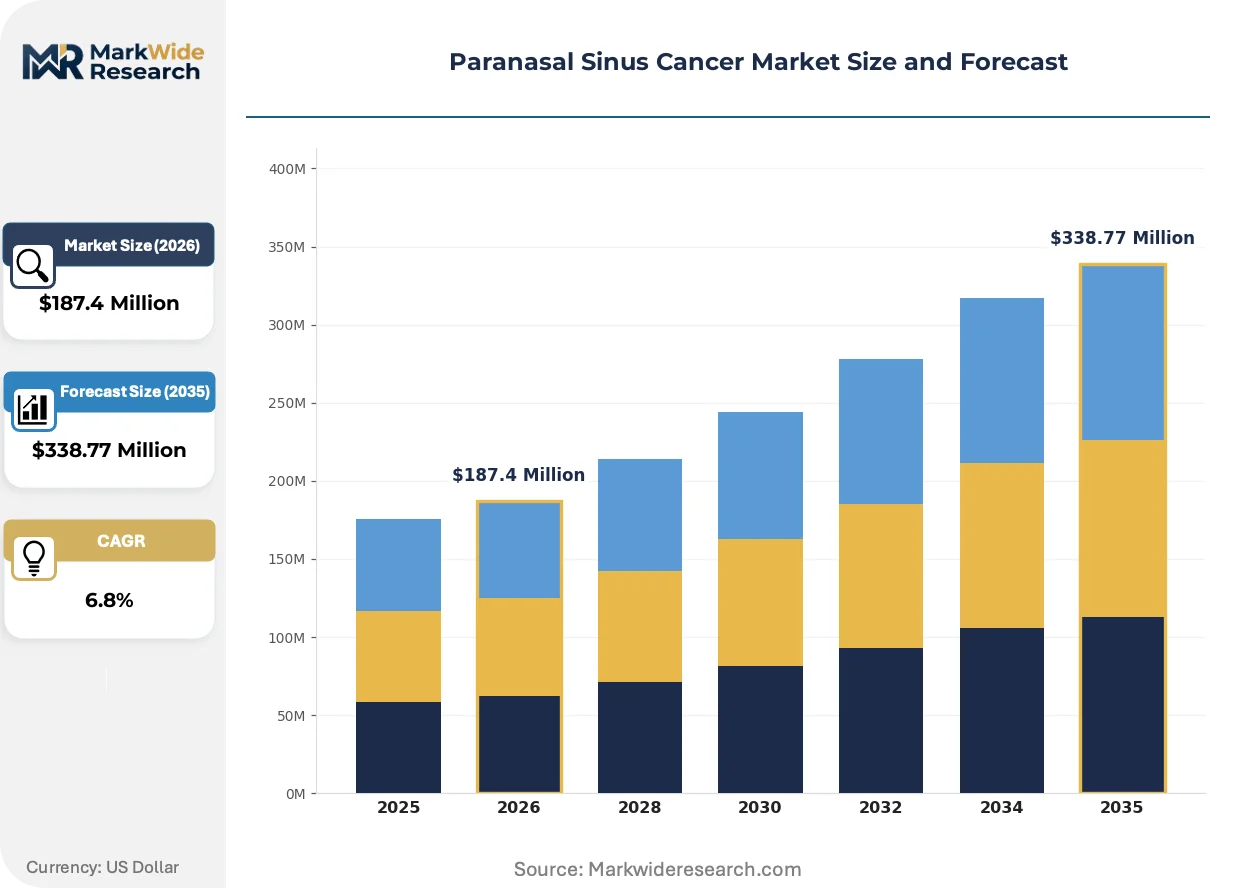
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy End User: Hospitals, Oncology Clinics, Ambulatory Surgical Centers, Research Institutions Stage of Disease: Localized, Regional, Distant, Recurrent Product Type: Diagnostic Imaging, Surgical Instruments, Pharmaceuticals, Supportive Care Products |
| Companies Covered | AbbVie, Pfizer, Eli Lilly and Company, Bristol-Myers Squibb, Roche, Novartis, AstraZeneca, Merck, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paranasal Sinus Cancer Market Strategic Shifts
Antibody-drug conjugate development is displacing conventional cytotoxic regimens in recurrent-stage protocols, while companion diagnostic integration and radiotherapy adjuvant innovation reshape how treatment pathways are constructed and reimbursed.
Next-generation sequencing panels for circulating tumor DNA are displacing tissue-based biopsy protocols in monitoring applications. Academic medical centers in the United States adopt liquid biopsy surveillance for post-treatment recurrence detection, compressing the interval between biochemical signal and radiographic confirmation. This displacement is enabling earlier salvage therapy initiation while reducing invasive procedure burden for patients with skull-base reconstruction.
EMA conditional marketing authorization frameworks for oncology agents accelerate approval timelines for therapies demonstrating early efficacy signals in rare malignancies. Manufacturers respond by structuring adaptive trial designs that integrate real-world evidence generation post-authorization. Head-and-neck oncology centers in Germany and France are most affected, restructuring pharmacy and therapeutics committees to manage conditional reimbursement protocols.
Consolidated purchasing through integrated delivery networks is compressing vendor negotiation cycles for molecular diagnostic platforms. Hospital systems in Japan and the United States are replacing decentralized laboratory procurement with enterprise-wide contracts, displacing smaller regional reference laboratories. This concentration is most visible in metropolitan areas where academic medical centers anchor hub-and-spoke pathology networks.
Paranasal Sinus Cancer Market Segmentation
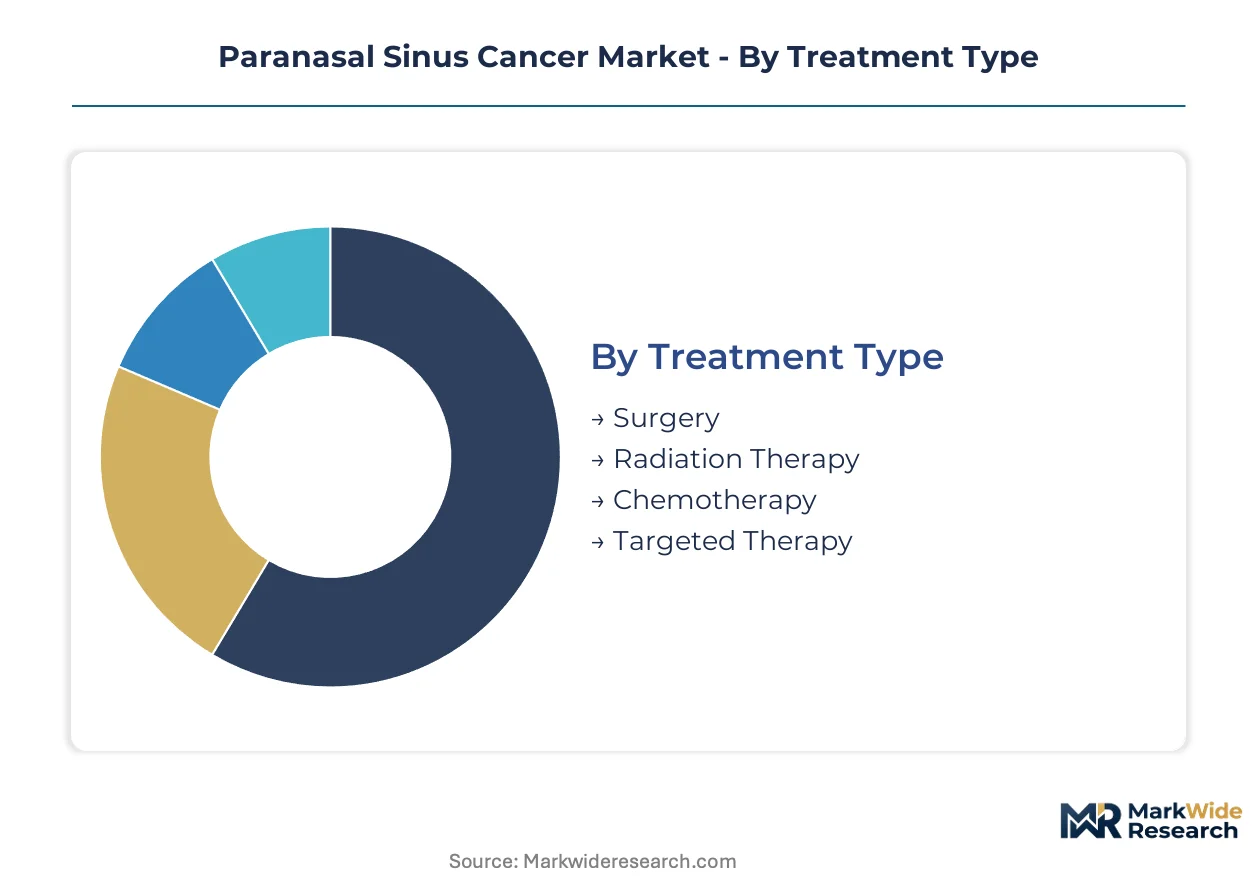
Paranasal sinus cancer treatment pathways fragment across four intersecting dimensions, each carrying distinct reimbursement codes and regulatory requirements. Procurement decisions hinge on whether care delivery occurs within academic medical centers or community settings, with molecular profiling capabilities increasingly determining patient routing.
Treatment Type:
FDA breakthrough therapy designations and EMA conditional marketing authorizations create divergent approval timelines across therapeutic modalities, concentrating investment in biologics over cytotoxic platforms.
- Surgery:Maxillectomy and endoscopic skull-base resection protocols demand subspecialized surgical oncologists with orbital preservation expertise. Academic medical centers in the United States and Germany anchor referral networks for complex cases requiring cranial nerve monitoring and free flap reconstruction, with procedure volumes concentrated in metropolitan clusters exceeding two million population.
- Targeted Therapy:Monoclonal antibodies and small-molecule inhibitors targeting EGFR, HER2, and NTRK fusions displace conventional regimens in recurrent-stage protocols. Companion diagnostic pairing requirements concentrate prescribing authority at centers with integrated molecular pathology laboratories, creating access barriers for community oncology settings lacking NGS infrastructure.
- Radiation Therapy:Intensity-modulated and proton beam modalities require capital-intensive infrastructure.
- Chemotherapy:Platinum-based regimens retain utility in neoadjuvant protocols despite toxicity limitations.
Established volume favors surgery; emerging adoption favors targeted therapy.
End User:
Care site selection depends on procedure complexity tiers and molecular profiling availability, with reimbursement differentials widening between academic and community settings.
- Hospitals:Tertiary centers with dedicated head-and-neck oncology divisions manage multimodal regimens requiring coordinated surgical, radiation, and medical oncology workflows. These institutions capture concentrated margin pools through bundled payment arrangements for skull-base and orbital preservation surgeries, with NCI-designated cancer centers in the United States anchoring regional referral networks.
- Oncology Clinics:Community-based medical oncology practices deliver systemic therapy for recurrent and metastatic patients, with molecular profiling outsourcing creating dependency on reference laboratory turnaround times. Clinics in Japan and Germany are reorganizing procurement priorities around precision oncology protocols, though biomarker testing standardization remains uneven.
- Ambulatory Surgical Centers:Limited to diagnostic endoscopy and biopsy procedures due to anesthesia and emergency backup requirements.
- Research Institutions:Phase I and II trial enrollment concentrates at academic medical centers with dedicated head-and-neck oncology programs.
Procedure revenue concentrates in hospitals; pharmaceutical margin capture is shifting toward oncology clinics.
Stage of Disease:
Clinical trial design and regulatory approval pathways segment by disease extent, with FDA accelerated approval mechanisms primarily serving recurrent and distant populations.
- Localized:T1-T2 tumors without orbital or skull-base invasion permit organ-preservation surgery with adjuvant radiation reserved for high-risk pathologic features. These patients command premium reimbursement through complex reconstruction codes, with maxillary sinus primaries dominating surgical volumes in United States academic centers.
- Recurrent:Second-line systemic therapy indications drive pharmaceutical pipeline investment, with circulating tumor DNA surveillance enabling earlier salvage intervention. Molecular profiling becomes standard-of-care for this population, expanding companion diagnostic deployment across Japan and Germany where centralized pathology networks support rapid turnaround.
- Regional:Nodal involvement mandates combined modality approaches with elevated toxicity profiles.
- Distant:Metastatic disease concentrates in palliative care pathways with limited curative intent.
Curative intent dominates localized-stage investment; recurrent-stage protocols are expanding most quickly.
Product Type:
Procurement consolidation through integrated delivery networks is compressing vendor negotiation cycles, favoring enterprise-scale suppliers over regional distributors.
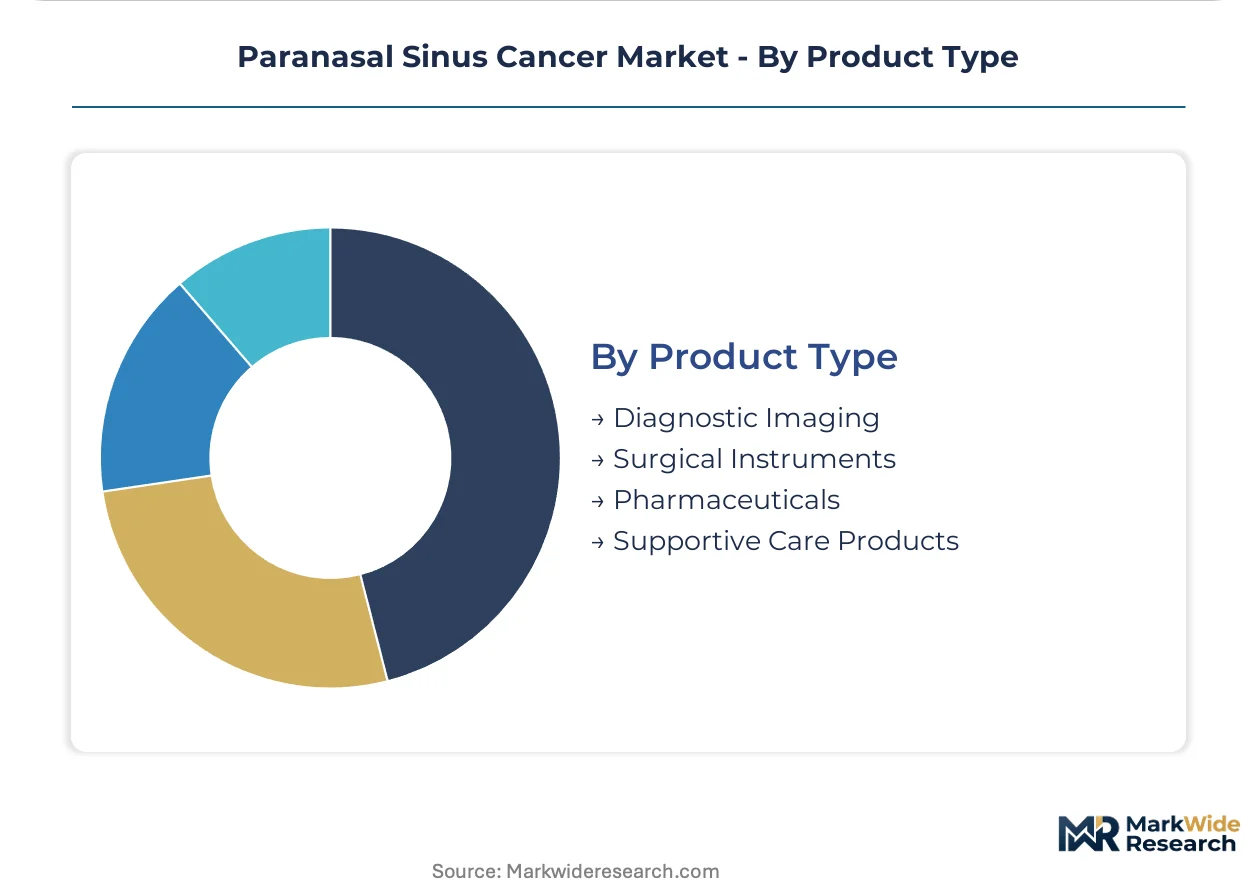
- Diagnostic Imaging:MRI with diffusion-weighted sequences and PET-CT with radiolabeled amino acid tracers enable precise tumor delineation for radiation planning and surgical navigation. Demand concentrates in academic medical centers performing skull-base resections, with advanced imaging protocols required for orbit and anterior cranial fossa assessment.
- Pharmaceuticals:Antibody-drug conjugates and immune checkpoint inhibitors are displacing cytotoxic backbones in recurrent-stage protocols. EMA conditional marketing authorizations accelerate European access, though payer evidence requirements for targeted therapy coverage create reimbursement friction in Germany and France.
- Surgical Instruments:Navigation systems and ultrasonic aspirators require specialized maintenance contracts.
- Supportive Care Products:Growth factor support and antiemetic protocols follow chemotherapy administration patterns.
Capital equipment procurement favors diagnostic imaging; recurring revenue expansion is climbing the fastest in pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ronald Reagan UCLA Medical Center anchors Pacific Coast referral networks for skull-base oncology, channeling complex sinus malignancies from seven states into its head-and-neck surgery division. FDA accelerated approval pathways and NCI-designated cancer center density concentrate precision oncology infrastructure in specific metropolitan corridors.
United States
MD Anderson Cancer Center and Memorial Sloan Kettering anchor competing referral networks for advanced sinus malignancies, with proton therapy centers in Houston and Manhattan commanding premium reimbursement for orbital preservation protocols. FDA breakthrough therapy designations for rare head-and-neck indications compress trial enrollment timelines at these sites. The Texas Medical Center cluster manages the highest surgical volume for maxillary sinus primaries requiring free flap reconstruction.
Germany
EMA conditional marketing authorizations accelerate patient access to antibody-drug conjugates at Charité Berlin and Heidelberg University Hospital, where pharmacy committees restructure procurement around real-world evidence generation requirements. The country's national pharmaceutical regulator mandates post-authorization safety studies for oncology agents granted conditional approval. The Mannheim-Heidelberg medical corridor concentrates molecular pathology infrastructure supporting companion diagnostic pairing.
Japan
PMDA sakigake designation pathways enable priority review for innovative oncology agents at National Cancer Center Hospital in Tokyo, where circulating tumor DNA surveillance protocols are displacing tissue biopsy for recurrence monitoring. METI funding for proton therapy expansion targets regional disparities in radiotherapy access. The Kanto metropolitan cluster houses eight of twelve heavy ion therapy facilities approved for head-and-neck malignancies.
China
NMPA streamlined review channels for innovative oncology agents expand multinational sponsor access to Fudan University Shanghai Cancer Center, where phase I trial enrollment concentrates for EGFR-targeted therapies in recurrent sinus carcinoma. The country's national pharmaceutical regulator prioritizes local clinical data for imported biologics seeking market authorization. The Yangtze River Delta medical corridor anchors molecular diagnostic platform deployment across 340 hospital partnerships.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex skull-base surgery at Royal Marsden and Guy's Hospital, with referral criteria restricting orbital preservation procedures to designated supra-regional centers. The MHRA early access to medicines scheme enables pre-approval use of promising oncology agents for rare malignancies. The London-Southeast cluster manages 60 percent of national clinical trial enrollment for head-and-neck precision therapies.
Paranasal Sinus Cancer Market Competitive Environment
Listed leaders compete with private specialists across therapeutic modality development, with publicly traded pharmaceutical conglomerates anchoring broad-spectrum portfolios while privately held biotechnology firms concentrate on single-asset antibody-drug conjugate programs. The market structure exhibits tiered consolidation, with top-tier players commanding integrated diagnostic-therapy platforms and mid-tier specialists competing on tumor-agnostic indication strategies. Three archetypes dominate: diversified oncology conglomerates with companion diagnostic capabilities, targeted therapy specialists pursuing rare disease designations, and radiotherapy adjuvant developers with proton therapy partnerships. Competitive moves concentrate on strategic licensing for molecular profiling technologies and adaptive trial design capabilities.
Among diversified oncology conglomerates, AbbVie, Pfizer, and Roche exemplify contrasting platform strategies. AbbVie occupies a position within the antibody-drug conjugate specialization tier, reflecting its nomenclature heritage in biologic therapy development. Pfizer represents the scale-driven archetype, with its corporate structure indicating broad pharmaceutical portfolio capabilities. Roche anchors the diagnostic-therapy integration tier, its name signaling historical concentration in molecular diagnostics pairing with targeted agent selection.
| Leading Market Players |
|---|
| AbbVie |
| Pfizer |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Roche |
| Novartis |
| AstraZeneca |
| Merck |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for antibody-drug conjugate manufacturing lock in supply access and price visibility for academic medical centers, while proton therapy capacity reservations in Japan and the United States create tiered access structures that concentrate margin capture at NCI-designated cancer centers.
Pricing Analysis
Volume-discount tiering structures separate academic medical center consortia from community oncology practices, with companion diagnostic bundling and molecular profiling service tiers creating three-tier pricing differentiation across premium integrated platforms, standard reference laboratory outsourcing, and economy-tier single-biomarker testing. Price differentiation hinges on NGS panel breadth and FDA breakthrough therapy designation status, with community clinics facing pricing pressure from extended reference laboratory turnaround times that delay targeted therapy initiation. Pharmaceutical buyers exhibit highest price sensitivity in chemotherapy backbones, while proton therapy centers command premium pricing power through orbital preservation outcomes.
Supply Chain Analysis
Inventory lead times for circulating tumor DNA assay kits extend to six weeks at community oncology settings lacking cold-chain infrastructure, while academic medical centers maintain two-week buffers through direct manufacturer relationships. Manufacturing concentrates in the United States, Germany, and China, with biologic API production drawing from Swiss and Irish contract manufacturing networks. Supply chain risk centers on single-source vulnerability for NTRK fusion detection reagents. Distribution runs through integrated delivery network pharmacy and therapeutics committees that consolidate molecular diagnostic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic service contracts and circulating tumor DNA surveillance programs expand faster than imaging hardware sales, positioning recurring revenue attachment as the dominant value-capture mechanism in precision oncology infrastructure.
For Market Incumbents: Consolidate molecular pathology laboratory networks through exclusive service contracts with National Cancer Center Hospital Tokyo and Charité Berlin, locking out emerging diagnostic platform vendors. Acquire or partner with liquid biopsy specialists to secure NGS infrastructure control before community oncology settings achieve testing standardization. Defend against reference laboratory disintermediation by embedding pathologists within virtual tumor board workflows. For New Entrants and Emerging Players: Differentiate on rapid turnaround time for NTRK fusion and HER2 amplification testing in German community oncology settings where centralized pathology networks remain underpenetrated. Target white space in telemedicine-enabled remote pathology consultation for peripheral Japanese centers lacking skull-base surgical expertise. Pursue go-to-market partnerships with proton therapy facility developers to bundle diagnostic surveillance with radiotherapy adjuvant protocols. For Investors and Strategic Acquirers: Single-asset antibody-drug conjugate developers with FDA orphan drug designations represent the most defensible acquisition archetype, given compressed clinical timelines and premium reimbursement pathways for rare head-and-neck indications. Long-term viability rests on adaptive trial design capabilities that integrate real-world evidence generation post-EMA conditional marketing authorization. Watch for inflection when NMPA grants priority review to EGFR-targeted therapies with China-specific clinical data packages.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | FDA breakthrough therapy designations increasingly mandate paired NGS platform adoption at academic medical centers. |
| Adaptive Trial Design Implementation | EMA conditional marketing authorization frameworks compress enrollment timelines for rare sinus malignancy protocols. |
| Liquid Biopsy Surveillance Expansion | Post-treatment circulating tumor DNA monitoring displaces tissue biopsy for recurrence detection in skull-base reconstruction patients. |
| Proton Therapy Capacity Buildout | METI funding targets regional disparities in radiotherapy access across Japan's metropolitan clusters. |
| Virtual Tumor Board Deployment | Telemedicine referral networks connect peripheral German centers to Heidelberg's molecular pathology expertise. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the paranasal sinus cancer treatment pathway, including head-and-neck surgical oncologists at MD Anderson and Memorial Sloan Kettering, formulary directors at German university hospital pharmacy committees, PMDA regulatory affairs specialists, and proton therapy center operations executives. Secondary validation drew from FDA orphan drug designation filings, EMA conditional marketing authorization decisions, ClinicalTrials.gov head-and-neck oncology protocols, and NMPA priority review announcements. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Across the analysis window, the forecast framework modeled treatment type segmentation by procedure complexity and molecular profiling dependency, end-user concentration at academic versus community settings, disease stage distribution affecting clinical trial eligibility, and product type dynamics between capital equipment and recurring pharmaceutical revenue. CAGRs derived from procedure volume trajectories at NCI-designated cancer centers and biologic therapy adoption curves in recurrent-stage populations. Forecast inputs incorporated PMDA sakigake designation timelines and NHS England specialized commissioning framework revisions.
The analysis sits within stated boundaries; outcomes outside sustained FDA accelerated approval pathway utilization or EMA conditional authorization scope expansion would require recalibration. Forecasts reflect assumptions regarding biomarker definition stability and payer evidence requirement evolution for targeted therapy coverage. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Germany Radiotherapy Market
Oncology
Metastases Spinal Tumor Market
Oncology
Radiation Therapy Software Market
Oncology
Metastatic Cancer Drug Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Pharyngeal Neoplasm Market
Oncology
Testicular Cancer Treatment Market
Oncology
Global Oncology Clinical Trials Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Pituitary Cancer Market
Oncology
Breast Cancer Therapy Market
Oncology
Global Skin Cancer Diagnostics and Therapeutics Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
France Radiation Oncology Market
Oncology
Pancreatic Cancer Market
Oncology
Europe Radiotherapy Patient Positioning Market