
 Europe Anchors and Grouts Market | 2026-2036
Europe Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Anchors and Grouts Market Foresight
Epoxy resin chemistry is rewriting performance benchmarks for structural anchoring across European construction sites. Sika AG leverages its Swiss R&D base to dominate specification-grade injection grout formulations for tunnel and bridge rehabilitation. MAPEI SpA anchors Mediterranean market presence through vertically integrated cementitious production and direct contractor relationships. BASF SE competes on polyurethane technology leadership, supplying high-strength chemical anchors for offshore wind foundation projects in the North Sea.
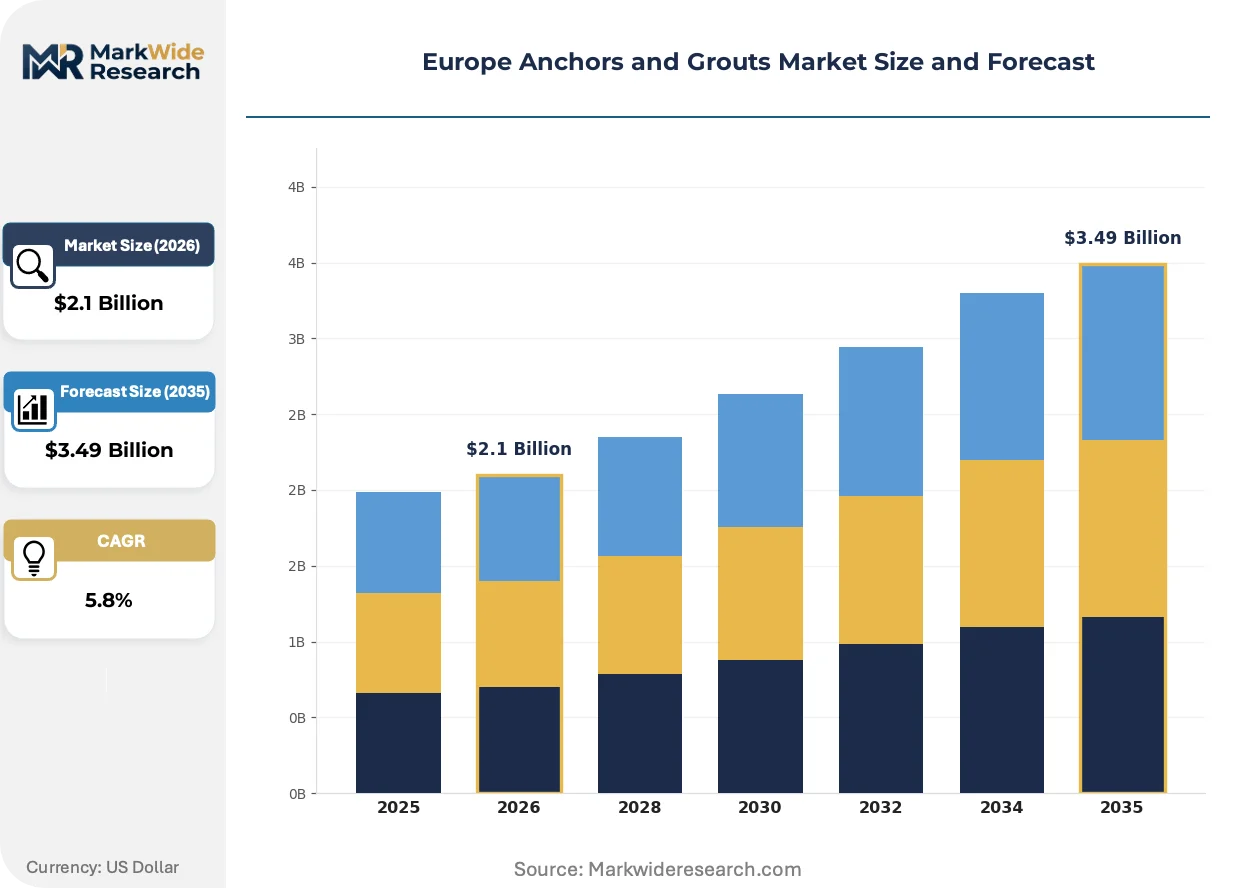
Europe anchors and grouts encompass load-transfer devices and void-filling binders engineered to bond steel elements into concrete, masonry, or rock substrates, typically achieving pull-out strengths exceeding 80 MPa for epoxy systems in cracked concrete applications. These products serve primarily to secure structural connections, restore bearing capacity, and seal water ingress paths in civil engineering assets. Chemical anchors lead value capture due to premium pricing in seismic and cracked-concrete specifications, while cementitious grouting compounds sustain volume dominance through infrastructure rehabilitation demand across the continent's aging bridge stock. Epoxy technology occupies the fastest-expanding margin pool as offshore wind and industrial machinery installations specify fatigue-resistant, corrosion-proof anchoring.
The Construction Products Regulation (CPR) mandates CE marking and declared performance for anchors used in structural applications, forcing manufacturers to maintain notified-body testing across multiple European jurisdictions. ECHA's REACH restrictions on isocyanates and crystalline silica are reformulating polyurethane and cementitious product lines, adding compliance costs that favor scaled producers with dedicated regulatory affairs teams. Germany's Federal Institute for Research on Building, Urban Affairs and Spatial Development (BBSR) sets reference standards for public infrastructure procurement that cascade into specification requirements across Austria, Switzerland, and Benelux markets. Stakeholders must monitor how the EU's evolving taxonomy for sustainable construction reclassifies conventional grout chemistries and whether national recovery funds tilt specification authority toward carbon-accounted product selection.
Market Dynamics
The EU Green Deal's embodied carbon mandates are forcing cementitious grout manufacturers to reformulate binders and respecify supply chains around low-clinker alternatives, compressing margins for legacy producers while opening specification gates for innovators.
Growth Catalysts
- Transport Infrastructure Renewal:Germany's federal tunnel rehabilitation programs and bridge bearing replacement schemes are absorbing high-performance injection grouts at unprecedented scale.
- REACH Compliance Innovation:ECHA's crystalline silica restrictions are accelerating adoption of pre-mixed, dust-controlled cementitious systems in public works procurement.
- Offshore Wind Foundation Anchoring:North Sea wind farm developers specify fatigue-resistant epoxy anchors for monopile transition piece connections.
Market Restraints
- Epoxy Resin Cost Volatility:Bisphenol-A and amine hardener feedstock prices fluctuate with crude oil derivatives, compressing formulation margins unpredictably.
- Notified Body Bottleneck:CE marking requirements under the Construction Products Regulation create multi-month certification delays for new product introductions.
- Cementitious Substitution Pressure:Mechanical expansion anchors compete on upfront cost for non-structural applications in residential construction.
Strategic Opportunities
- Benelux Tunnel Sealing:Belgium and Netherlands delta works maintenance programs under-specify current grouting technology, creating white space for hydrophobic polyurethane systems.
- CSRD Carbon Accounting:The EU Corporate Sustainability Reporting Directive rewards manufacturers with verified Environmental Product Declarations in public tender scoring.
- Bio-Based Binder Convergence:Geopolymer and alkali-activated cement chemistry merges with conventional grout application equipment, lowering clinker dependence.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in rheology-modified cementitious systems and epoxy-amine stoichiometry concentrates among aging technical workforces.
- Legacy Asset Compatibility:New low-carbon grouts must demonstrate bond strength parity with 30-year-old substrate conditions in heritage structure rehabilitation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Anchors and Grouts Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Anchors, Mechanical Anchors, Grouting Compounds, Injection Grouts Technology: Hydraulic, Epoxy, Cementitious, Polyurethane End User: Construction, Infrastructure, Marine, Industrial Application: Building Renovation, New Construction, Structural Repairs, Foundations |
| Companies Covered | Sika AG, MAPEI SpA, Fosroc Inc, Bostik (Arkema Group), Selena FM, BASF SE, Saint-Gobain Weber, MBCC Group, Ardex Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Anchors and Grouts Market Shifts & Advancements
Digital specification tools and predictive performance modeling are compressing traditional testing cycles. Manufacturers now compete on computational verification speed rather than laboratory turnaround alone.
Finite element analysis software is virtualizing anchor design validation for cracked concrete applications. Structural engineers at major infrastructure consultancies now simulate load distribution before physical pull-out testing. This compression of verification timelines is virtualizing the traditional six-month CE marking pathway into eight-week digital pre-certification workflows.
REACH Annex XVII amendments on isocyanates are restricting polyurethane anchor formulations. Manufacturers face reformulation costs exceeding seven figures for compliant hardener systems. Tunnel contractors in Austria and Switzerland are accelerating procurement of pre-restricted inventory while accelerating epoxy alternative trials.
Asset owner procurement teams now unbundle material supply from installation supervision. Dutch water management authorities and German federal construction agencies separately contract grout manufacturers and certified applicators. This disintermediation concentrates price pressure on product suppliers while elevating specialist contractor margins in the Benelux region.
Europe Anchors and Grouts Market Segmentation
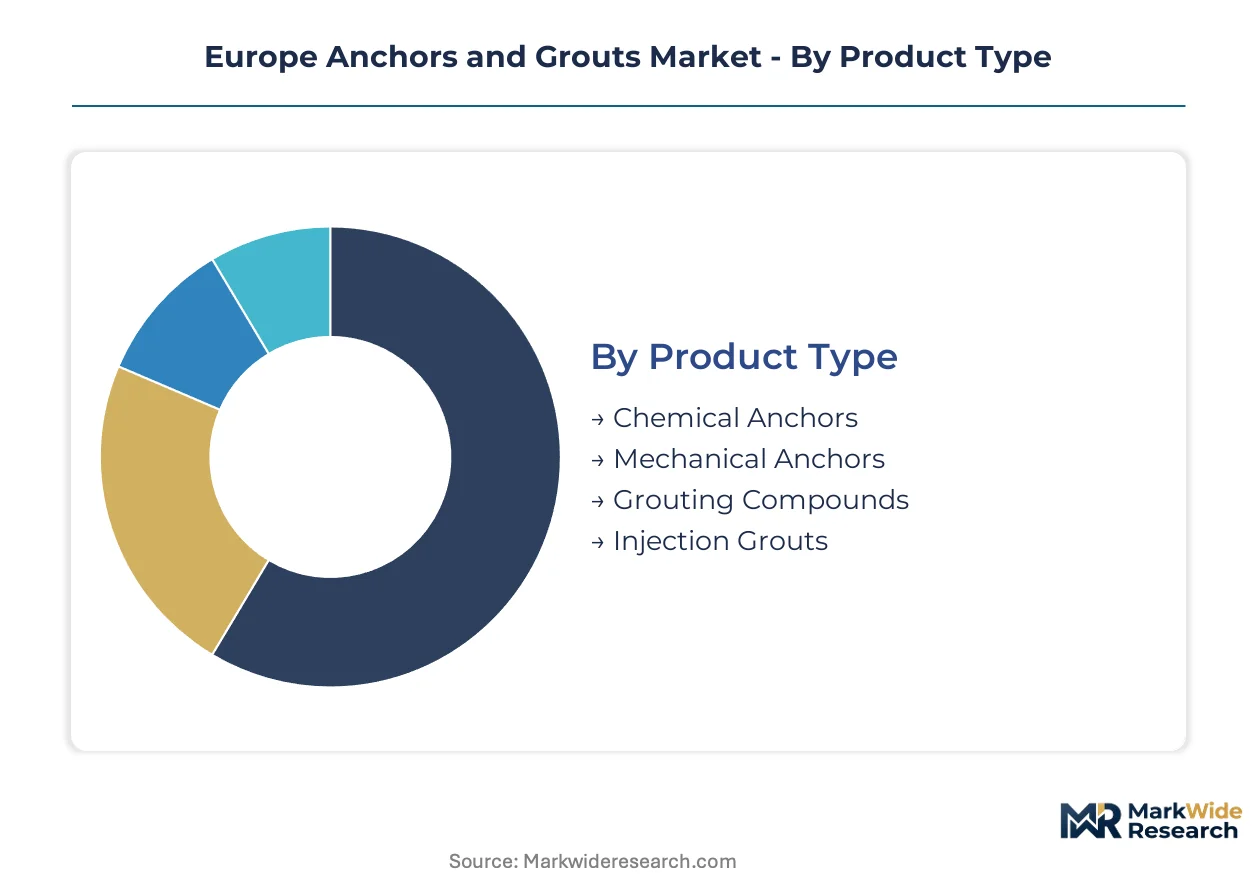
Segmentation in the Europe Anchors and Grouts Market reveals how specification authority flows through distinct procurement channels. Product chemistry, installation technology, and end-use asset class each create separate margin pools with divergent compliance burdens and customer concentration.
Product Type:
Mature mechanical systems coexist with emerging chemical formulations as specification standards tighten across European structural codes.
- Chemical Anchors:Epoxy-amine and vinylester resin systems bond steel elements into cracked concrete with pull-out strengths exceeding 80 MPa. German tunnel rehabilitation programs and North Sea offshore wind foundations specify these for fatigue-critical connections where mechanical expansion fails.
- Grouting Compounds:Cementitious and epoxy-based void fillers restore bearing capacity in bridge bearings and machine baseplates. Federal procurement in Austria and Switzerland favors pre-mixed formulations with dust-controlled delivery to satisfy ECHA crystalline silica restrictions.
- Mechanical Anchors:Expansion and undercut devices serve non-structural residential applications where upfront cost dominates specification.
- Injection Grouts:Low-viscosity pressure-injected systems seal water ingress paths in delta works and alpine tunnel linings.
Cementitious compounds handle the majority of throughput; chemical anchors are the fastest mover on share.
Technology:
Cost tier stratification separates commodity binders from premium resin systems with divergent raw material exposure.
- Epoxy:Two-part thermosetting formulations achieve superior bond strength and chemical resistance for structural rehabilitation. REACH compliance on bisphenol-A derivatives is forcing reformulation investments among specialized producers serving Benelux infrastructure authorities.
- Cementitious:Portland cement and supplementary cementitious material blends dominate volume through infrastructure renewal demand. EU Green Deal embodied carbon mandates are accelerating geopolymer and alkali-activated alternatives in German federal procurement.
- Polyurethane:Hydrophobic foam systems seal dynamic cracks in water-retaining structures.
- Hydraulic:Rapid-setting calcium sulfoaluminate binders enable short-window repairs in rail maintenance.
Cementitious technology commands the volume base; epoxy systems are expanding most quickly on specification premium.
End User:
Application maturity varies across asset classes with divergent maintenance cycles and procurement sophistication.
- Infrastructure:Public tunnel, bridge, and dam authorities in Germany, Austria, and the Netherlands specify performance-graded systems with certified applicator networks. CSRD carbon accounting requirements are beginning to influence tender scoring for material suppliers with verified Environmental Product Declarations.
- Construction:Private building renovation and new build contractors balance code compliance with cost containment, often defaulting to mechanical anchors for non-structural fixings.
- Industrial:Manufacturing facility owners specify chemical anchors for heavy machinery anchoring and precision alignment.
- Marine:Port authorities and offshore wind developers demand corrosion-resistant epoxy systems for splash zone and submerged applications.
Infrastructure absorbs the dominant procurement volume; industrial end-use is climbing the fastest on machinery investment cycles.
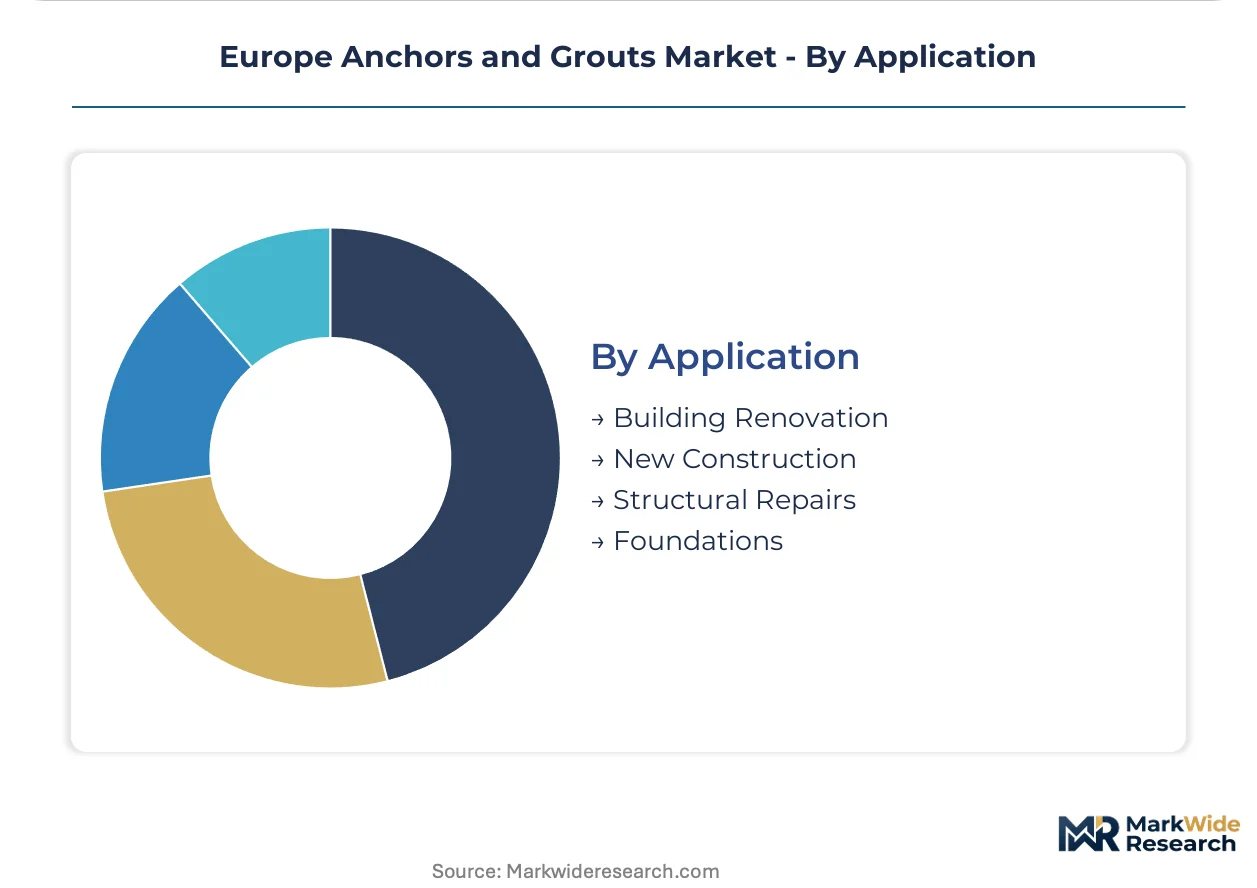
Application:
Volume concentration follows the age profile of European built assets and public maintenance commitments.
- Building Renovation:Energy retrofit programs and facade refurbishment across Germany's aging housing stock drive demand for shallow-embedment anchors and repair grouts. Compatibility with 30-year-old substrate conditions remains the critical specification filter.
- Structural Repairs:Bridge bearing replacement and tunnel lining rehabilitation in Alpine and Benelux corridors require injection grouts with verified rheology under pressure. BBSR reference standards cascade into Austrian and Swiss procurement specifications.
- New Construction:Greenfield commercial and residential development specifies standard mechanical and chemical anchors through distributor channels.
- Foundations:Deep embedment anchors for industrial machinery and offshore wind transition pieces demand fatigue-tested epoxy systems with extended design life certification.
Building renovation commands the current volume base; structural repairs are gaining share fastest on infrastructure renewal commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public infrastructure authorities concentrate procurement power across German federal agencies, Dutch water management boards, and Swiss cantonal engineering departments. These buyer archetypes specify performance-graded anchoring systems through certified applicator networks, with tender scoring increasingly weighting embodied carbon metrics under EU Green Deal implementation.
Germany
Federal tunnel rehabilitation programs and bridge bearing replacement schemes absorb premium injection grouts at scale. BBSR reference standards cascade into procurement specifications across Austria and Switzerland. The Rhine-Ruhr industrial corridor anchors manufacturing capacity for epoxy-amine formulations serving North Sea offshore wind foundations.
Netherlands
Delta works maintenance programs and port authority infrastructure renewal drive demand for hydrophobic polyurethane sealing systems. Rijkswaterstaat procurement unbundles material supply from installation supervision, elevating specialist contractor margins. The Rotterdam port cluster specifies corrosion-resistant epoxy anchors for marine splash zone applications.
Switzerland
Alpine tunnel lining rehabilitation and hydroelectric dam maintenance require injection grouts with verified rheology under pressure. Swissmedic-adjacent construction product standards enforce stringent performance certification. The Gotthard corridor concentrates specification-grade formulation demand for seismic-resistant structural connections.
France
Nuclear facility maintenance and high-speed rail infrastructure renewal specify fatigue-tested chemical anchoring systems. ECHA REACH compliance on crystalline silica accelerates adoption of dust-controlled cementitious delivery. The Île-de-France transport authority network drives standardization of pre-mixed grout specifications across Greater Paris renovation programs.
Italy
Heritage structure rehabilitation and seismic retrofit programs demand compatibility with 30-year-old substrate conditions. ANSM construction product oversight aligns with CE marking requirements under the Construction Products Regulation. The Po Valley industrial belt sustains volume demand for cementitious compounds through manufacturing facility modernization cycles.
Europe Anchors and Grouts Market Competitive Landscape
Channel-controlling players compete with product-specialist players for specification authority in public infrastructure procurement. The vendor base organizes around three tiers: multinational chemical conglomerates with construction divisions, dedicated building materials specialists with regional formulation expertise, and distributor-dependent mechanical anchor suppliers. Consolidation pressure operates through backward integration into resin synthesis and forward integration into certified applicator networks. Technology licensing agreements and EPD certification races constitute the dominant competitive moves.
Among Swiss and German chemical conglomerates, Sika AG and BASF SE exemplify the integrated-formulation archetype with captive R&D infrastructure. MAPEI SpA represents the Mediterranean specialist model with vertically controlled cementitious production. These three entities anchor the premium specification tier where CE marking authority and carbon-accounted product declarations determine tender outcomes.
| Leading Market Players |
|---|
| Sika AG |
| MAPEI SpA |
| Fosroc Inc |
| Bostik (Arkema Group) |
| Selena FM |
| BASF SE |
| Saint-Gobain Weber |
| MBCC Group |
| Ardex Group |
| Others |
Supply & Pricing Matrix
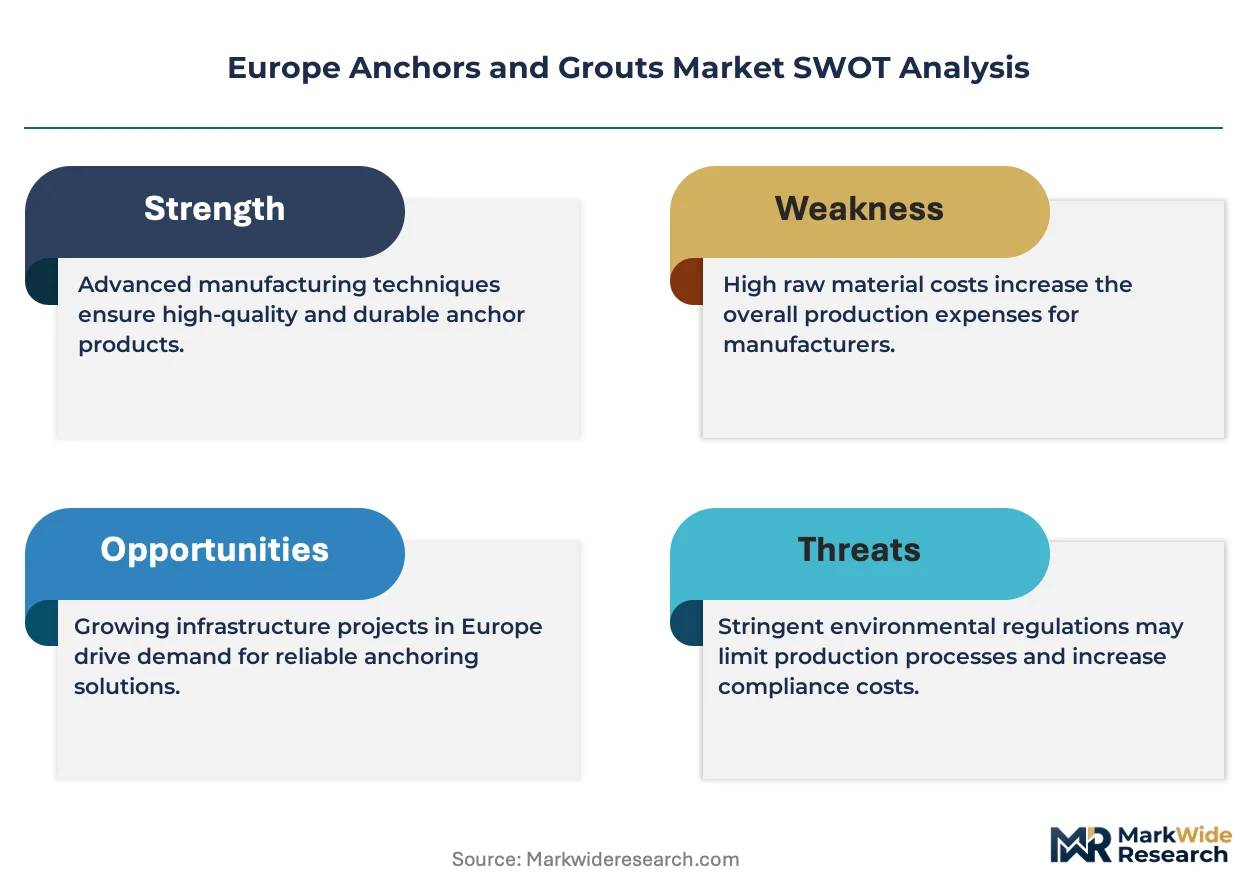
Bisphenol-A and amine hardener feedstock volatility cascades through epoxy formulation costs, compressing margins unpredictably while forcing buyers toward long-term offtake contracts. This raw material exposure stratifies the market into premium specification-grade suppliers with captive resin synthesis and standard-grade distributors exposed to spot market swings.
Pricing Analysis
Cost-plus contracts with bisphenol-A indexation dominate procurement between major formulation houses and infrastructure authorities. Three-tier pricing structure across performance-graded, standard-certified, and economy mechanical tiers separates Sika AG and BASF SE specification premiums from distributor-label alternatives. Pricing pressure stems from REACH-driven reformulation costs exceeding seven figures for compliant hardener systems. Public tunnel authorities in Germany and Switzerland demonstrate lowest price sensitivity, while residential construction contractors in Italy and Poland prioritize upfront cost over lifecycle performance.
Supply Chain Analysis
Toll manufacturing concentration in Germany's Rhine-Ruhr corridor and Switzerland's Basel region anchors epoxy-amine production for structural anchoring applications. Raw material sourcing draws from Belgian petrochemical complexes for bisphenol-A derivatives and Dutch specialty chemical producers for modified amine hardeners. Single-source vulnerability concentrates in vinylester resin feedstocks from select North Sea producers. Distribution runs through certified applicator networks rather than open merchant channels, with Sika AG and MAPEI SpA maintaining direct contractor relationships for specification-grade injection grouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Anchors and Grouts Market sits at a regulatory inflection where ECHA REACH restrictions on isocyanates and crystalline silica are disqualifying legacy formulations while rewarding compliant innovators with specification authority.
For Market Incumbents: Insulate specification-grade positioning through backward integration into low-carbon cementitious binder production and accelerated Environmental Product Declaration certification under CSRD scoring protocols. Threat displacement from geopolymer alternatives demands captive R&D in alkali-activated chemistry. Channel control through certified applicator network expansion in Benelux tunnel programs represents the priority defensive lever. For New Entrants and Emerging Players: Pursue white-space capture in hydrophobic polyurethane sealing systems for Netherlands delta works maintenance, where current procurement under-specifies performance-graded alternatives. Belgium's unbundled material-applicator contracting creates direct access paths for specialized formulation houses. Geopolymer grout compatibility with legacy injection equipment offers the most penetrable technology entry angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with notified-body certification breadth and carbon-accounted product portfolios. Long-term viability across the projection horizon hinges on EU Green Deal alignment in public tender scoring. Acquisition targets should demonstrate dual capability in epoxy structural anchoring and cementitious infrastructure rehabilitation. The signal to watch is BBSR reference standard adoption of embodied carbon thresholds in German federal procurement, which will cascade into Austrian and Swiss specification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive bisphenol-A supply insulates Sika AG and BASF SE from feedstock volatility in epoxy formulation. |
| Environmental Product Declaration Certification | Verified EPDs unlock CSRD-weighted tender scoring with Rijkswaterstaat and German federal construction agencies. |
| Geopolymer Formulation Development | Alkali-activated chemistry reduces clinker dependence for EU Green Deal compliance in infrastructure rehabilitation. |
| Certified Applicator Network Expansion | Direct contractor relationships in Benelux tunnel programs disintermediate distributor channels for premium grouts. |
| REACH-Compliant Hardener Reformulation | Pre-emptive isocyanate substitution secures specification continuity under ECHA Annex XVII amendments. |
Research Methodology
Desk research of ECHA regulatory filings, BBSR technical standards, and EU construction product certification databases preceded structured interviews with tunnel project engineers, structural specification consultants, grout formulation chemists, and public procurement officers at German federal construction agencies. Primary fieldwork with Benelux water management authorities and Swiss cantonal engineering departments validated volume assumptions for injection grout demand. Secondary triangulation incorporated trade data from Eurostat construction materials classifications and SEC disclosures from listed building chemicals producers. Bottom-up segment sizing across product chemistry, installation technology, and end-use asset class was cross-checked against top-down infrastructure spending projections.
Forecast assumptions held fixed the current EU Green Deal implementation trajectory and REACH restriction timelines while varying public infrastructure renewal commitment levels and offshore wind installation rates. The analytical framework modeled volume and value across the projection horizon through product type, technology chemistry, end-user asset class, and application segment dimensions. CAGRs were derived from infrastructure age profiles, maintenance cycle analysis, and specification substitution elasticities for chemical versus mechanical anchoring systems. Epoxy resin price volatility and notified-body certification bottlenecks were incorporated as scenario variables.
Sensitivities concentrate around German federal budget allocation shifts for tunnel rehabilitation, ECHA acceleration of crystalline silica restrictions, and North Sea offshore wind foundation installation delays. Forecasts reflect documented assumptions regarding REACH compliance timelines and CSRD carbon accounting adoption curves. Cross-checking against Eurostat construction materials production indices and national infrastructure pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Global Fencing Market
Specialty Construction
Expandable Shelter Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Indonesia Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Portable Walls Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Asia-Pacific Anchors and Grouts Market
Specialty Construction
Composite Repair Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Construction Repaint Market
Specialty Construction
Fire Hydrants Market