
 Asia-Pacific Anchors and Grouts Market | 2026-2036
Asia-Pacific Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Anchors and Grouts Market Outlook
Project finance for large-scale infrastructure in Southeast Asia is fragmenting the competitive landscape, allowing mid-tier contractors to specify specialized anchoring systems previously reserved for state-backed developers. Sika AG leverages its regional manufacturing footprint to sustain cost advantages across multiple ASEAN markets. MBCC Group anchors its position through deep technical service capabilities in high-specification marine grouting. Hilti Corporation differentiates by controlling direct distribution channels that bypass traditional construction supply intermediaries.
Asia-Pacific anchors and grouts encompass load-transfer devices and cementitious or resin-based bonding compounds engineered to achieve specified compressive strengths, typically formulated with Portland cement, epoxy resins, or vinylester systems for structural load distribution and crack injection. These materials secure structural elements to concrete, masonry, or rock substrates across civil engineering and industrial maintenance applications. Chemical anchors lead product type demand due to their superior performance in seismic zones, while injection grouts represent the fastest-growing category as aging infrastructure rehabilitation accelerates across Japan and South Korea. Structural stabilization applications command the deepest margin pools where engineering certification requirements limit supplier participation.
Japan's METI enforces JIS standards for earthquake-resistant construction materials, directly shaping product development priorities for grout formulations in high-seismic zones. Australia's building code regulators mandate compliance with AS 5216 for post-installed anchors, creating market access barriers that favor technically credentialed suppliers. China's SAMR oversees GB standards for construction chemicals, influencing domestic production specifications and import qualification protocols. Stakeholders must monitor evolving certification reciprocity agreements between national standards bodies, as harmonization would reshape competitive positioning across the region's fragmented regulatory environment.
Market Dynamics
China's high-speed rail expansion and India's BIS certification mandates are restructuring procurement patterns, forcing suppliers to recalibrate technical service capabilities and manufacturing footprints across the region.
Growth Catalysts
- Seismic-resistant construction codes:Japan's METI enforces JIS standards for earthquake-resistant materials, mandating high-performance grout formulations in high-seismic zones and accelerating product development cycles.
- Infrastructure rehabilitation:Aging tunnels and bridges across Japan and South Korea require specialized injection grouts for crack sealing and structural stabilization, expanding the addressable maintenance market.
- Mining sector demand:Australia's underground mining operations in Western Australia and Queensland command specialized ground anchoring systems with tailored resin formulations for rock stabilization.
Market Restraints
- Portland cement price volatility:Input cost fluctuations for cementitious grouts compress margin pools for mid-tier suppliers lacking backward integration into raw material sourcing.
- Import qualification barriers:China's SAMR oversees GB standards that create technical documentation burdens for foreign manufacturers seeking domestic market access.
- Epoxy resin substitution pressure:Vinylester systems gain traction in marine and chemical exposure applications, displacing traditional epoxy-based anchoring in coastal infrastructure.
Strategic Opportunities
- Indonesia's trans-island connectivity:The country's archipelagic bridge and tunnel programs require specialized marine grouting expertise currently underpenetrated by domestic suppliers.
- Vietnam's port modernization:Deep-water terminal expansions in Hai Phong and Ba Ria-Vung Tau create demand for high-specification post-installed anchoring in salt-exposure environments.
- Digital inventory platforms:Construction supply intermediaries in Southeast Asia are adopting B2B procurement portals, enabling direct technical specification uploads from engineering firms.
Industry Challenges
- Certification timeline compression:Australia's AS 5216 compliance requirements for post-installed anchors extend product validation cycles, delaying revenue recognition for new formulation launches.
- Application engineering scarcity:The shortage of certified field technicians for injection grout placement in underground mining constrains deployment velocity in Australia's Pilbara region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Anchors and Grouts Market |
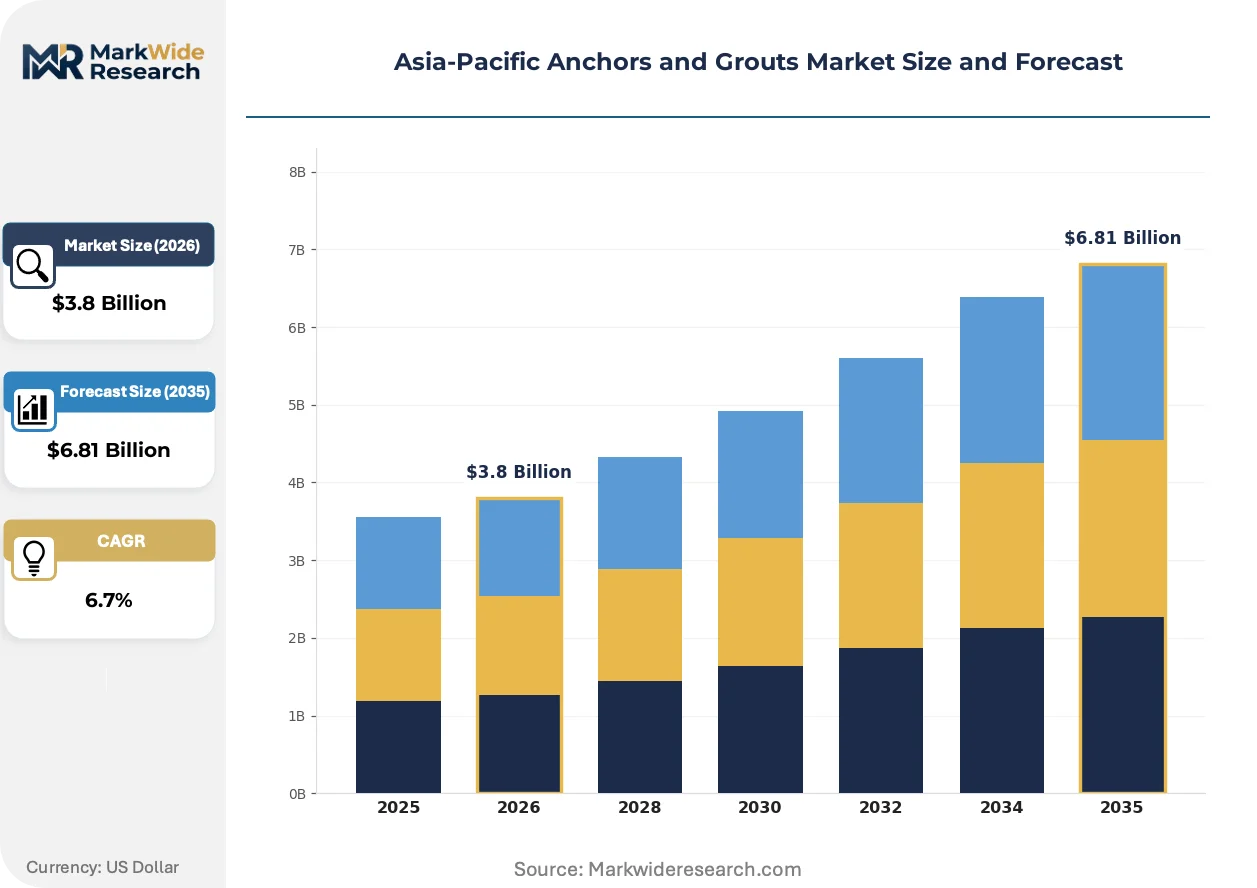
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Anchors, Mechanical Anchors, Grout Fillers, Injection Grouts End User: Construction, Marine, Oil & Gas, Mining Application: Concrete Repair, Structural Stabilization, Marine Applications, Ground Anchoring Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Distributors |
| Companies Covered | Ardex Group, MBCC Group, Sika AG, MAPEI S.p.A., Fischer Group, Hilti Corporation, Saint-Gobain, Würth Group, Fosroc International Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Anchors and Grouts Market Strategic Shifts
Grout formulation chemistry and installation monitoring systems are converging to reshape quality assurance protocols across civil engineering applications in the region.
Ultrasonic pulse velocity testing equipment is digitizing quality control workflows for injection grout placement. Mining contractors in Australia's Bowen Basin are deploying real-time monitoring systems to verify compressive strength development in ground anchoring applications. This technology is digitizing documentation standards that previously relied on destructive core sampling, compressing project handover timelines.
India's BIS certification mandates for structural anchoring systems are accelerating product standardization among domestic and multinational suppliers. The Bureau of Indian Standards now requires third-party testing for load-transfer devices used in commercial high-rise construction. Domestic manufacturers are responding by establishing in-house metallurgical laboratories to reduce external certification dependencies.
Engineering firms in Southeast Asia are consolidating anchor specifications around performance-based procurement criteria rather than brand-specific approvals. State-backed developers in Thailand and the Philippines now accept equivalent technical certifications from multiple suppliers, displacing sole-source relationships that previously locked contractors into premium pricing tiers. This pattern is most visible in Bangkok's mass transit extensions, where mid-tier contractors specify specialized systems previously reserved for flagship projects.
Asia-Pacific Anchors and Grouts Market Segmentation
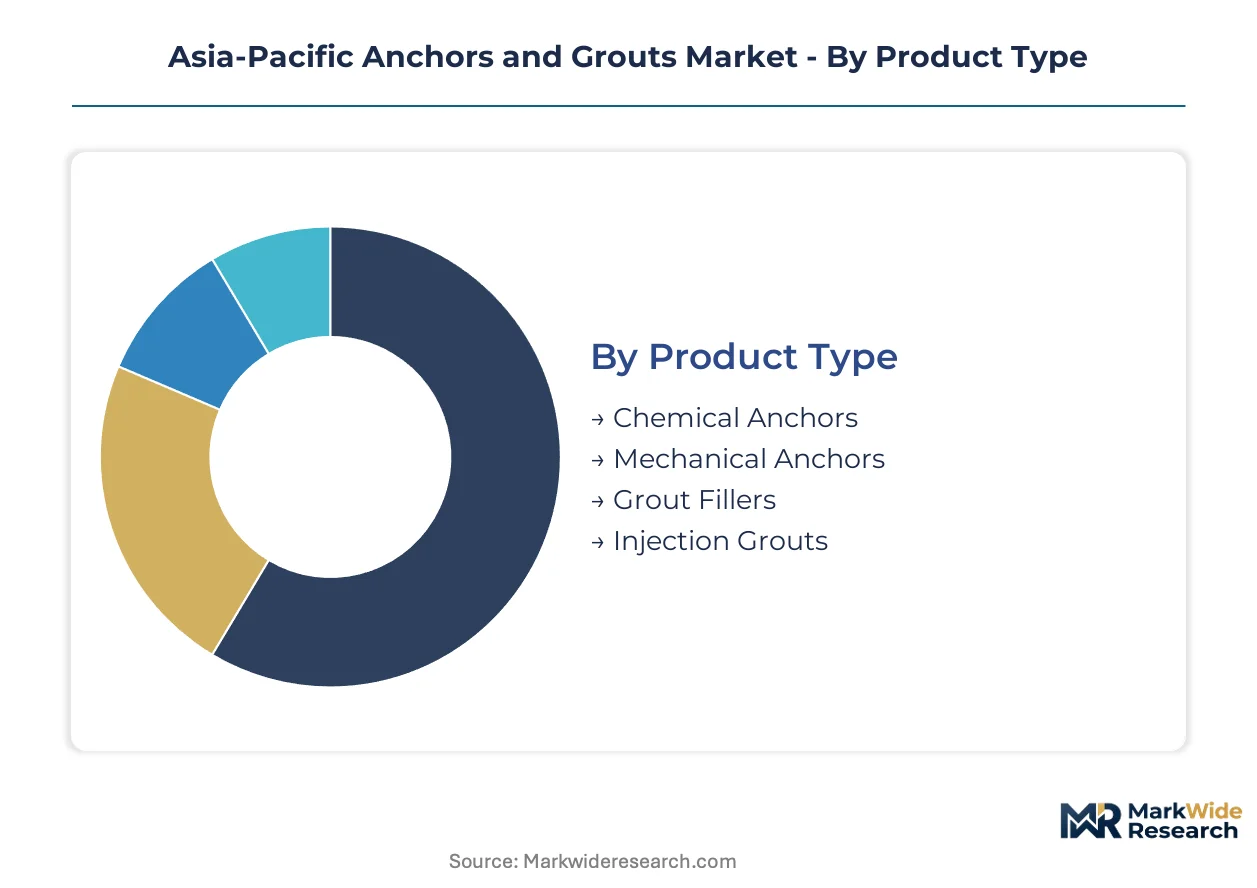
Segmentation in the Asia-Pacific anchors and grouts market reveals how procurement authority, application criticality, and supply chain configuration reshape competitive access. Product specifications diverge sharply between seismic-resistant infrastructure and routine maintenance, while distribution channel selection determines whether suppliers capture specification influence or compete on price alone.
Product Type:
Formulation chemistry spans resin-based bonding systems, mechanical load-transfer devices, and cementitious compounds engineered for compressive strength targets ranging from 40 to 100 MPa depending on substrate and load requirements.
- Chemical Anchors:Epoxy, vinylester, and hybrid resin formulations bond threaded rods and rebar into concrete and masonry substrates. Japan's METI-enforced JIS standards for earthquake-resistant construction materials concentrate specification authority for high-seismic zones around certified formulations with documented cyclic load performance.
- Injection Grouts:Low-viscosity cementitious or resin-based compounds penetrate crack networks for structural rehabilitation. Aging tunnels and bridges across Japan and South Korea are expanding procurement volumes for specialized formulations with controlled shrinkage and rapid strength development.
- Mechanical Anchors:Expansion and undercut devices achieve load transfer through friction and mechanical interlock. Australia's AS 5216 compliance mandates for post-installed anchors restrict market access to technically credentialed suppliers with validated torque-controlled installation protocols.
- Grout Fillers:High-flow cementitious compounds fill voids beneath baseplates and structural elements. Mining contractors in Australia's Pilbara region specify rapid-setting formulations to compress equipment installation schedules.
The dominant share belongs to chemical anchors, while injection grouts are closing the gap fastest.
End User:
Customer procurement sophistication ranges from engineering-driven specification in heavy infrastructure to price-sensitive purchasing in residential construction, with certification requirements creating tiered supplier access barriers.
- Construction:Commercial high-rise and infrastructure developers specify performance-certified anchoring systems with third-party load testing documentation. India's BIS certification mandates for structural anchoring systems are accelerating product standardization among domestic and multinational suppliers serving this segment.
- Mining:Underground operations in Western Australia and Queensland command specialized ground anchoring with resin formulations tailored to rock mass conditions and groundwater chemistry. The shortage of certified field technicians for injection grout placement constrains deployment velocity in the Bowen Basin.
- Marine:Port infrastructure and offshore installations require corrosion-resistant anchoring in salt-exposure environments. Vietnam's deep-water terminal expansions in Hai Phong and Ba Ria-Vung Tau are generating specification demand for high-performance post-installed systems.
- Oil & Gas:Petrochemical facilities and LNG terminals specify fire-resistant and chemically inert anchoring formulations. Indonesia's trans-island connectivity programs are creating procurement opportunities for marine grouting expertise in bridge and tunnel foundations.
Construction commands the deepest specification authority, though mining generates the steepest margin premiums for technically credentialed suppliers.
Application:
Engineering risk profiles determine whether procurement prioritizes initial cost minimization or lifecycle performance assurance, with structural stabilization applications imposing the most stringent certification burdens.
- Structural Stabilization:Load-transfer applications in seismic zones and heavy industrial facilities demand documented performance under cyclic and sustained loading. Engineering certification requirements limit supplier participation to manufacturers with in-house testing capabilities and established regulatory relationships.
- Ground Anchoring:Rock and soil stabilization in mining and civil engineering applies tensioned anchors with specialized grout formulations. Real-time monitoring systems in Australia's Bowen Basin are digitizing quality control workflows and compressing project handover timelines.
- Concrete Repair:Crack injection and spall rehabilitation in aging infrastructure utilizes low-viscosity grouts with controlled setting characteristics. Japan's tunnel and bridge maintenance programs are expanding addressable market volume for specialized injection systems.
- Marine Applications:Subsea and splash-zone installations require formulations resistant to chloride ingress and biological fouling. MBCC Group's technical service capabilities in high-specification marine grouting anchor its regional competitive position.
Structural stabilization captures the highest certification barriers, while ground anchoring is expanding most quickly on mining sector investment.
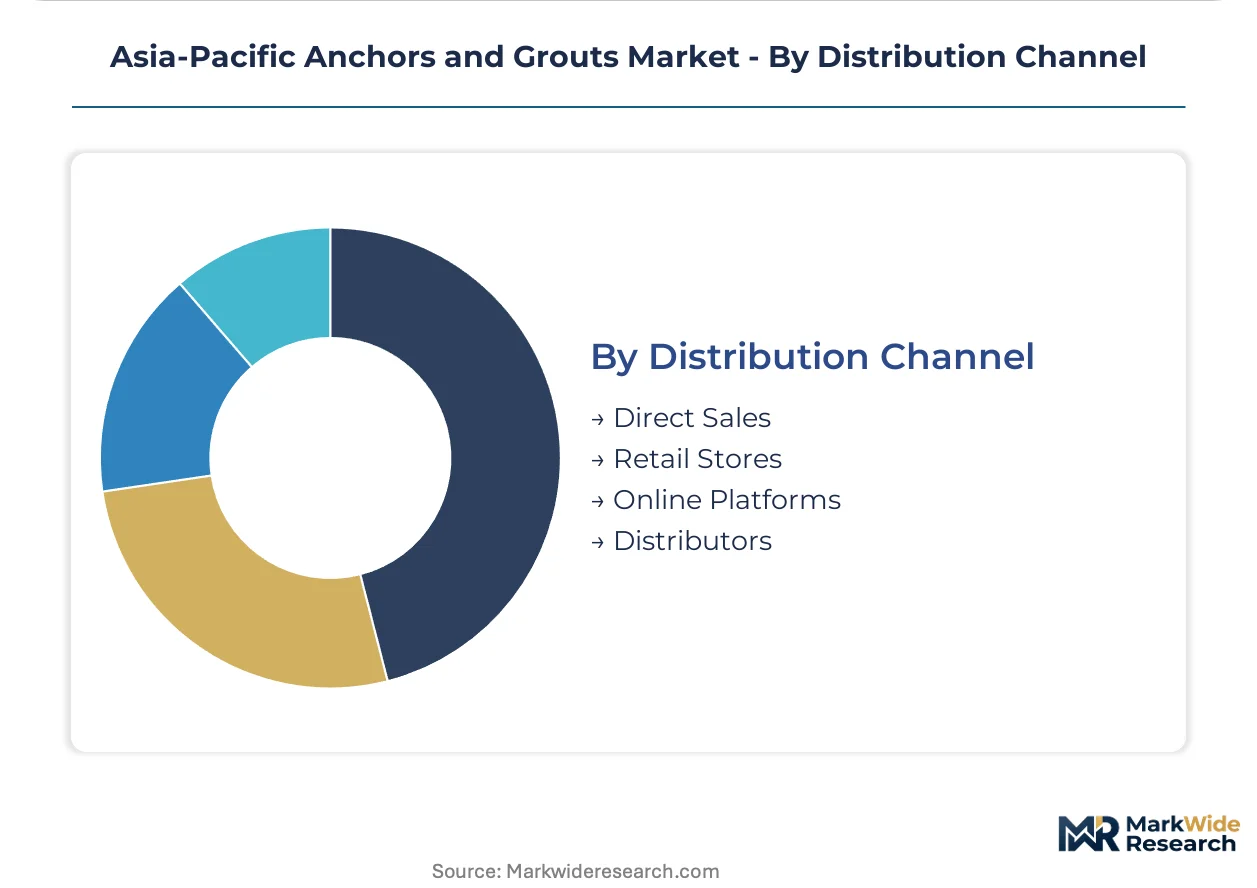
Distribution Channel:
Channel selection determines whether suppliers retain specification influence through direct technical engagement or cede margin to intermediaries in fragmented construction supply markets.
- Direct Sales:Manufacturer-controlled technical specification and application engineering bypass traditional supply intermediaries. Hilti Corporation differentiates by controlling direct distribution channels that capture procurement authority from engineering firms.
- Distributors:Regional construction supply intermediaries aggregate demand from mid-tier contractors and smaller developers. Project finance fragmentation in Southeast Asia is allowing these channels to specify specialized systems previously reserved for state-backed developers.
- Online Platforms:B2B procurement portals enable direct technical specification uploads from engineering firms. Construction supply intermediaries in Southeast Asia are adopting these platforms to streamline anchor specification consolidation.
- Retail Stores:Hardware and construction material outlets serve residential and light commercial maintenance applications with standardized mechanical anchors and pre-packaged grout systems.
Direct sales retains the strongest margin position, though distributor channels are gaining specification authority fastest as project finance fragments across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates with engineering firms specifying certified anchoring systems for high-seismic infrastructure, mining operations, and marine installations across the region's most capital-intensive construction corridors.
China
High-speed rail corridor modernization drives procurement of high-performance injection grouts for tunnel stabilization and trackbed anchoring. SAMR oversees GB standards for construction chemicals, creating technical documentation requirements for imported formulations. Manufacturing clusters in the Yangtze River Delta supply specialized grout systems for domestic infrastructure developers.
Japan
Aging tunnel and bridge rehabilitation expands demand for crack-injection grouts with controlled shrinkage characteristics. METI enforces JIS standards for earthquake-resistant construction materials, mandating documented cyclic load performance for structural applications. Engineering firms in the Kanto region specify certified formulations for Tokyo's mass transit maintenance programs.
India
Commercial high-rise construction accelerates procurement of BIS-certified structural anchoring systems with third-party load testing documentation. The Bureau of Indian Standards now mandates certification for load-transfer devices in commercial construction. Domestic manufacturers in Maharashtra and Gujarat are establishing in-house metallurgical laboratories to reduce external certification dependencies.
Australia
Underground mining operations in Western Australia and Queensland command specialized ground anchoring systems with resin formulations tailored to rock mass conditions. Building code regulators mandate AS 5216 compliance for post-installed anchors, restricting market access to technically credentialed suppliers. Real-time monitoring systems in the Bowen Basin are digitizing quality control workflows for grout placement.
Vietnam
Deep-water terminal expansions in Hai Phong and Ba Ria-Vung Tau generate specification demand for high-performance post-installed anchoring in salt-exposure environments. Port modernization programs are creating procurement opportunities for corrosion-resistant formulations. Engineering procurement for marine infrastructure is consolidating around performance-based technical criteria.
Asia-Pacific Anchors and Grouts Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structured by certification barriers and technical service depth. The competitive landscape fragments into three tiers: multinational chemical conglomerates with regional manufacturing footprints, specialized construction chemical firms with marine and seismic expertise, and distributor-dependent domestic suppliers serving price-sensitive segments. M&A activity concentrates among European-headquartered firms acquiring Southeast Asian technical service capabilities, while capacity expansion focuses on grout formulation plants proximate to Australia's mining belt.
Within the multinational tier, Sika AG, MBCC Group, and Hilti Corporation occupy positions shaped by divergent channel strategies. Sika leverages regional manufacturing scale across multiple ASEAN markets. MBCC anchors its presence through technical service depth in high-specification marine applications. Hilti differentiates by controlling direct distribution channels that bypass traditional construction supply intermediaries, capturing specification influence from engineering firms rather than competing on distributor price alone.
| Leading Market Players |
|---|
| Ardex Group |
| MBCC Group |
| Sika AG |
| MAPEI S.p.A. |
| Fischer Group |
| Hilti Corporation |
| Saint-Gobain |
| Würth Group |
| Fosroc International Ltd. |
| Others |
Value Chain & Pricing Dynamics
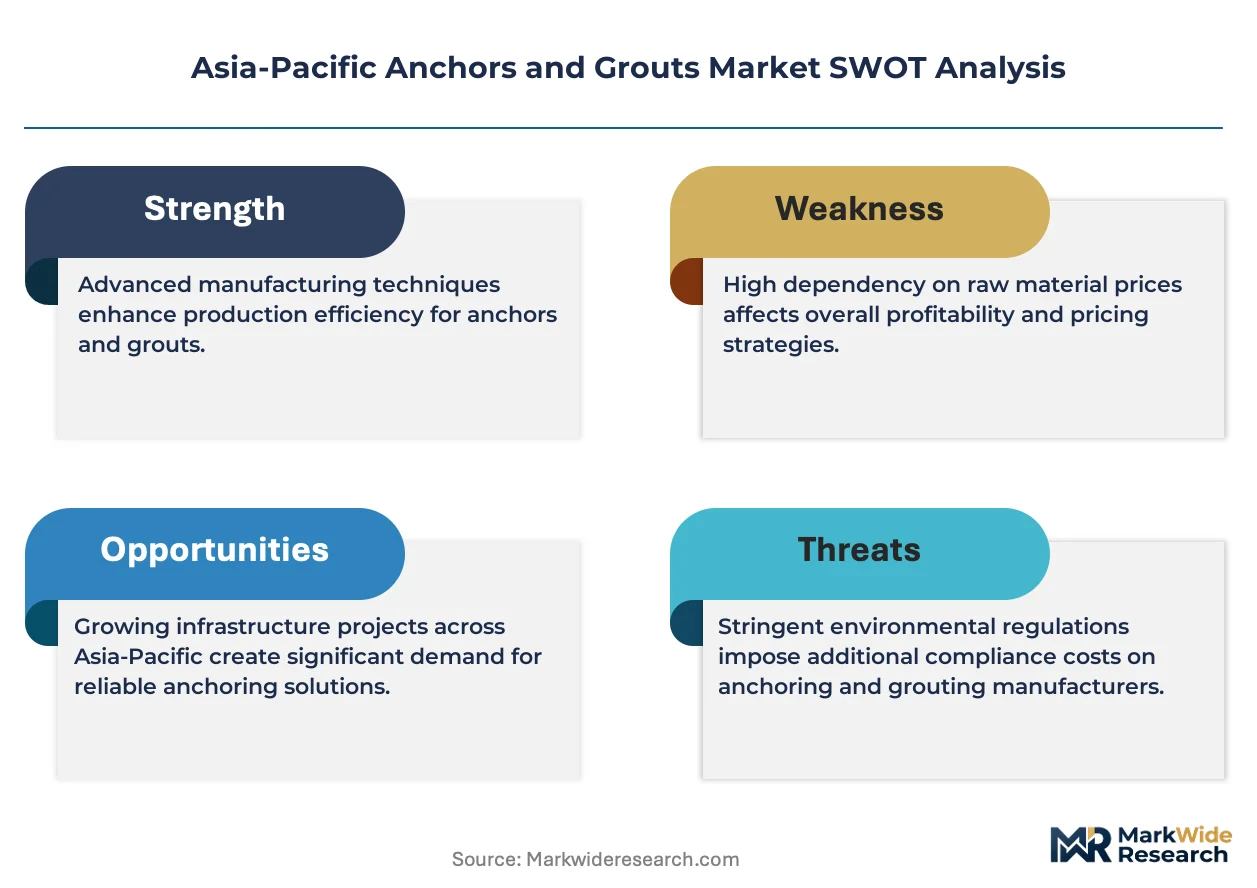
Overcapacity in China's Yangtze River Delta grout formulation plants is compressing supplier margins and accelerating price competition for standard-grade cementitious products, while specialized resin manufacturers in Japan and Australia maintain pricing power through technical certification scarcity.
Pricing Analysis
Certification level creates the primary spread between supplier tiers, with JIS-certified seismic formulations commanding substantial premiums over uncertified alternatives. Three-tier pricing structure separates premium resin systems from standard cementitious grouts and economy mechanical anchors. Price erosion runs through mid-tier cementitious products as Chinese capacity expansion outpaces regional demand growth. Mining contractors in Australia's Pilbara region exhibit the lowest price sensitivity due to operational downtime costs, while Southeast Asian residential developers drive aggressive procurement negotiations.
Supply Chain Analysis
Extended payment terms from Australian mining majors and supply-chain finance facilities from Japanese trading houses are reshaping working capital requirements across the supplier base. Manufacturing concentrates in China, Japan, and Australia, with formulation chemistry expertise anchored in Japanese and Australian technical centers. Raw material flows draw from Saudi epoxy resin producers, Australian Portland cement suppliers, and Korean vinylester polymer plants. Single-source vulnerability around specialized resin intermediates creates supply risk for seismic-grade formulations. Distribution runs through direct technical sales for high-specification applications and regional construction supply intermediaries for standardized products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as Australia's mining capital expenditure rebounds and Japan's infrastructure rehabilitation programs accelerate procurement timelines.
For Market Incumbents: Entrench specification authority by deepening technical service capabilities in Australia's Bowen Basin mining operations and securing JIS certification reciprocity for expanded Japanese public works access. Vinylester substitution pressure threatens epoxy-based product margins, making backward integration into specialty resin sourcing the critical defensive lever. Capacity consolidation in Southeast Asian distributor networks will capture fragmented project finance flows. For New Entrants and Emerging Players: Mid-market commercial buildings in Vietnam and Indonesia represent the most penetrable entry point, as performance-based procurement criteria displace legacy sole-source relationships. Indonesia's trans-island bridge programs lack domestic marine grouting expertise, creating specification gaps for credentialed foreign suppliers. A technical service partnership model with established EPC contractors offers the fastest route to specification influence without manufacturing footprint investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with captive technical service relationships in Australian mining and Japanese seismic infrastructure. The five-to-ten year viability window favors acquisition targets with established regulatory relationships in multiple Asia-Pacific jurisdictions rather than pure manufacturing scale. The signal to watch is certification reciprocity agreements between national standards bodies, which would reshape competitive positioning and unlock valuation multiples for harmonized product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in BIS Standards | Unlocks access to India's commercial high-rise construction procurement with third-party testing documentation. |
| Technical Service Expansion in Mining Belts | Captures premium margins in Australia's Pilbara region through certified field technician deployment. |
| Marine Grouting Capability Acquisition | Addresses underpenetrated demand from Indonesia's archipelagic bridge and tunnel foundation programs. |
| Direct Distribution Channel Buildout | Bypasses construction supply intermediaries to capture specification authority from engineering firms. |
| Real-Time Monitoring System Integration | Compresses project handover timelines in Australian mining through digitized quality control workflows. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant managers at grout formulation facilities, procurement leads at Australian mining contractors, technical directors at marine engineering firms, and regulatory affairs specialists at standards bodies; alongside secondary validation through customs trade databases, BIS certification registries, JIS standard documentation, and SEC filings from listed construction chemical manufacturers. Bottom-up volume estimates from country-level project pipelines were triangulated against top-down market sizing from regional production capacity data.
Forecast inputs incorporated product type segmentation across chemical anchors, injection grouts, mechanical anchors, and grout fillers; end-use segmentation spanning construction, mining, marine, and oil and gas applications; and geographic clustering by regulatory framework similarity. CAGRs were derived from regression analysis of historical procurement patterns against infrastructure investment cycles, with specific incorporation of Australia's AS 5216 compliance timeline impacts and Japan's METI-mandated seismic material replacement schedules.
Stress conditions across Portland cement price volatility, Australian mining investment cycles, and certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and infrastructure program continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Construction
Concrete and Cement Dissolver Market
Specialty Construction
Global Fencing Market
Specialty Construction
Europe Anchors and Grouts Market
Specialty Construction
Construction Repaint Market
Specialty Construction
India Anchors and Grouts Market
Specialty Construction
Asia-Pacific Waterproofing Solutions Market
Specialty Construction
Welded Metal Bellows Market
Specialty Construction
Roller Shutter Market
Specialty Construction
Portable Walls Market
Specialty Construction
Shotcrete Accelerators Market
Specialty Construction
South America Anchors and Grouts Market
Specialty Construction
ASEAN Waterproofing Market
Specialty Construction
Temporary Fencing Panels Market
Specialty Construction
Indonesia Waterproofing Solutions Market
Specialty Construction
Composite Repair Market
Specialty Construction
Expandable Shelter Market