
 Flat Plate Solar Collector Market | 2026-2036
Flat Plate Solar Collector Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Plate Solar Collector Market Analysis
Aftermarket service revenue is narrowing as manufacturers integrate installation and maintenance into initial equipment contracts. Rheem leverages its established distribution network across North American HVAC channels to capture bundled service margins. Greenonetec specializes in large-scale collector arrays for district heating utilities across Northern Europe. Himin Solar anchors volume production through backward integration into tempered glass and selective coating supply.
A flat plate solar collector consists of an insulated box containing an absorber plate bonded to fluid-carrying tubes, covered with transparent glazing that achieves typical thermal efficiencies of 50-70% depending on operating temperature and insolation conditions. The device converts incident solar radiation into usable thermal energy for water or space heating applications across residential, commercial, and industrial settings. Active solar collectors dominate commercial and industrial installations where pumped circulation enables higher temperature differentials and larger system scales. Water heating applications command the largest share of end-user demand, while process heating represents the fastest-expanding segment as food processing and textile manufacturers seek thermal decarbonization pathways.
FERC net metering rules and the IRA clean energy tax credits shape US deployment economics by reducing payback periods for residential and commercial installations. Ecodesign requirements under the EU Green Deal and F-Gas Regulation phase-outs push European manufacturers toward higher-efficiency absorber coatings and low-global-warming-potential heat transfer fluids. China's MIIT efficiency labeling standards and dual carbon goals mandate minimum performance thresholds that filter lower-tier domestic producers. Stakeholders must monitor how building code electrification mandates in key states and provinces redefine the competitive boundary between solar thermal and heat pump technologies.
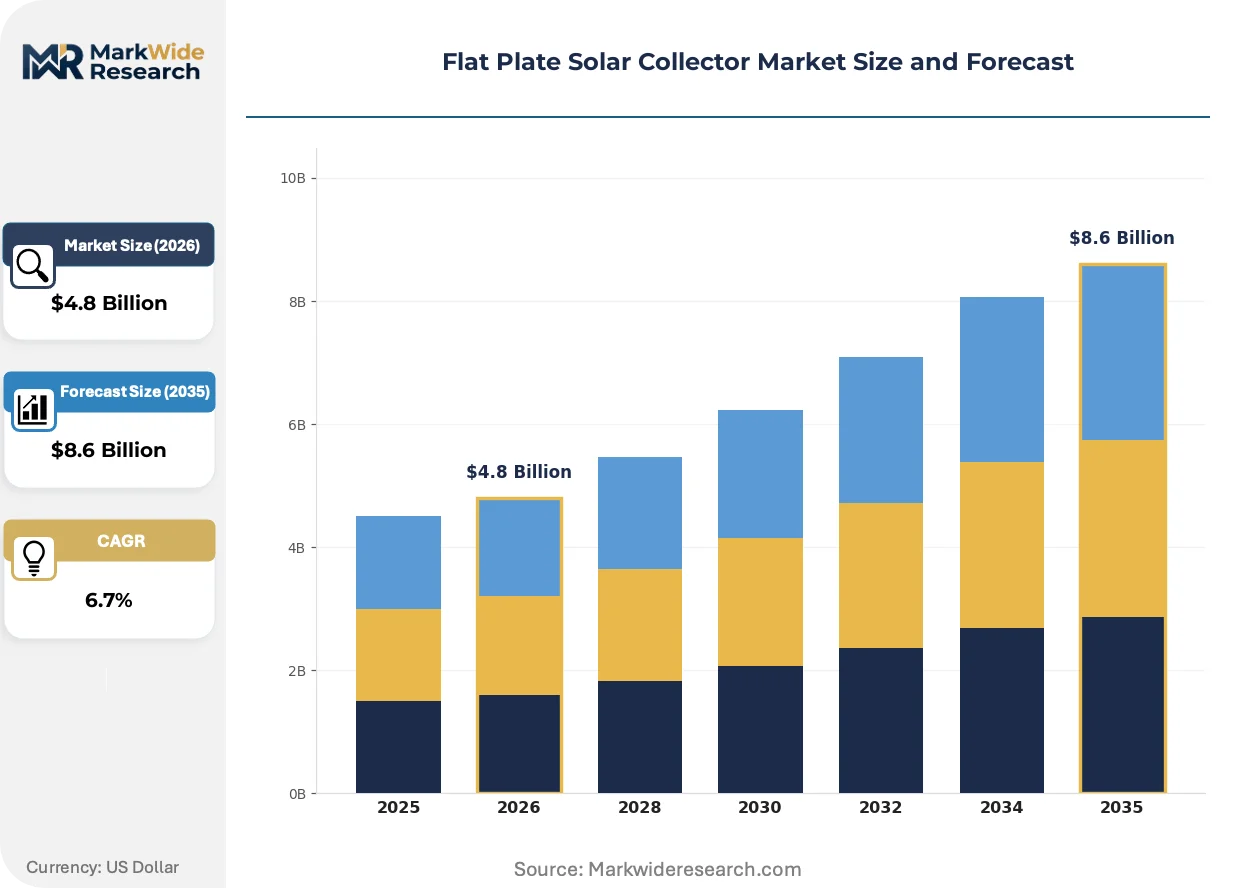
Market Dynamics
Building-integrated solar mandates are compressing installation timelines and forcing collector manufacturers to redesign form factors for architectural compatibility. Germany's Bavaria region exemplifies this pressure, where municipal codes now require solar thermal pre-installation in new residential construction.
Growth Catalysts
- Residential water heating retrofit cycles:Suburban housing stock across Germany and Austria reaches replacement age simultaneously, triggering synchronized demand waves for collector replacements.
- IRA clean energy tax credits:US federal incentives reduce residential payback periods below seven years in sun-belt states, accelerating homeowner conversion decisions.
- Selective coating chemistry advances:Sputtered titanium-nitride-oxide layers push absorber efficiency above 95% emissivity ratios, expanding viable operating temperature ranges.
Market Restraints
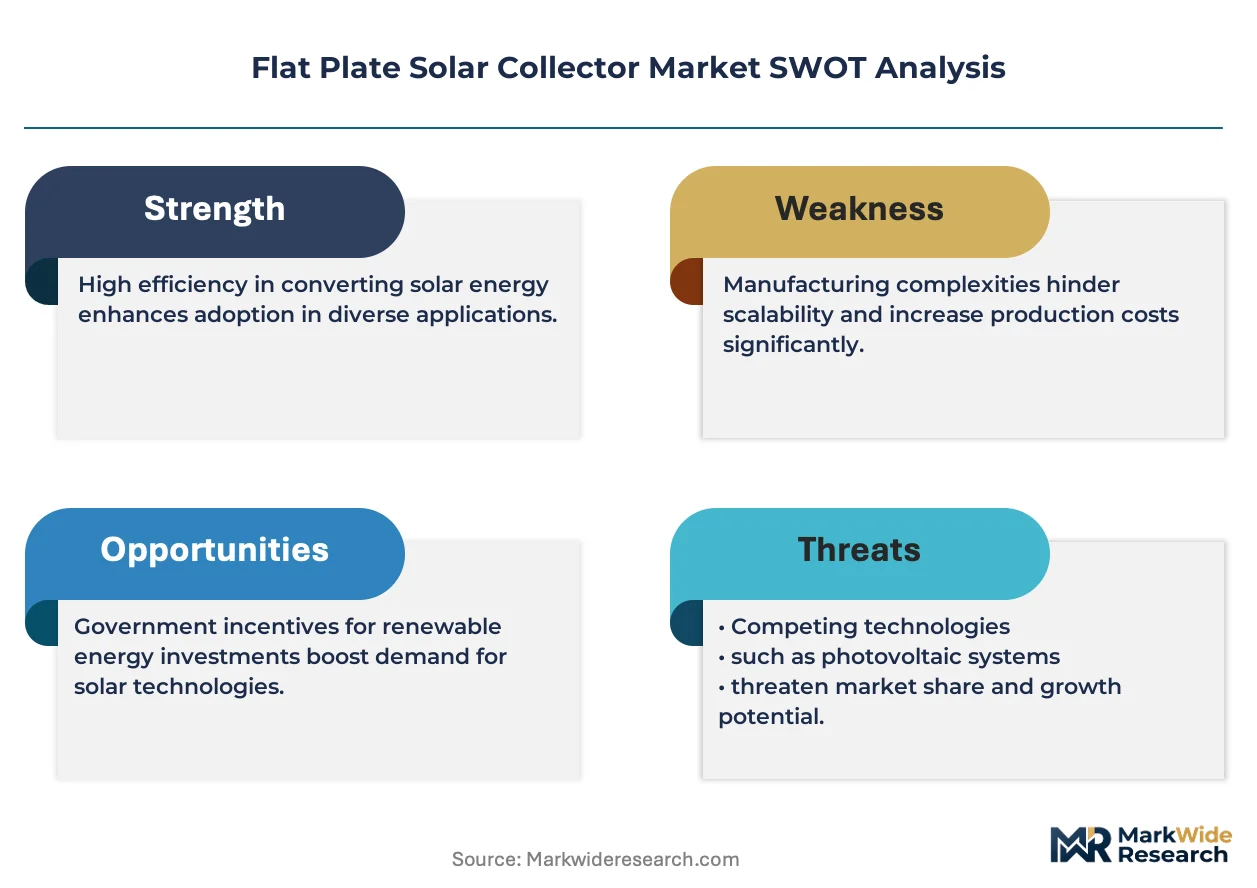
- Copper and aluminum price volatility:Absorber plate materials constitute 35-40% of bill-of-materials costs, exposing margins to London Metal Exchange fluctuations.
- Single-source tempered glass supply:Collector glazing concentrates among three Chinese manufacturers, creating geographic chokepoints for European and North American assemblers.
- Heat pump substitution threat:Building code electrification mandates in California and New York position air-source heat pumps as competing thermal decarbonization pathways.
Strategic Opportunities
- Industrial process heat expansion:Food pasteurization and textile dyeing facilities in Portugal and Spain seek 80-120°C thermal inputs that flat plate arrays now deliver cost-effectively.
- District heating utility procurement:Copenhagen and Stockholm municipal networks tender multi-megawatt collector fields under 20-year heat purchase agreements.
- EU F-Gas Regulation phase-outs:Restrictions on synthetic heat transfer fluids create openings for propylene glycol and ionic liquid alternatives with lower global warming potential.
Industry Challenges
- Certification timeline compression:China's GB standards revision cycles now complete in 18 months versus historical 36-month windows, straining testing laboratory capacity.
- Integration complexity with legacy hydronics:Victorian-era radiator systems in UK housing stock require flow-temperature matching that standard collector controllers cannot address without custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Plate Solar Collector Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Solar Collectors, Passive Solar Collectors, Hybrid Solar Collectors, Flat-Plate Solar Panels End User: Residential Users, Commercial Users, Industrial Applications, Government Projects Application: Space Heating, Water Heating, Pool Heating, Process Heating Installation Type: Roof-Mounted, Ground-Mounted, Wall-Mounted, Integrated Systems |
| Companies Covered | Rheem, SunMaxx Solar, Greenonetec, Fivestar, Solimpeks, Viessmann, Himin Solar, SunEarth, SolarWorld, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Plate Solar Collector Market Emerging Trajectories
Material science breakthroughs and regulatory tightening are converging to redefine collector performance benchmarks. Manufacturers must now optimize simultaneously for thermal efficiency, architectural integration, and fluid compatibility.
Perforated micro-channel absorber designs are rendering obsolete traditional tube-and-sheet bonding methods. District heating utilities in Denmark specify these extruded aluminum configurations for their superior freeze resistance and reduced fluid volume. The shift eliminates solder joint failure modes that previously dominated warranty claims.
EU Ecodesign requirements under the Green Deal mandate minimum optical efficiency thresholds that filter non-compliant imports. Spanish and Italian manufacturers accelerate sputtering line investments to meet selective coating specifications. German certification bodies report 15% applicant rejection rates for absorber submissions failing emissivity tests.
Aftermarket service bundling into original equipment contracts is displacing third-party maintenance providers. Rheem's North American HVAC channel integration captures recurring revenue streams that independent installers previously controlled. This consolidation concentrates service capability within factory-trained networks across US sun-belt states.
Flat Plate Solar Collector Market Segmentation
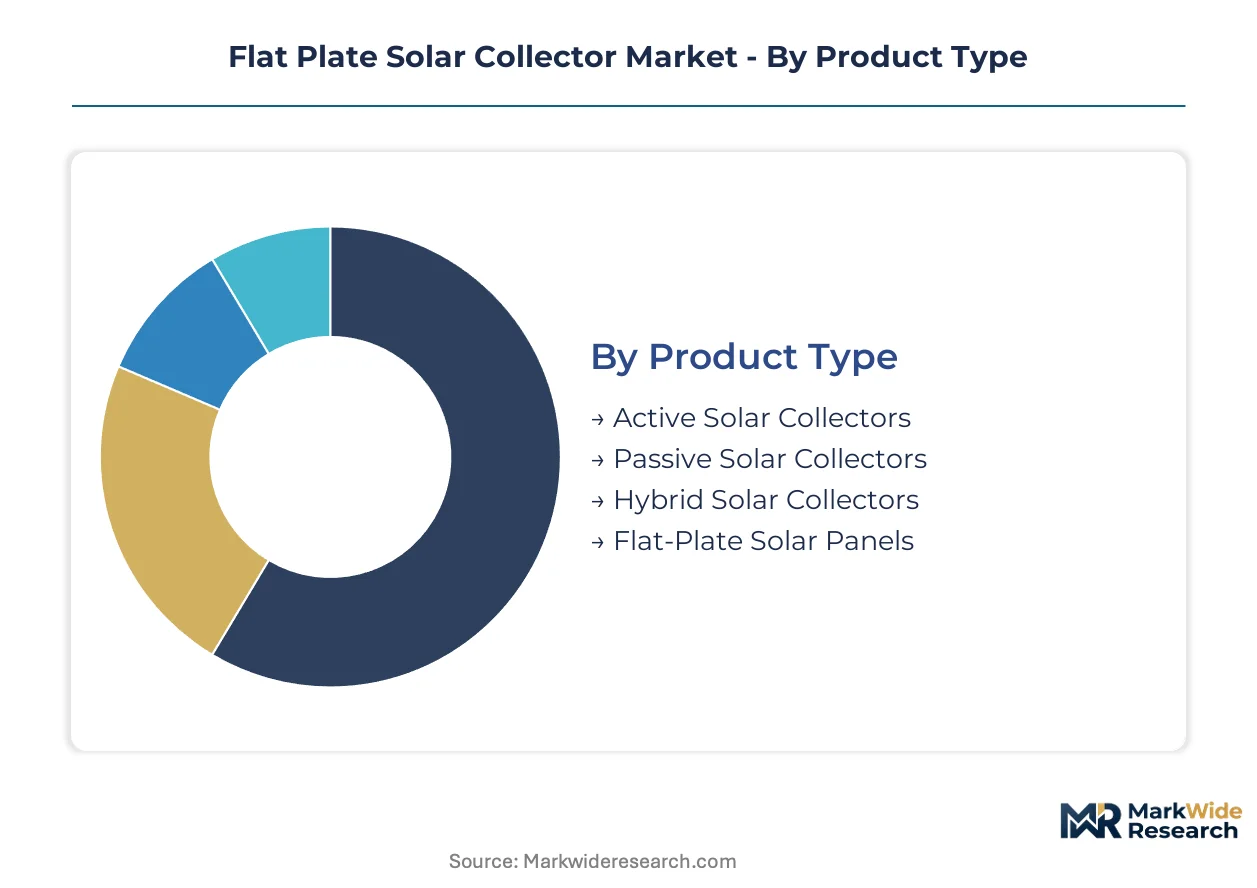
Flat plate solar collector deployment varies sharply across thermal demand profiles, installation constraints, and regulatory environments. Manufacturers must align absorber specifications, mounting hardware, and control systems to each segment's operating temperature and architectural integration requirements.
Product Type:
Cost tier differentiation separates circulation-dependent systems from passive thermal siphon designs.
- Active Solar Collectors:Pumped glycol or water circuits enable 60-80°C output for space heating and industrial process loads. Germany's district heating utilities specify active systems for their precise temperature control and scalability.
- Passive Solar Collectors:Thermosiphon circulation eliminates parasitic pump energy, suiting residential water heating in sun-belt climates. Australia's Queensland housing retrofits favor passive configurations for their zero-maintenance operation.
- Hybrid Solar Collectors:Photovoltaic-thermal integration captures electrical and thermal output from shared aperture area. Portugal's agro-industrial facilities deploy hybrid arrays to maximize land-use efficiency.
- Flat-Plate Solar Panels:Standardized box-and-tube construction dominates volume production for residential retrofit markets. China's MIIT efficiency labeling drives quality tiering across domestic manufacturing bases.
Active systems command the established base. The steepest expansion runs through hybrid configurations.
End User:
Application maturity separates established residential retrofit demand from emerging industrial thermal substitution.
- Residential Users:Single-family and multi-family dwellings account for replacement-cycle volume across German and Austrian suburban housing stock. IRA tax credits compress payback periods below seven years in US sun-belt states.
- Commercial Users:Hotels, hospitals, and office buildings require 50-70°C service water with predictable load profiles. Spain's hospitality sector tenders collector arrays under energy service company financing.
- Industrial Applications:Food pasteurization and textile dyeing seek 80-120°C thermal inputs previously met by gas boilers. Portugal's dairy processors pilot flat plate arrays for CIP (clean-in-place) sterilization loops.
- Government Projects:Municipal procurement mandates drive standardization and long-term service contracts. Copenhagen's district heating network tenders multi-megawatt collector fields under 20-year heat purchase agreements.
Residential users anchor current volumes. Industrial applications are climbing the fastest as thermal decarbonization deadlines approach.
Application:
Operating temperature range dictates absorber coating selection and glazing specifications.
- Space Heating:Low-temperature hydronic integration requires 30-50°C collector output matched to underfloor or radiator systems. UK's Victorian-era housing stock demands custom flow-temperature controllers.
- Water Heating:Domestic hot water at 45-60°C represents the largest addressable demand pool across all geographies. China's GB standards tighten optical efficiency thresholds for water heating certification.
- Pool Heating:Unglazed or single-glazed collectors suffice for 25-35°C pool temperature maintenance. Australia's recreational facility sector specifies polymer absorber variants for saltwater corrosion resistance.
- Process Heating:Industrial thermal loads at 80-150°C push selective coating emissivity above 95%. Denmark's district heating utilities specify perforated micro-channel absorbers for freeze resistance and reduced fluid volume.
Water heating holds the dominant share. Process heating is gaining share fastest as manufacturers achieve higher temperature differentials.
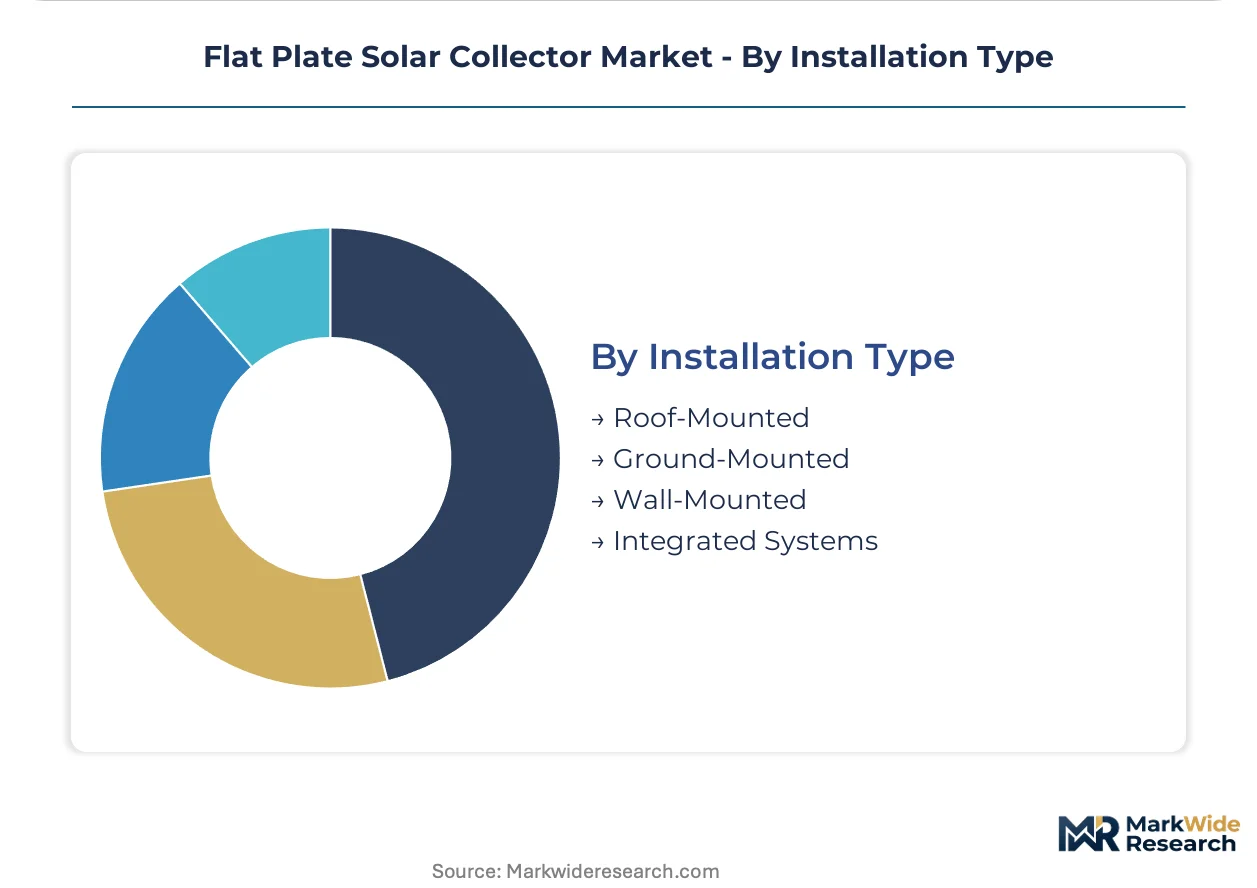
Installation Type:
Mounting configuration determines structural loading, architectural integration, and maintenance access economics.
- Roof-Mounted:Tilted rack systems dominate residential retrofits across pitched roof geometries. Germany's Bavaria region mandates solar thermal pre-installation in new residential construction.
- Ground-Mounted:Large-scale arrays for district heating and industrial process heat optimize tilt angles and cleaning access. Sweden's municipal utilities prefer ground-mount for megawatt-scale collector fields.
- Wall-Mounted:Vertical facade integration serves space heating in high-rise residential with limited roof area. Austria's passive house developments specify wall-mounted collectors for architectural coherence.
- Integrated Systems:Building-integrated solar thermal (BIST) replaces conventional cladding materials with collector facades. EU Green Deal Ecodesign requirements accelerate BIST adoption for new construction.
Roof-mounted configurations retain the installed base. Integrated systems show the steepest expansion trajectory as building codes tighten renewable thermal mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential water heating dominates German and Austrian deployments, while industrial process heat drives Portuguese and Spanish procurement patterns. China's market concentrates on efficiency-tiered domestic manufacturing for export and local installation.
Germany
Suburban housing replacement cycles and Bavarian building-integrated solar mandates synchronize demand waves. The EU Green Deal Ecodesign requirements tighten absorber coating specifications. Munich and Nuremberg municipal codes now require solar thermal pre-installation in new residential construction.
China
MIIT efficiency labeling standards and dual carbon goals filter lower-tier producers from domestic supply. GB standards revision cycles compress to eighteen months, straining testing laboratory capacity. Shandong and Jiangsu provinces anchor volume production through captive tempered glass and selective coating supply chains.
United States
IRA clean energy tax credits reduce residential payback periods below seven years in sun-belt states. FERC net metering rules shape deployment economics for commercial installations. California and Florida housing retrofits concentrate demand through established HVAC distribution channels.
Portugal
Agro-industrial facilities and dairy processors pilot flat plate arrays for pasteurization and CIP sterilization loops. EU F-Gas Regulation phase-outs create openings for propylene glycol heat transfer fluids. Lisbon and Porto districts tender collector arrays under energy service company financing models.
Denmark
Copenhagen's district heating network tenders multi-megawatt collector fields under twenty-year heat purchase agreements. Perforated micro-channel absorber designs address freeze resistance requirements. Aarhus municipal utilities specify ground-mounted configurations for megawatt-scale installations.
Flat Plate Solar Collector Market Vendor Landscape
Capability concentration sits with specialized coating and absorber technology developers; scale advantage sits with integrated HVAC conglomerates and volume manufacturers. The market structures around three tiers: premium European engineering specialists, mid-scale regional assemblers, and high-volume Chinese producers. Dominant competitive moves include backward integration into glazing and coating supply, plus bundling installation services into original equipment contracts.
Among Germany-based engineering specialists, Viessmann and Greenonetec occupy positions emphasizing system integration and district heating utility relationships. Rheem exemplifies the HVAC-channel archetype through North American distribution network leverage. Himin Solar anchors the volume-production tier through in-house supply of tempered glass and selective coating materials.
| Leading Market Players |
|---|
| Rheem |
| SunMaxx Solar |
| Greenonetec |
| Fivestar |
| Solimpeks |
| Viessmann |
| Himin Solar |
| SunEarth |
| SolarWorld |
| Others |
Supply Flow & Price Mechanics
Single-source tempered glass dependency in collector glazing concentrates pricing power among three Chinese manufacturers, forcing European and North American assemblers into long-term offtake contracts while compressing margin tiers across premium engineering and volume production segments.
Pricing Analysis
Long-term heat purchase agreements dominate utility-scale procurement, while residential retrofits run through project-based installer quotes. Three-tier pricing structure across premium, standard, and economy levels separates sputtered titanium-nitride-oxide absorber specifications from basic selective coatings. Cost compression in the standard tier is intensifying because copper and aluminum price volatility on the London Metal Exchange directly impacts absorber plate materials constituting 35-40% of bill-of-materials costs. Residential retrofit buyers in US sun-belt states show highest price sensitivity due to IRA tax credit dependency, while district heating utilities in Copenhagen and Stockholm demonstrate lowest sensitivity given 20-year contract horizons.
Supply Chain Analysis
Contract manufacturing capacity for tempered glass and selective coating concentrates in Shandong and Jiangsu provinces of China, with Himin Solar anchoring captive supply integration. Absorber plate production draws from copper and aluminum feedstocks, while extruded aluminum micro-channel configurations source from European specialty mills. Single-source vulnerability in glazing supply creates geographic chokepoints for European and North American assemblers. Distribution runs through HVAC channel networks in North America, direct utility procurement in Northern Europe, and energy service company financing in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flat plate solar collector market is entering a cyclical recovery phase driven by synchronized suburban housing replacement cycles across Germany and Austria, where building-integrated solar mandates compress installation timelines and force collector redesigns for architectural compatibility.
For Market Incumbents: Build switching-cost moats through backward integration into selective coating and tempered glass supply chains. Rheem's HVAC channel integration exemplifies capturing recurring service revenue that independent installers previously controlled. Greenonetec's district heating utility relationships in Copenhagen and Stockholm demonstrate how 20-year heat purchase agreements lock out competitors. Capacity addition in Shandong province for captive glass supply hedges against single-source chokepoint exposure from the three dominant Chinese glazing manufacturers. For New Entrants and Emerging Players: Pursue industrial process heat applications in Portugal and Spain, where food pasteurization and textile dyeing facilities seek 80-120°C thermal inputs that flat plate arrays now deliver cost-effectively. The CIP sterilization loop segment in dairy processing shows lowest incumbent saturation and highest thermal decarbonization urgency. Energy service company financing models in Lisbon and Porto districts offer established go-to-market infrastructure without requiring direct utility relationships. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-outs reshape the acquisition landscape by eliminating synthetic heat transfer fluid incumbents and creating openings for propylene glycol and ionic liquid alternative specialists. Long-term viability centers on coating chemistry capabilities and certification laboratory access across the 5-10 year technology transition window. Acquisition targets should demonstrate sputtering line investments meeting EU Ecodesign optical efficiency thresholds. Watch German certification body rejection rates for absorber submissions as an inflection indicator for coating technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Selective Coating Supply | Himin Solar's captive titanium-nitride-oxide production secures 95% emissivity absorber specifications against supply chokepoints. |
| Long-term Heat Purchase Agreements | Copenhagen's district heating network tenders create 20-year revenue visibility that locks out competing thermal technologies. |
| Perforated Micro-channel Absorber Adoption | Denmark's district heating utilities specify extruded aluminum configurations for freeze resistance and reduced fluid volume. |
| EU Ecodesign Certification Investment | Spanish and Italian manufacturers accelerate sputtering lines to meet optical efficiency thresholds filtering non-compliant imports. |
| Service Bundling into Equipment Contracts | Rheem's North American HVAC channel integration captures recurring revenue streams from factory-trained installer networks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC filings from listed HVAC conglomerates, EIA renewable energy deployment statistics, and FERC net metering rulemakings. Primary interviews engaged solar thermal system engineers, district heating utility procurement officers, building code officials in Bavaria, and absorber coating R&D directors. Bottom-up triangulation across installation volume data and top-down validation through equipment manufacturer revenue disclosures ensure cross-verified market sizing.
Forecast inputs incorporate active versus passive collector segmentation, operating temperature tier differentiation, and installation type architectural constraints across the projection horizon. CAGRs derive from regression analysis of historical deployment patterns against regulatory milestone timing and housing stock replacement cycle synchronization. Industry-specific inputs include IRA tax credit phase-out schedules and EU Green Deal Ecodesign revision timelines.
Macroeconomic conditions sit as an overlay; deviation in copper and aluminum London Metal Exchange pricing, mortgage rate sensitivity in suburban housing markets, or heat pump technology cost curves would shift the trajectory. Forecasts reflect documented assumptions about certification timeline compression and selective coating chemistry advancement. Quarterly review of German certification body rejection rates, Chinese GB standards revision announcements, and district heating utility tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Skin Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Saudi Arabia Solar Energy Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market