
 Global Solar PV Balance of System Market | 2026-2036
Global Solar PV Balance of System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solar PV Balance of System Market Outlook
Utility-scale buyer pools is consolidating across major independent power producers and energy majors seeking multi-gigawatt project pipelines. Sungrow Power Supply anchors Chinese supply chains through integrated inverter and energy storage manufacturing. SMA Solar Technology differentiates through European-engineered string and central inverter platforms with extended service networks. Huawei Technologies competes aggressively on digital power electronics and smart PV management systems for utility-scale deployments.
Solar PV Balance of System encompasses all non-module components required to convert, transmit, and mount photovoltaic generation into operational power plants, including inverters with maximum power point tracking algorithms, aluminum or steel mounting structures engineered for specific load ratings, DC and AC cabling sized to current carrying capacity, and protection switchgear rated for outdoor electrical environments. Mounting systems and inverters capture the dominant share of component value, with floating and carport installation types representing the fastest-expanding structural categories as land constraints intensify. Cables and switchgear constitute mature, cost-optimized segments where margin pools concentrate in fire-resistant and high-voltage-rated product grades.
IEC 61215 and IEC 61630 standards govern module and system qualification testing that directly shapes BoS component specifications and warranty terms across export markets. IEEE 1547 interconnection requirements in the United States and CE marking under EU directives enforce grid-support functionality that elevates inverter technical thresholds. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content rules that threaten to fragment procurement strategies across major installation markets.
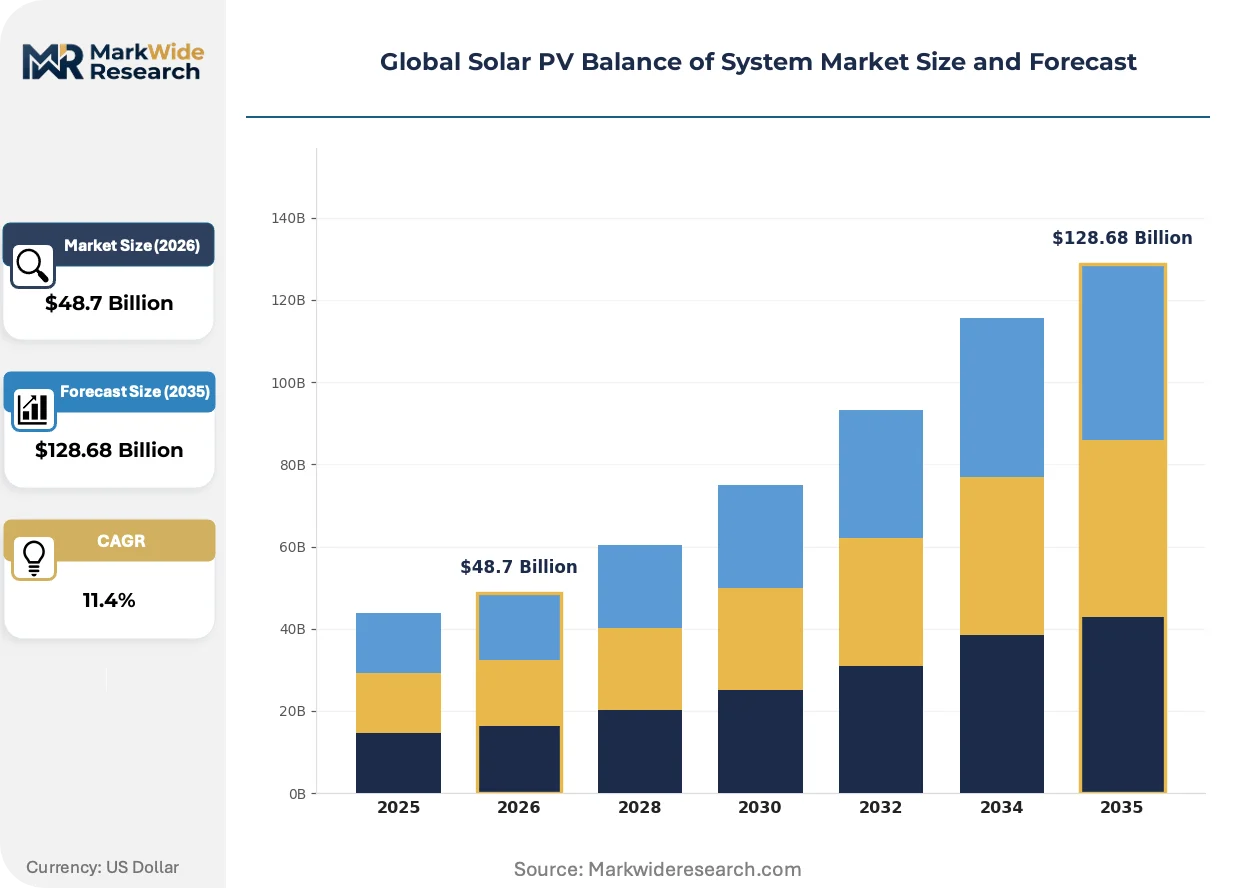
Market Dynamics
Utility-scale procurement consolidation across China, India, and the United States is compressing supplier margins while elevating technical qualification barriers for inverter and mounting system vendors.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic content mandates for government-backed projects are redirecting procurement toward local inverter and cabling producers.
- IEC 61630 system qualification testing:Harmonized international standards reduce certification duplication and accelerate cross-border equipment deployment.
- Floating PV installations:Land scarcity in Japan, South Korea, and the Netherlands is driving specialized corrosion-resistant mounting structures and marine-grade cabling demand.
Market Restraints
- Aluminum price volatility:Mounting structure fabricators face margin compression when LME aluminum spikes, with limited pass-through to EPC contracts.
- Chinese inverter supply concentration:Over three-quarters of global string inverter capacity sits in Anhui and Guangdong provinces, creating geopolitical exposure.
- Grid code fragmentation:IEEE 1547-2018 in the United States, CE grid support requirements in Europe, and India's CEA technical standards force redundant product variants.
Strategic Opportunities
- Saudi Arabia's renewable energy procurement:The PIF-backed ACWA Power pipeline offers multi-gigawatt BoS contracts with limited incumbent supplier relationships.
- Agrivoltaics integration:Elevated tracking systems that preserve ground-level agricultural activity command premium pricing in France and Japan.
- EU Battery Regulation supply chain disclosure:Carbon footprint documentation requirements favor European-assembly inverter and storage system providers.
Industry Challenges
- Power electronics engineering talent scarcity:Grid-forming inverter firmware development requires specialized control systems expertise concentrated in Germany and China.
- Extended IEC 61215 certification timelines:Thermal cycling and humidity freeze testing for new module-integrated electronics stretches product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solar PV Balance of System Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Inverters, Mounting Systems, Cables, Switchgear Installation Type: Ground-Mounted, Roof-Mounted, Floating, Carport End User: Residential, Commercial, Utility, Industrial Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Fimer, Power Electronics, Sungrow Power Supply, Solaredge, GoodWe, Huawei Technologies, SolarEdge Technologies, ABB, SMA Solar Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solar PV Balance of System Market Strategic Shifts
Digitalization of plant-level power electronics is compressing O&M costs while grid codes are forcing intelligence into previously passive BoS components.
String inverter topology with integrated arc fault detection and module-level power electronics is automating string-level diagnostics and rapid shutdown compliance. Large EPCs in California and Texas are specifying these units for residential and commercial rooftops to reduce commissioning labor and liability exposure. The technology is automating manual troubleshooting workflows that previously required technician site visits.
The EU F-Gas Regulation phase-down of fluorinated greenhouse gases is pressuring central inverter cooling system designs toward dielectric fluid alternatives and dry air cooling architectures. Manufacturers serving European utility-scale projects must redesign thermal management subsystems or forfeit market access. German and Spanish project developers now specify cooling technology in RFPs as a scored evaluation criterion.
Aggregated portfolio procurement by independent power producers is displacing project-by-project EPC contracting for BoS packages. Developers in India and Brazil now issue multi-year master supply agreements covering inverters, mounting, and cabling across pipeline tranches. This concentration is most visible in Maharashtra and Gujarat, where Adani Green and Azure Power have consolidated supplier panels to three to four qualified vendors per component category.
Global Solar PV Balance of System Market Segmentation
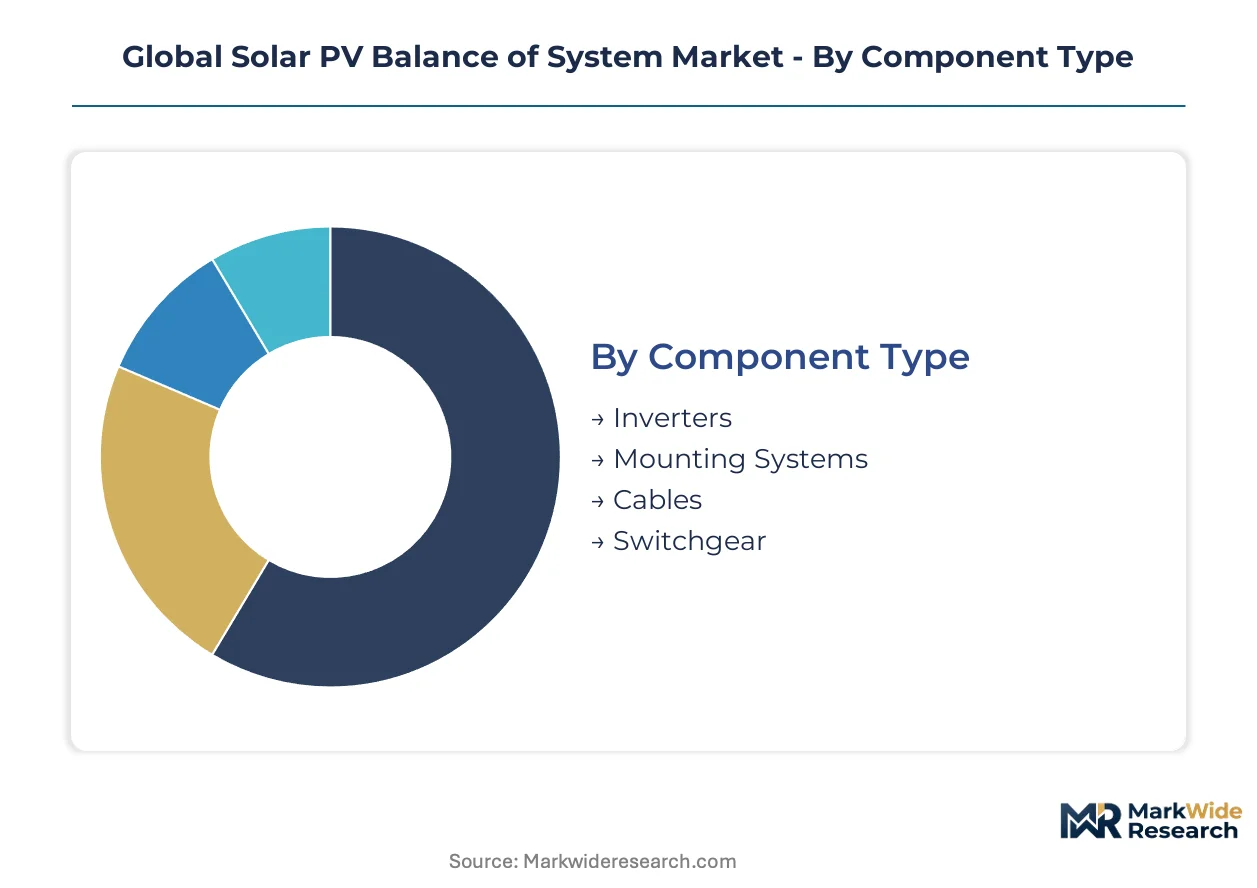
BoS component selection dictates project economics, installation timelines, and regulatory compliance across divergent site conditions and buyer sophistication levels. Segmentation reveals where capital deployment concentrates and which technology configurations command premium positioning.
Component Type:
Capital intensity varies sharply across BoS categories, with power electronics and structural systems absorbing the majority of upfront project expenditure.
- Inverters:Power conversion equipment with maximum power point tracking algorithms and grid-forming capabilities. Utility-scale procurement in India and the United States favors string and central topologies with extended warranty terms and local service networks.
- Mounting Systems:Aluminum or steel structural assemblies engineered for wind and snow load ratings. Floating and tracking configurations in Japan and the Netherlands command 15-40% cost premiums over fixed-tilt ground mounts due to specialized corrosion resistance and precision drive mechanisms.
- Cables:DC and AC conductors sized to current-carrying capacity with fire-resistant and UV-stabilized insulation grades. Procurement concentrates in cost-optimized copper and aluminum variants for utility-scale deployments.
- Switchgear:Protection and isolation equipment rated for outdoor electrical environments. Demand clusters in high-voltage AC and DC disconnects compliant with IEC 61439 and UL 1741 standards.
Inverters absorb the bulk of installed capacity value; floating mounting configurations are expanding most quickly as land constraints intensify.
Installation Type:
Site topology determines structural engineering requirements, labor intensity, and permitting complexity across deployment scenarios.
- Ground-Mounted:Fixed-tilt and tracking systems on graded or ungraded terrain. Utility-scale pipelines in Gujarat and Texas favor single-axis trackers for energy yield optimization.
- Roof-Mounted:Ballasted or penetrating attachments for commercial and residential buildings. California and Germany specify rapid shutdown compliance and fire setback requirements.
- Floating:Pontoon or tension-moored platforms for water bodies. South Korea and the Netherlands drive demand for marine-grade cabling and corrosion-resistant coatings.
- Carport:Elevated canopy structures combining generation with covered parking. Premium pricing persists in France and Japan where agrivoltaic integration commands dual-use land premiums.
Ground-mounted systems dominate megawatt-scale deployment; floating installations are gaining share fastest in markets with severe land scarcity.
End User:
Buyer sophistication and procurement scale create distinct margin pools and technical qualification barriers.
- Residential:Single-family and multi-family rooftop installations. California and Texas specify module-level power electronics for arc fault protection and rapid shutdown compliance.
- Commercial:C&I rooftops, parking canopies, and onsite generation. India and Brazil favor string inverters with monitoring platforms for portfolio aggregation.
- Utility:Independent power producers and energy majors with multi-gigawatt pipelines. Central inverters and single-axis trackers dominate procurement in China and the United States.
- Industrial:Manufacturing facilities and data centers with high load factors. Germany and Japan specify grid-forming inverters for resilience and peak shaving.
Utility buyers concentrate procurement volume; commercial segment adoption is climbing fastest as PPA structures mature.
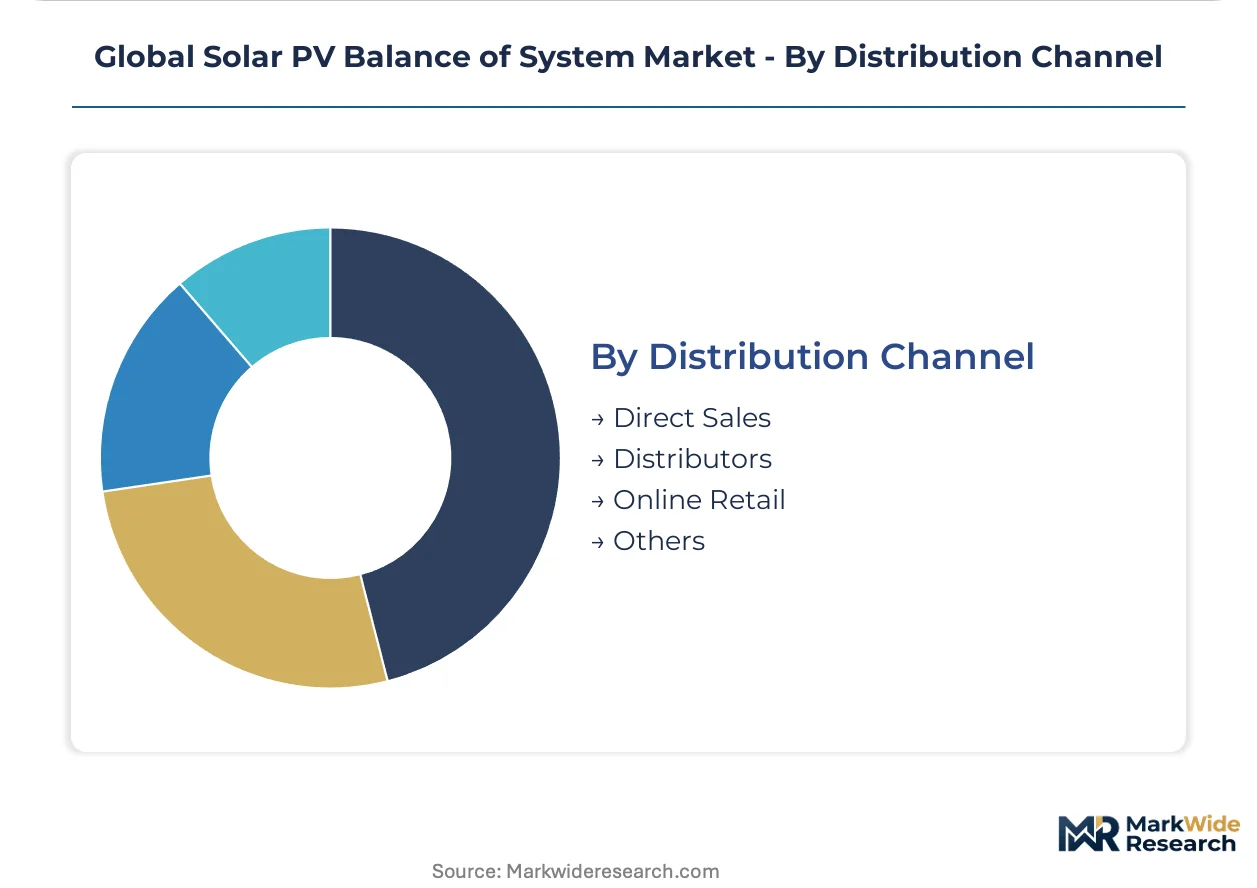
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and geographic proximity to supplier manufacturing.
- Direct Sales:Manufacturer-to-EPC or manufacturer-to-IPP relationships. Large Indian and Brazilian developers negotiate multi-year master supply agreements for inverter and mounting packages.
- Distributors:Regional stocking and logistics intermediaries. Residential and commercial contractors in Germany and the United States rely on distributor inventory for project scheduling flexibility.
- Online Retail:E-commerce platforms for standardized small-scale components. Limited to residential cabling and mounting hardware in markets with mature digital procurement infrastructure.
- Others:Engineering-procure-construct integrators and project developers with captive procurement functions. Saudi Arabia's ACWA Power pipeline exemplifies direct tendering for multi-gigawatt BoS packages.
Direct sales capture utility-scale volume; distributor channels are expanding most quickly in fragmented commercial and residential markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anhui and Guangdong provinces concentrate string inverter manufacturing capacity, anchoring Chinese supply chains that feed utility-scale procurement pipelines across three continents.
China
Massive domestic installation targets and integrated manufacturing ecosystems drive concentrated demand for central inverters and single-axis trackers. MIIT dual carbon goals accelerate grid-forming inverter firmware requirements. Hefei and Shenzhen industrial clusters house vertically integrated power electronics assembly operations serving both domestic and export markets.
United States
Independent power producers in Texas and California consolidate multi-gigawatt procurement through master supply agreements for string and central inverter platforms. IEEE 1547-2018 interconnection standards enforce grid-support functionality that elevates technical qualification barriers. Houston and Los Angeles metropolitan areas host EPC consolidation and developer headquarters coordinating nationwide BoS logistics.
India
Gujarat and Maharashtra states anchor utility-scale deployment with aggressive renewable purchase obligations and land availability for ground-mounted installations. CEA technical standards and PLI scheme domestic content mandates redirect procurement toward local inverter and cabling producers. Mundra and Pune industrial corridors concentrate mounting structure fabrication and regional distribution hubs.
Germany
EU F-Gas Regulation phase-down pressures central inverter cooling system redesigns toward dielectric fluid alternatives and dry air cooling architectures. CE marking and grid support requirements under EU directives enforce intelligence integration into previously passive BoS components. Bavaria and North Rhine-Westphalia host engineering talent pools for power electronics control systems development.
Saudi Arabia
PIF-backed ACWA Power pipeline offers multi-gigawatt BoS contracts with limited incumbent supplier relationships, creating entry opportunities for new equipment vendors. SFDA and national procurement frameworks emphasize local content and supply chain disclosure requirements. NEOM and Eastern Province developments concentrate floating PV and agrivoltaic pilot installations requiring specialized corrosion-resistant mounting structures.
Global Solar PV Balance of System Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital power electronics and smart PV management systems. The vendor base stratifies across integrated Chinese manufacturers, European-engineered specialists, and technology-focused challengers. Three archetypes dominate: scale-driven fabricators with captive component supply, premium-tier engineering houses with extended service networks, and digital-native power electronics firms. Competitive moves center on multi-year master supply agreement negotiations and geographic expansion into underpenetrated procurement markets.
Among the named participants, Sungrow Power Supply and Huawei Technologies represent scale-driven integrated manufacturing archetypes, while SMA Solar Technology exemplifies European-engineered premium positioning. These three anchors demonstrate how geographic origin and corporate structure correlate with strategic emphasis—Anhui-based Sungrow and Shenzhen-based Huawei leverage proximity to component ecosystems, while German GmbH-structured SMA maintains engineering differentiation through regional talent concentration.
| Leading Market Players |
|---|
| Fimer |
| Power Electronics |
| Sungrow Power Supply |
| Solaredge |
| GoodWe |
| Huawei Technologies |
| SolarEdge Technologies |
| ABB |
| SMA Solar Technology |
| Others |
Value Chain & Pricing Dynamics
Multi-gigawatt independent power producers in India, China, and the United States negotiate project-based long-term offtake contracts that compress supplier margins while elevating technical qualification barriers. This buyer concentration shifts pricing power toward procurement teams capable of consolidating inverter, mounting, and cabling packages across pipeline tranches.
Pricing Analysis
Volume-scale utility procurement captures thin margins while specialized floating and agrivoltaic configurations sustain premium positioning. Pricing stratifies across IEC 61630-certified premium tiers, domestic-content-compliant standard tiers, and import-dependent economy tiers. Cost compression in string inverter segments is intensifying because Chinese manufacturing overcapacity feeds aggressive export pricing. Residential contractors in Germany and California exhibit highest price sensitivity due to fragmented project scales, while Saudi Arabian IPPs demonstrate lowest sensitivity given limited incumbent relationships and technology-agnostic procurement scoring.
Supply Chain Analysis
Aluminum supply rests on Chinese smelting capacity, German engineered steel fabrication, and Southeast Asian cable jacketing compounds. Power electronics draw from Anhui and Guangdong inverter assembly clusters, while marine-grade mounting structures source from South Korean and Dutch corrosion-coating specialists. Single-source vulnerability concentrates in IGBT semiconductor modules where German and Japanese fabricators dominate. Distribution runs through direct manufacturer-to-EPC relationships for utility-scale volume, with regional distributors capturing residential and commercial fragmentation in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
String inverter topology with integrated arc fault detection and module-level power electronics is displacing legacy central inverter architectures across residential and commercial segments. This technology transition rewards vendors with firmware development capabilities and penalizes pure hardware fabricators.
For Market Incumbents: To counter margin compression from Chinese scale-driven competitors, SMA Solar Technology and European-engineered specialists should deepen captive supply of IGBT power modules through German semiconductor partnerships. Grid-forming inverter firmware development represents a defensible capability concentration given engineering talent scarcity in Germany and China. For New Entrants and Emerging Players: E-commerce platforms for standardized residential cabling and mounting hardware offer lowest barrier-to-entry routes into fragmented German and United States contractor markets. Saudi Arabia's ACWA Power pipeline presents the most penetrable utility-scale geography given limited incumbent supplier relationships and PIF-backed procurement neutrality. Digital PV management systems bundled with string inverter sales provide differentiated go-to-market positioning against hardware-commoditized competitors. For Investors and Strategic Acquirers: Distressed-cycle entries favor European-assembly inverter providers with carbon footprint documentation capabilities aligned to EU Battery Regulation supply chain disclosure requirements. Long-term viability hinges on grid-forming firmware intellectual property and multi-year master supply agreement visibility with Indian and Brazilian IPPs. Watch IEEE 1547-2018 interconnection standard adoption velocity across United States independent power producers as inflection indicator for premium inverter demand.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Inverter Firmware Development | German engineering talent pools anchor control systems expertise for IEEE 1547-2018 compliance. |
| Multi-Year Master Supply Agreement Negotiation | Adani Green and Azure Power in Maharashtra consolidate supplier panels to three qualified vendors per category. |
| Marine-Grade Corrosion-Resistant Coating Investment | South Korean and Dutch floating PV demand requires specialized structural fabrication capabilities. |
| Carbon Footprint Documentation Program | EU Battery Regulation favors European-assembly providers over Chinese import-dependent competitors. |
| Dielectric Fluid Cooling System Redesign | EU F-Gas Regulation phase-down forces thermal management architecture changes for market access. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with IPP project developers, EPC contractors, inverter procurement officers, and grid interconnection engineers combined with FERC filings, EIA generation databases, IEA renewable energy reports, and IEC standards documentation. Bottom-up project pipeline aggregation and top-down manufacturing capacity assessment provided cross-validation across the analysis window.
Data-stream reconciliation integrated component-level bill-of-materials costing with end-user procurement survey responses. Segmentation dimensions modeled include inverter topology, mounting system configuration, installation type, end-user scale tier, and regional regulatory framework. CAGRs were derived from installed capacity forecasts cross-referenced with component pricing trajectories. Grid code evolution velocity and aluminum LME price volatility bands served as key sensitivity inputs.
Inputs from customs records and trade association membership directories were available through the study window; gaps in proprietary IPP procurement contract terms introduce uncertainty bands around pricing trajectory assumptions. Forecasts reflect documented assumptions regarding PLI scheme continuity in India and IEEE 1547-2018 enforcement consistency across United States interconnection queues. Regulatory standard revision timelines, carbon border adjustment mechanism implementation scope, and Chinese manufacturing capacity expansion decisions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
Solar Skin Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Solar Power Bank Market