
 Europe Solar Concentrator Market | 2026-2036
Europe Solar Concentrator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Concentrator Market Analytics
Industrial heat buyers is collapsing toward utility-scale electricity generators as the dominant procurement archetype in the Europe Solar Concentrator Market. Abengoa Solar leverages its tower system expertise to anchor Spanish project pipelines. Aalborg CSP competes through specialized thermal energy storage integration for district heating networks. Siemens Energy sustains technology leadership in heat transfer fluid systems across Mediterranean installations.
A solar concentrator harnesses mirrors or lenses to focus sunlight onto a receiver, achieving temperatures exceeding 400°C for thermal-to-electric conversion or direct process heat. Parabolic trough systems dominate installed capacity due to proven bankability and operational track records across decades of Spanish and Italian plants. Tower systems represent the fastest-expanding category as molten-salt storage configurations extend dispatchable generation hours. Hybrid systems combining photovoltaic-thermal capture are gaining traction where land constraints and grid stability requirements coincide.
The EU Green Deal and F-Gas Regulation shape equipment standards and refrigerant choices across concentrator supply chains. ECHA chemical compliance protocols and CE marking requirements govern receiver coatings and heat transfer fluid formulations entering European markets. Stakeholders must monitor evolving national renewable auction designs and cross-border grid capacity allocations to time capital deployment effectively.
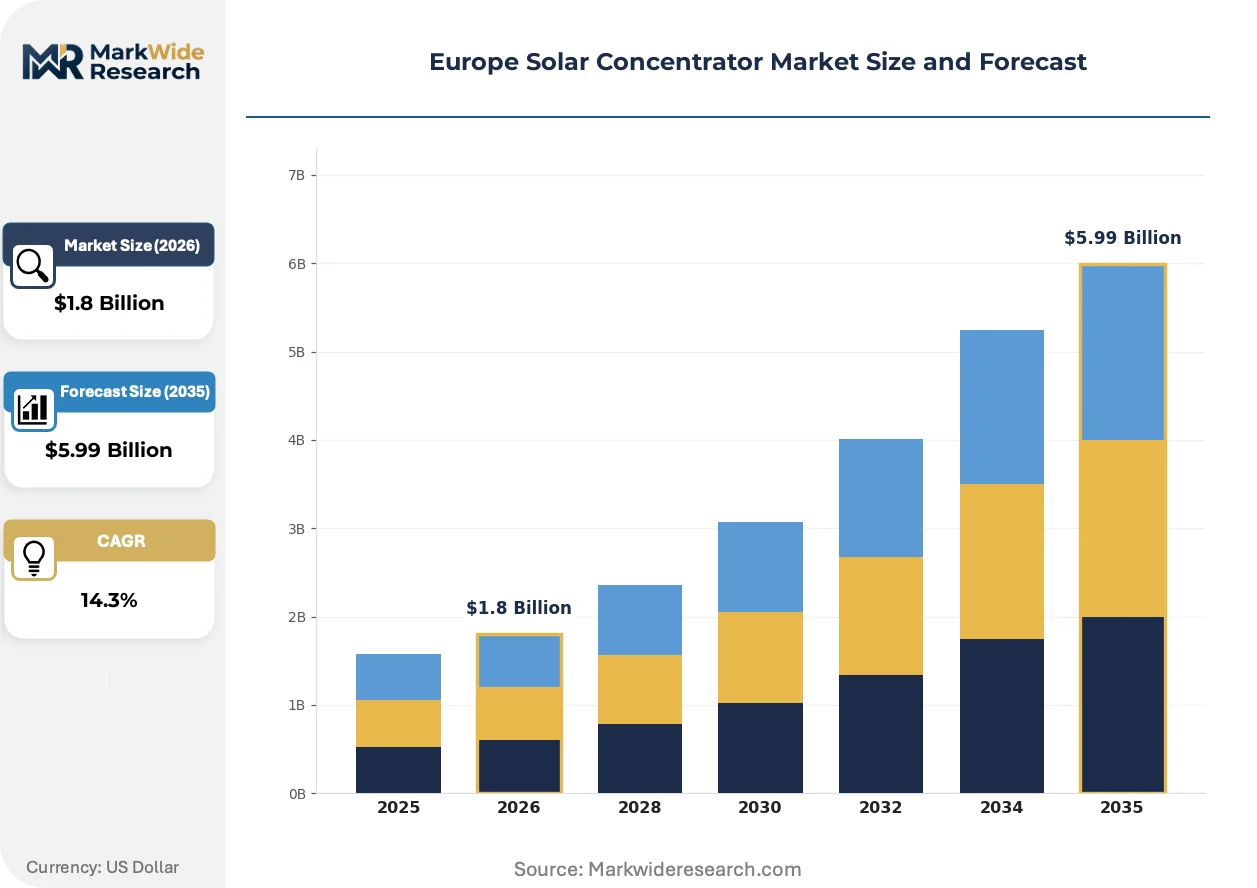
Market Dynamics
Utility-scale electricity generators are consolidating procurement power across Southern Europe while molten-salt thermal storage configurations extend dispatchable generation hours, compressing project development timelines and reshaping competitive positioning among technology providers.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Cement and steel producers in Spain's Extremadura corridor are procuring concentrated solar thermal for process heat, displacing natural gas combustion.
- Spain's renewable energy auction mechanism:Updated price floors and grid access guarantees are accelerating concentrated solar power project approvals in Andalusia.
- Molten-salt thermal storage integration:Tower system configurations now achieve 15-hour dispatch capability, enabling evening peak electricity sales to Iberian grid operators.
Market Restraints
- Heat transfer fluid supply concentration:Synthetic oil formulations for parabolic trough receivers depend on German and Belgian specialty chemical producers, creating input cost volatility.
- F-Gas Regulation refrigerant restrictions:ECHA compliance protocols are limiting receiver coating chemistries and extending equipment qualification timelines.
- Photovoltaic cost compression:Utility-scale PV without storage now undercuts concentrated solar thermal on levelized cost in high-irradiance zones.
Strategic Opportunities
- District heating network integration:Danish and Swedish municipal utilities are piloting concentrated solar thermal for seasonal heat storage, opening Nordic demand outside traditional Southern European markets.
- CE marking fast-track pathways:Simplified conformity assessment procedures for renewable heat equipment are reducing time-to-market for tower system receivers.
- Hybrid PV-thermal configurations:Land-constrained installations in Italy's Sicily region are combining photovoltaic capture with thermal concentration to maximize output per hectare.
Industry Challenges
- High-temperature receiver fabrication skill gaps:Specialized welding and coating technicians for molten-salt-compatible receivers remain scarce across Spanish project sites.
- Cross-border grid capacity allocation delays:Iberian interconnection bottlenecks are forcing project developers to queue for transmission access in Portugal's Alentejo region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Concentrator Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabolic Trough, Fresnel Lens, Dish/Engine System, Tower System Technology: Thermal Energy Storage, Heat Transfer Fluid, Photovoltaic-thermal, Hybrid Systems Application: Industrial Heating, Electricity Generation, Desalination, Agriculture End User: Utility Companies, Commercial Enterprises, Government Projects, Residential Users |
| Companies Covered | BrightSource Energy, Aalborg CSP, Abengoa Solar, Torresol Energy, Sener, Acciona, SolarReserve, Abors Green GmbH, Siemens Energy, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Concentrator Market Evolving Landscape
Molten-salt storage configurations and hybrid thermal-electric designs are actively reshaping how concentrated solar systems compete against battery-stored photovoltaic alternatives across European renewable auctions.
Tower systems with direct molten-salt receivers are bifurcating the installed base between legacy parabolic trough plants and next-generation configurations. Spanish utility-scale developers are prioritizing tower bids in renewable auctions due to extended storage duration. This technology is compressing the addressable market for trough-only suppliers while expanding total addressable market for integrated storage providers.
The EU F-Gas Regulation is restricting heat transfer fluid formulations with high global warming potential. ECHA is accelerating phase-out timelines for perfluorinated compounds used in some receiver cooling loops. Spanish and Italian project developers are reformulating fluid specifications to maintain CE marking compliance and avoid procurement disqualification.
Industrial offtake agreements are displacing pure merchant power sales as the dominant revenue model. Cement producers in Greece and chemical manufacturers in Portugal are signing 15-20 year heat purchase contracts directly with concentrated solar developers. This shift is most visible in Spain's Extremadura region where industrial clusters co-locate with high solar irradiance zones.
Europe Solar Concentrator Market Segmentation
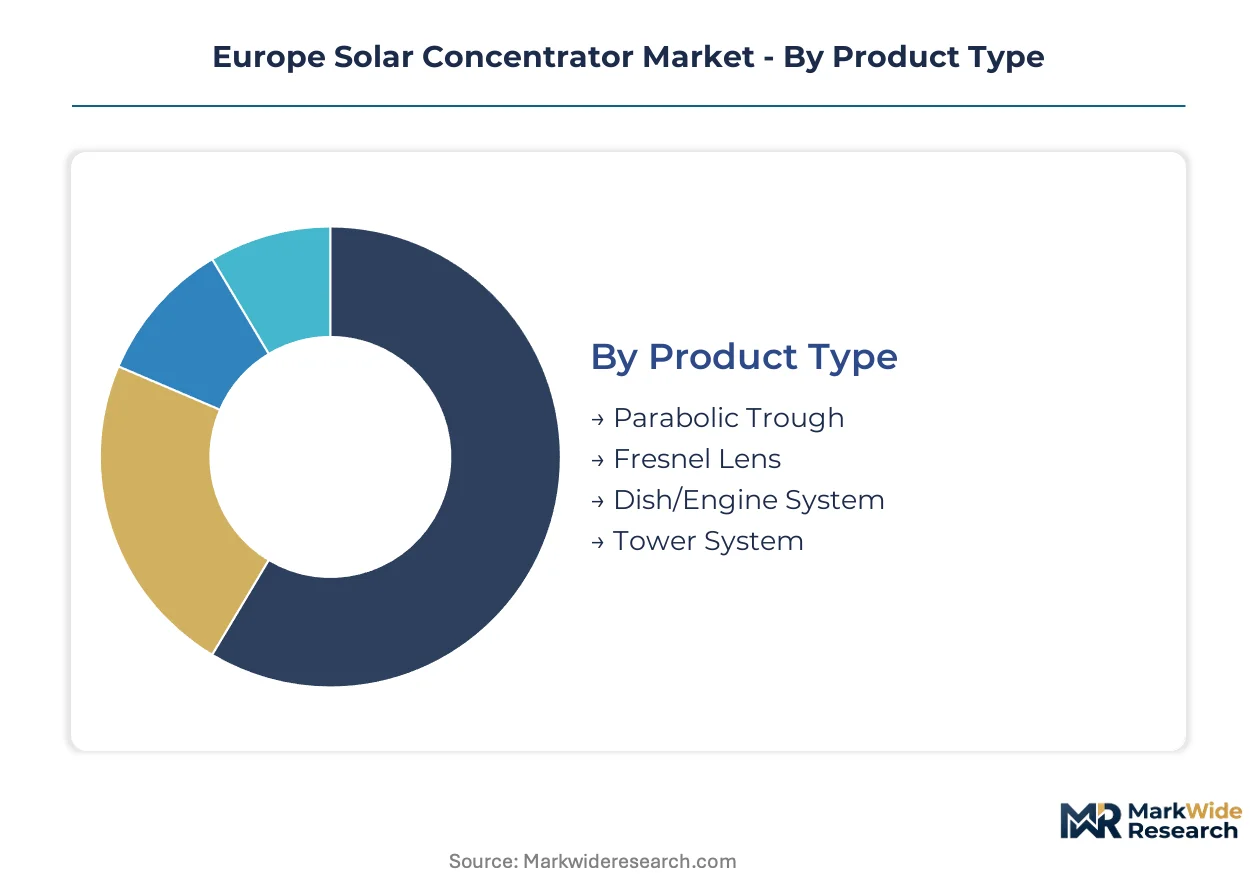
Technology choices in the Europe Solar Concentrator Market determine project bankability, storage duration, and regulatory compliance pathways. Procurement patterns diver sharply between legacy parabolic trough installations and emerging tower configurations with molten-salt integration.
Product Type:
Parabolic trough systems face intensifying substitution pressure from photovoltaic-battery hybrids in high-irradiance zones, while tower systems with thermal storage defend dispatchable generation premiums in Iberian renewable auctions.
- Parabolic Trough:Linear curved mirrors focus sunlight onto receiver tubes containing synthetic oil heat transfer fluid. Spanish plants in Andalusia and Extremadura anchor operational capacity, though ECHA fluid compliance costs and PV cost compression constrain new build economics.
- Tower System:Heliostat fields direct radiation to central molten-salt receivers achieving temperatures above 565°C. Developers in Spain's renewable auctions prioritize tower bids for 15-hour storage duration, displacing trough-only proposals in evening peak revenue slots.
- Fresnel Lens:Flat mirror strips with reduced wind loads and lower steel intensity suit land-constrained industrial sites in Italy's Sicily region.
- Dish/Engine System:Stirling engine receivers at focal points serve remote agricultural pumping in Portugal's Alentejo corridor where grid access remains limited.
Parabolic trough anchors the volume base while tower systems gain share at the steepest rate.
Technology:
Cost tier differentiation separates premium molten-salt storage configurations from standard heat transfer fluid systems, with hybrid designs commanding intermediate pricing in constrained land markets.
- Thermal Energy Storage:Molten-salt tanks enable dispatchable generation across evening peak demand windows. Spanish utility-scale developers integrate two-tank indirect systems to maximize renewable auction competitiveness against battery-stored PV.
- Heat Transfer Fluid:Synthetic aromatic formulations circulate through parabolic trough receivers. German and Belgian specialty chemical producers concentrate supply, creating input cost volatility under F-Gas Regulation phase-out timelines.
- Photovoltaic-thermal:Combined electricity and heat capture maximizes land productivity in Italy's densely populated southern regions.
- Hybrid Systems:Concentrating solar thermal paired with PV generation balances baseload continuity with midday output peaks in Greek industrial zones.
Thermal energy storage commands the steepest expansion trajectory among technology categories, while heat transfer fluid systems defend the largest installed base.
Application:
Customer type concentration varies sharply across end-uses, with industrial heating procurement consolidating around cement and steel clusters while electricity generation fragments across utility and merchant developers.
- Industrial Heating:Process heat above 400°C displaces natural gas combustion in Spain's Extremadura cement corridor. EU Green Deal industrial decarbonization mandates accelerate offtake contracting with 15-20 year heat purchase agreements.
- Electricity Generation:Dispatchable power sales to Iberian grid operators dominate revenue models. Tower system configurations with extended storage duration capture evening peak pricing premiums in Spanish auction mechanisms.
- Desalination:Multi-effect distillation plants in Mediterranean coastal zones utilize waste heat from concentrating solar facilities.
- Agriculture:Greenhouse heating and crop drying applications concentrate in Portugal's Alentejo region where solar irradiance co-locates with intensive horticulture.
Industrial heating applications are climbing the fastest as decarbonization mandates displace fossil combustion, while electricity generation retains the largest addressable market.
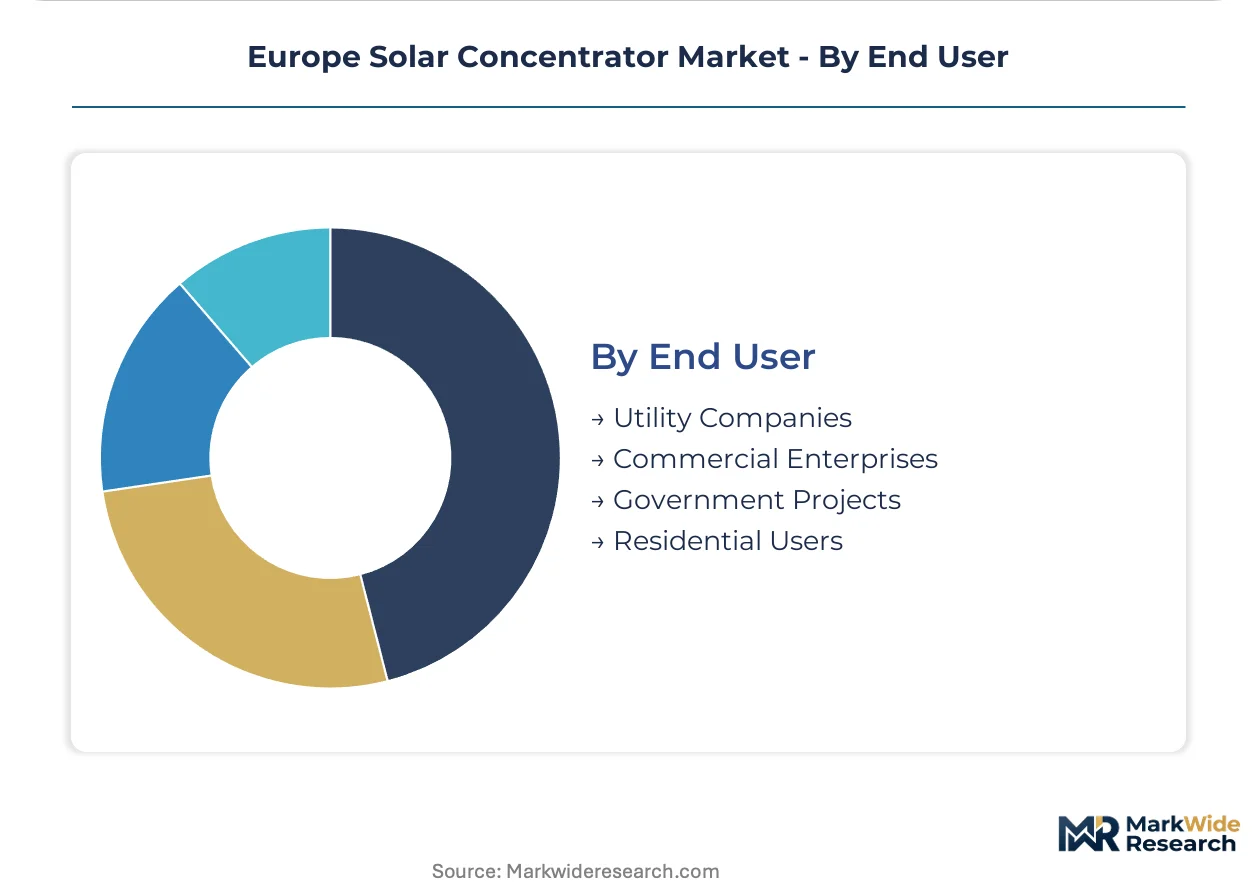
End User:
Geography drives procurement concentration, with Spanish utility companies dominating auction participation while commercial enterprises in industrial clusters pioneer direct heat offtake models.
- Utility Companies:Iberian grid operators and renewable developers bid tower systems into Spanish capacity auctions. Grid access guarantees and price floor mechanisms determine project viability timelines in Andalusia and Extremadura.
- Commercial Enterprises:Cement producers and chemical manufacturers sign direct heat purchase contracts bypassing electricity intermediation. Greek and Portuguese industrial clusters lead long-term offtake innovation.
- Government Projects:Municipal district heating pilots in Denmark and Sweden test seasonal thermal storage outside traditional Southern European markets.
- Residential Users:Distributed solar thermal for domestic hot water concentrates in Mediterranean coastal housing developments with high cooling loads.
Utility companies anchor current procurement volumes while commercial enterprises are expanding most quickly through direct industrial heat contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bay of Biscay electrical interconnector and Iberian grid infrastructure underwrite Southern Europe's concentrator deployment capacity, while Nordic district heating pilots test seasonal thermal storage beyond traditional irradiance zones.
Spain
Extremadura cement clusters and Andalusian utility-scale developers drive procurement concentration. Spain's updated renewable energy auction mechanism with price floors and grid access guarantees accelerates tower system approvals. Developers in Extremadura sign 15-20 year industrial heat purchase agreements with cement producers under EU Green Deal mandates.
Italy
Sicily's land-constrained industrial zones favor Fresnel lens installations and hybrid PV-thermal configurations. CE marking requirements under EU machinery directives govern receiver equipment qualification timelines. Agrigento and Catania provinces host pilot installations combining photovoltaic capture with thermal concentration for process heat.
Portugal
Alentejo agricultural pumping and horticulture applications sustain dish-engine system demand where grid access remains limited. Cross-border grid capacity allocation delays with Spain force transmission access queuing. Évora and Beja districts concentrate solar irradiance co-located with intensive greenhouse operations.
Denmark
Municipal district heating utilities pilot concentrated solar thermal for seasonal heat storage outside traditional Southern European markets. Simplified CE marking fast-track pathways for renewable heat equipment reduce receiver time-to-market. Aarhus and Copenhagen metropolitan utilities test molten-salt storage integration with existing district networks.
Greece
Cement producers in the Peloponnese and chemical manufacturers sign direct long-term heat purchase contracts bypassing electricity intermediation. ECHA chemical compliance protocols govern heat transfer fluid formulations entering Hellenic markets. Corinth and Patras industrial clusters pioneer offtake innovation under industrial decarbonization pressure.
Europe Solar Concentrator Market Competitive Landscape
Concentration sits with integrated tower system developers and specialized thermal storage fabricators across the Iberian project pipeline. Spanish and Danish developers maintain technology leadership through molten-salt receiver expertise and district heating integration capabilities respectively. Two strategic archetypes dominate: utility-scale auction bidders optimizing dispatch duration, and industrial heat specialists securing long-term offtake contracts. Competitive moves center on securing grid interconnection capacity allocations and qualifying receiver coatings under tightening F-Gas Regulation timelines.
Among Spanish-origin developers, Abengoa Solar and Torresol Energy exemplify the integrated tower system archetype with established project execution track records. Aalborg CSP occupies a position representing the specialized thermal storage tier, anchoring Nordic district heating applications through molten-salt integration expertise. Siemens Energy sits within the heat transfer fluid systems segment, sustaining equipment supply relationships across Mediterranean installations. These three company profiles illustrate how technology specialization and geographic focus stratify competitive positioning without requiring scale-driven consolidation.
| Leading Market Players |
|---|
| BrightSource Energy |
| Aalborg CSP |
| Abengoa Solar |
| Torresol Energy |
| Sener |
| Acciona |
| SolarReserve |
| Abors Green GmbH |
| Siemens Energy |
| Others |
Value Network & Pricing Analysis
Synthetic oil replacement by molten-salt heat transfer media is redrawing procurement geography toward Spanish tower system fabricators while compressing margins for legacy parabolic trough suppliers dependent on German and Belgian chemical feedstocks.
Pricing Analysis
Volume-discount tiering structures separate utility-scale auction bidders securing multi-hundred-megawatt commitments from industrial heat offtakers negotiating smaller-scale site-specific installations. Price differentiation hinges on storage duration guarantees and CE marking certification grade, with 15-hour dispatch configurations commanding premiums over standard heat transfer fluid systems. Cost compression in parabolic trough segments is intensifying because photovoltaic-battery hybrids undercut levelized economics in high-irradiance zones. Merchant power developers exhibit highest price sensitivity, while cement producers under EU Green Deal mandates demonstrate lower elasticity due to carbon compliance deadlines.
Supply Chain Analysis
Extended lead times for molten-salt-compatible receiver coatings are forcing Spanish project developers to pre-position inventory 18-24 months ahead of construction windows. Supply concentrates in Germany, Belgium, and Spain for synthetic oil formulations, heliostat drive mechanisms, and molten-salt tank fabrication respectively. Raw material dependencies span nickel-chromium alloys for high-temperature receivers, borosilicate glass for mirror substrates, and nitrate salt blends for thermal storage media. Single-source vulnerability sits with German specialty chemical producers dominating aromatic heat transfer fluid formulations. Distribution runs through EPC contractors integrating tower system packages for Iberian utility developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
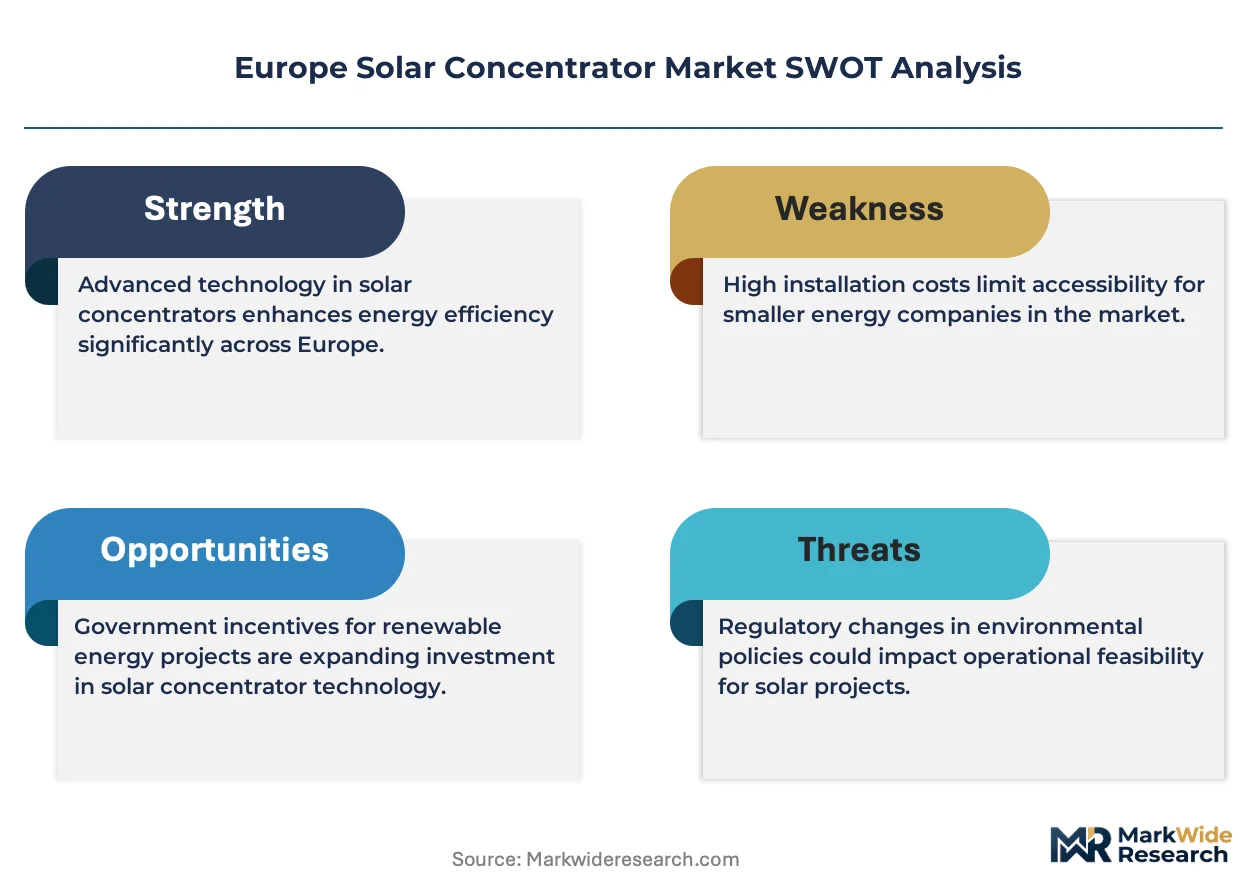
The Europe Solar Concentrator Market functions as a service-attach opportunity where thermal storage operation contracts and receiver recoating services expand faster than hardware sales, embedding recurring revenue into project finance structures.
For Market Incumbents: Secure molten-salt receiver fabrication capacity in Extremadura and Andalusia before grid interconnection queues lengthen. Lock in 10-15 year service agreements with industrial heat offtakers to defend against photovoltaic-battery substitution in process heat segments. Backward integration into nitrate salt supply insulates margin pressure from commodity chemical volatility. For New Entrants and Emerging Players: Post-installation thermal storage optimization services represent a service-layer gap where incumbents under-serve district heating utilities unfamiliar with molten-salt seasonal cycling. Target Danish and Swedish municipal pilots seeking operational support outside traditional Southern European irradiance zones. Pursue equipment-leasing models with performance guarantees to bypass capital-intensive balance sheet requirements. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated tower system developers with proven molten-salt execution track records over pure-component suppliers. Long-term viability hinges on industrial decarbonization mandate durability across the next decade. Monitor Iberian renewable auction price floor adjustments as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Molten-Salt Storage Integration | 15-hour dispatch capability captures evening peak pricing in Spanish auction mechanisms. |
| Industrial Heat Offtake Contracting | Direct cement and steel producer agreements bypass merchant power price volatility. |
| CE Marking Fast-Track Qualification | Reduced receiver certification timelines accelerate time-to-market for tower systems. |
| Backward Integration into Salt Supply | Captive nitrate sourcing insulates project margins from chemical commodity swings. |
| District Heating Network Partnership | Nordic municipal utilities open demand outside traditional Southern European markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and industrial heat procurement managers; and secondary validation against EIA project databases, IEA renewable technology reports, FERC interconnection filings, and Spanish renewable auction documentation. Bottom-up installation capacity tallies triangulated against top-down addressable market sizing by technology segment and application.
Across the projection horizon, the analytical framework modeled technology type, storage configuration tier, end-use application, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with macro renewable deployment trajectories. Forecast inputs incorporated Iberian grid interconnection queue data and EU Green Deal industrial decarbonization compliance timelines.
Material uncertainties — auction mechanism redesign, F-Gas Regulation phase-out acceleration, photovoltaic cost compression trajectories — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these structural variables. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Solar Software Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Italy Distributed Solar Power Generation Market