
 Solar Tracker Market | 2026-2036
Solar Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Tracker Market Intelligence
India is reconfiguring its solar manufacturing base through production-linked incentive schemes that attract tracker component suppliers. Nextpower leverages vertical integration across steel fabrication and control systems to protect margin pools. Array Technologies anchors its competitive position through domestic US manufacturing capacity that qualifies for IRA tax credits. Trina Solar's tracker division competes aggressively on module-plus-tracker bundled pricing in emerging markets.
A solar tracker is a mechanical system that orients photovoltaic modules toward the sun throughout the day, typically achieving a 20-35% energy yield improvement over fixed-tilt installations through single or dual-axis rotation. These systems incorporate torque tubes, drive motors, controllers, and foundation structures engineered to withstand wind loads across decades of operation. Single-axis trackers dominate utility-scale deployments due to their favorable levelized cost of energy, while dual-axis systems occupy niche commercial and industrial segments where land constraints justify higher capital intensity. Smart tracking technology incorporating predictive algorithms and sensor feedback is displacing conventional passive designs in premium installations.
The US Inflation Reduction Act and Federal Energy Regulatory Commission interconnection rules are accelerating domestic tracker demand by improving project financeability and grid access timelines. India's Bureau of Indian Standards and Central Electricity Authority mandate specific wind load and corrosion standards that filter out non-compliant imports. China's Ministry of Ecology and Environment enforces dual carbon goals that tighten steel and aluminum sourcing requirements for tracker manufacturers. Stakeholders must monitor evolving domestic content thresholds across multiple jurisdictions to preserve qualification for production tax credits and avoid supply chain disqualification.
Market Dynamics
The solar tracker industry is pivoting toward domestic manufacturing qualification as the primary competitive filter, with the US Inflation Reduction Act's content bonuses and India's PLI schemes rewriting procurement rules for steel fabrication and control systems.
Growth Catalysts
- IRA Domestic Content Bonuses:The US Inflation Reduction Act awards additional production tax credits to projects sourcing tracker steel and electronics from American facilities, redirecting capital toward domestic torque tube and drive motor production.
- Single-Axis Efficiency Gains:Module manufacturers are shipping higher-wattage bifacial panels that extract greater value from tracking architectures, amplifying the yield advantage over fixed-tilt systems in high-irradiance zones.
- India PLI Manufacturing Incentives:Production-linked incentive schemes for solar components are attracting tracker control system suppliers to establish local assembly operations serving South Asian utility-scale developers.
Market Restraints
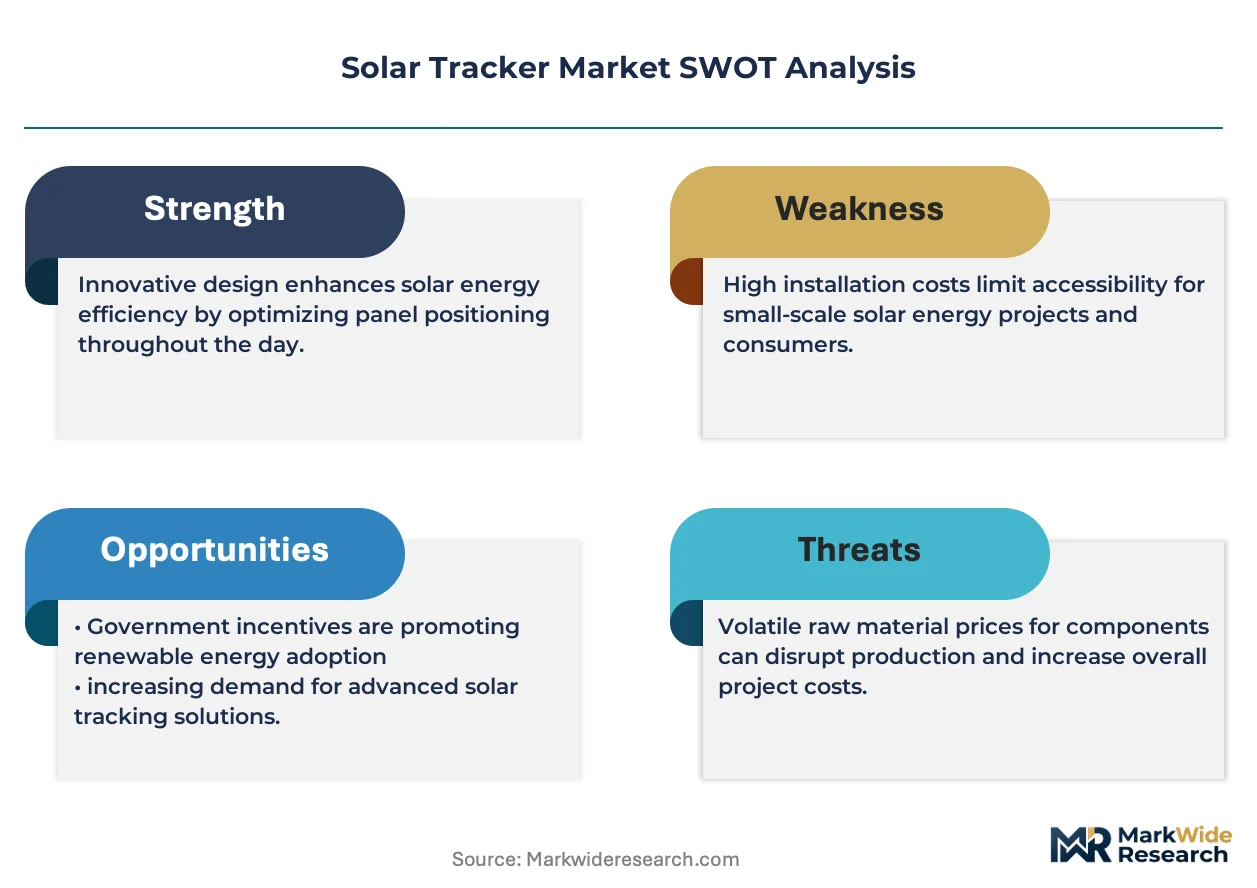
- Steel Input Volatility:Galvanized steel torque tubes constitute the largest material cost block, and price swings in hot-rolled coil directly compress tracker margin pools during procurement cycles.
- Foundation Labor Intensity:Geotechnical variability across southwestern US desert sites drives unpredictable pile-driving costs and schedule overruns that erode project returns.
- Wind Load Certification Barriers:India's Bureau of Indian Standards mandates site-specific structural validation that disqualifies imported tracker designs lacking indigenous wind tunnel testing.
Strategic Opportunities
- Bifacial-Plus-Tracker Bundling:Module suppliers are integrating tracking hardware into turnkey power plant offerings, capturing margin from balance-of-system procurement that previously flowed to independent tracker vendors.
- Predictive Control Algorithms:Machine learning-based sun-position forecasting is virtualizing sensor hardware, reducing field component counts while improving tracking accuracy during variable cloud cover.
- Middle East Desert Deployment:Saudi Arabia and UAE utility-scale tenders specify tracker compatibility for gigawatt-scale projects where sand abrasion resistance and high-temperature electronics performance create premium specification tiers.
Industry Challenges
- Control Systems Talent Scarcity:Embedded firmware engineers with photovoltaic power plant experience command premium compensation, constraining tracker OEM capacity to scale software development teams.
- Interconnection Queue Delays:Federal Energy Regulatory Commission reforms have shortened study timelines but transmission upgrade backlogs still strand completed tracker installations awaiting grid energization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Tracker Market |
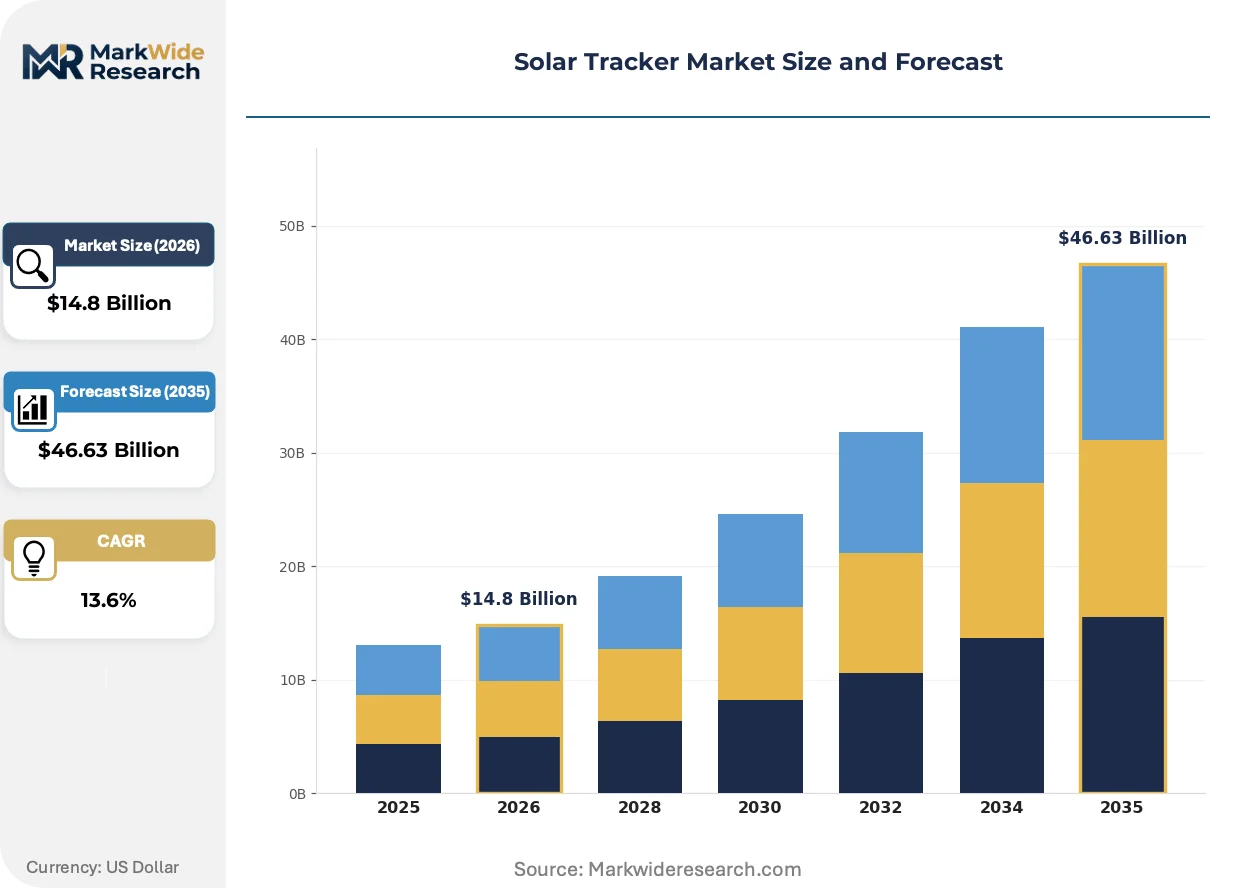
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $46.63 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axis, Dual Axis, Hybrid, Fixed Tilt End User: Utility Scale, Commercial, Residential, Industrial Technology: Active, Passive, Smart, Conventional Installation: Ground Mounted, Roof Mounted, Integrated, Portable |
| Companies Covered | Nextpower (formerly Nextracker), Array Technologies, Trina Tracker, Arctech Solar, Soltec, GameChange Solar, PV Hardware, Versolsolar, SunPower Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Tracker Market Strategic Shifts & Innovations
Tracker technology is converging with predictive analytics and module-level power electronics, compressing the traditional separation between mechanical tracking hardware and plant-level optimization software.
Machine learning-driven sun-position forecasting is virtualizing physical sensor networks across premium tracker installations. Array Technologies and Nextracker are deploying cloud-trained algorithms that replace distributed pyranometers and inclinometers with modeled irradiance predictions. This compression of field hardware reduces capital cost per megawatt while improving tracking precision during intermittent cloud conditions.
China's Ministry of Ecology and Environment is enforcing dual carbon goals that tighten embodied carbon disclosure requirements for steel and aluminum tracker components. Manufacturers must now document smelting energy sources and transportation emissions to qualify for state-backed project finance. European developers importing Chinese tracker hardware face mounting pressure to verify supply chain carbon intensity under the EU Green Deal's carbon border adjustment mechanism.
Utility-scale developers are consolidating procurement authority into fewer engineering-procurement-construction firms with tracker specification expertise. Bechtel, Fluor, and McCarthy are internalizing tracker vendor evaluation and commissioning protocols that previously resided with independent owner's engineers. This channel concentration in the southwestern United States is compressing the vendor shortlist for multi-gigawatt portfolios and favoring suppliers with proven EPC relationship management capabilities.
Solar Tracker Market Segmentation
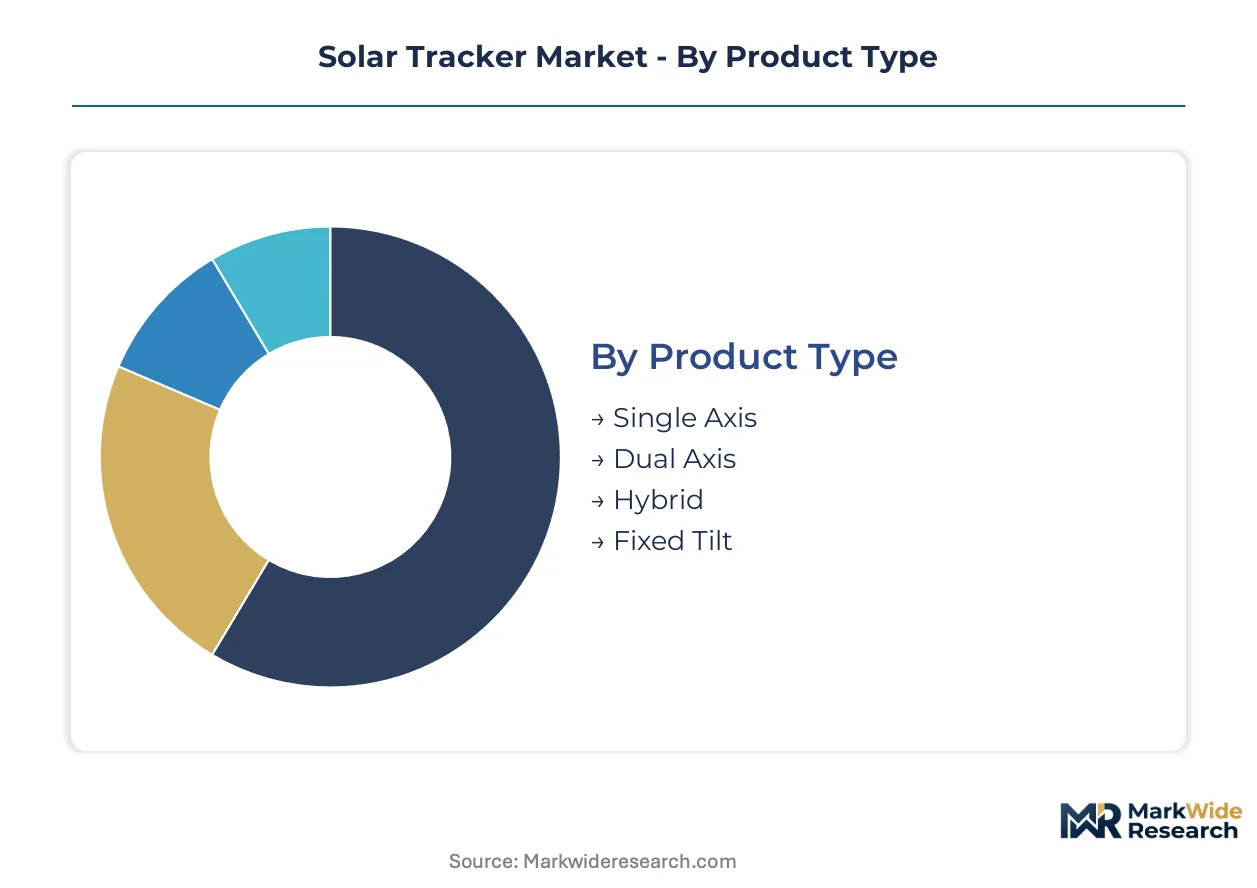
Solar tracker segmentation reveals how technology maturity, project scale, and mounting constraints reshape procurement patterns across utility and distributed generation. Product architecture and control system sophistication determine capital intensity and operational complexity for developers sizing installations against irradiance profiles and land availability.
Product Type:
Mature single-axis designs dominate utility procurement while emerging hybrid configurations capture niche applications demanding optimization flexibility.
- Single Axis:Torque tube assemblies rotate modules along one horizontal axis, tracking the sun's east-west path from dawn to dusk. Utility-scale developers in the southwestern United States specify these systems for gigawatt-scale desert installations where levelized cost of energy optimization outweighs dual-axis capital premiums. Bifacial module compatibility amplifies yield gains on high-albedo ground surfaces.
- Dual Axis:Azimuth and elevation drives enable precise sun following across both daily and seasonal arcs, extracting maximum irradiance capture per module area. Commercial and industrial rooftop installations in Japan and Germany justify the higher structural cost through land constraint premiums and feed-in tariff optimization where every square meter generates revenue.
- Hybrid:Combines passive thermal actuation with active motor correction for simplified control architectures in remote deployments.
- Fixed Tilt:Stationary racking without tracking capability occupies cost-sensitive residential markets and legacy retrofit projects.
Single Axis retains volume leadership; Hybrid holds the steepest expansion curve among emerging mechanical configurations.
End User:
Project finance scale tiers separate capital deployment strategies across customer categories from distributed kilowatt installations to multi-gigawatt portfolios.
- Utility Scale:Independent power producers and regulated utilities deploy trackers across hundreds of megawatts with standardized engineering-procurement-construction contracts. FERC interconnection queue reforms and IRA production tax credits accelerate procurement timelines for southwestern US project pipelines where single-axis compatibility is specified in tender documents.
- Commercial:On-site generation for retail, logistics, and corporate campuses balances rooftop constraints against power purchase agreement structuring.
- Residential:Distributed rooftop installations rarely justify tracker mechanical complexity given limited surface area and shading variability.
- Industrial:Manufacturing facilities with high baseload demand and available land pursue behind-the-meter tracking for peak shaving and renewable energy certificate generation.
Utility Scale commands procurement volume concentration; Commercial segments are expanding most quickly as corporate renewable targets harden.
Technology:
Control system sophistication stratifies across sensor density, computational intensity, and predictive capability.
- Active:Motor-driven positioning with real-time sensor feedback dominates utility-scale installations requiring precise angular adjustment under variable cloud conditions. Array Technologies and Nextracker deploy active architectures with distributed drive motors responding to centralized controller commands across kilometer-long tracker rows.
- Smart:Machine learning algorithms replace physical pyranometers with modeled irradiance predictions, compressing hardware counts while improving tracking precision during intermittent weather. Cloud-trained neural networks at premium installations reduce capital cost per megawatt and enable predictive maintenance scheduling.
- Passive:Thermal or hydraulic actuation without electrical control suits off-grid and low-maintenance deployments.
- Conventional:Timer-based or simple sensor feedback systems occupy cost-constrained emerging markets with lower performance requirements.
Active technology retains installed base dominance; Smart control architectures gain share fastest as software-defined optimization displaces field hardware.
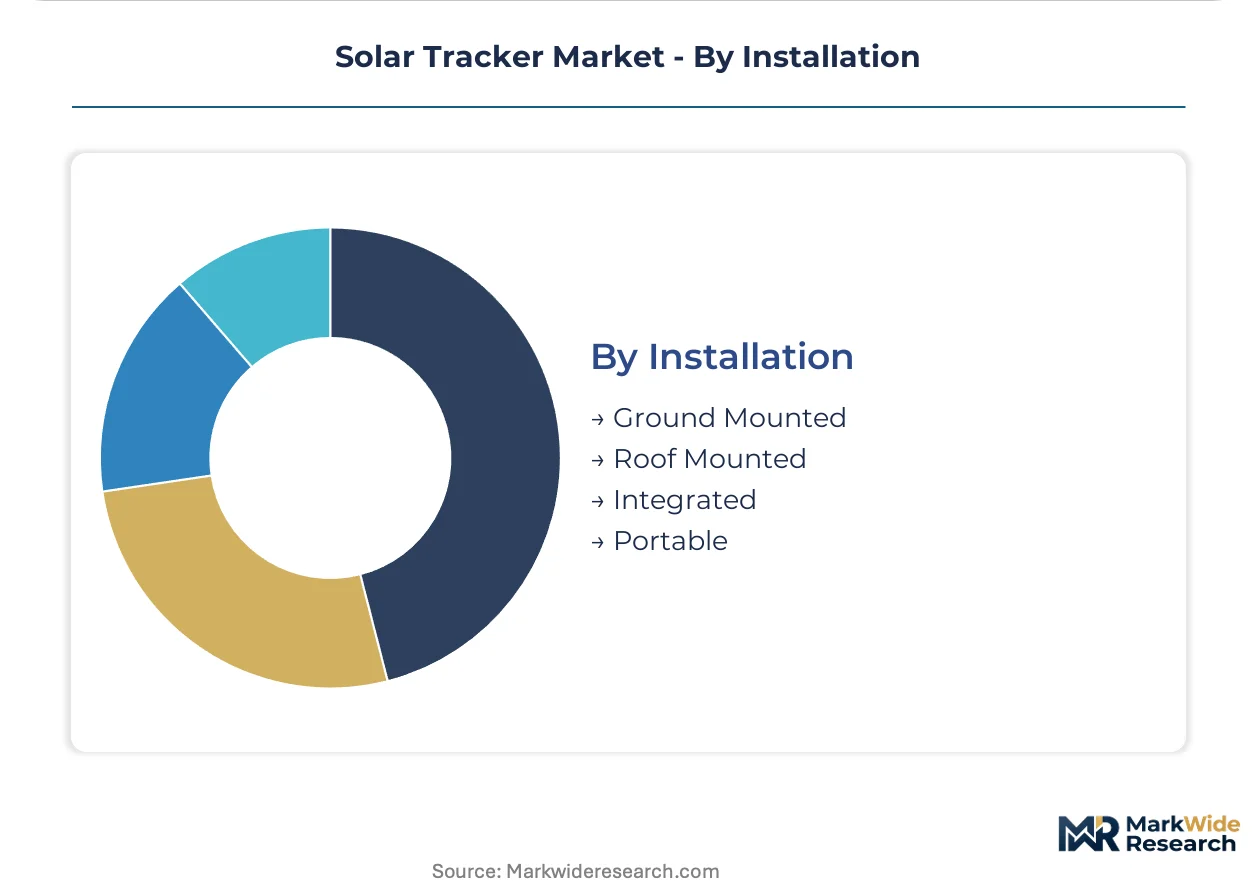
Installation:
Mounting topology constraints determine structural loading, foundation requirements, and tracker mechanical envelope.
- Ground Mounted:Pile-driven or ballasted foundations support utility-scale torque tube assemblies across graded or uneven terrain. Geotechnical variability in southwestern US desert sites drives unpredictable pile-driving costs that erode project returns when bedrock or caliche layers resist penetration.
- Roof Mounted:Structural integration with commercial and industrial building envelopes demands wind load certification and distributed weight management.
- Integrated:Tracker mechanics embedded within building-integrated photovoltaic systems occupy architectural facade and canopy applications.
- Portable:Rapidly deployable tracking units serve military, disaster relief, and temporary power applications requiring relocation capability.
Ground Mounted dominates capacity additions; Portable configurations are climbing the fastest as resilience and mobility requirements reshape emergency power procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interconnection reforms and IRA production tax credits anchor US tracker procurement velocity, while India's PLI schemes and China's dual carbon enforcement reshape manufacturing geography across three continents.
United States
Utility-scale developers in Arizona, Nevada, and Texas deploy single-axis systems across gigawatt-scale desert portfolios where high irradiance maximizes bifacial yield gains. The IRA's domestic content bonuses redirect supply chain investments toward American steel fabrication and control system assembly. Array Technologies manufactures torque tubes and drive motors at facilities in New Mexico and Arizona that qualify projects for additional tax credits.
India
Production-linked incentive schemes attract tracker component suppliers to establish local assembly serving South Asian utility-scale developers. The Bureau of Indian Standards mandates site-specific wind load certification that filters out non-compliant imports lacking indigenous wind tunnel validation. Gujarat and Rajasthan host concentrated manufacturing clusters where domestic fabricators qualify for PLI disbursements tied to local value addition.
China
The Ministry of Ecology and Environment enforces dual carbon goals that tighten embodied carbon disclosure for steel and aluminum tracker components. State-backed project finance now requires documentation of smelting energy sources and transportation emissions across the supply chain. Jiangsu and Zhejiang provinces concentrate control system manufacturing where vendors integrate carbon accounting into qualification protocols for state utility tenders.
Saudi Arabia
Gigawatt-scale renewable tenders specify tracker compatibility for desert installations where sand abrasion resistance and high-temperature electronics performance create premium specification tiers. The Saudi Electricity Company mandates IEC-certified structural validation for all tracking hardware deployed under long-term power purchase agreements. NEOM and the Eastern Province anchor deployment concentration where EPC contractors source specialized coating systems for extreme environment durability.
Germany
Commercial and industrial rooftop installations justify dual-axis tracking premiums through land constraint economics and feed-in tariff optimization. The EU Green Deal's carbon border adjustment mechanism pressures developers to verify supply chain carbon intensity for imported tracker hardware. Bavaria and Baden-Württemberg concentrate precision engineering clusters where control system specialists integrate machine learning algorithms into tracking firmware.
Solar Tracker Market Key Industry Players
Capability concentration sits with vertically integrated specialists; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three functional tiers: pure-play tracker OEMs with captive steel fabrication, diversified solar manufacturers bundling tracking hardware with module supply, and regional fabricators serving protected procurement markets. Consolidation pressure intensifies as domestic content rules favor manufacturers with localized torque tube production and in-house control system development. Strategic moves center on backward integration into steel supply and geographic expansion through EPC partnership networks.
Among US-based pure-play specialists, Nextpower and Array Technologies exemplify the integrated manufacturing archetype with domestic facilities qualifying for IRA tax credit bonuses. Trina Tracker represents the diversified solar conglomerate model, leveraging module manufacturing scale to bundle tracking hardware into turnkey power plant offerings. These three anchors illustrate how competitive positioning stratifies between domestic content qualification and global procurement efficiency.
| Leading Market Players |
|---|
| Nextpower (formerly Nextracker) |
| Array Technologies |
| Trina Tracker |
| Arctech Solar |
| Soltec |
| GameChange Solar |
| PV Hardware |
| Versolsolar |
| SunPower Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese steel galvanizing facilities is compressing torque tube pricing globally and forcing tracker OEMs to renegotiate annual supply contracts or absorb margin erosion. This utilization dynamic simultaneously rewards developers with procurement leverage while pressuring mid-tier fabricators without captive melt shop access.
Pricing Analysis
Geographic price spreads between US domestic and imported tracker systems have widened substantially since IRA content bonus qualification took effect. Three-tier pricing structure across premium smart-tracking, standard active-motor, and economy passive configurations now stratifies primarily by control system sophistication and wind-load certification tier. Pricing pressure stems from EPC consolidation in the southwestern United States, where volume purchasers extract bundled-module discounts that independent tracker vendors struggle to match. Utility-scale developers exhibit lowest price sensitivity given tax credit capture priorities, while commercial rooftop installers face acute capital constraint pressure.
Supply Chain Analysis
Hot-rolled steel coil from China, India, and Vietnam feeds the upstream torque tube fabrication tier that anchors tracker cost structures. Galvanized steel torque tubes, aluminum drive housings, and embedded controller electronics constitute the critical input trinity that manufacturing footprints rest on. Tariff exposure on Chinese steel inputs creates margin vulnerability for fabricators without alternative sourcing from Indian or Southeast Asian melt shops. Distribution runs through engineering-procurement-construction contractors with direct vendor qualification authority rather than traditional distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across domestic content qualification regimes is creating addressable niches for specialists who can navigate jurisdiction-specific certification requirements. The proliferation of PLI schemes, IRA bonuses, and carbon disclosure mandates is splintering what was once a globally fungible procurement landscape into regional competency zones.
For Market Incumbents: Harden domestic manufacturing footprints in the southwestern United States and Gujarat to preserve IRA and PLI qualification. Array Technologies and Nextracker must deepen captive steel fabrication capacity as tariff volatility threatens imported torque tube cost structures. Certification investment in Bureau of Indian Standards wind tunnel validation represents a critical defensive moat against low-cost Chinese entrants.
For New Entrants and Emerging Players: Mid-scale commercial and industrial installations in Germany and Japan represent the most penetrable entry point where dual-axis premiums justify specialized engineering capabilities. Portable tracker configurations for military and disaster relief applications offer faster qualification cycles than utility-scale desert deployments. A control-systems-first go-to-market angle leveraging predictive algorithm licensing bypasses capital-intensive mechanical fabrication barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-qualification play because domestic content rules are hardening faster than technology differentiation can compensate. Acquisition targets should display integrated torque tube production and established EPC contractor relationships rather than pure software capabilities. The signal to watch is FERC interconnection queue clearance velocity, which determines whether stranded tracker inventory or sustained procurement demand characterizes the mid-decade investment window.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Steel Fabrication Buildout | IRA tax credit qualification hinges on American-sourced torque tube production capacity. |
| Smart Control System Licensing | Predictive algorithm partnerships with Array Technologies reduce field hardware capital intensity. |
| India PLI Manufacturing Entry | Bureau of Indian Standards certification opens access to Rajasthan and Gujarat utility pipelines. |
| Bifacial Module Bundling | Trina Solar's integrated offerings capture balance-of-system margin from independent tracker vendors. |
| Desert Environment Specialization | Saudi Electricity Company tenders reward sand abrasion resistance and high-temperature electronics performance. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility-scale project developers, EPC procurement directors, tracker OEM engineering leads, and steel fabrication plant managers. Secondary validation drew from FERC interconnection filings, EIA generation capacity databases, Bureau of Indian Standards certification registries, and IRA domestic content guidance documents. Bottom-up project pipeline aggregation was cross-referenced against top-down steel consumption and control system shipment estimates to establish volume triangulation.
Calibration against historical capacity installation records and steel price elasticity patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, control system technology tier, end-use scale category, and regional regulatory cluster. CAGRs were derived from least-squares fitting of annual installation trajectories adjusted for interconnection queue clearance assumptions and module efficiency improvement curves. IRA bonus phase-out schedules and PLI disbursement timelines informed regional growth differential inputs.
Stress conditions across steel price volatility, FERC queue reform implementation delays, and bifacial module penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about domestic content threshold evolution and carbon disclosure enforcement intensity. Cross-checking against IEA renewable capacity deployment benchmarks and SEIA installation tracking data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
Europe IoT in Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Solar Farm Market
Renewable Energy
South Africa Rooftop Solar Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Malaysia Renewable Energy Market
Renewable Energy
China Wind Energy Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Philippines Wind Energy Market
Renewable Energy
Solar Drying System Market