
 Solar Power Manager Market | 2026-2036
Solar Power Manager Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Power Manager Market Insights
UL 1741 certification for grid-interactive inverters is collapsing the competitive field to engineering-intensive suppliers. Texas Instruments sustains broad analog and power management portfolios that span residential to utility scale. STMicroelectronics specializes in silicon carbide and gallium nitride power devices for next-generation solar converters. SolarEdge anchors string inverter architecture with module-level power electronics and storage integration.
A solar power manager is an electronic system that orchestrates energy harvesting, conversion, storage dispatch, and load balancing across photovoltaic arrays, typically managing voltage windows between 12V and 1500V DC depending on application scale. Its commercial purpose centers on maximizing energy yield, protecting battery health, and enabling grid code compliance. Home systems and utility scale deployments diverge sharply in margin structure, with residential controllers competing on software ecosystems while utility-grade hardware commands premium pricing through redundancy and remote management capabilities. Hybrid systems pairing photovoltaic generation with energy storage represent the fastest-expanding configuration as net metering erosion forces self-consumption optimization.
FERC Order 2222 in the United States enables distributed solar and storage aggregation into wholesale markets, directly expanding addressable revenue pools for power management platforms. The EU Green Deal and F-Gas Regulation together accelerate demand for refrigerant-free thermal management in solar electronics while tightening embodied carbon disclosure requirements. Stakeholders must track how interconnection queue reform and evolving IEEE 1547 standards reshape product qualification burdens and regional market access timelines.
Market Dynamics
Net metering erosion across major solar markets is forcing power manager architectures toward self-consumption optimization, collapsing the economic case for simple grid-tied inverters while elevating hybrid storage-integrated controllers.
Growth Catalysts
- FERC Order 2222:The US regulation enables distributed solar and storage aggregation into wholesale markets, expanding revenue streams for power management platforms that orchestrate bidirectional dispatch.
- Germany's residential microgrid momentum:Homeowners in Bavaria and Baden-Württemberg are deploying island-capable controllers to maximize self-consumption under revised EEG feed-in tariffs.
- Lithium-ion cost compression:Cell price declines are making hybrid photovoltaic-storage systems economically viable at residential scale, driving controller demand with integrated battery management.
Market Restraints
- Silicon carbide substrate shortage:Limited 6-inch SiC wafer capacity constrains gallium nitride device scaling for next-generation converters, creating 18-24 month lead times for automotive-qualified suppliers.
- UL 1741 certification bottleneck:The safety standard's grid-interactive inverter requirements are collapsing the competitive field to engineering-intensive suppliers with dedicated test facilities.
- Copper and rare earth magnet volatility:Input cost swings for inductors and magnetics compress margin predictability for power converter manufacturers serving price-sensitive residential segments.
Strategic Opportunities
- Australia's NEM 3.0 preparation:The country's pending net metering reforms are creating preemptive replacement demand for export-limited power managers with time-of-use optimization.
- EU F-Gas Regulation compliance:Refrigerant-free thermal management mandates are opening retrofit markets for liquid-cooled controller architectures in utility-scale installations.
- Vehicle-to-home convergence:Bidirectional EV charging integration with residential solar controllers represents unclaimed white space as automakers and inverter suppliers negotiate interoperability standards.
Industry Challenges
- IEEE 1547 revision compliance:Evolving grid-interconnection standards require firmware requalification cycles that strain smaller engineering teams and delay product launches.
- Embedded carbon disclosure:EU Green Deal supply-chain transparency mandates are forcing controller manufacturers to trace semiconductor provenance and document manufacturing emissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Power Manager Market |
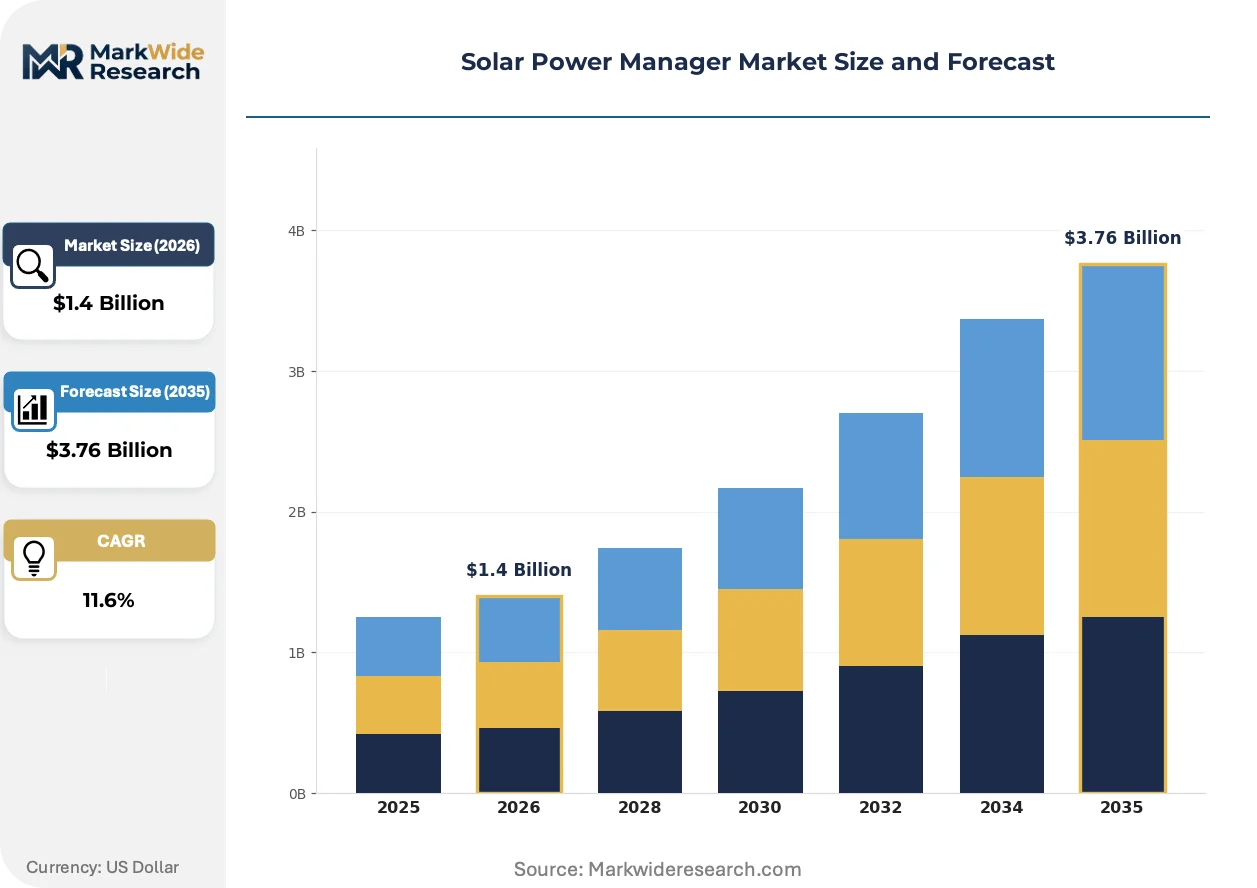
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.76 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Systems, Commercial Systems, Utility Scale, Hybrid Systems Deployment: On-Premise, Cloud-Based, Hybrid Deployment, Remote Management End User: Residential, Commercial Enterprises, Government Facilities, Industrial Users Technology: Photovoltaic, Concentrated Solar Power, Solar Thermal, Energy Storage |
| Companies Covered | Monolithic Power Systems (MPS), Analog Devices, DFROBOT, Maxim Integrated, STMicroelectronics, Texas Instruments, Silvertel, Waveshare, SolarEdge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Power Manager Market Trends and Innovations
Power electronics architecture is fragmenting as module-level electronics displace centralized string inverters, while software-defined energy management collapses hardware differentiation cycles.
Silicon carbide MOSFETs are replacing silicon IGBTs in DC-DC conversion stages for utility-scale solar plus storage plants. Developers in Texas and Arizona are specifying 1500V SiC-based power blocks for 2025 commissioning. This transition is decomposing the traditional inverter-battery boundary into distributed power conversion nodes with independent MPPT and dispatch control.
The EU Green Deal and F-Gas Regulation together mandate refrigerant-free thermal management in solar electronics while tightening embodied carbon disclosure. European utility-scale project developers now require liquid-cooled power conversion systems with documented supply-chain emissions. German EPCs are pre-qualifying controller suppliers based on carbon accounting transparency ahead of 2026 CSRD reporting deadlines.
Buyers in California's NEM 3.0 transition are prioritizing controllers with native time-of-use optimization and battery dispatch algorithms over hardware-centric specifications. Solar installers are unbundling equipment procurement from installation labor, creating direct-to-consumer controller sales channels. This pattern is most visible in the Los Angeles and San Diego metropolitan markets where installer consolidation has compressed equipment margins.
Solar Power Manager Market Segmentation
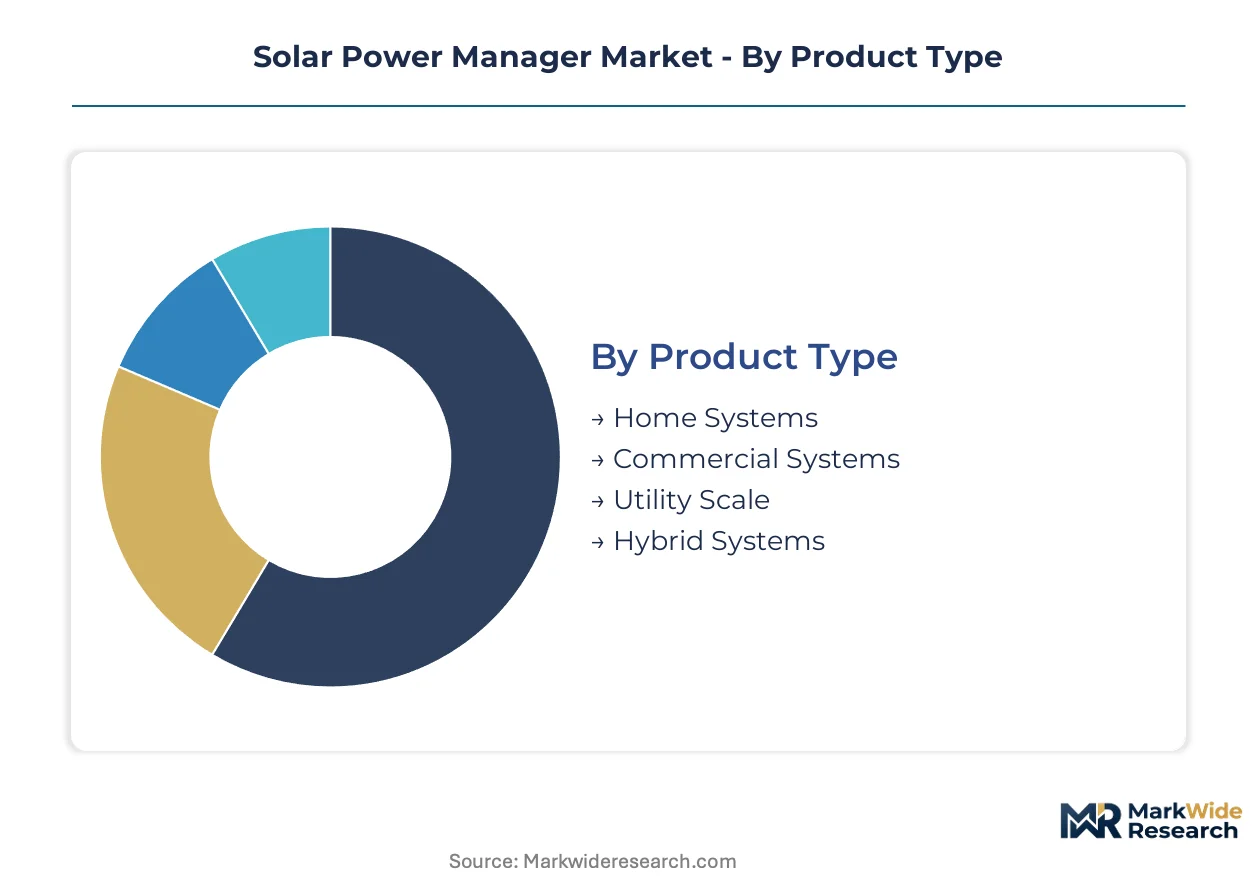
Power manager architectures fragment sharply by application scale, with voltage windows, thermal management requirements, and software complexity diverging across residential rooftops and utility substations. Segmentation reveals where premium pricing endures versus where commoditization pressures dominate procurement decisions.
Product Type:
Margin pools concentrate in hybrid systems where battery integration commands hardware-software bundled pricing, while utility scale competes on volume efficiency and residential segments face ecosystem lock-in battles.
- Hybrid Systems:Integrated photovoltaic-storage controllers orchestrate bidirectional DC-DC conversion with native battery management protocols. California NEM 3.0 adopters in Los Angeles and San Diego metropolitan markets prioritize these units for time-of-use arbitrage as export compensation collapses.
- Utility Scale:1500V DC central inverters and distributed power blocks manage multi-megawatt arrays with redundancy and remote SCADA integration. Developers in Texas and Arizona specify silicon carbide-based architectures for 2025 commissioning timelines where efficiency gains justify premium procurement.
- Home Systems:String inverters and module-level power electronics compete on software ecosystems and installer channel relationships.
- Commercial Systems:Mid-scale controllers bridge rooftop and ground-mount applications with flexible AC coupling options.
The dominant share belongs to Utility Scale, while Hybrid Systems is closing the gap fastest.
Deployment:
Cloud-based architectures are displacing traditional on-premise monitoring as fleet operators prioritize predictive analytics and over-the-air firmware updates.
- Cloud-Based:Centralized data aggregation platforms enable fleet-wide performance benchmarking and automated fault detection across distributed installations. German EPCs managing Bavarian residential microgrids leverage these systems for remote diagnostics under revised EEG tariff structures.
- Remote Management:Satellite and cellular-connected controllers serve off-grid and weak-grid installations with limited technician access. Australian installers preparing for NEM 3.0 export limits deploy these units for preemptive dispatch optimization in Queensland and New South Wales.
- On-Premise:Local SCADA systems persist in utility-scale installations requiring deterministic response times.
- Hybrid Deployment:Edge-cloud split architectures balance latency-sensitive protection functions with centralized analytics.
Cloud-Based deployments capture the largest installed base, though Remote Management is expanding most quickly in island-capable and weak-grid applications.
End User:
Procurement sophistication varies dramatically, with industrial buyers demanding documented supply-chain emissions and residential customers prioritizing installer recommendations over technical specifications.
- Industrial Users:Manufacturing facilities and data centers specify power managers with power quality compliance and islanding capability for critical load protection. EU Green Deal embodied carbon disclosure mandates force these buyers to pre-qualify suppliers based on semiconductor provenance documentation ahead of CSRD reporting deadlines.
- Government Facilities:Military bases and municipal buildings require cybersecurity-hardened controllers with NERC CIP compliance and domestic content preferences. FERC Order 2222 aggregation pilots in Texas and California are reshaping procurement specifications for these assets.
- Residential:Homeowners in Germany and Australia drive microgrid controller demand under evolving feed-in tariff regimes.
- Commercial Enterprises:Retail and office building operators focus on payback period and lease structure compatibility.
Industrial Users dominate absolute spending, while Government Facilities is gaining share fastest through resilience and cybersecurity mandates.
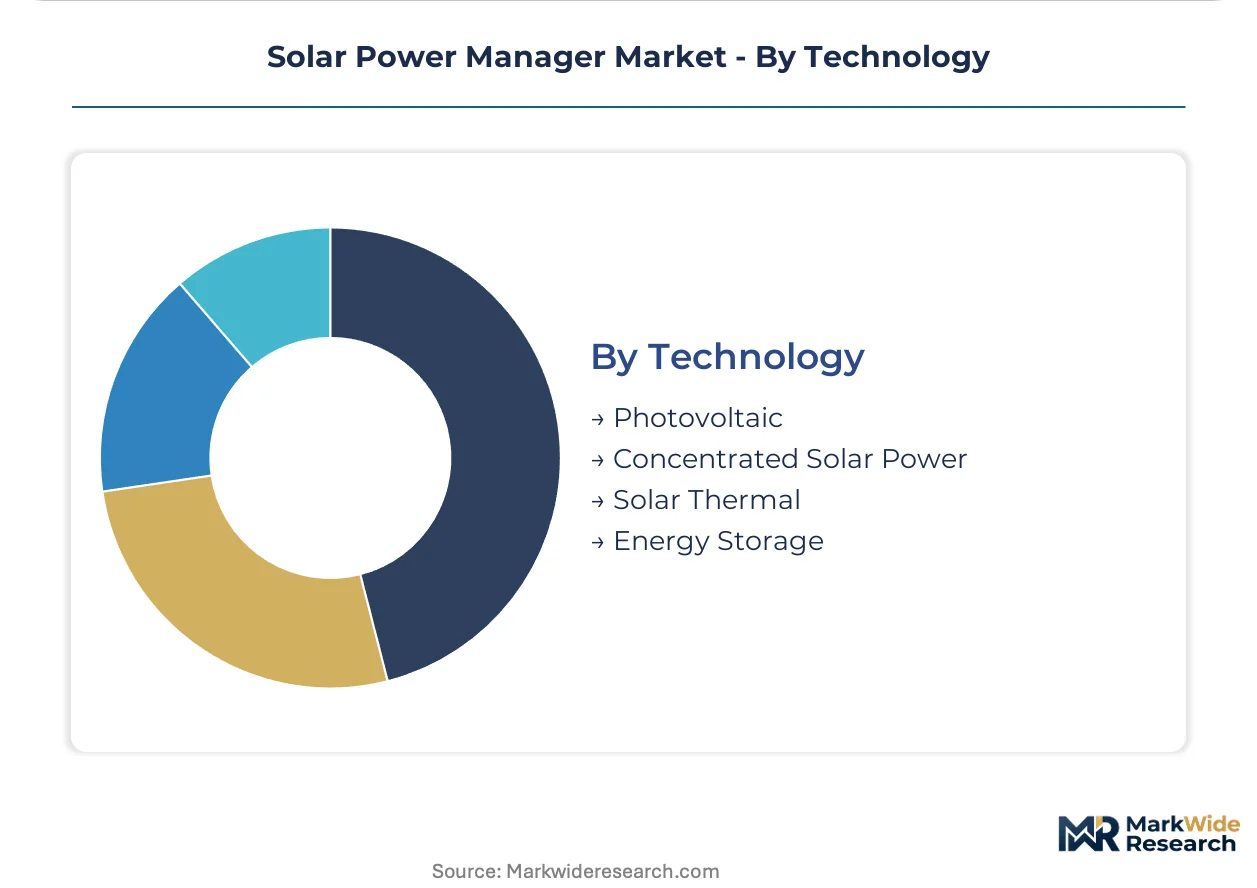
Technology:
Photovoltaic integration anchors the installed base, though energy storage coupling is redefining controller architecture requirements across all scales.
- Energy Storage:Battery-integrated power managers incorporate bidirectional inverters, thermal runaway protection, and dispatch optimization algorithms. Lithium-ion cost compression is making these systems viable at residential scale in Germany's Baden-Württemberg region.
- Photovoltaic:Silicon and thin-film array controllers remain the volume foundation, with module-level electronics displacing centralized string architectures in residential and commercial applications.
- Concentrated Solar Power:Thermal energy storage coupling requires specialized high-temperature power conversion and molten salt heat exchanger integration.
- Solar Thermal:Domestic hot water and industrial process heat systems use simpler DC controllers with limited grid-interactive functionality.
Photovoltaic maintains the dominant technology position, while Energy Storage integration is climbing the fastest as net metering erosion forces self-consumption optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers and residential microgrid adopters concentrate procurement decisions in jurisdictions with active net metering reform or feed-in tariff restructuring. Utility-scale developers prioritize markets with streamlined interconnection queues and established renewable portfolio standards.
United States
California's NEM 3.0 implementation is collapsing export compensation rates and forcing Los Angeles and San Diego installers toward storage-integrated controllers with native time-of-use optimization. FERC Order 2222 enables distributed solar aggregation into wholesale markets, expanding revenue streams for power management platforms. Texas developers specify silicon carbide-based 1500V architectures for 2025 commissioning timelines.
Germany
Homeowners in Bavaria and Baden-Württemberg deploy island-capable controllers to maximize self-consumption under revised EEG feed-in tariffs. The EU Green Deal and F-Gas Regulation mandate refrigerant-free thermal management and embodied carbon disclosure ahead of 2026 CSRD deadlines. German EPCs pre-qualify suppliers based on semiconductor provenance documentation.
Australia
Queensland and New South Wales installers prepare for pending NEM 3.0 export limits by deploying preemptive replacement demand for export-limited power managers with time-of-use optimization. Remote management capabilities serve weak-grid installations with limited technician access. The country's national energy regulator shapes dispatch optimization requirements for distributed assets.
China
Dual carbon goals accelerate utility-scale hybrid system deployment across western provinces with high solar irradiance. The national standardization administration tightens grid-interconnection technical requirements for distributed photovoltaic systems. Yangtze River Delta manufacturing clusters supply silicon carbide substrates and gallium nitride devices for converter scaling.
India
PLI scheme incentives for solar module manufacturing extend to power electronics localization requirements. State-level renewable purchase obligations in Gujarat and Rajasthan drive utility-scale controller demand. The Central Electricity Authority mandates technical standards for grid-connected distributed generation systems.
Solar Power Manager Market Competitive Landscape
Player mix skews toward diversified analog semiconductor suppliers and specialized power electronics fabricators. Engineering-intensive suppliers with dedicated UL 1741 test facilities command premium positioning as certification requirements collapse the competitive field. Strategic archetypes include silicon carbide device specialists, string inverter architects with module-level integration, and broad portfolio analog suppliers spanning residential to utility scale. Dominant competitive moves center on backward integration into substrate supply and strategic partnerships for battery management protocol licensing.
Within the diversified semiconductor tier, Texas Instruments and Analog Devices occupy positions spanning voltage regulation to gate driver portfolios. STMicroelectronics exemplifies the silicon carbide and gallium nitride specialization archetype for next-generation converter applications. SolarEdge anchors the string inverter architecture segment with module-level power electronics integration. Monolithic Power Systems represents the focused power management IC supplier archetype.
| Leading Market Players |
|---|
| Monolithic Power Systems (MPS) |
| Analog Devices |
| DFROBOT |
| Maxim Integrated |
| STMicroelectronics |
| Texas Instruments |
| Silvertel |
| Waveshare |
| SolarEdge |
| Others |
Pricing and Supply Chain Analysis
UL 1741 certification requirements for grid-interactive inverters simultaneously gate supply-side qualification and stratify price tiers, concentrating pricing power among engineering-intensive suppliers with captive test facilities while compressing margins for residential-grade hardware lacking bundled software ecosystems.
Pricing Analysis
Cost-plus contracts with copper and rare earth magnet indexation dominate procurement for utility-scale power blocks, insulating developers from raw material volatility while locking in margin predictability for manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-based 1500V architectures from silicon IGBT alternatives and entry-level residential string inverters. Price erosion runs through residential segments as installer consolidation in California metropolitan markets unbundles equipment from labor. Industrial buyers exhibit lowest price sensitivity, prioritizing documented supply-chain emissions and islanding capability over unit economics.
Supply Chain Analysis
Port congestion on Asia-North America trade lanes elevates inbound logistics costs for gallium nitride device shipments bound for Texas and Arizona commissioning sites. Manufacturing concentrates in China, Taiwan, and South Korea for silicon carbide substrates, with Yangtze River Delta clusters feeding converter scaling. The supply chain draws from copper inductors, rare earth magnets, and lithium-ion cells. Single-source vulnerability in 6-inch SiC wafer capacity creates 18-24 month qualification bottlenecks. Distribution runs through EPC contractors and direct-to-consumer channels serving installer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through UL 1741 and IEEE 1547 certification creates switching costs that protect incumbent positioning against modular software entrants.
For Market Incumbents: Compound certification advantages by deepening backward integration into silicon carbide substrate supply and expanding dedicated test facility capacity ahead of IEEE 1547 revision cycles. SolarEdge and STMicroelectronics face emerging threat from Chinese gallium nitride specialists with state-backed wafer expansion. Prioritize firmware requalification investment to compress product launch timelines relative to engineering-constrained competitors. For New Entrants and Emerging Players: Anchor in Australia's NEM 3.0 preparation window where preemptive replacement demand for export-limited controllers outpaces established supplier coverage. Vehicle-to-home bidirectional charging integration represents the most penetrable white space, with automaker-inverter interoperability standards still unsettled. Pursue direct-to-consumer sales channels in Los Angeles and San Diego metropolitan markets where installer consolidation has already unbundled equipment procurement. For Investors and Strategic Acquirers: FERC Order 2222 implementation reshapes the acquisition landscape by expanding addressable revenue pools for distributed solar aggregation platforms. Long-term viability centers on hybrid system architectures with native battery management protocols. Target engineering-intensive suppliers with UL 1741 test facilities and silicon carbide device portfolios. Watch California NEM 3.0 adoption curves as inflection indicator for storage attachment economics across subsequent state-level net metering reforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Yangtze River Delta manufacturing clusters reduce gallium nitride device lead times for automotive-qualified suppliers. |
| UL 1741 Certification Investment | Dedicated test facilities collapse competitive field to engineering-intensive suppliers with grid-interactive inverter capabilities. |
| Vehicle-to-Home Protocol Development | Bidirectional EV charging integration creates unclaimed white space as automakers negotiate interoperability standards. |
| Cloud-Based Fleet Management Platform | German EPCs leverage centralized analytics for remote diagnostics across Bavarian residential microgrid deployments. |
| Refrigerant-Free Thermal Management Retrofit | EU F-Gas Regulation compliance opens utility-scale markets for liquid-cooled controller architectures ahead of CSRD deadlines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators, validated against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up unit economics triangulated with top-down market sizing across voltage tier, deployment scale, and regional regulatory cluster.
Across the analysis window, volume and value outputs reflect segmentation by product architecture, deployment model, end-user procurement sophistication, and technology integration depth. CAGRs derived from installation run-rate trajectories and technology substitution curves incorporate lithium-ion cost compression timelines and net metering reform implementation schedules.
Material uncertainties — silicon carbide substrate shortage duration, IEEE 1547 revision compliance burdens, copper and rare earth magnet volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about interconnection queue reform pace and feed-in tariff restructuring timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
North America Single Axis Solar Tracker Market