
 Solar Bug Zapper Market | 2026-2036
Solar Bug Zapper Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Bug Zapper Market Insights
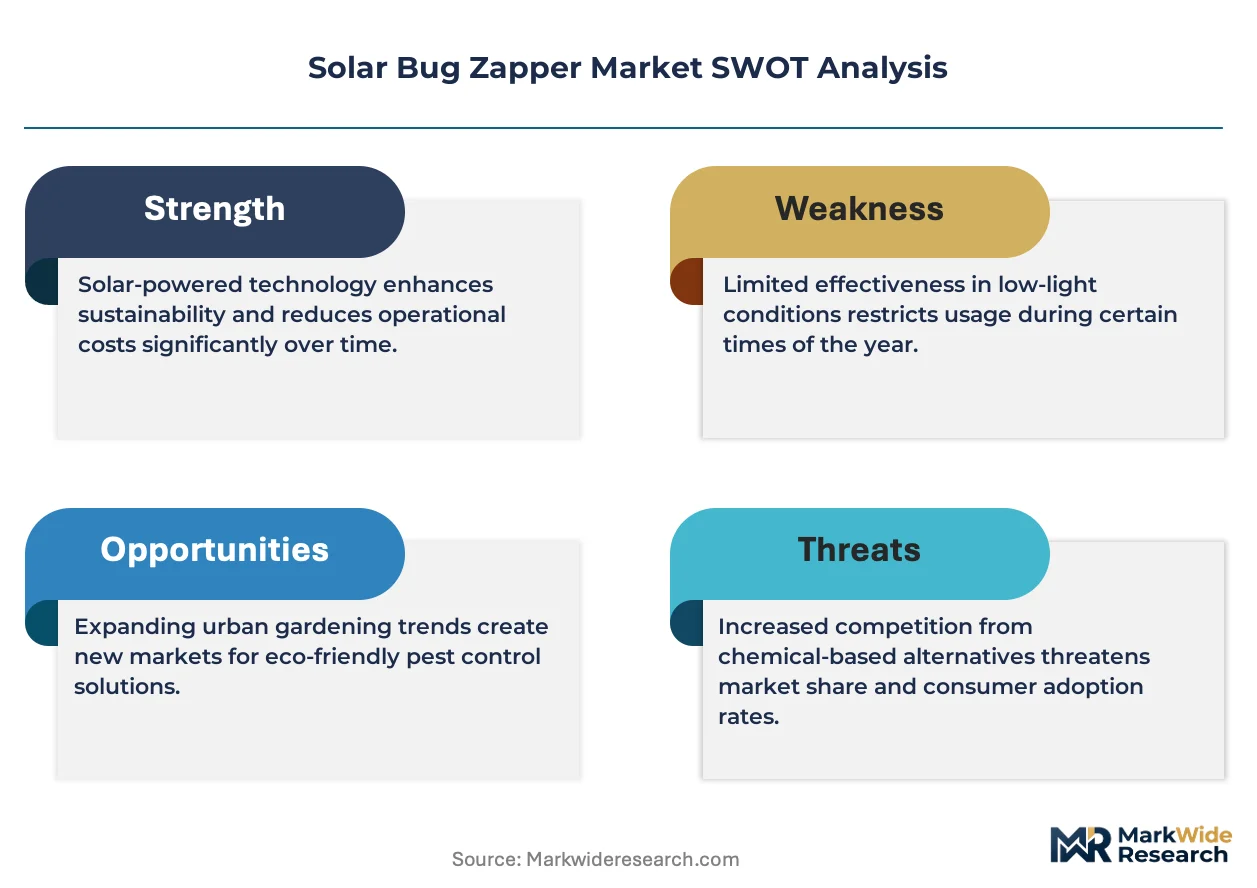
CE marking under the EU Low Voltage Directive is redrawing competitive boundaries for solar-powered insect control devices entering European channels. Flowtron Outdoor Products leverages its heritage in outdoor electrical equipment to sustain brand recognition among rural property owners. Black+Decker anchors shelf presence through home improvement retail partnerships that control point-of-sale visibility. Aspectek specializes in value-tier positioning that competes on unit economics against premium solar alternatives.
A solar bug zapper is a photovoltaic-powered electrocution device that converts sunlight into stored electrical energy, typically via lithium-ion or nickel-metal hydride batteries, to power ultraviolet LED arrays and high-voltage grid assemblies that attract and eliminate flying insects. Its primary commercial purpose is to provide autonomous, off-grid pest suppression for residential patios, agricultural perimeters, and hospitality venues without recurring chemical costs or grid dependency. Solar zappers within the product type taxonomy command expanding shelf space as retailers prioritize rechargeable outdoor living assortments, while the agricultural end user segment exhibits the steepest volume trajectory as vineyard and orchard operators replace pesticide spraying cycles with permanent trap installations. The energy efficient feature tier concentrates margin pools through premium pricing on monocrystalline panel configurations and smart dusk-to-dawn sensors.
EPA pesticide device regulations in the United States classify electric insect traps as regulated articles, mandating efficacy claims substantiation and label accuracy that shape product development timelines and market access costs. CE marking and REACH compliance in Europe impose material restrictions on housing polymers and battery disposal protocols that filter out undercapitalized manufacturers. OSHA workplace safety standards influence commercial deployment specifications for agricultural and hospitality installations. Stakeholders must monitor evolving state-level pollinator protection statutes that could restrict ultraviolet wavelength emissions in ecologically sensitive jurisdictions.
Market Dynamics
EPA pesticide device regulations are compressing product development timelines for electric insect control equipment, forcing manufacturers to front-load efficacy testing and substantiation costs before market entry. This regulatory density favors capitalized players with dedicated compliance infrastructure.
Growth Catalysts
- Residential patio adoption:Sun Belt households in Texas and Florida are replacing chemical repellents with autonomous solar units to avoid recurring spray costs and odor complaints.
- REACH material restrictions:European housing polymer standards are filtering out low-grade manufacturers, clearing shelf space for compliant producers with certified battery disposal protocols.
- Monocrystalline panel efficiency gains:Vineyard operators in California are installing permanent trap grids that eliminate seasonal pesticide spraying cycles.
Market Restraints
- Lithium-ion battery cost volatility:Cell price fluctuations compress margins on entry-tier units that compete on unit economics rather than performance premiums.
- Ultraviolet wavelength technical limitations:Fixed-spectrum LED arrays attract beneficial pollinators, creating ecological liability exposure in sensitive jurisdictions.
- Grid-powered substitute threat:Corded electrocution devices with higher kill rates retain share among commercial buyers with reliable electrical access.
Strategic Opportunities
- Smart dusk-to-dawn sensor convergence:Integration of photovoltaic controllers with IoT connectivity enables remote monitoring for agricultural perimeter networks.
- Home improvement retail channel expansion:Point-of-sale visibility partnerships control shelf positioning against direct-to-consumer entrants.
- Indian agricultural underpenetration:Orchard operators in Maharashtra and Karnataka lack distributed grid access, creating off-grid pest suppression demand.
Industry Challenges
- EPA efficacy certification timelines:Substantiation protocols for electric insect traps extend development cycles by twelve to eighteen months.
- High-voltage grid assembly skill gaps:Manufacturers face shortages of technicians trained in electrocution safety engineering for outdoor equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Bug Zapper Market |
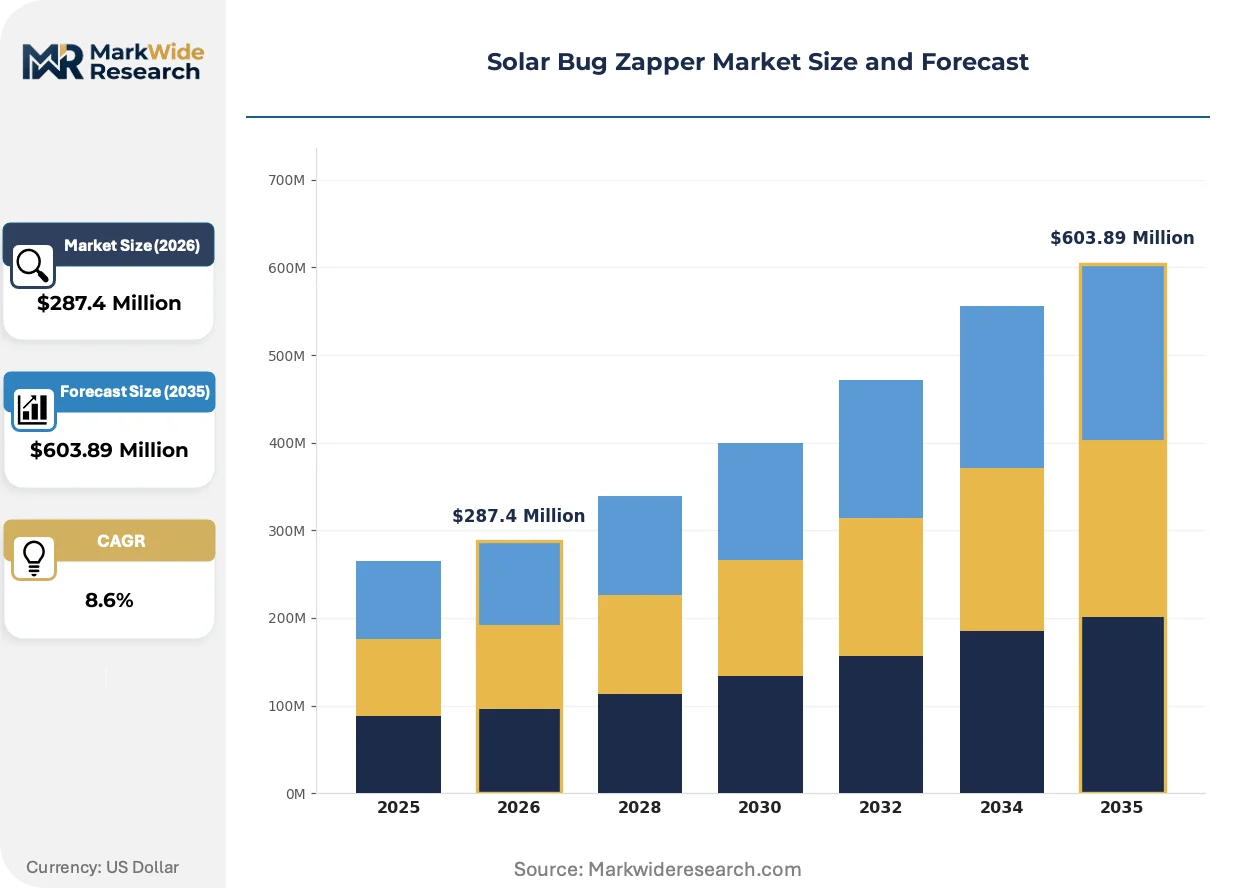
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $603.89 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Zappers, Chemical Zappers, Hybrid Zappers, Solar Zappers End User: Residential, Commercial, Agricultural, Outdoor Events Feature: Portable, Rechargeable, Weatherproof, Energy Efficient Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Home Improvement Stores |
| Companies Covered | Hoont, Flowtron Outdoor Products, Black+Decker, Aspectek, Stinger, Katchy, Bell+Howell, Liba, Woodstream Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Bug Zapper Market Trends and Innovations
Product architecture is bifurcating between premium smart-enabled systems and stripped-down value units, while regulatory compliance costs reshape competitive boundaries. This divergence is compressing mid-tier positioning.
Ultraviolet LED array technology is fragmenting across wavelength-specific configurations that target mosquito species versus general flying insect suppression. Vineyard operators in Napa Valley are adopting narrow-spectrum units that minimize beneficial insect collateral. This specialization is fragmenting supplier R&D budgets across multiple efficacy validation tracks.
CE marking under the EU Low Voltage Directive is tightening electrical safety standards for battery-powered outdoor equipment. Housing polymer flame-retardancy requirements are forcing material substitutions that extend tooling lead times. European importers are consolidating supplier relationships to reduce compliance audit burden.
Buyer preference is rotating toward certified chemical-free pest management in hospitality venues. Resort procurement teams in Arizona and Florida are specifying solar zappers in sustainability scorecards that govern vendor selection. This certification-driven preference shift is displacing traditional spray contractors in seasonal contract bidding.
Solar Bug Zapper Market Segmentation
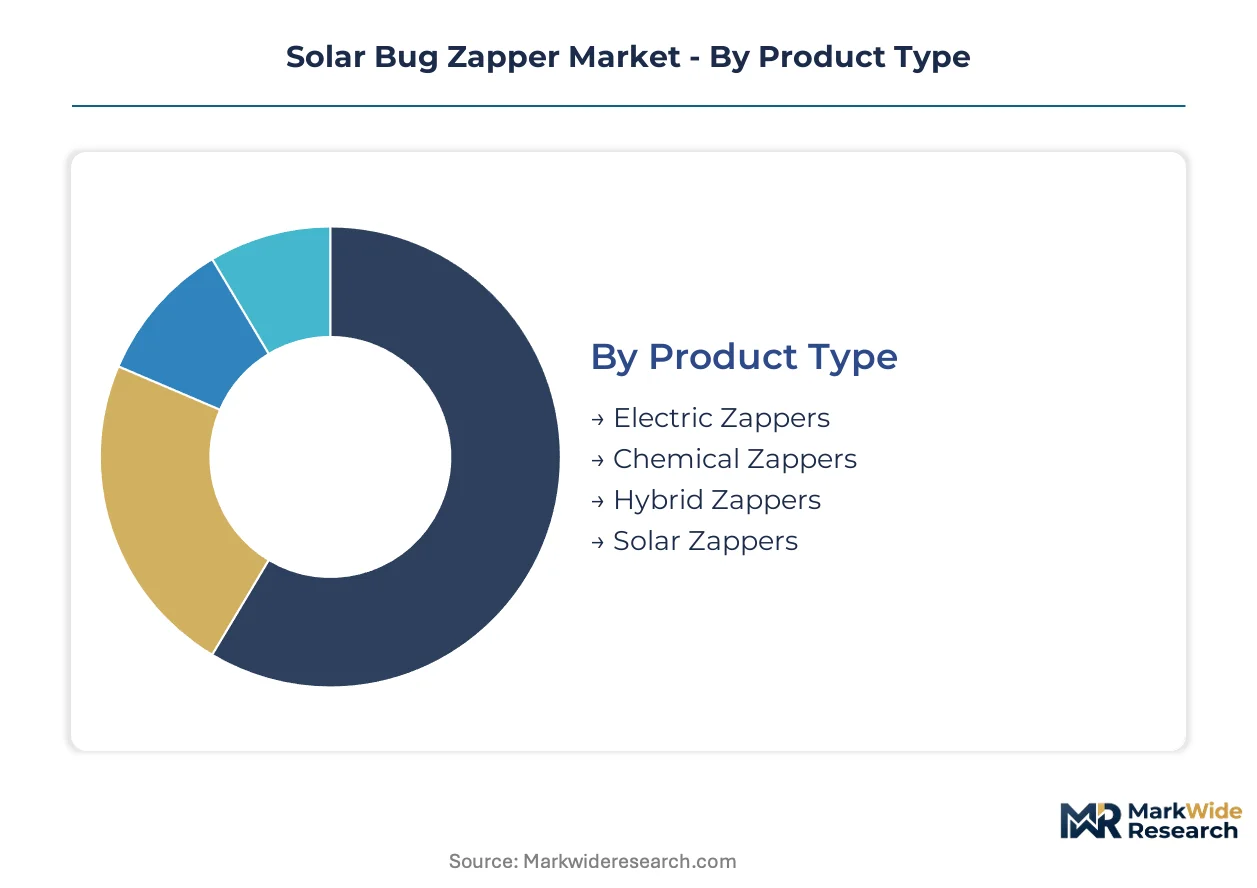
Solar bug zapper segmentation reveals how photovoltaic pest control devices bifurcate across technical architectures, deployment contexts, and buyer sophistication tiers. Channel placement and feature bundling determine margin capture, while end-use concentration shapes regional demand patterns.
Product Type:
Channel placement varies sharply by power source, with solar variants commanding premium shelf positioning in outdoor living assortments while electric units retain commercial contractor preference.
- Solar Zappers:Photovoltaic panels charge lithium-ion storage cells to power ultraviolet LED arrays and high-voltage grids autonomously. Vineyard operators in California's Central Valley favor permanent installations that eliminate seasonal pesticide spraying cycles and grid dependency.
- Electric Zappers:Corded electrocution devices draw continuous grid power for sustained high-voltage output. Hospitality venues in Florida maintain preference for corded units where electrical access is reliable and kill rate consistency governs procurement.
- Chemical Zappers:Hybrid systems combine electrocution with attractant lures or residual chemical strips. Agricultural perimeter deployments in Texas utilize these for species-specific targeting beyond general insect suppression.
- Hybrid Zappers:Dual-mode units switch between solar battery and grid power based on charge state. Rural property owners in Arizona value operational continuity across variable sunlight conditions.
Solar zappers dominate installed base growth. Electric zappers anchor commercial replacement demand where grid infrastructure exists.
End User:
Cost tier stratification separates premium autonomous systems from value-tier substitutes, with agricultural buyers accepting higher unit costs against eliminated chemical recurring spend.
- Agricultural:Permanent trap grids protect vineyard and orchard perimeters without pesticide drift concerns. Napa Valley operators specify narrow-spectrum UV configurations to minimize beneficial insect collateral.
- Residential:Patio-mounted units serve Sun Belt households seeking chemical-free outdoor living. Texas and Florida consumers prioritize dusk-to-dawn automation and weatherproof housing.
- Commercial:Hospitality venues in Arizona integrate solar zappers into sustainability scorecards governing vendor selection. Resort procurement teams specify certified chemical-free pest management.
- Outdoor Events:Temporary deployments for festivals and catering require portable, rapid-setup configurations. Event operators in Florida favor rechargeable units with minimal ground disturbance.
Agricultural end use commands the steepest volume trajectory. Residential patio adoption is climbing fastest among consumer segments.
Feature:
Margin pools concentrate in premium feature tiers, with monocrystalline panel configurations and smart sensors extracting pricing premiums against stripped-down value alternatives.
- Energy Efficient:Monocrystalline photovoltaic cells and smart charge controllers maximize daily kill cycles per watt harvested. Premium vineyard installations in California specify these for maximum autonomous operation.
- Weatherproof:IP-rated housing polymers and sealed battery compartments withstand outdoor exposure. Coastal installations in Florida demand salt-corrosion resistance in housing specifications.
- Rechargeable:Lithium-ion battery architectures enable multi-night operation without direct sunlight. Suburban households in Texas value overnight capacity during cloudy periods.
- Portable:Lightweight collapsible designs suit camping and temporary event deployment. Outdoor recreation retailers in Arizona stock these for seasonal tourist demand.
Energy efficient configurations dominate margin capture. Portable feature demand is expanding fastest in recreation channels.
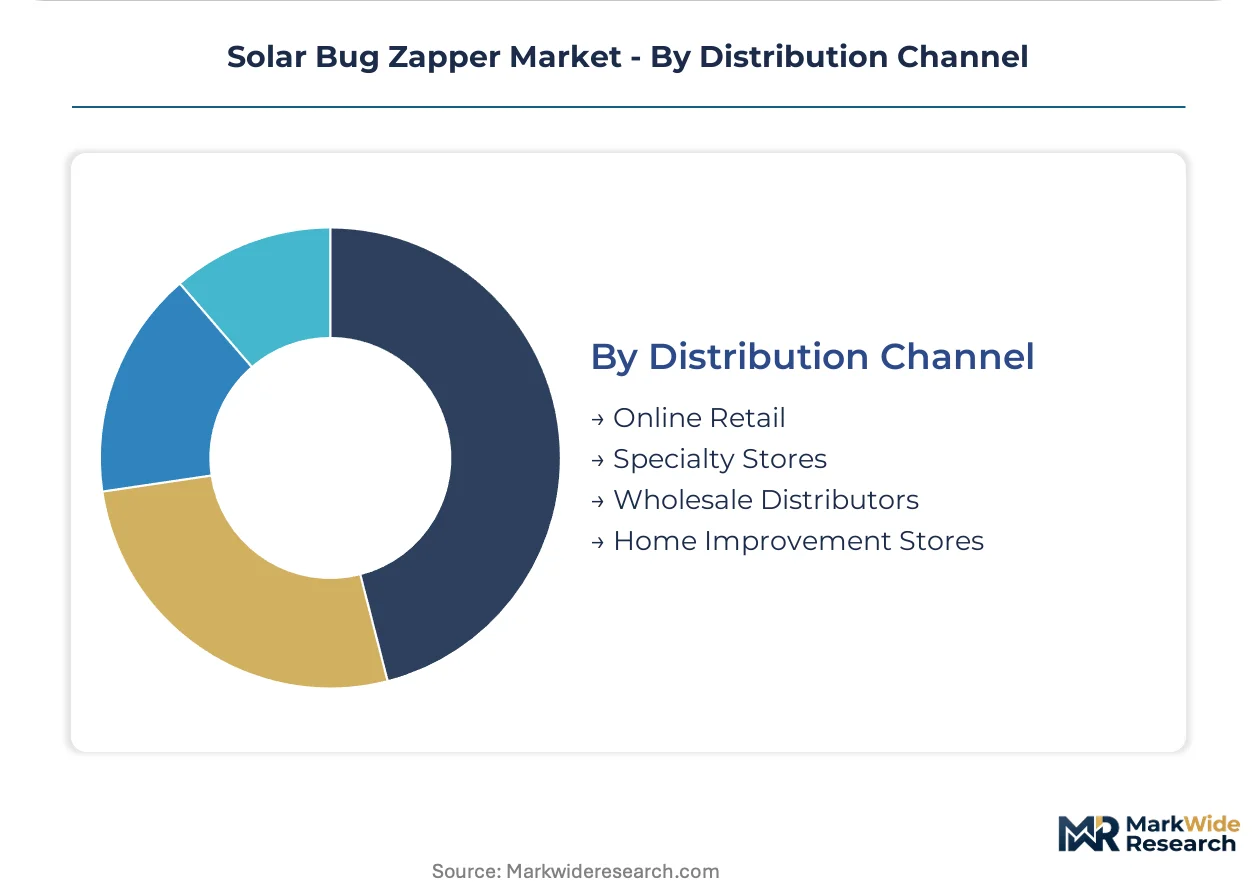
Distribution Channel:
Supply concentration in home improvement retail controls point-of-sale visibility, while online channels fragment price discovery and compress entry-tier margins.
- Home Improvement Stores:Controlled shelf positioning and seasonal promotional calendars drive consumer awareness. Retail partnerships in Texas and Florida govern brand visibility during peak mosquito season.
- Online Retail:Direct-to-consumer platforms enable specification comparison and review-driven selection. Price transparency here compresses margins on undifferentiated solar alternatives.
- Specialty Stores:Agricultural supply and outdoor living boutiques offer technical consultation for complex deployments. Vineyard operators in California prefer these for integration advice.
- Wholesale Distributors:Bulk procurement channels serve commercial and hospitality buyers with volume pricing. Resort procurement teams in Arizona leverage these for property-wide standardization.
Home improvement stores dominate consumer installed base. Online retail is where price-based substitution concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor underpins United States demand through integrated plastics supply chains serving housing polymer specifications for outdoor electrical equipment.
United States
Sun Belt households in Texas and Florida drive residential patio adoption as mosquito seasons extend. EPA pesticide device regulations mandate efficacy claim substantiation that filters out undercapitalized entrants. Vineyard operators in California's Napa Valley install permanent trap grids to eliminate seasonal pesticide spraying cycles.
Germany
REACH material restrictions on housing polymers and battery disposal protocols reshape manufacturing compliance burdens. CE marking under the EU Low Voltage Directive tightens electrical safety standards for photovoltaic outdoor equipment. Industrial clusters in Baden-Württemberg concentrate precision electronics fabrication for smart dusk-to-dawn sensor modules.
China
Monocrystalline photovoltaic cell manufacturing scale drives component cost compression for export-oriented assemblers. GB standards for electrical safety and battery transportation govern domestic circulation and cross-border shipment certification. Yangtze River Delta industrial zones host integrated supply chains linking panel fabrication with lithium-ion cell assembly.
India
Maharashtra and Karnataka orchard operators lack distributed grid access, creating off-grid pest suppression demand for vineyard and mango plantation perimeters. BIS certification requirements for electrical equipment impose testing timelines that extend market entry for imported units. Agricultural supply networks in Pune and Bengaluru channel technical consultation for complex deployment specifications.
Australia
Coastal hospitality venues in Queensland integrate solar zappers into sustainability procurement scorecards governing vendor selection. TGA-equivalent electrical safety standards administered by state regulators filter non-compliant imports from Asian manufacturing sources. Outdoor recreation retailers in New South Wales stock portable configurations for seasonal tourist demand from camping and festival segments.
Solar Bug Zapper Market Competitive Landscape
Listed leaders compete with private specialists across channel access and compliance infrastructure dimensions. The vendor base stratifies between capitalized multi-category brands with dedicated regulatory teams and regional fabricators competing on unit economics. Three archetypes dominate: home improvement retail anchor brands, agricultural supply specialists, and direct-to-consumer value-tier entrants. Competitive moves concentrate on home improvement retail partnership expansion and EPA efficacy certification pre-positioning.
Within the retail anchor tier, Flowtron Outdoor Products and Black+Decker exemplify channel-controlled positioning through point-of-sale visibility partnerships. Aspectek occupies a value-tier position competing on unit economics against premium solar alternatives. These three represent divergent strategic postures: heritage outdoor electrical equipment credibility, home improvement retail shelf dominance, and stripped-down specification targeting.
| Leading Market Players |
|---|
| Hoont |
| Flowtron Outdoor Products |
| Black+Decker |
| Aspectek |
| Stinger |
| Katchy |
| Bell+Howell |
| Liba |
| Woodstream Corporation |
| Others |
Pricing and Supply Chain Analysis
Monocrystalline photovoltaic cell scale economies in the Yangtze River Delta compress component costs for export-oriented assemblers while simultaneously concentrating supply power among integrated panel-battery manufacturers, creating price floors that undercapitalized fabricators cannot breach.
Pricing Analysis
Volume-discount tiering separates premium monocrystalline configurations with smart dusk-to-dawn sensors from standard polycrystalline units and economy-tier stripped-down alternatives. Price differentiation rests on certification grade—EPA efficacy substantiation and CE marking under the EU Low Voltage Directive extract premiums from compliant producers. Pricing pressure intensifies in the entry tier as lithium-ion battery cost volatility compresses margins on units competing on unit economics. Agricultural buyers exhibit lowest price sensitivity, accepting higher upfront costs against eliminated chemical recurring spend, while residential patio consumers in Texas and Florida drive hardest bargain hunting.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells and housing polymers dominates inventory strategy as manufacturers buffer against raw material volatility and extended EPA certification timelines. Supply concentrates in China for monocrystalline photovoltaic fabrication, South Korea for battery cell assembly, and the United States for precision electronics integration. Raw material dependencies include polysilicon ingots, flame-retardant housing polymers, and ultraviolet LED emitters. Single-source vulnerability in battery cell supply creates exposure to export restriction shocks. Distribution runs through home improvement retail partnerships that control point-of-sale visibility against direct-to-consumer fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA efficacy certification expertise and high-voltage grid assembly engineering capability sit in short supply relative to market expansion, creating durable competitive moats for incumbents with dedicated compliance infrastructure and trained technician pipelines.
For Market Incumbents: Consolidate regulatory compliance capabilities through dedicated EPA pre-submission teams and CE marking audit infrastructure to extend lead times that undercapitalized entrants cannot match. Deepen backward integration into lithium-ion cell supply through captive offtake agreements with Yangtze River Delta manufacturers, insulating margin pressure from raw material volatility. Channel control through home improvement retail partnership expansion remains essential against direct-to-consumer erosion. For New Entrants and Emerging Players: Anchor in Indian agricultural supply networks serving Maharashtra and Karnataka orchard operators lacking distributed grid access, where off-grid pest suppression demand outstrips compliant supply. Target technical consultation positioning through specialty store relationships that vineyard operators prefer for complex deployment integration. Pursue narrow-spectrum UV specialization to minimize beneficial insect collateral and capture premium positioning in ecologically sensitive jurisdictions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among agricultural perimeter network operators with permanent trap grid installations and seasonal maintenance contracts, offering superior cash flow predictability over residential transactional sales. Long-term viability favors targets with EPA efficacy certification pre-positioning and REACH-compliant material sourcing infrastructure. Watch for inflection when state-level pollinator protection statutes restrict ultraviolet wavelength emissions, favoring narrow-spectrum technology holders.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Efficacy Certification Pre-Positioning | Front-loaded substantiation costs filter undercapitalized competitors from United States market access. |
| Backward Integration into Battery Supply | Captive lithium-ion cell offtake insulates margin compression from raw material price volatility. |
| Narrow-Spectrum UV R&D Specialization | Species-specific targeting minimizes ecological liability exposure under emerging pollinator protection statutes. |
| Home Improvement Retail Partnership Expansion | Controlled shelf positioning governs consumer awareness during peak mosquito season in Texas and Florida. |
| Smart Sensor IoT Convergence | Remote monitoring integration enables agricultural perimeter network subscription revenue models. |
Research Methodology
A standing panel of agricultural supply distributors, home improvement retail category managers, vineyard operations directors, EPA regulatory affairs consultants, and lithium-ion battery procurement specialists provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with these stakeholders and trade observation at specialty agricultural supply exhibitions. Secondary sources included EPA pesticide device registration databases, CE marking compliance directories, customs trade records for photovoltaic outdoor equipment, and hospitality procurement sustainability scorecard disclosures. Bottom-up installed base modeling triangulated against top-down market sizing from channel shipment data.
Consistency checks validated volume and value outputs against external benchmarks including solar outdoor lighting category growth patterns and electric insect control equipment trade flows. The analytical framework modeled demand across product type, end user sophistication tier, feature bundling, and distribution channel concentration throughout the projection horizon. CAGRs derived from segment-level trajectory analysis incorporating photovoltaic efficiency improvement curves and regulatory compliance cost inflation. Industry-specific forecast inputs included Sun Belt household formation patterns and vineyard acreage expansion in California's Central Valley.
Material uncertainties—lithium-ion battery cost volatility, pollinator protection statute adoption timelines, and REACH material restriction enforcement intensity—sit outside the modeled envelope. Forecasts reflect assumptions regarding EPA efficacy certification timeline stability and monocrystalline panel cost compression continuity. Revision becomes warranted when state-level ultraviolet emission restrictions cross implementation thresholds or when battery cell supply concentration triggers export control measures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
US Solar Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Solar Photovoltaic (PV) Market