
 Next Generation Advanced Battery Market | 2026-2036
Next Generation Advanced Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Advanced Battery Market Foresight
Silicon anode chemistry is shifting cost-performance tradeoffs across the next generation advanced battery landscape. CATL leverages its integrated mining-to-cell manufacturing footprint to secure raw material access at scale. LG Energy Solution anchors its position through dedicated supply partnerships with premium automotive OEMs. Samsung SDI competes on cylindrical form-factor specialization for high-performance drivetrain applications.
Next generation advanced batteries encompass electrochemical storage systems exceeding 300 Wh/kg energy density with enhanced thermal stability profiles, manufactured through dry electrode coating and solid electrolyte integration processes to enable extended-cycle electric propulsion and grid-scale dispatch. Solid-state product types command premium positioning due to manufacturing complexity and unresolved interface engineering constraints, while lithium-sulfur technology variants attract defense and aerospace procurement interest for their gravimetric advantages. Electric vehicle applications absorb the dominant share of cell output, though renewable energy storage deployments are expanding fastest as utility procurement standards harden around four-hour duration requirements.
The EPA tailpipe emissions framework and the EU Green Deal battery passport requirements are accelerating demand for domestically traceable cell supply chains with verified carbon intensity thresholds. China's MIIT cell quality grading standards and NMPA safety certification protocols shape product access for manufacturers targeting the world's largest electric vehicle fleet. Stakeholders must monitor which regulatory jurisdiction succeeds in standardizing solid-state cell safety testing protocols, as this determination will concentrate certification-seeking investment and reshape competitive access.
Market Dynamics
Solid-state electrolyte integration is compressing conventional lithium-ion development timelines as OEMs demand thermal runaway elimination and 30-minute fast-charge compatibility. This chemistry transition is redistributing capital toward dry electrode coating equipment and sulfide-based ceramic separator manufacturing.
Growth Catalysts
- EPA Tailpipe Emissions Framework:The US regulatory mandate for fleet electrification by 2032 is forcing automakers to secure high-density cell supply with verified carbon intensity thresholds.
- Silicon Anode Chemistry:This material substitution pathway is unlocking 20% energy density gains over graphite architectures while leveraging existing roll-to-roll manufacturing infrastructure.
- German Industrial Clusters:Concentrated pilot production capacity around Stuttgart and Dresden is attracting cathode precursor and separator membrane suppliers into co-located supply networks.
Market Restraints
- Lithium Carbonate Volatility:Spot price swings in Chilean and Australian spodumene concentrate are compressing cathode manufacturer margins and destabilizing long-term offtake contracting.
- Chinese Cathode Concentration:Over 70% of global NMC precursor refining capacity sits within Jiangsu and Fujian provinces, creating single-source vulnerability for European cell producers.
- Solid-State Interface Instability:Dendrite penetration through ceramic electrolyte layers at sub-zero temperatures remains unresolved, delaying automotive qualification timelines.
Strategic Opportunities
- Indian PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting electrode coating and electrolyte formulation investments into Gujarat and Tamil Nadu.
- Grid-Scale Four-Hour Duration Mandates:Utility procurement standards in Texas and California are opening containerized battery system deployments with solid-state safety profiles.
- Lithium-Sulfur Aerospace Convergence:Defense procurement programs are funding gravimetric-optimized cell architectures for unmanned aerial vehicle propulsion beyond 400 Wh/kg.
Industry Challenges
- Dry Electrode Coating Talent Scarcity:Process engineers with solvent-free calendaring expertise command premium compensation as equipment vendors struggle to scale training programs.
- Solid-State Certification Timelines:UN 38.3 transport safety testing protocols lack standardized procedures for sulfide electrolyte cells, forcing manufacturers into bilateral negotiations with national aviation regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Advanced Battery Market |
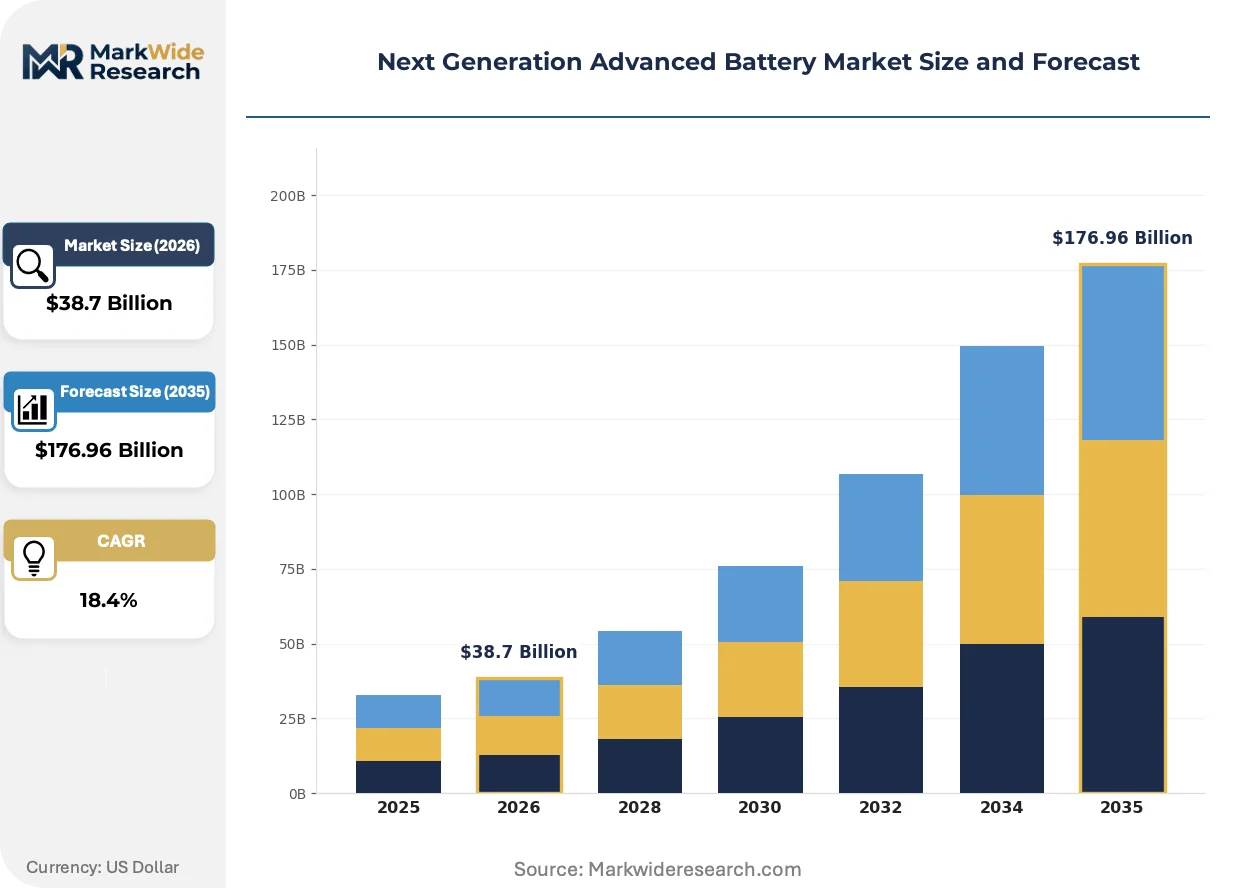
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Flow Application: Electric Vehicles, Renewable Energy Storage, Consumer Electronics, Industrial Equipment Technology: Graphene, Lithium-Sulfur, Cobalt-Free, Thin-Film End User: Automotive Manufacturers, Electronics Companies, Energy Providers, Aerospace |
| Companies Covered | Contemporary Amperex Technology Co. Ltd. (CATL), LG Energy Solution, BYD Company Ltd., Panasonic Energy Co. Ltd., Samsung SDI, QuantumScape Battery Inc., GS Yuasa Corporation, Sion Power Corporation, Johnson Matthey PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Advanced Battery Market Shifts & Advancements
Electrochemical architecture decisions are locking in competitive positioning for the next decade as energy density targets harden and thermal safety becomes non-negotiable for automotive qualification.
Semi-solid hybrid electrolyte formulations are overtaking pure liquid systems in premium electric vehicle segments. These gel-polymer architectures suppress thermal runaway propagation while maintaining ionic conductivity above 10 mS/cm. Korean and Japanese automakers are fast-tracking platform integration for 2027 model year launches. This chemistry bridge is overtaking conventional NMC811 as the default pathway to solid-state readiness without full manufacturing retooling.
The EU Green Deal battery passport requirements are mandating full supply chain traceability from mine to module. This regulatory framework forces disclosure of carbon intensity, recycled content share, and human rights due diligence across tier-three suppliers. European cell producers are responding by vertically integrating into Finnish nickel refining and Portuguese lithium conversion to secure compliant feedstock.
Automotive OEMs are consolidating cell procurement around direct long-term offtake agreements rather than spot market purchasing. This contracting shift eliminates trader intermediaries and locks in volume commitments with cathode active material suppliers. The restructuring is most visible in German premium vehicle programs where dual-source strategies are giving way to exclusive partnerships with single cell producers.
Next Generation Advanced Battery Market Segmentation
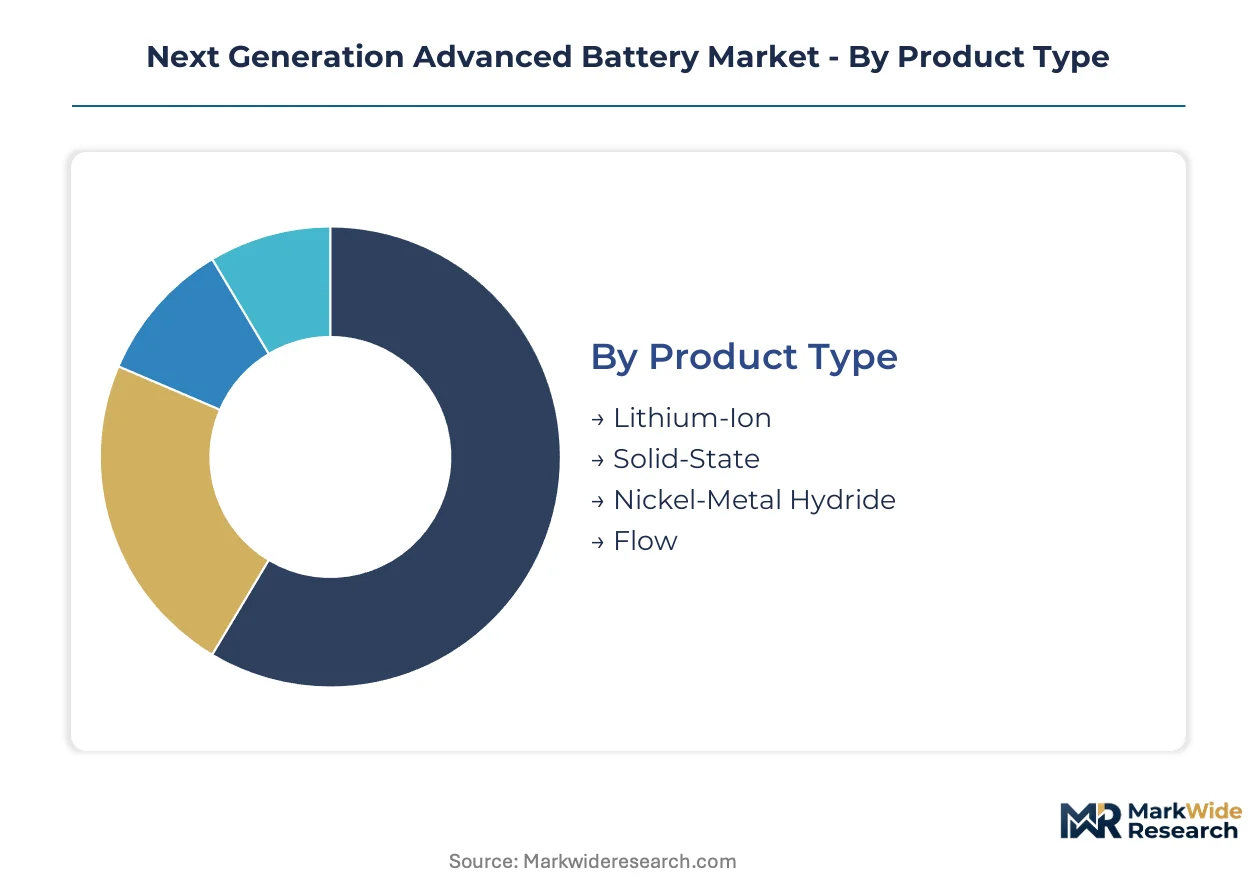
Electrochemical architecture choices in next generation advanced batteries lock in decade-long competitive positioning as energy density targets harden and thermal safety becomes non-negotiable for automotive qualification. Segment boundaries are blurring as solid-state manufacturing techniques migrate across product categories and application requirements reshape cell form factors.
Product Type:
Volume concentration clusters around established manufacturing infrastructure while premium positioning accrues to emerging chemistries with unresolved scaling challenges.
- Lithium-Ion:Graphite-anode and NMC-cathode configurations dominate current production through proven roll-to-roll coating infrastructure. Automotive OEMs in Germany and the United States anchor demand as fleet electrification mandates tighten, though silicon-anode substitution is compressing traditional energy density advantages.
- Solid-State:Ceramic or sulfide electrolyte architectures eliminate thermal runaway risk while enabling lithium-metal anodes. Pilot production lines in Japan and South Korea are supplying German premium vehicle programs, constrained by interface engineering challenges and dry electrode coating equipment bottlenecks.
- Nickel-Metal Hydride:Mature chemistry retains hybrid vehicle applications where cost sensitivity outweighs gravimetric performance requirements.
- Flow:Vanadium and zinc-bromide redox systems target grid-scale duration needs above four hours, with utility procurement in Texas driving containerized deployments.
Mature deployment sits with Lithium-Ion. Newer deployment is concentrated in Solid-State.
Application:
Customer procurement patterns diverge sharply between mobility platforms requiring crash-safe packaging and stationary systems prioritizing cycle life over volumetric density.
- Electric Vehicles:Passenger and commercial drivetrain applications demand cylindrical or prismatic cells exceeding 300 Wh/kg with 30-minute fast-charge compatibility. Chinese MIIT quality grading standards and EPA tailpipe frameworks are hardening qualification requirements simultaneously.
- Renewable Energy Storage:Utility-scale deployments absorb containerized battery systems as California and Texas procurement standards mandate four-hour duration minimums. Solid-state safety profiles are opening substation-adjacent siting opportunities previously restricted by fire code limitations.
- Consumer Electronics:Pouch cell formats prioritize thin-profile packaging for smartphones and laptops, with EU Green Deal battery passport requirements forcing supply chain traceability disclosures.
- Industrial Equipment:Forklift and material handling applications favor established chemistries with swap-station infrastructure already deployed across manufacturing clusters.
Procurement scale concentrates in Electric Vehicles. Steepest expansion trajectory is occurring in Renewable Energy Storage.
Technology:
Material substitution pathways are redistributing R&D capital away from conventional cathode formulations toward architectures that reduce critical mineral dependence.
- Graphene:Conductive additive integration enhances electrode kinetics and thermal conductivity in high-rate applications. Defense procurement programs are funding scaled production of few-layer graphene for unmanned aerial vehicle power systems.
- Lithium-Sulfur:Elemental sulfur cathodes paired with lithium-metal anodes achieve gravimetric densities above 400 Wh/kg. Aerospace end users in the United States and Europe are qualifying cells for satellite and high-altitude platform propulsion where mass reduction dominates cost considerations.
- Cobalt-Free:Lithium-iron-phosphate and high-nickel low-cobalt NMC variants reduce supply chain exposure to Democratic Republic of Congo sourcing risks.
- Thin-Film:Micro-scale solid-state cells target medical implant and sensor applications requiring extreme cycle stability in constrained form factors.
Commercial maturity clusters around Cobalt-Free formulations. Emerging qualification activity centers on Lithium-Sulfur.
End User:
Contracting power has shifted toward direct long-term offtake agreements as traders are eliminated from cathode active material procurement.
- Automotive Manufacturers:German premium vehicle programs are consolidating dual-source strategies into exclusive partnerships with single cell producers. OEMs are co-locating battery pack assembly with cell manufacturing to capture integrated margin and simplify carbon intensity verification.
- Electronics Companies:Smartphone and laptop brands are mandating recycled content minimums and human rights due diligence across tier-three suppliers under EU Green Deal disclosure requirements.
- Energy Providers:Utility procurement desks are standardizing around four-hour duration containerized systems with solid-state safety profiles for substation-adjacent deployment.
- Aerospace:Defense agencies are funding gravimetric-optimized cell architectures beyond 400 Wh/kg for unmanned aerial vehicle propulsion and satellite power systems.
Contracting volume dominance rests with Automotive Manufacturers. Gaining share fastest is Energy Providers as utility procurement standards harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of cell output as the world's largest electric vehicle fleet expands, while Germany and the United States concentrate pilot production capacity and government-backed innovation funding. Fleet electrification mandates across these three economies are redirecting manufacturing investment toward solid-state and silicon-anode architectures.
China
CATL and BYD anchor domestic demand through integrated mining-to-cell manufacturing footprints that secure raw material access at scale. MIIT cell quality grading standards and NMPA safety certification protocols shape product access for manufacturers targeting the national electric vehicle fleet. Jiangsu and Fujian provinces concentrate over 70 percent of global NMC precursor refining capacity, creating single-source vulnerability for European cell producers seeking compliant feedstock.
Germany
Stuttgart and Dresden industrial clusters attract cathode precursor and separator membrane suppliers into co-located supply networks serving premium automotive OEMs. EU Green Deal battery passport requirements mandate full supply chain traceability from mine to module, forcing disclosure of carbon intensity and recycled content share. Bavarian cell producers are responding by securing Finnish nickel refining and Portuguese lithium conversion to meet verified carbon intensity thresholds.
United States
EPA tailpipe emissions framework mandates fleet electrification by 2032, forcing automakers to secure high-density cell supply with domestic traceability. Texas and California utility procurement standards mandate four-hour duration minimums, opening containerized battery system deployments with solid-state safety profiles. The IRA production tax credits are attracting electrode coating and electrolyte formulation investments into the Southeast manufacturing corridor.
Japan
Panasonic Energy and Samsung SDI compete on cylindrical form-factor specialization for high-performance drivetrain applications serving domestic and export markets. METI technology roadmaps prioritize sulfide-based ceramic separator manufacturing for solid-state qualification timelines. Kyushu-based pilot production lines are supplying German premium vehicle programs, constrained by interface engineering challenges and dry electrode coating equipment bottlenecks.
South Korea
LG Energy Solution anchors its position through dedicated supply partnerships with premium automotive OEMs requiring 30-minute fast-charge compatibility. Korean automakers are fast-tracking semi-solid hybrid electrolyte platform integration for 2027 model year launches. The Busan-Ulsan industrial complex concentrates cathode active material production as dual-source strategies give way to exclusive partnerships with single cell producers.
Next Generation Advanced Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers race to secure qualified supply for 2027-2030 automotive platform launches. The vendor base stratifies across three tiers: integrated mining-to-cell conglomerates with captive raw material access, specialized cylindrical and prismatic form-factor producers with automotive qualification track records, and solid-state technology ventures focused on ceramic electrolyte interface engineering. Strategic archetypes include backward integration into precursor refining, exclusive offtake partnerships with premium OEMs, and sulfide electrolyte manufacturing scale-up. Geographic expansion into India and Southeast Asia and technology licensing for dry electrode coating processes represent the dominant competitive moves.
Among integrated Chinese manufacturers, Contemporary Amperex Technology Co. Ltd. exemplifies the mining-to-cell archetype through its control over upstream material access. LG Energy Solution and Samsung SDI occupy positions within the specialized form-factor tier, representing Korean industrial concentration around cylindrical cell architectures for high-performance applications. These three entities anchor the competitive structure as the industry transitions from liquid electrolyte systems toward solid-state manufacturing platforms.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| LG Energy Solution |
| BYD Company Ltd. |
| Panasonic Energy Co. Ltd. |
| Samsung SDI |
| QuantumScape Battery Inc. |
| GS Yuasa Corporation |
| Sion Power Corporation |
| Johnson Matthey PLC |
| Others |
Supply & Pricing Matrix
Process engineers with solvent-free calendaring expertise in Germany's Stuttgart-Dresden corridor command premium compensation, widening spreads between premium solid-state cell pricing and standard lithium-ion contract rates as labor-cost differentials compound raw material volatility effects.
Pricing Analysis
Volume concentration in graphite-anode NMC cells competes against margin capture in solid-state pilot production. Three-tier pricing structure across premium, standard, and economy levels separates automotive qualification-grade cells from industrial equipment swaps and consumer electronics pouches. Price differentiation hinges on carbon intensity certification tiers under EU Green Deal battery passport requirements and MIIT quality grading standards. Cost compression in standard lithium-ion tiers is intensifying because Chinese cathode concentration enables aggressive offtake contracting. Automotive OEMs exhibit lowest price sensitivity given fleet electrification mandates; renewable energy storage procurement desks show highest sensitivity as utility rate-base scrutiny hardens.
Supply Chain Analysis
Containerized freight costs from Chilean spodumene ports and Australian concentrate terminals amplify raw material price swings for European cathode manufacturers. Geographic supply concentration clusters in China, South Korea, and Japan for cell production, with Jiangsu and Fujian provinces anchoring NMC precursor refining. Raw material dependencies center on lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks. Single-source vulnerability pervades the Jiangsu-Fujian refining corridor, exposing European cell producers to disruption. Distribution runs through direct long-term offtake agreements with automotive OEMs, eliminating trader intermediaries from cathode active material procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Green Deal battery passport requirements erect barrier-to-entry moats favoring producers with verified carbon intensity thresholds and full mine-to-module traceability infrastructure.
For Market Incumbents: Acquire dry electrode coating equipment fleets and sulfide-based ceramic separator manufacturing lines to defend against semi-solid hybrid electrolyte substitution threats. Secure captive supply of Finnish nickel refining and Portuguese lithium conversion to meet EU Green Deal carbon intensity verification. Anchor capacity expansion in Germany's Stuttgart-Dresden corridor to exploit co-located supplier network effects. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cell manufacturing opens a window for electrode coating and electrolyte formulation investments into Gujarat and Tamil Nadu. Target renewable energy storage deployments in Texas and California where four-hour duration mandates and solid-state safety profiles create substation-adjacent siting opportunities. Pursue defense procurement programs for lithium-sulfur gravimetric-optimized architectures as the most penetrable aerospace segment. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state technology ventures possessing resolved interface engineering capabilities given automotive qualification timeline compression. Long-term viability over the analysis window favors producers with sulfide electrolyte manufacturing scale-up and dry electrode process expertise. Monitor which regulatory jurisdiction standardizes solid-state cell safety testing protocols as the inflection signal for certification-seeking investment concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Sulfide Electrolyte Manufacturing Scale-Up | Resolves interface engineering constraints blocking automotive qualification timelines under UN 38.3 protocols. |
| Backward Integration into Precursor Refining | Captures Finnish nickel and Portuguese lithium conversion to satisfy EU Green Deal carbon intensity thresholds. |
| Exclusive Offtake Partnerships with Premium OEMs | Locks volume commitments as German vehicle programs consolidate dual-source strategies into single-producer relationships. |
| Dry Electrode Coating Process Licensing | Addresses talent scarcity in solvent-free calendaring expertise constraining solid-state pilot production expansion. |
| Geographic Expansion into India PLI Corridors | Captures production-linked incentives for advanced chemistry cell manufacturing in Gujarat and Tamil Nadu clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with cell production engineers, cathode precursor procurement leads, automotive platform electrification directors, utility storage procurement managers, and sulfide electrolyte R&D specialists. Secondary validation drew from MIIT quality grading disclosures, EPA tailpipe framework dockets, EU Green Deal battery passport documentation, EIA utility-scale storage deployment databases, and IEA critical mineral supply chain reports. Bottom-up cell production capacity modeling triangulated against top-down automotive electrification mandate projections.
Segment-level granularity modeled electrochemical architecture choices, application requirements across mobility and stationary platforms, technology substitution pathways, and end-user contracting patterns throughout the forecast period. CAGRs derived from installed base evolution, replacement cycle compression, and regulatory mandate phase-in schedules. Industry-specific forecast inputs incorporated solid-state manufacturing yield assumptions and silicon-anode substitution curves.
The model assumes a particular technology adoption path; alternative pathways for sulfide-based ceramic separator manufacturing would alter the outlook. Forecasts reflect assumptions regarding interface engineering resolution timelines and dry electrode coating equipment deployment rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market