
 Solar Appliances Market | 2026-2036
Solar Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Appliances Market Analytics
Passivated contact cell architecture is reshaping how solar appliances convert and store energy, pushing manufacturers toward higher-efficiency module designs that reduce balance-of-system costs. LONGi leverages vertical integration from polysilicon to module assembly to sustain cost leadership in photovoltaic water heaters. JinkoSolar anchors its position through R&D intensity in bifacial cell technology for commercial rooftop installations. Trina Solar differentiates by controlling distributed generation channels across Southeast Asian markets.
Solar appliances integrate photovoltaic or thermal collectors with dedicated storage and control systems to power heating, cooling, charging, or refrigeration functions without grid dependency. Most residential units employ monocrystalline silicon panels rated between 300W and 600W paired with lithium-ion or lead-acid battery banks sized for diurnal cycling. Solar water heaters dominate product type revenue due to mature supply chains and straightforward retrofit compatibility with existing plumbing infrastructure. Off-grid installation systems represent the fastest-expanding segment as microfinance and pay-as-you-go business models unlock rural consumer access. Agricultural end users command disproportionate policy attention through dedicated subsidy mechanisms, though commercial buyers deliver steadier margin pools through volume procurement contracts.
The EU Green Deal and REACH chemical safety standards constrain material choices for solar thermal collectors sold in European markets, while India's BIS certification mandates efficiency labeling for domestic solar water heater sales. The US EPA Energy Star program and state-level renewable portfolio standards shape demand pull for grid-tied residential systems across California, Texas, and Florida. Stakeholders must monitor how evolving battery chemistry regulations and circular economy mandates for panel recycling reshape component sourcing and end-of-life liability structures.
Market Dynamics
Passivated contact cell architecture is compressing balance-of-system costs across solar appliance portfolios, forcing manufacturers to redesign module layouts and thermal management systems around higher-efficiency conversion layers.
Growth Catalysts
- India's KUSUM Scheme:Farm-level solarization subsidies are channeling procurement toward hybrid installation systems for agricultural pumping and cold storage, accelerating rural electrification uptake.
- Sub-Saharan electrification programs:Off-grid solar refrigerators and chargers are penetrating agricultural cooperatives through pay-as-you-go financing structures that bypass traditional credit barriers.
- EU Green Deal efficiency mandates:REACH chemical safety standards and renewable energy directives are tightening material specifications for imported solar thermal collectors, reshaping supplier qualification criteria.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in East Asia create input cost volatility and geopolitical exposure for storage-dependent appliance categories.
- Polysilicon price cycles:Raw material cost swings compress module margins and destabilize long-term procurement contracts for water heater manufacturers.
- Lead-acid substitution ceiling:Rural off-grid segments remain tethered to heavier, shorter-cycle battery chemistries due to lithium-ion price premiums and temperature sensitivity constraints.
Strategic Opportunities
- Microfinance channel expansion:Distributed generation vendors are unlocking rural consumer access through asset-financing partnerships that reduce upfront capital barriers.
- Bifacial cell convergence:Dual-sided photovoltaic technology is penetrating commercial rooftop installations, enabling higher yield per square meter and reducing land-use intensity.
- Circular economy mandates:EU panel recycling directives and extended producer responsibility frameworks are creating aftermarket service revenue streams and material recovery ecosystems.
Industry Challenges
- Certification timeline compression:BIS efficiency labeling requirements for domestic solar water heaters in India are forcing manufacturers to accelerate testing cycles and documentation workflows.
- Installation skill scarcity:Distributed generation channel growth in Southeast Asian markets is outpacing trained technician availability, creating service quality variability and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Appliances Market |
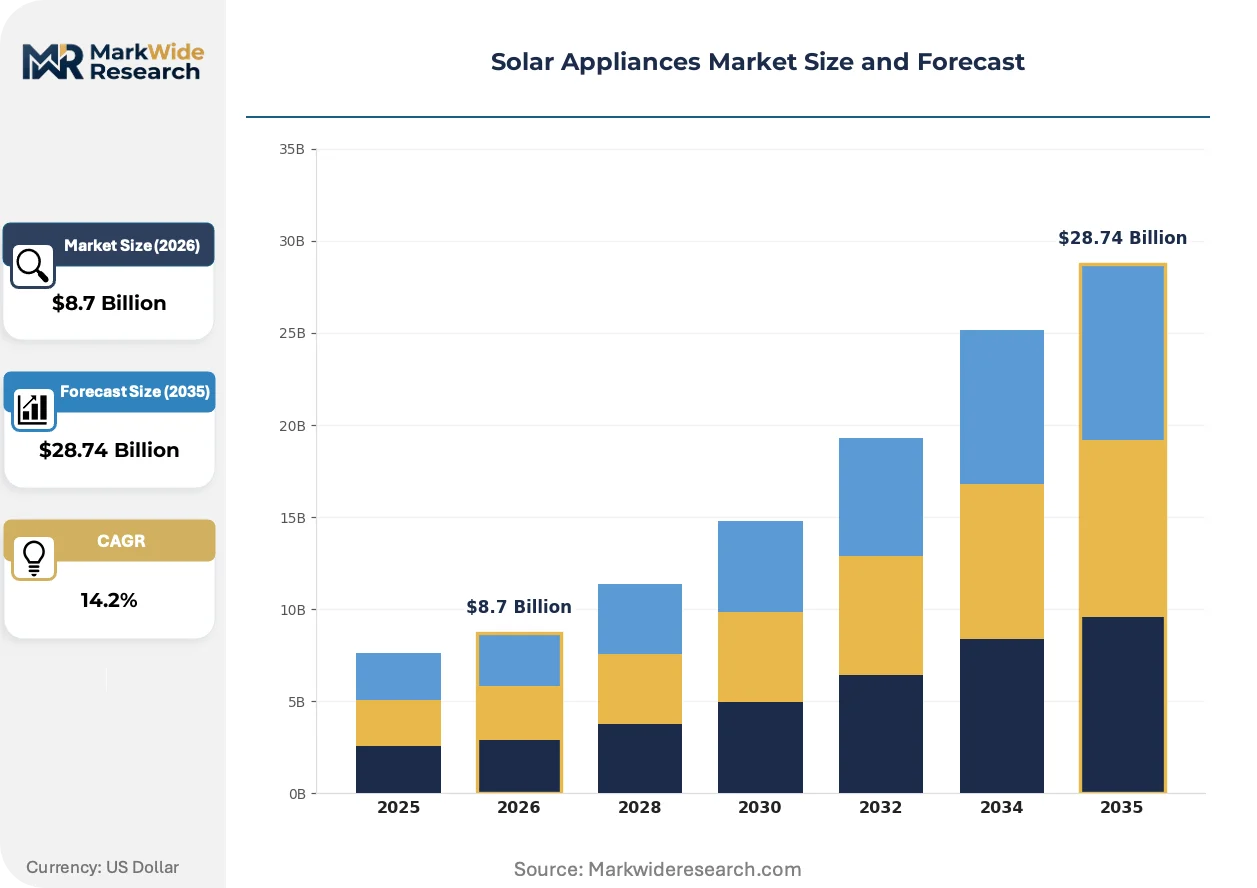
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Water Heaters, Solar Cookers, Solar Chargers, Solar Refrigerators End User: Residential, Commercial, Industrial, Agricultural Installation Type: On-grid, Off-grid, Hybrid, Portable Technology: Photovoltaic, Concentrated Solar Power, Thermal, Solar Thermal |
| Companies Covered | LONGi, Canadian Solar, JinkoSolar, Aiko Solar, Astronergy, JA Solar, Tongwei Solar, DAS Solar, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Appliances Market Evolving Landscape
Digital control layers and smart monitoring systems are embedding intelligence throughout solar appliance architectures, shifting competitive differentiation from hardware efficiency toward software-enabled optimization and predictive maintenance capabilities.
Perovskite-silicon tandem cell technology is virtualizing traditional module efficiency ceilings by stacking light-harvesting layers that capture broader spectrum segments. Commercial rooftop buyers in high-irradiance zones are piloting these configurations despite manufacturing scale constraints. The technology is virtualizing established cost-per-watt benchmarks and compressing payback periods for premium installation segments.
REACH chemical safety standards are restricting thermal absorber coating formulations across European markets, compelling manufacturers to reformulate selective surface materials and resubmit conformity assessments. The F-Gas Regulation is simultaneously phasing out high-global-warming-potential refrigerants in solar cooling appliances, accelerating hydrocarbon and CO2 system transitions. Solar thermal collector suppliers are responding by consolidating certification portfolios and relocating production to jurisdictions with aligned regulatory frameworks.
After-sales service unbundling is fragmenting traditional equipment-plus-installation bundles into componentized subscription tiers. Commercial buyers in California and Texas are separating monitoring, maintenance, and performance guarantees into distinct contractual vehicles. This pattern is most pronounced among agricultural end users seeking to align operational expenditures with seasonal cash flow cycles rather than absorbing capital-intensive upfront purchases.
Solar Appliances Market Segmentation
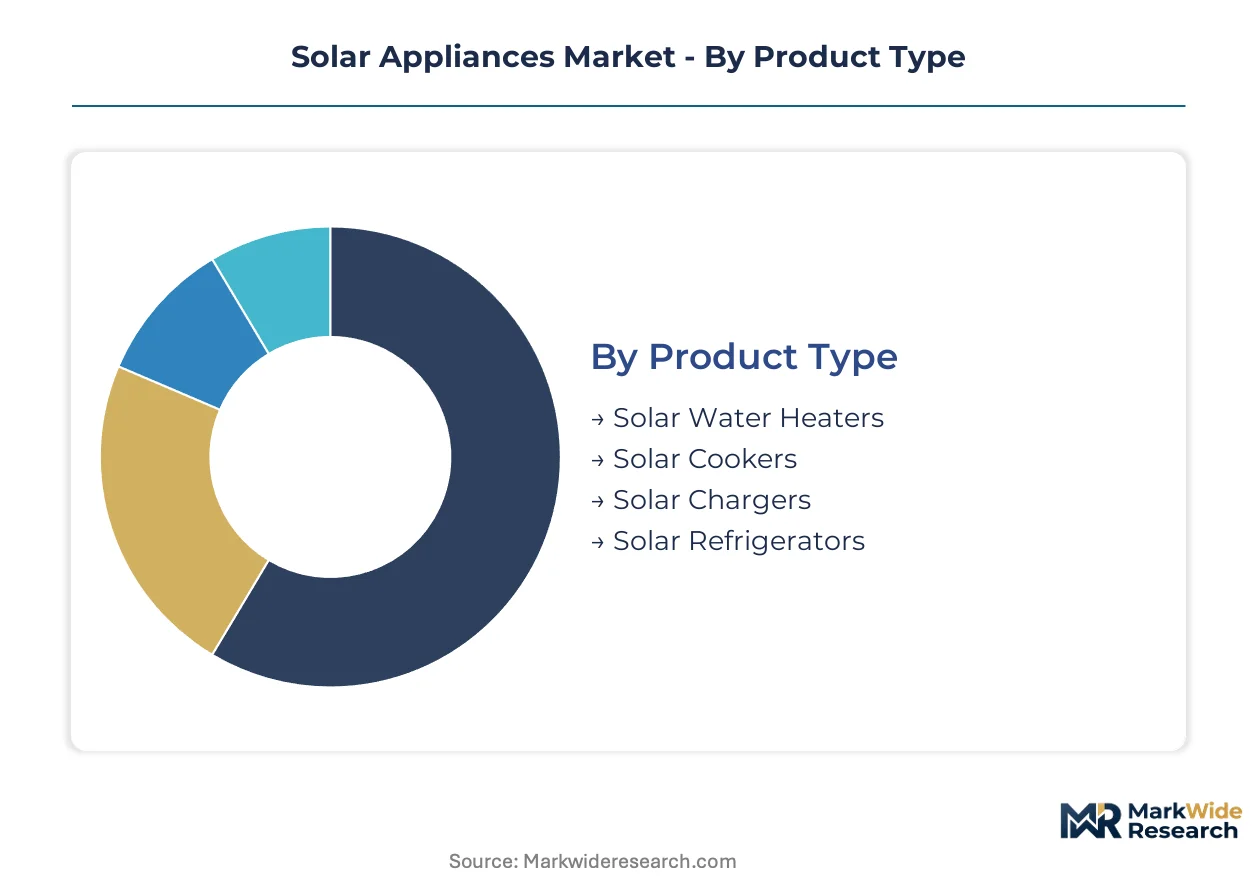
Solar appliances fragment across multiple technical and commercial dimensions that determine procurement patterns, financing structures, and after-sales service requirements. Understanding how product specifications align with end-use constraints and installation contexts enables vendors to calibrate pricing tiers and channel strategies.
Product Type:
Mature supply chains dominate thermal conversion products while photovoltaic-based categories are accelerating through pay-as-you-go financing innovations.
- Solar Water Heaters:Evacuated tube and flat-plate collectors integrate with existing plumbing infrastructure through mature distribution networks. Residential retrofits in India and commercial installations across EU member states concentrate procurement volumes, with BIS efficiency labeling and EU Green Deal standards tightening qualification requirements for suppliers.
- Solar Refrigerators:DC-powered compressor units paired with lithium-ion or lead-acid battery banks serve agricultural cooperatives and rural health clinics. Sub-Saharan electrification programs and microfinance partnerships in Kenya and Nigeria are unlocking penetration through asset-financing structures that bypass traditional credit barriers.
- Solar Cookers:Box and parabolic designs target off-grid households with minimal capital requirements.
- Solar Chargers:Portable photovoltaic units power mobile devices and small electronics for outdoor recreation and emergency preparedness segments.
Solar water heaters handle the majority of throughput; solar refrigerators are climbing the fastest on share.
End User:
Customer type determines financing vehicle preference, with agricultural buyers prioritizing seasonal cash flow alignment and commercial purchasers emphasizing performance guarantees.
- Agricultural:Farm-level solarization under India's KUSUM scheme channels procurement toward hybrid pumping and cold storage systems. Smallholder cooperatives in sub-Saharan Africa leverage pay-as-you-go structures for solar refrigerators and chargers, aligning operational expenditures with harvest cycles rather than absorbing capital-intensive upfront purchases.
- Commercial:Rooftop installations across California, Texas, and Florida concentrate volume procurement contracts with steady margin pools. Bifacial cell technology penetration is highest in this segment due to scale economies and performance guarantee requirements that justify premium module pricing.
- Residential:Grid-tied systems dominate in high-sunshine US states and EU markets with renewable portfolio standards.
- Industrial:Process heat applications and captive power generation drive concentrated solar power adoption.
Commercial buyers anchor procurement volumes; agricultural end users are expanding most quickly through dedicated subsidy mechanisms.
Installation Type:
Grid connectivity status shapes balance-of-system costs, battery sizing requirements, and regulatory compliance obligations across deployment contexts.
- Off-grid:Standalone photovoltaic or thermal systems with dedicated storage serve rural electrification gaps where grid extension is economically unviable. Microfinance and pay-as-you-go business models in sub-Saharan Africa and rural India are unlocking consumer access, though lead-acid substitution ceilings persist due to lithium-ion price premiums and temperature sensitivity constraints.
- Hybrid:Grid-tied systems with battery backup optimize self-consumption and provide resilience during outages. India's rooftop solar subsidies and KUSUM scheme are channeling agricultural procurement toward this configuration for pumping and cold storage applications.
- On-grid:Net-metered installations without storage dominate mature markets with reliable utility infrastructure.
- Portable:Mobile units serve recreational, emergency, and distributed energy access use cases with minimal installation requirements.
Off-grid systems are gaining share fastest through rural electrification programs; hybrid installations handle expanding throughput as grid resilience priorities intensify.
Technology:
Conversion mechanism determines efficiency ceilings, material inputs, and regulatory exposure across thermal and photovoltaic pathways.
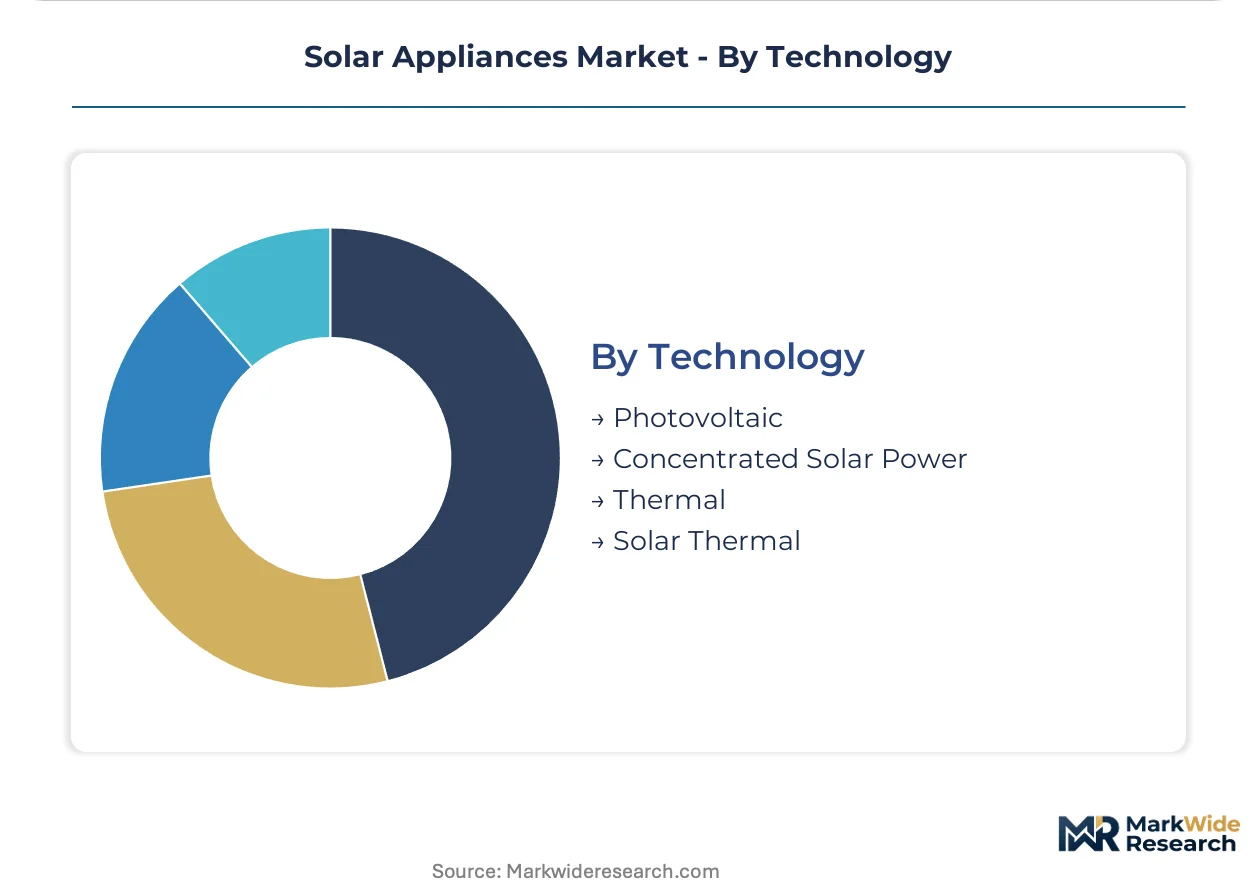
- Photovoltaic:Monocrystalline silicon panels rated between 300W and 600W dominate residential and commercial installations. Passivated contact cell architecture is compressing balance-of-system costs and forcing module layout redesigns, while perovskite-silicon tandem technology is virtualizing established efficiency benchmarks in pilot commercial rooftop deployments.
- Thermal:Flat-plate and evacuated tube collectors for water heating leverage mature supply chains and straightforward retrofit compatibility. REACH chemical safety standards and F-Gas Regulation constraints in EU markets are compelling reformulation of selective surface materials and refrigerant transitions.
- Concentrated Solar Power:Mirror-based thermal generation targets utility-scale and industrial process heat applications with high capital requirements.
- Solar Thermal:Direct thermal conversion for heating and cooling functions without photovoltaic intermediation.
Photovoltaic technology anchors installed capacity; thermal systems maintain stable share in water heating applications with established retrofit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial buyers in the United States, agricultural cooperatives in India, and residential retrofits across Germany concentrate procurement volumes. Sub-Saharan electrification programs and pay-as-you-go financing unlock rural demand clusters. Regulatory tightening in the EU and subsidy expansion in Asia shape supplier qualification requirements.
United States
Grid-tied residential installations dominate procurement across California, Texas, and Florida. The EPA Energy Star program and state-level renewable portfolio standards shape demand pull for rooftop systems. The California-Arizona solar corridor anchors distributed generation channel expansion.
India
Farm-level solarization under the KUSUM scheme channels hybrid installation procurement toward agricultural pumping and cold storage. BIS efficiency labeling mandates accelerate testing cycles for domestic solar water heater manufacturers. The Gujarat-Maharashtra industrial belt concentrates module assembly and thermal collector fabrication.
Germany
Commercial rooftop installations drive bifacial cell penetration through performance guarantee requirements. REACH chemical safety standards and the EU Green Deal tighten material specifications for imported solar thermal collectors. The Bavaria-Baden-Württemberg manufacturing cluster hosts selective surface coating reformulation activities.
Kenya
Agricultural cooperatives and rural health clinics procure DC-powered solar refrigerators through pay-as-you-go asset financing. Sub-Saharan electrification programs bypass traditional credit barriers for smallholder farmers. The Nairobi-Nakuru logistics corridor enables distributed generation vendor channel penetration.
China
Polysilicon-to-module vertical integration sustains cost leadership in photovoltaic water heater exports. Dual carbon goals and MIIT efficiency standards shape domestic procurement patterns. The Yangtze River Delta manufacturing base concentrates passivated contact cell architecture production.
Solar Appliances Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base fragments between scale-driven module manufacturers and regional installation service providers. Three archetypes dominate: vertically integrated polysilicon-to-module producers, distributed generation channel specialists, and thermal collector fabricators with selective surface expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure raw material access and installation technician networks.
Among Chinese vertically integrated producers, LONGi, JinkoSolar, and Trina Solar exemplify the scale-driven archetype that anchors global supply. These entities occupy positions spanning polysilicon production through module assembly, representing the cost-leadership tier that supplies photovoltaic components for water heating and distributed generation applications. Their geographic concentration in eastern China manufacturing clusters shapes supplier qualification criteria for export markets facing REACH and BIS regulatory constraints.
| Leading Market Players |
|---|
| LONGi |
| Canadian Solar |
| JinkoSolar |
| Aiko Solar |
| Astronergy |
| JA Solar |
| Tongwei Solar |
| DAS Solar |
| Trina Solar |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster anchors photovoltaic module production capacity, concentrating cost leadership among vertically integrated producers and compressing pricing power for downstream assemblers of solar water heaters and distributed generation systems.
Pricing Analysis
Cost-plus contracts with polysilicon indexation dominate procurement between module manufacturers and thermal collector fabricators, exposing water heater producers to raw material cost swings. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because of lithium-ion supply concentration in East Asia. Agricultural cooperatives exhibit highest price sensitivity due to seasonal cash flow constraints, while commercial buyers in California and Texas accept premium tiers for performance guarantees.
Supply Chain Analysis
Contract manufacturing concentrates among polysilicon-to-module integrators in eastern China, with LONGi, JinkoSolar, and Trina Solar holding captive wafer and cell capacity. The supply chain draws from polysilicon feedstock in Xinjiang and Inner Mongolia, lithium carbonate from South American salares, and aluminum framing from domestic Chinese smelters. Single-source vulnerability in East Asian battery cell production creates geopolitical exposure for storage-dependent appliance categories. Distribution runs through distributed generation channel partners across Southeast Asian markets and direct EPC relationships in EU member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities are expanding as pay-as-you-go financing unlocks rural consumer access, creating niche positions for asset-financing specialists alongside established module manufacturers.
For Market Incumbents: Build certification moats around BIS efficiency labeling and EU REACH compliance to exclude smaller thermal collector competitors. Deepen backward integration into polysilicon purification to defend margin position against raw material cost cycles. Anchor channel control through technician training networks in Southeast Asia where installation skill scarcity threatens service quality.
For New Entrants and Emerging Players: Build out pay-as-you-go asset financing partnerships targeting agricultural cooperatives in sub-Saharan Africa and rural India, the most penetrable segment given traditional credit barrier bypass. Pursue white-space positions in solar refrigerator after-sales service unbundling, separating monitoring and maintenance into subscription tiers. Deploy microfinance channel partnerships as the primary go-to-market angle rather than competing on module cost.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors distributed generation channel specialists with installation technician networks over pure-play module manufacturers facing commoditization pressure. Long-term viability over a multi-year horizon rests on controlling customer touchpoints rather than production scale. Acquisition targets should display circular economy service capabilities aligned with EU panel recycling directives. Watch perovskite-silicon tandem cell manufacturing scale-up as the inflection signal for premium module pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive feedstock supply insulates LONGi and Tongwei Solar from Xinjiang sourcing volatility and trade restrictions. |
| Pay-as-you-Go Channel Partnership | Asset-financing structures in Kenya and Nigeria bypass traditional credit barriers for agricultural solar refrigerator procurement. |
| Bifacial Cell Technology Licensing | Dual-sided photovoltaic penetration in commercial rooftop installations commands premium pricing through performance guarantees. |
| Circular Economy Service Buildout | EU extended producer responsibility frameworks create aftermarket revenue streams for panel recycling and material recovery. |
| Microfinance Alliance Formation | Partnerships with rural banking networks in India accelerate KUSUM scheme compliance and farm-level solarization uptake. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with distributed generation channel heads, agricultural cooperative procurement managers, EPC contractors, thermal collector fabrication engineers, and microfinance partnership directors. Secondary validation drew from BIS certification databases, EU ECHA REACH filings, SEC 10-K disclosures from listed module manufacturers, and IEA renewable energy deployment statistics. Bottom-up unit economics from pay-as-you-go financing structures were triangulated against top-down policy allocation targets under India's KUSUM scheme and EU Green Deal implementation frameworks.
Calibration against historical deployment trajectories in sub-Saharan electrification programs and German residential retrofit cycles anchored volume projections across the analysis window. Segmentation modeling incorporated product type, end-user archetype, installation configuration, and technology pathway dimensions. CAGRs were derived from slope analysis of policy-driven procurement waves and technology cost curves, with passivated contact cell adoption rates and lithium-ion substitution ceilings treated as scenario variables.
Stress conditions across polysilicon price cycles, East Asian battery supply disruptions, and EU chemical safety regulatory tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy continuity and financing innovation penetration. Quarterly review of BIS testing cycle backlogs and REACH conformity assessment timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Photovoltaic Solar Kits Market