
 France Distributed Solar Power Generation Market | 2026-2036
France Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
France Distributed Solar Power Generation Market Foresight
Subscription-based energy management software is restructuring how distributed solar value gets captured in France. Engie SA leverages its utility-scale data infrastructure to anchor remote monitoring and predictive maintenance contracts for commercial portfolios. TotalEnergies SE differentiates through integrated battery-solar offerings that extend customer lock-in beyond hardware installation. Neoen specializes in hybrid system configurations that combine grid-tied generation with storage, positioning the firm for France's evolving capacity market rules.
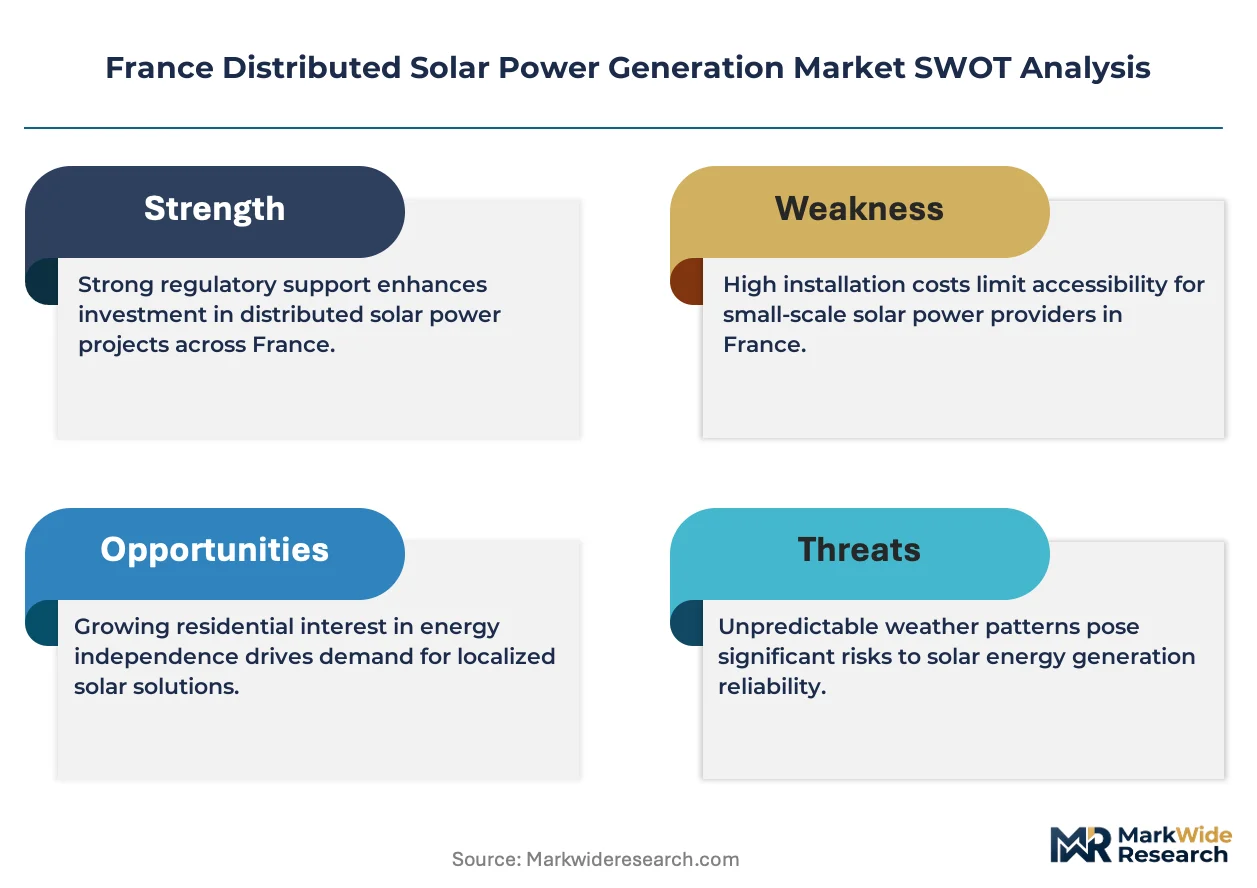
France distributed solar power generation encompasses photovoltaic systems installed at or near the point of consumption, typically ranging from residential rooftop arrays under 3 kW to commercial ground-mounted installations up to 30 MW, converting sunlight into direct current electricity through silicon-based cells before inversion to grid-compatible alternating current. These systems serve to reduce transmission losses, lower end-user electricity costs, and provide grid stabilization services through localized generation. Rooftop installations dominate the current installed base due to favorable building stock and simplified permitting under France's self-consumption framework, while floating solar emerges as a structural growth vector given land-use constraints and the country's extensive reservoir network. Agricultural enterprises represent an expanding end-user segment as farmers deploy ground-mounted and carport systems to offset irrigation and cold-chain energy costs, with hybrid solar systems capturing margin pools through combined generation-storage revenue stacking.
France's energy regulator CRE sets feed-in tariff structures and self-consumption premiums that directly shape project economics for residential and commercial installers. EU Green Deal targets and France's National Low Carbon Strategy mandate building-integrated solar on new commercial construction, tightening product standards through CE marking and harmonized IEC certification requirements. ANSM and CNIL oversight of smart inverter data protocols adds compliance layers for software-connected systems. Stakeholders must monitor CRE's evolving capacity tariff design and the pace of distribution network reinforcement investments by Enedis, as these factors determine which installation types and applications remain economically viable across France's regional grid constraints.
Market Dynamics
France's distributed solar sector faces a structural squeeze between accelerating permitting reforms and distribution grid saturation in high-irradiance zones, forcing developers toward hybrid storage configurations and network-constrained regions.
Growth Catalysts
- EU Green Deal building mandates:Tightened energy performance standards for new commercial construction create embedded demand for rooftop photovoltaic systems across French urban centers.
- Agricultural self-consumption:French farms deploy ground-mounted arrays to offset irrigation pump loads and cold-chain refrigeration, with simplified interconnection rules under CRE's agricultural tariff framework accelerating deployment timelines.
- Hybrid system economics:Co-located battery storage enables revenue stacking through capacity market participation and peak-shaving services, improving project returns in grid-constrained departments.
Market Restraints
- Polysilicon supply concentration:Dependence on Asian ingot and wafer suppliers exposes French installers to input cost volatility and logistics bottlenecks.
- Distribution network reinforcement gaps:Enedis grid upgrade timelines lag behind connection requests in Occitanie and Provence-Alpes-Côte d'Azur, forcing project delays or curtailment risk.
- Land-use competition:Agricultural zoning restrictions and reservoir conservation priorities limit available sites for ground-mounted and floating solar expansion.
Strategic Opportunities
- Nouvelle-Aquitaine reservoir network:Floating photovoltaic installations on hydroelectric lakes and irrigation basins unlock capacity without land-use conflicts.
- Smart inverter data monetization:ANSM and CNIL-compliant aggregation of generation and consumption patterns enables grid services contracts and demand-response revenue streams.
- Building-integrated photovoltaics:France's National Low Carbon Strategy mandates for new construction create a captive market for façade-integrated and solar tile products.
Industry Challenges
- Electrical engineering talent scarcity:Shortages of certified grid interconnection specialists and battery system integrators constrain installation throughput.
- CE marking harmonization delays:Evolving IEC certification requirements for hybrid inverters and storage modules extend product approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Distributed Solar Power Generation Market |
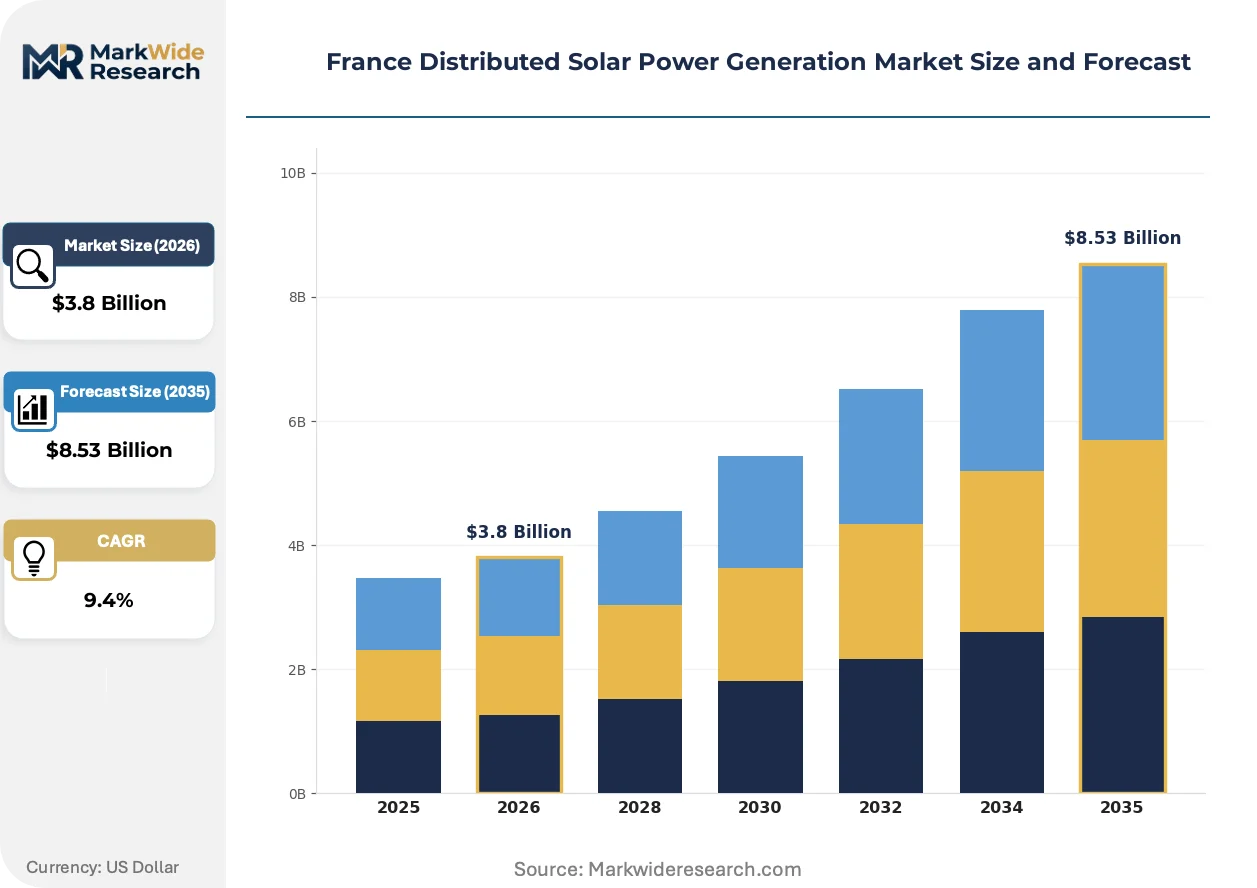
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Battery Storage, Solar Trackers, Charge Controllers End User: Residential Customers, Commercial Establishments, Agricultural Enterprises, Educational Institutions, Hospitality Sector Installation Type: Rooftop, Ground-Mounted, Building-Integrated, Floating Solar, Carport Systems Application: Grid-Tied Systems, Off-Grid Systems, Hybrid Solar Systems, Microgrids, Energy Storage Integration |
| Companies Covered | Neoen, SunPower Corporation, Engie SA, Enel Green Power, Akuo Energy, TotalEnergies SE, Voltalia, Urbasolar, EDF Renewables, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Distributed Solar Power Generation Market Shifts & Advancements
Technology convergence and regulatory tightening are compressing traditional installation models while opening margin pools in software-layer services and hybrid system configurations across French regions.
Bifacial photovoltaic modules with dual-sided light capture are rewriting energy yield calculations for ground-mounted and floating installations. Agricultural and commercial developers in Nouvelle-Aquitaine and Occitanie are specifying these panels for elevated tracking systems, squeezing project payback periods and enabling smaller footprints per megawatt installed.
France's energy regulator CRE is recalibrating self-consumption premium structures and capacity tariff designs to reward grid-flexible assets. This policy evolution favors hybrid solar-storage configurations over pure generation assets, pushing developers toward battery integration and remote monitoring capabilities to maintain economic viability under evolving compensation frameworks.
French agricultural enterprises are consolidating procurement through cooperative purchasing structures and long-term energy service contracts rather than direct equipment ownership. This shift displaces traditional equipment vendor relationships with integrated providers offering generation, storage, and optimization software, with the transformation most visible in the irrigation-intensive sectors of Provence-Alpes-Côte d'Azur and Occitanie.
France Distributed Solar Power Generation Market Segmentation
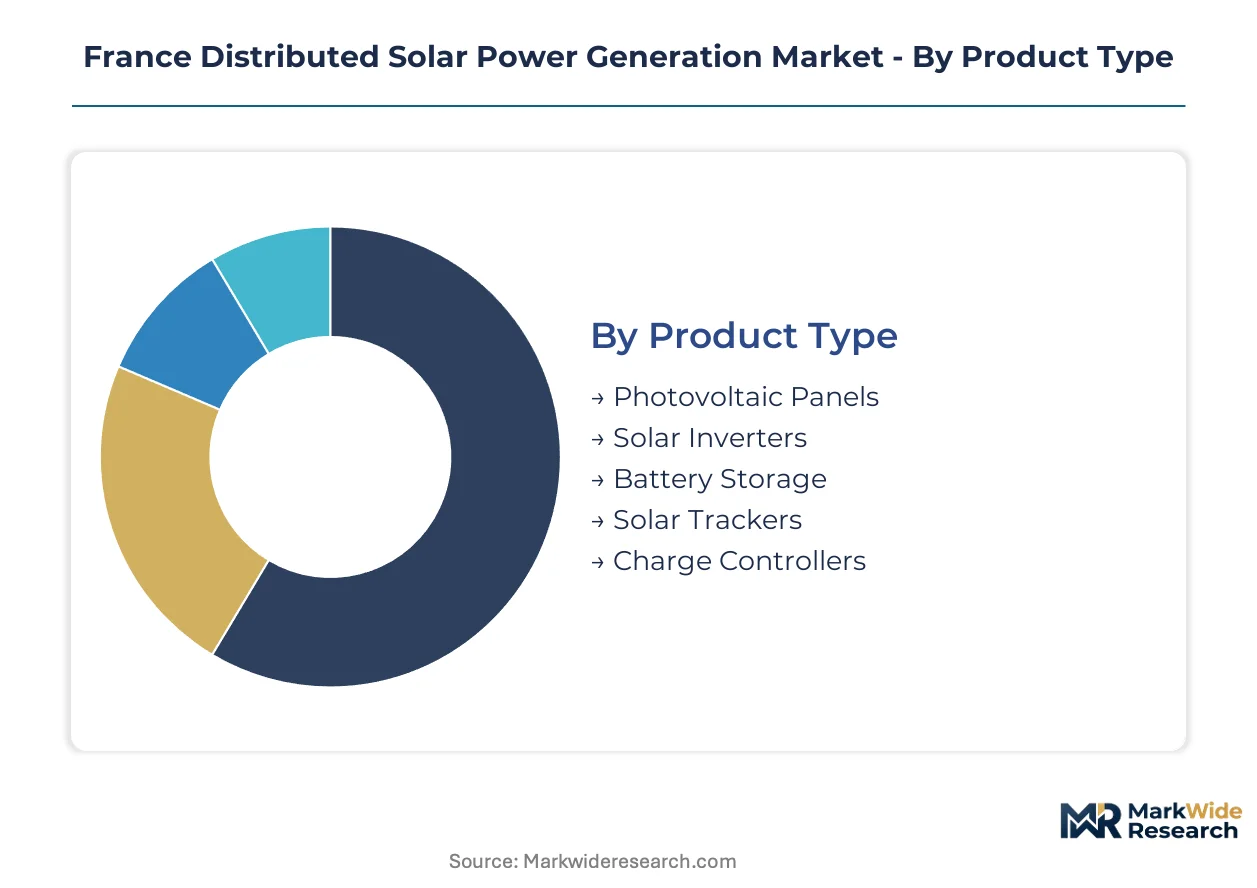
Segmentation reveals how hardware specifications, installation constraints, and end-use economics fragment France's distributed solar landscape. Equipment choices and deployment configurations diverge sharply across regulatory zones and customer types.
Product Type:
Equipment replacement cycles and technology upgrades drive purchasing patterns across French installation portfolios, with inverter and storage upgrades outpacing panel swaps.
- Photovoltaic Panels:Silicon-based modules with monocrystalline cells dominate French rooftops and ground arrays. Demand clusters in Occitanie and Provence-Alpes-Côte d'Azur where elevated irradiance justifies premium efficiency specifications.
- Solar Inverters:String inverters and power optimizers convert DC generation to grid-compatible AC output. CRE's evolving smart inverter mandates accelerate replacement of legacy units lacking remote monitoring capabilities.
- Battery Storage:Lithium-ion systems enable self-consumption optimization and capacity market participation.
- Solar Trackers:Single-axis and dual-axis mounting systems follow sun paths to boost yield.
- Charge Controllers:MPPT and PWM regulators manage battery charging in off-grid configurations.
Photovoltaic panels sit at the top of the volume ranking, with battery storage climbing the fastest.
End User:
Customer procurement maturity and financing access create distinct margin tiers across French distributed solar demand.
- Residential Customers:Households deploy sub-3 kW rooftop systems under France's self-consumption tariff framework. Simplified permitting in rural departments accelerates deployment timelines.
- Commercial Establishments:Retail and office buildings specify 30-250 kW rooftop arrays with remote monitoring. EU Green Deal building codes mandate solar-ready construction in new commercial stock.
- Agricultural Enterprises:Farmers deploy ground-mounted and carport systems to offset irrigation and refrigeration loads.
- Educational Institutions:Schools and universities integrate rooftop arrays with curriculum-linked energy education programs.
- Hospitality Sector:Hotels and resorts pursue visible sustainability credentials through building-integrated and carport installations.
Commercial establishments anchor current revenue concentration, with agricultural enterprises expanding most quickly.
Installation Type:
Site constraints and land-use regulations push French developers toward specialized mounting configurations that minimize permitting friction.
- Rooftop:Building-mounted arrays leverage France's extensive commercial and residential stock. Simplified interconnection rules under CRE's self-consumption framework sustain deployment velocity in urban centers.
- Ground-Mounted:Elevated tracking systems on agricultural land maximize yield per hectare. Zoning restrictions in high-irradiance departments constrain available sites.
- Building-Integrated:Façade-integrated and solar tile products serve new construction mandates.
- Floating Solar:Reservoir-mounted arrays avoid land-use conflicts on hydroelectric lakes and irrigation basins.
- Carport Systems:Parking canopy installations serve commercial and hospitality customers seeking dual-use infrastructure.
Rooftop deployment holds the largest installed base, with floating solar gaining share fastest.
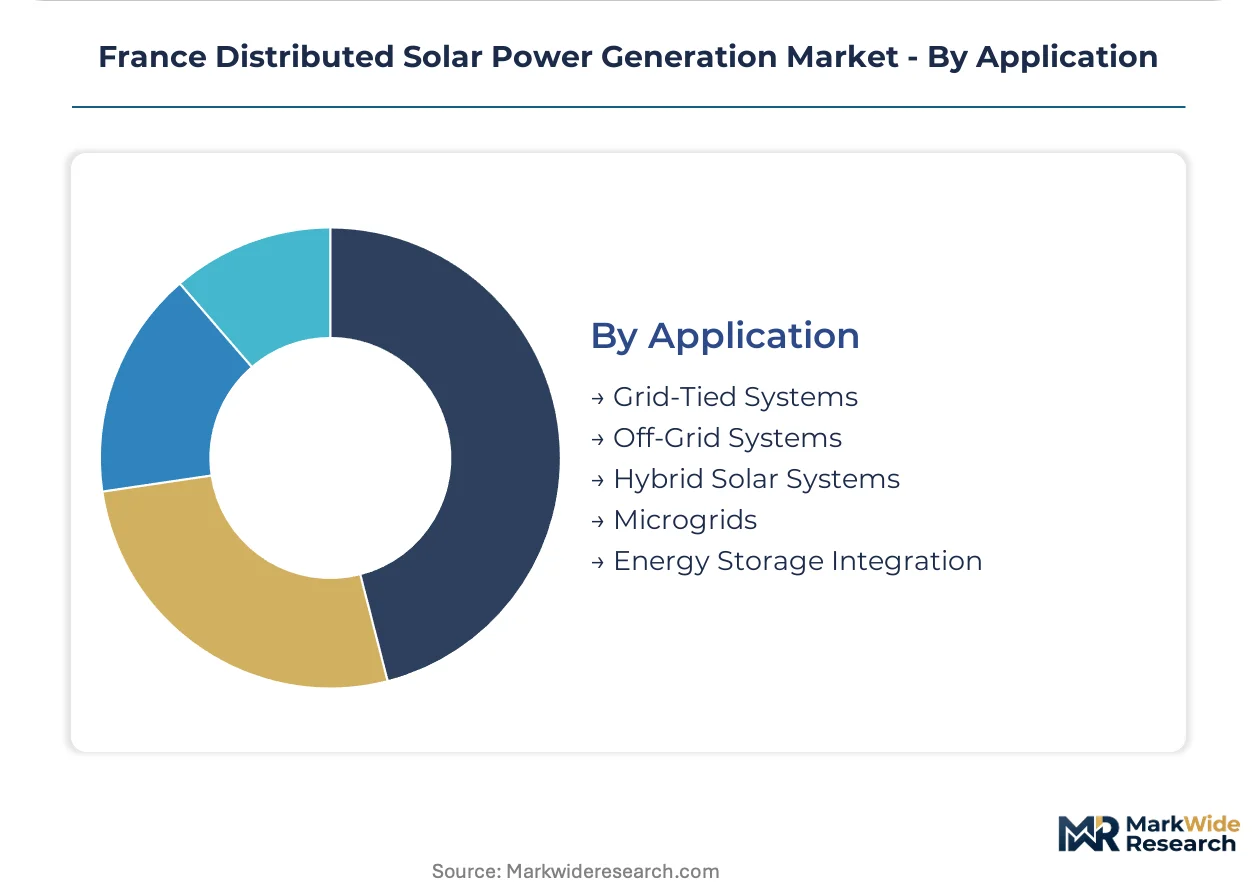
Application:
Grid interconnection architecture determines revenue stacking potential and regulatory compliance burdens for French system operators.
- Grid-Tied Systems:Net-metered and feed-in-tariff configurations dominate French distributed solar. CRE tariff recalibrations are compressing pure export economics.
- Off-Grid Systems:Standalone configurations with battery backup serve remote agricultural and mountain installations. Limited addressable market constrains segment scale.
- Hybrid Solar Systems:Co-located generation and storage enable capacity market participation and peak-shaving services.
- Microgrids:Campus-scale isolated networks serve industrial parks and institutional clusters.
- Energy Storage Integration:Battery-coupled systems optimize self-consumption ratios and grid service revenues.
Grid-tied systems dominate current deployment, with hybrid solar systems showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where French developers concentrate distributed solar deployment, with sub-regional variation in CRE tariff implementation and Enedis grid reinforcement timelines creating measurable cost-of-compliance gaps across metropolitan France.
Île-de-France
Building-integrated mandates under the National Low Carbon Strategy drive rooftop adoption across Parisian commercial stock. CRE's urban self-consumption premium structures accelerate permitting in dense arrondissements. La Défense business cluster anchors corporate procurement of remote-monitored arrays with battery coupling.
Occitanie
Agricultural enterprises deploy ground-mounted tracking systems to offset irrigation pump loads across Languedoc vineyards. Simplified interconnection rules under CRE's agricultural tariff framework compress deployment timelines. Montpellier's tech corridor incubates smart inverter startups targeting data-monetization revenue streams.
Provence-Alpes-Côte d'Azur
High irradiance levels and hospitality sector demand concentrate carport and rooftop installations along the Côte d'Azur. EU Green Deal building codes tighten energy performance standards for new hotel construction. Nice's airport zone anchors commercial-scale hybrid systems with capacity market participation.
Nouvelle-Aquitaine
Floating solar emerges as a structural growth vector on hydroelectric reservoirs and irrigation basins. Land-use constraints and reservoir conservation priorities limit ground-mounted expansion. Bordeaux's wine cooperatives consolidate procurement through long-term energy service contracts rather than direct ownership.
Auvergne-Rhône-Alpes
Industrial parks and manufacturing clusters drive commercial rooftop demand around Lyon and Grenoble. ANSM oversight of smart inverter data protocols adds compliance layers for software-connected systems. The Isère valley anchors microgrid deployments serving campus-scale isolated networks.
France Distributed Solar Power Generation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated energy majors commanding commercial portfolios while regional installers retain residential penetration. The vendor base concentrates around three strategic archetypes: utility-backed developers leveraging balance-sheet scale, pure-play solar specialists pursuing technology differentiation, and agricultural cooperatives capturing rural self-consumption demand. M&A activity targets hybrid system integration capabilities, while strategic partnerships with battery manufacturers reshape competitive positioning.
Among France-based integrated developers, Engie SA, TotalEnergies SE, and Neoen exemplify distinct strategic postures within the competitive set. Engie SA occupies a position anchored in utility-scale data infrastructure extended to distributed portfolios. TotalEnergies SE represents the integrated energy major archetype with combined generation-storage offerings. Neoen sits within the specialist tier focused on hybrid configurations aligned with evolving capacity market rules.
| Leading Market Players |
|---|
| Neoen |
| SunPower Corporation |
| Engie SA |
| Enel Green Power |
| Akuo Energy |
| TotalEnergies SE |
| Voltalia |
| Urbasolar |
| EDF Renewables |
| Others |
Supply & Pricing Matrix
Polysilicon spot price volatility cascades through France's distributed solar supply chain, compressing margins for installers while creating tiered procurement economics that separate integrated energy majors from regional specialists dependent on module spot markets.
Pricing Analysis
Distributor margins on photovoltaic modules stratify across premium, standard, and economy tiers based on cell efficiency ratings and IEC certification completeness. Price differentiation hinges on volume procurement scale and after-sales service bundling, with agricultural cooperatives exhibiting highest price sensitivity due to thin operating margins on farm operations. Cost compression in the residential tier is intensifying as Enedis interconnection queues lengthen and installers absorb carrying costs.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Rotterdam and Hamburg entry points, with regional staging centers in Lyon and Toulouse feeding last-mile logistics to Occitanie and Provence-Alpes-Côte d'Azur deployment sites. Module supply concentrates in China, Vietnam, and Malaysia, drawing from polysilicon feedstock anchored in Xinjiang and Inner Mongolia. Logistics chokepoints through Suez and Mediterranean port congestion constitute the dominant supply chain risk, with inventory-holding strategies displacing just-in-time procurement among French EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's distributed solar market offers margin expansion through bifacial module adoption and software-layer service attach, as hardware commoditization pushes value capture toward predictive maintenance and capacity market optimization.
For Market Incumbents: Anchor hybrid system integration capabilities through captive battery supply agreements or strategic partnerships with lithium-ion cell manufacturers. Defend against pure-play software entrants by deepening remote monitoring data moats and securing long-term energy service contracts with agricultural cooperatives in Nouvelle-Aquitaine and Occitanie.
For New Entrants and Emerging Players: Launch via floating solar specialization targeting reservoir networks in Nouvelle-Aquitaine, where land-use constraints limit incumbent ground-mounted expansion. Penetrate the hospitality sector along Provence-Alpes-Côte d'Azur through building-integrated photovoltaic offerings that satisfy EU Green Deal construction mandates while bypassing saturated rooftop competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale developers holding grid interconnection queue positions in Enedis-constrained departments. Prioritize acquisition targets with hybrid project pipelines and ANSM-compliant smart inverter data platforms. Watch CRE capacity tariff recalibrations as the inflection signal for storage-attached project economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration | Co-located storage enables capacity market participation under evolving CRE compensation frameworks. |
| Floating Solar Development | Reservoir-mounted arrays circumvent agricultural zoning restrictions in land-constrained departments. |
| Smart Inverter Data Monetization | ANSM and CNIL-compliant aggregation unlocks grid services contracts with Enedis. |
| Agricultural Energy Service Contracts | Long-term optimization agreements displace direct equipment sales in irrigation-intensive regions. |
| Backward Integration into Battery Supply | Captive lithium-ion sourcing insulates project economics from cell price volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IPP project developers, EPC contractors, Enedis grid planning officers, and CRE regulatory affairs specialists with secondary validation against EIA data, IEA renewable energy reports, FERC distributed generation filings, and European project development databases. Bottom-up installation forecasts triangulated against top-down capacity targets under France's National Low Carbon Strategy.
Segment-weighting approaches modeled photovoltaic panels, inverters, and battery storage as distinct hardware categories, crossed with installation type, end-user archetype, and regional grid constraint severity across the projection horizon. CAGRs derived from unit economics modeling of self-consumption premiums, capacity tariff structures, and hybrid system revenue stacking potential, with sensitivity analysis on polysilicon input costs and Enedis reinforcement timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal implementation or prolonged polysilicon supply disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar PV Panels Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Polycrystalline Solar Cell Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Polycrystalline Solar Panel Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Austria Solar Energy Market