
 Solar Crimp Set Market | 2026-2036
Solar Crimp Set Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Crimp Set Market Insights
Preventive maintenance subscription packages for crimp tool calibration and die replacement are repositioning vendor-customer relationships toward lifecycle revenue models. TE Connectivity leverages its broad connector portfolio to bundle crimp sets with terminal blocks for utility-scale installations. Phoenix Contact anchors its competitive stance through IEC-compliant testing protocols that reduce field failure rates. Weidmüller differentiates by specializing in rail-compatible crimping systems for solar inverter integration.
A solar crimp set comprises precision-engineered dies, handles or powered actuators, and alignment fixtures designed to cold-form metallic contacts onto photovoltaic cables without solder, typically achieving pull-force ratings exceeding 50 newtons per crimp. The equipment ensures electrical continuity across MC4-compatible connectors that carry direct current from panel strings to inverters in rooftop and ground-mount arrays. Handheld crimp tools dominate current revenue as installer fleets prioritize field portability over cycle speed. Automatic crimping machines represent the fastest-expanding product category as panel manufacturers automate junction box assembly lines to match gigawatt-scale output targets. Copper material grades command premium positioning due to superior conductivity and corrosion resistance in humid climates.
FCC equipment authorization rules govern powered crimping tools deployed in North American solar farms, while REACH compliance restricts hazardous substances in European-sold die coatings and handle polymers. India's BIS certification mandates torque-repeatability testing for imported crimp sets used in government-subsidized photovoltaic programs. Stakeholders must monitor evolving connector interoperability standards between regional module manufacturers and balance-of-system suppliers to avoid stranded tooling investments as DC cable architectures shift.
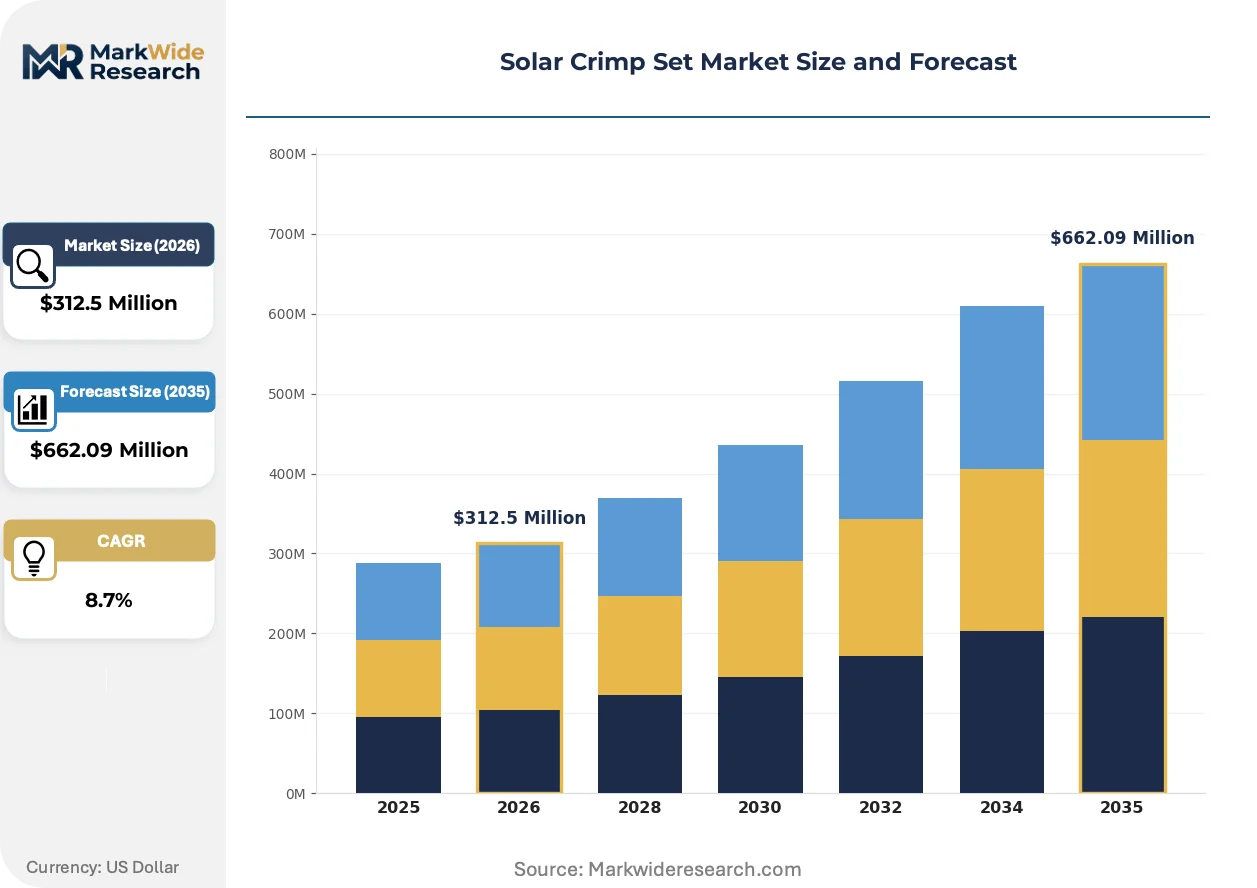
Market Dynamics
Utility-scale solar farm developers are consolidating procurement around certified crimp sets as gigawatt-scale project pipelines force standardization of connector reliability protocols across balance-of-system installations.
Growth Catalysts
- IEC 61215 Testing Mandates:Tightened connector reliability requirements across major solar markets are forcing developers to specify certified crimp tooling, expanding addressable demand for precision-engineered die sets.
- Domestic PV Manufacturing Surge:China, India, and Germany are accelerating photovoltaic production capacity, creating concentrated demand for automated crimping systems in junction box assembly lines.
- Copper Material Superiority:Premium copper grades with enhanced conductivity and corrosion resistance are commanding specification preference in humid climate installations across Southeast Asian and Latin American solar farms.
Market Restraints
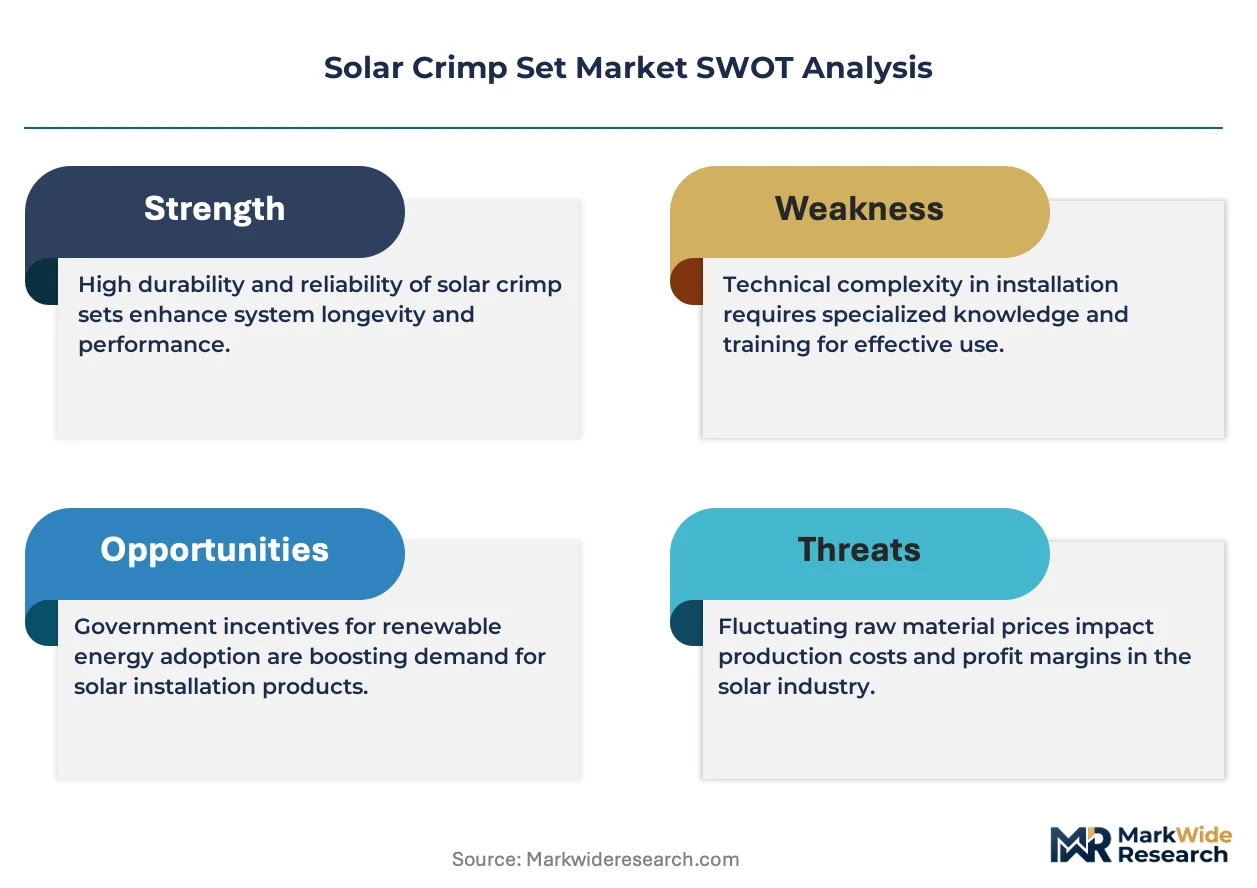
- Raw Material Volatility:Copper price swings and die steel supply tightness are compressing margin structures for mid-tier crimp set manufacturers without captive metallurgical sourcing.
- Geographic Supply Concentration:Precision die manufacturing clusters in Germany and Japan create vulnerability to regional logistics disruptions and currency fluctuation exposure.
- Interoperability Friction:Divergent regional connector architectures between Chinese module producers and European balance-of-system suppliers risk stranding tooling investments as DC cable standards evolve.
Strategic Opportunities
- Preventive Maintenance Subscriptions:Lifecycle revenue models repositioning vendor relationships through calibration and die replacement packages are capturing recurring revenue streams from installer fleets.
- Automation Convergence:Integration of machine vision alignment with pneumatic crimp actuators is opening specification pathways in panel manufacturer junction box assembly automation.
- Rail-Compatible System Demand:Solar inverter integration requirements are creating white space for crimping systems engineered to DIN rail mounting standards in commercial rooftop installations.
Industry Challenges
- Calibration Skill Scarcity:Field technician shortages capable of executing torque-repeatability validation are extending commissioning timelines for utility-scale solar farm crimping operations.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with India's BIS torque standards, FCC equipment authorization for powered tools, and REACH substance restrictions is elongating product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Crimp Set Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Crimp Tools, Automatic Crimping Machines, Pneumatic Crimpers, Crimping Die Sets Material: Aluminum, Copper, Steel, Alloy End User: Installers, Manufacturers, OEMs, Maintenance Services Industry Vertical: Renewable Energy, Electrical, Construction, Telecommunications |
| Companies Covered | TE Connectivity, Phoenix Contact, Amphenol, Molex, Foxconn Interconnect Technology, Hirose Electric, VIOX Electric, Weidmüller, ECO-WORTHY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Crimp Set Market Trends and Innovations
Crimp tooling architectures are converging around predictive maintenance capabilities and automated quality verification, compressing the gap between handheld field portability and production-line throughput.
Battery-powered crimp actuators with integrated pull-force sensors are consolidating field installation workflows by eliminating pneumatic hose dependencies while capturing crimp quality data for warranty documentation. Rooftop installer fleets in Australia and the United States are adopting these units to reduce setup time on distributed commercial projects. The technology is consolidating mid-tier pneumatic tool demand into single-platform specifications that span residential to light-commercial applications.
REACH compliance deadlines for hazardous substance restrictions in die coatings and handle polymers are forcing European vendors to reformulate product lines ahead of enforcement windows. Manufacturers serving Germany and France are accelerating substitution of legacy chrome plating with tungsten-carbide surface treatments. Solar farm EPC contractors in the Netherlands and Denmark are now specifying REACH-compliant tooling to preempt project finance due-diligence scrutiny.
Service unbundling is separating crimp tool hardware from calibration and die replacement programs, with installer cooperatives in India and Brazil pooling maintenance subscriptions to reduce per-unit ownership costs. Distributor channels are ceding recurring revenue to direct vendor relationships as procurement teams prioritize uptime guarantees over upfront equipment pricing. This behavioral shift is most visible among government-subsidized photovoltaic programs where BIS certification mandates create vendor lock-in effects.
Solar Crimp Set Market Segmentation
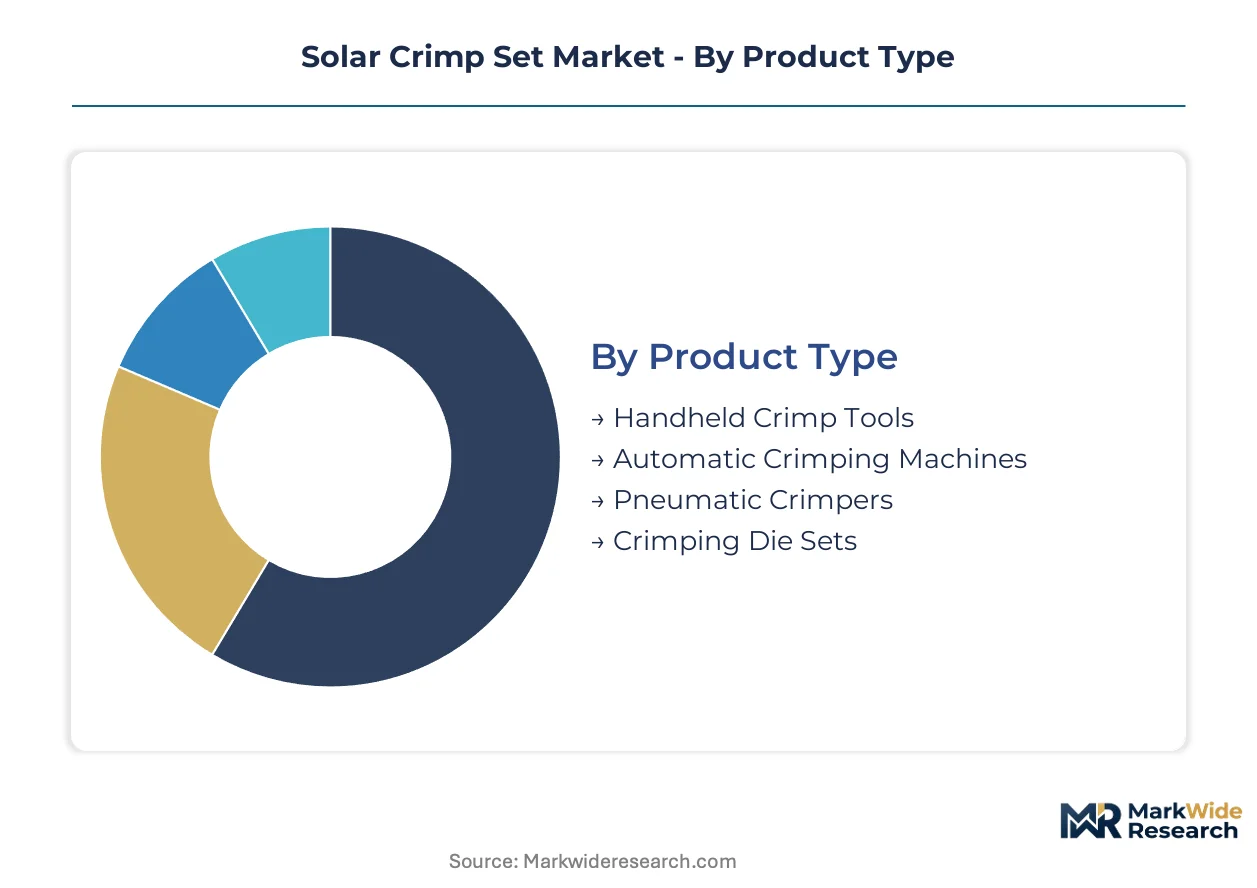
Solar crimp set segmentation reveals distinct procurement patterns between field installation fleets and automated production environments. Equipment specifications diverge sharply across material grades, with conductivity requirements and climate exposure driving die selection. Understanding these segment boundaries enables vendors to align product development with the divergent reliability protocols of utility-scale developers versus distributed rooftop contractors.
Product Type:
Integration depth separates portable field tools from fixed production-line systems, with handheld units serving standalone installation workflows while automated machines embed directly into junction box assembly lines.
- Handheld Crimp Tools:Manual or battery-powered actuators with interchangeable die sets achieve 50+ newton pull-force ratings for MC4-compatible connectors. Installer fleets in Australia and the United States prioritize these units for distributed commercial rooftop projects where setup speed outweighs cycle throughput. Field portability dominates current procurement volumes.
- Automatic Crimping Machines:Pneumatic or servo-driven systems with machine vision alignment integrate into panel manufacturer production lines. China's accelerating photovoltaic manufacturing capacity is concentrating demand here as gigawatt-scale output targets force automation of junction box assembly operations. These systems are expanding most quickly.
- Pneumatic Crimpers:Shop-floor actuators requiring compressed air infrastructure serve mid-volume electrical contractors with recurring solar installation contracts.
- Crimping Die Sets:Precision-engineered cold-forming inserts sold separately enable tool fleet refurbishment and connector standardization across mixed-vendor installations.
Handheld crimp tools lead volumes today; automatic crimping machines are gaining share fastest.
Material:
Cost tier stratification positions copper at premium specification levels while aluminum and steel alloys capture price-sensitive procurement in emerging solar markets.
- Copper:High-conductivity grades with enhanced corrosion resistance command specification preference for humid climate installations across Southeast Asian and Latin American solar farms. Premium positioning reflects IEC 61215 reliability mandates for connector longevity in salt-air environments.
- Aluminum:Lightweight, cost-optimized material serves budget-constrained distributed generation projects where conductivity requirements permit higher resistance tolerances. India's government-subsidized photovoltaic programs specify aluminum dies for rural electrification deployments.
- Steel:Hardened die substrates provide wear resistance for high-cycle production environments in Chinese panel manufacturing facilities.
- Alloy:Engineered material blends balance conductivity and mechanical durability for specialized crimp geometries in European utility-scale installations.
Copper dominates premium specifications; aluminum shows steepest volume expansion in emerging markets.
End User:
Customer type segmentation distinguishes fleet-based installation operators from captive manufacturing operations with divergent procurement cadences and lifecycle service expectations.
- Installers:Distributed contractor fleets prioritize handheld tool portability and preventive maintenance subscriptions to minimize field downtime. Australia's rooftop solar cooperatives pool calibration programs to reduce per-unit ownership costs.
- Manufacturers:Panel producers with in-house junction box assembly lines specify automated crimping systems with machine vision quality verification. Germany's photovoltaic production expansion is concentrating demand here.
- OEMs:Balance-of-system suppliers bundle crimp tooling with connector kits for utility-scale EPC contractors seeking single-source procurement efficiency.
- Maintenance Services:Post-commissioning operators require portable recalibration equipment and die replacement inventories for warranty-period connector integrity verification.
Installers represent the largest addressable base; manufacturers show fastest specification growth.
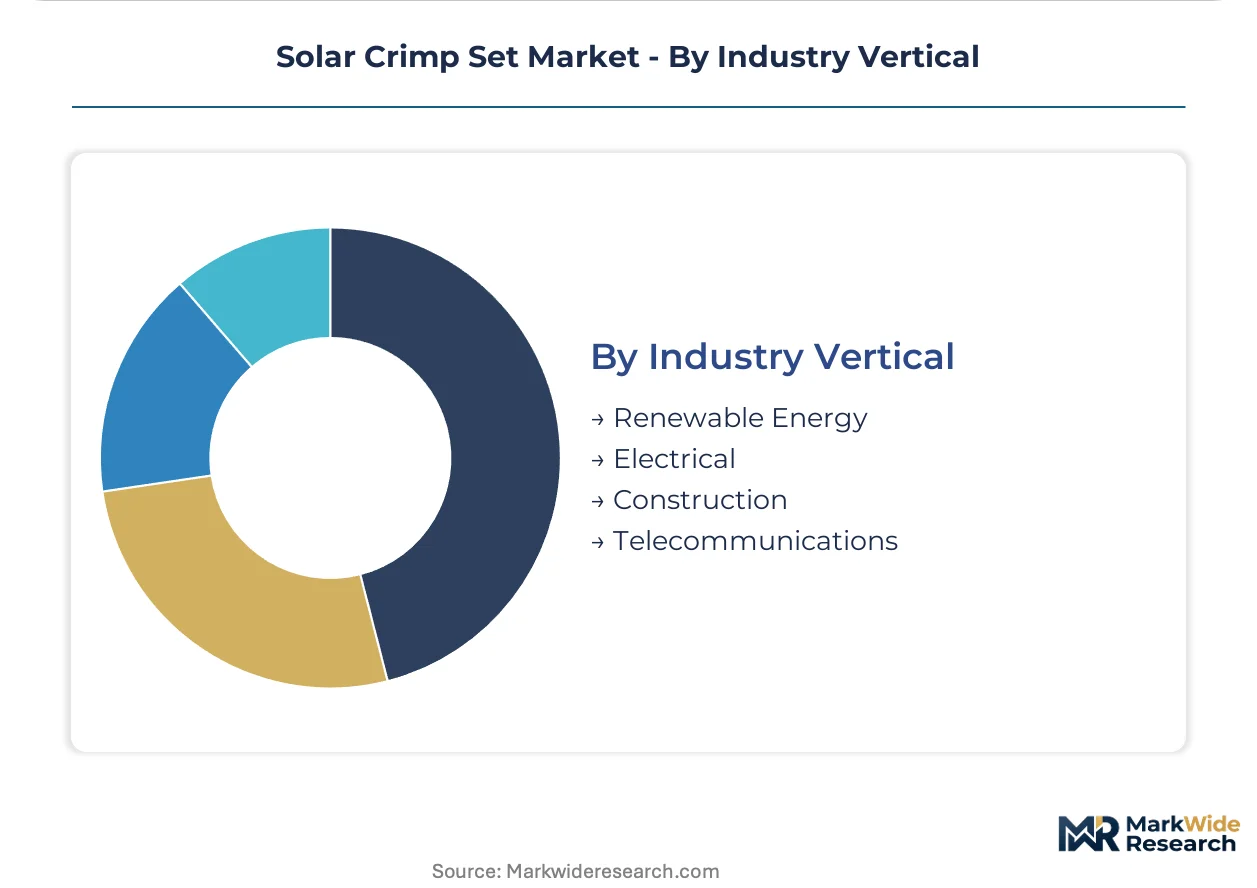
Industry Vertical:
Application maturity varies dramatically, with renewable energy driving specialized connector reliability requirements that electrical and construction verticals adopt secondarily.
- Renewable Energy:Photovoltaic-specific crimp sets must achieve IEC 61215 and UL 1703 certification for DC connector integrity across rooftop and ground-mount arrays. Utility-scale solar farm developers in Germany and India mandate these standards for project finance eligibility.
- Electrical:Generalist contractors serving mixed industrial and commercial portfolios specify multi-application crimp tools with interchangeable die systems spanning solar and conventional electrical termination.
- Construction:Large-scale EPC firms integrate crimp tooling procurement into balance-of-system packages for turnkey solar farm delivery, prioritizing vendor consolidation over specialized performance.
- Telecommunications:Secondary demand source repurposes precision crimp technology for fiber and coaxial termination, with minimal overlap to solar-specific MC4 connector requirements.
Renewable energy commands specification leadership; electrical contractors provide cross-vertical volume stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting solar crimp set procurement toward jurisdictions with streamlined certification pathways and concentrated manufacturing ecosystems. Production migration follows cost-of-compliance gaps between mature standard regimes and emerging domestic content incentives.
China
Gigawatt-scale photovoltaic manufacturing expansion in Jiangsu and Zhejiang provinces is concentrating automated crimping system demand. GB standards alignment with IEC connector protocols reduces export friction for module producers serving European utility-scale developers. Suzhou and Shenzhen industrial clusters host precision die fabrication facilities supplying domestic panel assembly lines.
Germany
Domestic PV manufacturing resurgence under EU Green Deal industrial policy is expanding specification-grade crimp tooling procurement. REACH substance restrictions in die coatings and handle polymers force reformulation timelines ahead of enforcement windows. Bavaria and North Rhine-Westphalia balance-of-system suppliers specify IEC 61215-certified tooling for project finance eligibility.
India
PLI scheme subsidies for photovoltaic manufacturing are accelerating junction box assembly automation demand across Gujarat and Tamil Nadu production corridors. BIS certification mandates torque-repeatability testing for imported crimp sets used in government-subsidized rural electrification programs. Installer cooperatives in Maharashtra pool preventive maintenance subscriptions to reduce per-unit ownership costs.
United States
IRA production tax credits are reshoring panel manufacturing capacity in Arizona and Texas, expanding automated crimping system specifications. FCC equipment authorization rules govern powered crimping tools deployed in utility-scale solar farms across the Southwest. Rooftop installer fleets in California and Florida adopt battery-powered actuators with integrated pull-force sensors for warranty documentation.
Australia
Distributed commercial rooftop deployment growth is prioritizing handheld tool portability and field calibration service availability. TGA-equivalent electrical safety standards align with IEC connector reliability protocols for salt-air environment installations. Sydney and Melbourne installer cooperatives drive subscription-based maintenance program adoption to minimize fleet downtime.
Solar Crimp Set Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with connector-integrated suppliers commanding premium positioning in utility-scale procurement while independent tooling vendors capture distributed installation volumes. Market structure tilts toward consolidation at the high-reliability tier and fragmentation among field-portable equipment suppliers. Three archetypes dominate: integrated connector-tooling bundlers, precision die specialists, and contract manufacturers serving price-sensitive emerging markets. Capacity expansion and strategic partnerships represent the dominant competitive moves as vendors secure metallurgical supply agreements and calibration service networks.
Among connector-integrated bundlers, TE Connectivity and Phoenix Contact exemplify the premium-tier positioning that utility-scale developers specify for project finance compliance. Weidmüller anchors the rail-compatible specialization segment serving commercial rooftop inverter integration requirements. These three entities represent divergent strategic postures—broad portfolio leverage, protocol-centric certification focus, and application-specific engineering depth—rather than direct segment overlap.
| Leading Market Players |
|---|
| TE Connectivity |
| Phoenix Contact |
| Amphenol |
| Molex |
| Foxconn Interconnect Technology |
| Hirose Electric |
| VIOX Electric |
| Weidmüller |
| ECO-WORTHY |
| Others |
Pricing and Supply Chain Analysis
Family-owned precision die specialists in Germany and Japan anchor supply-side discipline, translating captive metallurgical expertise into pricing power that resists commoditization even as automated crimping demand accelerates across Chinese panel manufacturing corridors.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade handheld tools even as premium IEC-certified systems maintain specification premiums. Three-tier pricing structure across certified-premium, field-standard, and economy-import levels separates TE Connectivity's bundled connector offerings from mid-tier pneumatic alternatives and unbranded Asian imports. Cost compression in economy tiers intensifies because aluminum die substitutions and simplified handle polymers erode perceived quality differentiation. Installer cooperatives in India and Brazil exhibit highest price sensitivity, pooling maintenance subscriptions to defray per-unit ownership costs, while German utility-scale EPCs prioritize certification compliance over upfront equipment pricing.
Supply Chain Analysis
Dual-sourcing qualification mandates from tier-one panel manufacturers force crimp set vendors to maintain qualified secondary suppliers across Germany, Japan, and South Korea for precision die substrates. Raw material dependencies center on high-grade copper cathodes from Chilean and Indonesian smelters, specialty die steels from Austrian and Swedish mills, and REACH-compliant polymer compounds from Belgian chemical producers. Single-source vulnerability concentrates in tungsten-carbide surface treatment capacity, where Japanese coating specialists control proprietary vapor deposition techniques. Distribution runs through authorized industrial distributors in mature markets and direct vendor relationships in subsidy-driven procurement environments like India's PLI-subsidized manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solar Crimp Set Market functions as a regulatory compounder where tightening IEC 61215 and UL 1703 certification mandates create durable demand for precision-engineered tooling as project finance eligibility hinges on connector reliability documentation.
For Market Incumbents: Acquire calibration service networks and die replacement inventory pools to capture lifecycle revenue streams before independent distributors consolidate this recurring income layer. Defensive consolidation should prioritize backward integration into copper metallurgical processing to insulate margin structures from London Metal Exchange volatility, while simultaneously investing in machine vision alignment capabilities to match automation specifications from Chinese gigafactory junction box assembly lines. Threat substitution from press-fit connector technologies demands preemptive R&D in hybrid crimp-press tooling platforms. For New Entrants and Emerging Players: Rural electrification contractors in India's government-subsidized photovoltaic programs represent an underserved buyer archetype seeking aluminum-grade tooling with pooled maintenance subscriptions. White-space penetration should target Australia's distributed commercial rooftop segment, where battery-powered actuator adoption outpaces vendor service coverage, and Brazil's emerging installer cooperative channel seeking REACH-compliant alternatives to European imports. Go-to-market execution through equipment leasing partnerships with regional electrical distributors reduces capital barriers for fleet-scale procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier pneumatic tool manufacturers lacking certification depth but possessing established installer channel relationships. Long-term viability over the next decade hinges on automation convergence capabilities and regulatory compliance infrastructure rather than pure manufacturing scale. Acquisition target archetypes include rail-compatible system specialists serving commercial rooftop inverter integration and machine vision integration firms supplying quality verification for junction box automation. The specific signal to watch is BIS certification timeline acceleration in India, which would trigger vendor consolidation as compliance costs eliminate unqualified competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Subscription Launch | Captures recurring revenue from installer fleets in Australia and India seeking uptime guarantees. |
| Machine Vision Integration Partnership | Opens specification pathways in Chinese panel manufacturer junction box assembly automation. |
| REACH-Compliant Die Coating Reformulation | Preempts enforcement windows in Germany and France while satisfying project finance due-diligence scrutiny. |
| Copper Metallurgical Backward Integration | Insulates margin structures from LME volatility and secures conductivity-grade supply for humid climate specifications. |
| Rail-Compatible System Certification | Addresses DIN mounting standards for commercial rooftop inverter integration in European utility-scale deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with solar EPC procurement directors, panel manufacturer production engineers, certified installer fleet managers, and industrial distributor category buyers with secondary validation against IEC certification databases, customs trade flows for crimp tooling HS codes, BIS registration filings, and SEC disclosures from connector-integrated bundlers. Bottom-up segment sizing across handheld, automatic, pneumatic, and die set product categories triangulated against top-down photovoltaic installation capacity forecasts and junction box production estimates.
Segment-weighting approaches applied differential growth assumptions across product types, material grades, end-user archetypes, and industry verticals throughout the projection horizon. The analytical framework modeled pull-force certification tiers, copper versus aluminum material substitution elasticities, and automation penetration curves in panel manufacturing. CAGRs derived from installation volume trajectories, manufacturing capacity buildouts, and regulatory compliance deadline clustering. Industry-specific forecast inputs included BIS torque-repeatability testing mandate implementation schedules and IRA production tax credit reshoring timelines.
Underlying measurement precision varies by segment; automated crimping machine specifications carry tighter precision than handheld tool volumes given direct OEM procurement visibility. Forecasts reflect documented assumptions regarding IEC standard harmonization, copper price band stability, and subsidy program continuity. Deviation in Chinese domestic content requirement enforcement or REACH substance restriction acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Printable Solar Cells Market