
 Ground Mount PV Utility Market | 2026-2036
Ground Mount PV Utility Market Size, Share, and Industry Trends Forecast 2026-2036
Ground Mount PV Utility Market Foresight
The EU Green Deal is decoupling European utility-scale solar procurement from fossil-fuel baselines, forcing grid operators to rebalance capacity auctions toward zero-carbon assets. JinkoSolar leverages its integrated wafer-cell-module footprint to secure multi-gigawatt supply contracts across European offtakers. First Solar anchors North American project pipelines with its thin-film cadmium telluride technology, avoiding polysilicon supply exposure. LONGi Solar dominates high-efficiency monocrystalline shipments, sustaining margin capture through in-house silicon and wafer production.
Ground mount PV utility systems are large-scale photovoltaic installations fixed to the earth via steel or aluminum racking structures, typically deployed across hundreds of hectares with DC capacities exceeding one megawatt and connected through medium-voltage transformers to transmission networks. These arrays convert solar irradiance into grid-synchronized alternating current, serving as centralized generation assets for utility portfolio managers and wholesale electricity markets. Tracking systems command premium pricing due to energy yield advantages over fixed-tilt configurations, while bifacial modules capture growing share as developers seek elevated rear-side gain in high-albedo desert and snow-belt environments. Above 100 MW installations concentrate capital deployment and EPC margins, though the 11-50 MW bracket attracts independent power producers with faster permitting cycles and distributed offtake structures.
FERC Order 2023 and state renewable portfolio standards in the US reshape interconnection queue priorities, favoring solar-plus-storage configurations that accelerate grid access timelines. The EU AI Act and CSRD disclosure rules pressure European developers to document supply chain carbon intensity and algorithmic forecasting transparency across asset management platforms. India's CEA technical standards and MNRE bidding guidelines enforce domestic content requirements that filter module sourcing toward local manufacturing. Stakeholders must monitor evolving tariff structures and carbon border adjustments that will determine project finance spreads and offtake contract tenors.
Market Dynamics
Utility-scale solar procurement is decoupling from fossil-fuel baselines as carbon intensity rules tighten across major economies, forcing grid operators to rebalance capacity auctions toward zero-carbon assets and rewiring competitive positioning around supply chain traceability and domestic content compliance.
Growth Catalysts
- EU Green Deal carbon intensity mandates:European grid operators now prioritize zero-carbon assets in capacity auctions, redirecting procurement toward solar-plus-storage configurations that accelerate interconnection timelines.
- India PLI scheme domestic manufacturing incentives:Central government auctions under the production-linked incentive scheme attract foreign developers to state-level solar parks, concentrating capital deployment in Gujarat and Rajasthan.
- Bifacial module rear-side gain technology:Developers in high-albedo desert and snow-belt environments capture elevated energy yields, driving adoption across utility portfolios seeking optimized capacity factors.
Market Restraints
- Polysilicon supply concentration:Upstream purification capacity clusters in specific manufacturing hubs, exposing project timelines to raw material volatility and trade policy friction.
- Interconnection queue bottlenecks:FERC Order 2023 reshapes grid access priorities, but transmission upgrade backlogs still delay commercial operation dates for above-100 MW installations.
- Steel and aluminum racking input costs:Commodity price swings for structural metals compress EPC margins and destabilize fixed-price engineering contracts across multi-hundred-hectare deployments.
Strategic Opportunities
- Agrivoltaics dual-use land applications:Developers in India and Southern Europe deploy elevated tracking arrays over active agricultural plots, unlocking rural land access and diversifying revenue streams.
- Solar-plus-storage hybrid configurations:Co-located battery systems qualify for accelerated grid access under revised interconnection rules, creating premium pricing for dispatchable clean capacity.
- EU CSRD supply chain disclosure requirements:Early compliance with corporate sustainability reporting rules positions developers for preferential offtake terms with carbon-conscious corporate buyers.
Industry Challenges
- High-voltage substation engineering talent scarcity:Specialized skills for medium-voltage transformer integration and grid synchronization command premium wages, constraining EPC execution capacity.
- CEA technical standards certification timelines:India's Central Electricity Authority enforcement of domestic content requirements filters module sourcing, extending procurement cycles for foreign equipment.
- Algorithmic forecasting transparency compliance:EU AI Act documentation requirements for asset management platforms impose new compliance burdens on predictive maintenance and energy yield software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ground Mount PV Utility Market |
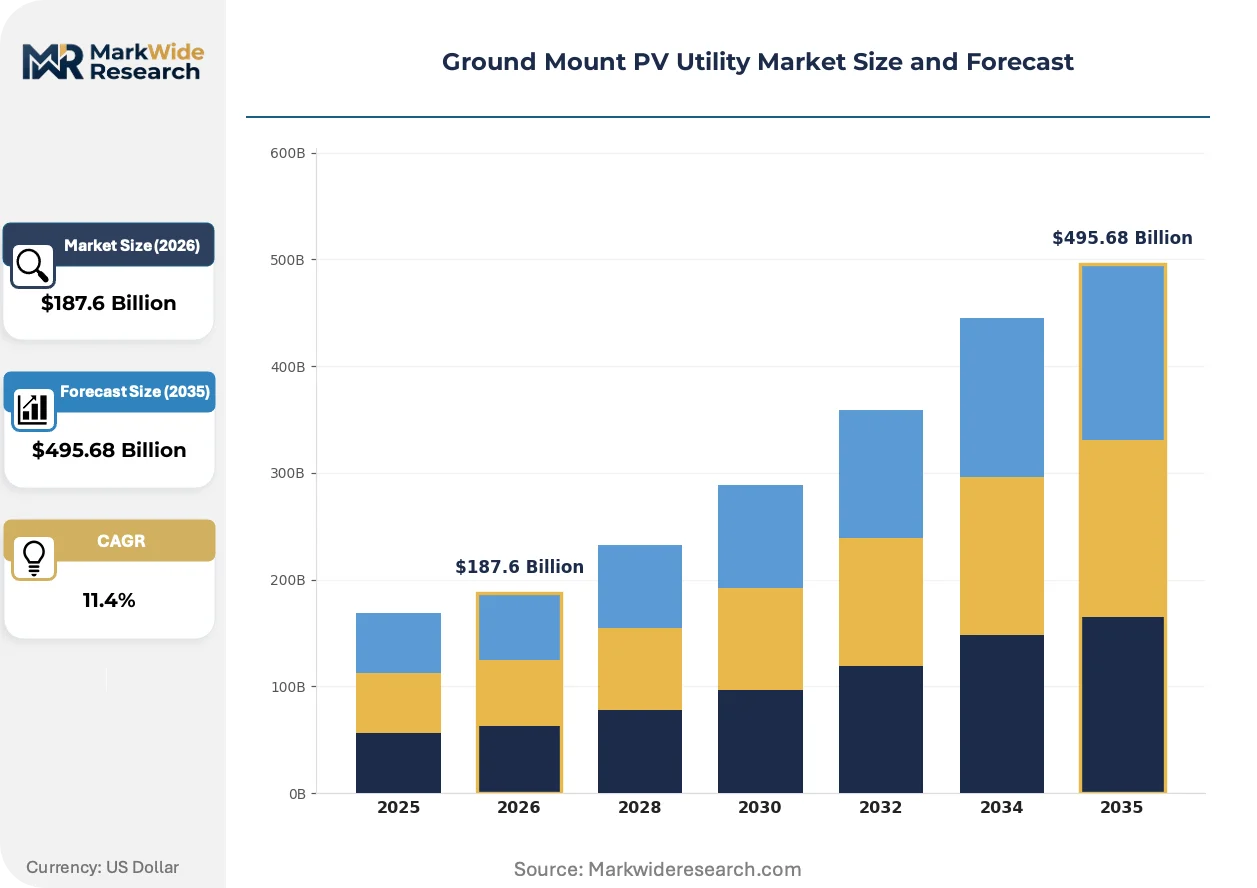
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film Installation Type: Fixed Tilt, Adjustable Tilt, Tracking Systems, Hybrid Systems Power Capacity: 1-10 MW, 11-50 MW, 51-100 MW, Above 100 MW End User: Utility Companies, Independent Power Producers, Government Projects, Commercial Developers |
| Companies Covered | GameChange Solar, Ameresco, Arctech, Clenergy, JinkoSolar, First Solar, Canadian Solar, LONGi Solar, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ground Mount PV Utility Market Shifts & Advancements
Technology convergence and regulatory disclosure mandates are compressing development cycles while rewiring competitive advantage around supply chain transparency and predictive system intelligence.
String inverter architecture with integrated power electronics is integrating grid-forming capabilities that enable higher renewable penetration without synchronous generation. European utilities now specify these advanced inverters in above-50 MW tenders, demanding fault-ride-through and reactive power support that legacy equipment cannot provide. This technology is integrating plant-level controls with wholesale market dispatch signals, compressing the gap between renewable generation and grid stability services.
The EU CSRD and EU AI Act impose parallel disclosure obligations on European developers, requiring documented carbon intensity across module supply chains and algorithmic transparency for forecasting platforms. Industrial consequence includes mandatory third-party auditing of manufacturing emissions and explainable AI documentation for energy prediction models. Large independent power producers in Germany and Spain are responding by consolidating supplier relationships with vertically integrated manufacturers capable of granular traceability reporting.
Corporate power purchase agreements now dominate offtake structuring for utility-scale projects, displacing traditional utility-sponsored procurement in North America and Europe. Energy-intensive manufacturers and data center operators negotiate directly with project developers, bypassing regulated utility intermediaries and capturing price hedging benefits. This pattern concentrates in jurisdictions with retail choice frameworks, particularly Texas and the PJM interconnection region where virtual PPA structures enable geographic flexibility.
Ground Mount PV Utility Market Segmentation
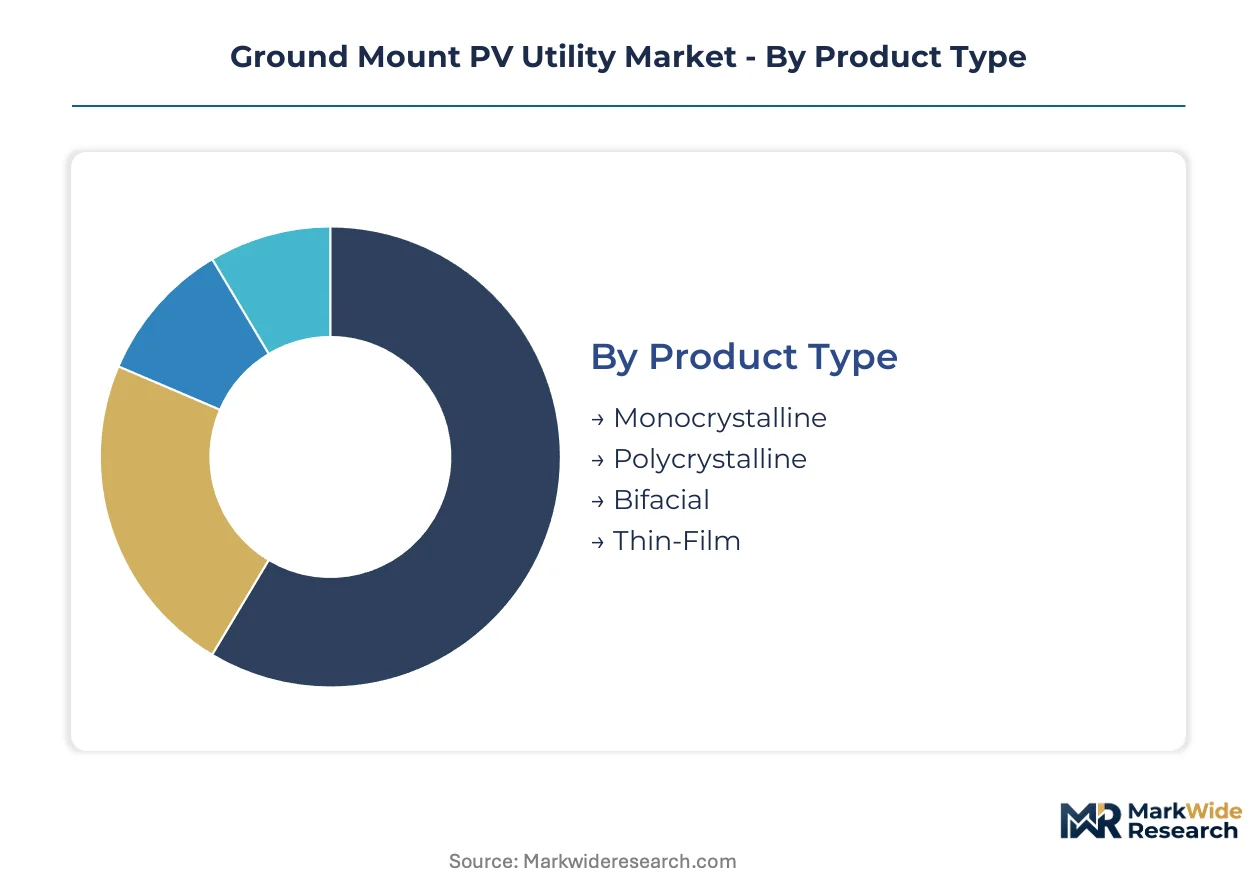
Ground mount PV utility procurement divides across four structural dimensions that determine capital intensity, permitting complexity, and offtake contracting structures. Each segmentation axis carries distinct regulatory burdens and margin profiles that reshape competitive positioning across development pipelines.
Product Type:
CEA technical standards and EU CSRD disclosure rules impose divergent certification burdens across module technologies, with domestic content requirements filtering sourcing toward locally qualified manufacturers.
- Monocrystalline:High-purity silicon ingots sliced into single-crystal wafers deliver conversion efficiencies exceeding 21%. LONGi Solar and other integrated producers dominate shipments to Indian solar parks and European utility tenders where efficiency premiums justify unit costs. CEA certification timelines extend procurement cycles for foreign equipment lacking domestic qualification.
- Bifacial:Dual-sided glass-glass construction captures rear-side irradiance reflected from high-albedo surfaces, boosting energy yields 8-20% over monofacial equivalents. Rajasthan desert installations and snow-belt projects in Germany concentrate demand as developers optimize capacity factors under EU Green Deal carbon intensity mandates.
- Polycrystalline:Multi-crystalline silicon cells manufactured through simpler casting processes offer lower unit costs but reduced efficiency. Procurement concentrates in price-sensitive emerging markets with less stringent performance requirements.
- Thin-Film:Cadmium telluride or CIGS semiconductor layers deposited on glass substrates avoid polysilicon supply exposure entirely. First Solar's integrated manufacturing anchors North American project pipelines where tariff avoidance and supply security outweigh efficiency trade-offs.
Leading the category by volume: Monocrystalline. Growing fastest: Bifacial.
Installation Type:
Structural configuration determines steel and aluminum input costs, labor intensity, and energy yield optimization potential across divergent terrain and irradiance profiles.
- Tracking Systems:Single-axis or dual-axis motorized racking follows solar azimuth through daily and seasonal cycles, delivering 15-25% energy yield advantages over fixed configurations. Premium pricing commands project finance spreads in Texas, Spain, and Gujarat where land availability permits row spacing optimization and high irradiance maximizes tracking returns.
- Fixed Tilt:Stationary racking set at optimal latitude angle minimizes mechanical complexity and maintenance burden. Below-50 MW installations in India and distributed utility portfolios favor this configuration for faster deployment and lower OPEX exposure.
- Adjustable Tilt:Seasonally reconfigurable racking angles optimize capture without motorized components. Limited adoption concentrates in research installations and demonstration projects.
- Hybrid Systems:Integrated fixed-tilt foundations with tracking upgrade pathways or agrivoltaic elevation structures. Southern European and Indian developers deploy elevated arrays over active agricultural plots to unlock rural land access.
Tracking Systems capture premium pricing tiers. Fixed Tilt dominates deployment counts.
Power Capacity:
Scale thresholds reshape interconnection queue positioning, EPC margin structures, and offtake contracting flexibility under FERC Order 2023 and equivalent grid access frameworks.
- Above 100 MW:Centralized generation assets requiring high-voltage substation integration and transmission-level interconnection. Above-100 MW installations concentrate capital deployment and EPC margins in Gujarat, Rajasthan, and Texas, though interconnection backlogs delay commercial operation dates.
- 11-50 MW:Distributed utility scale attracting independent power producers with faster permitting cycles and bilateral offtake structures. European corporate PPA markets and Indian state-level solar parks favor this bracket for regulatory agility.
- 1-10 MW:Small utility scale serving rural cooperative utilities and municipal procurement. Limited transmission upgrade requirements accelerate grid access in secondary markets.
- 51-100 MW:Mid-scale category bridging distributed and centralized development models. Emerging concentration in hybrid solar-plus-storage configurations qualifying for accelerated interconnection.
Above 100 MW absorbs majority capital flows. 11-50 MW expands most quickly.
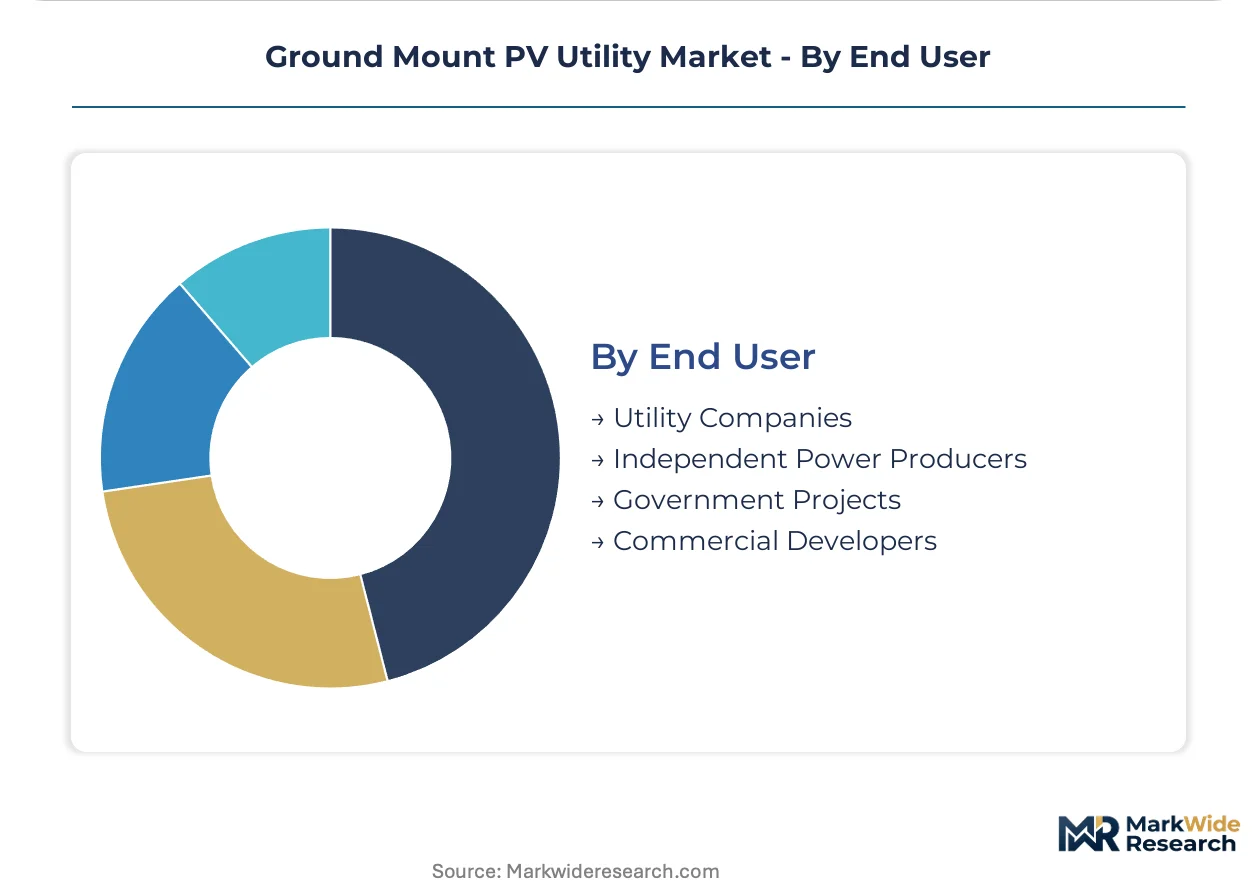
End User:
Counterparty credit quality and procurement mandate stringency determine project finance availability, contract tenor, and supply chain disclosure obligations.
- Independent Power Producers:Non-utility developers merchant-exposing capacity or contracting corporate PPAs directly. IPPs in Germany, Spain, and Texas bypass regulated utility intermediaries to capture price hedging benefits through virtual structures.
- Utility Companies:Regulated or unregulated load-serving entities procuring under renewable portfolio standards. FERC Order 2023 and state RPS frameworks reshape interconnection queue priorities toward solar-plus-storage configurations.
- Government Projects:Central and state-level auctions under India's PLI scheme, EU Green Deal procurement windows, and federal land deployments. Domestic content requirements filter module sourcing toward qualified manufacturers.
- Commercial Developers:Industrial offtakers and data center operators negotiating direct bilateral contracts. EU CSRD disclosure obligations pressure supply chain carbon intensity documentation.
Independent Power Producers drive contract innovation. Government Projects anchor volume commitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bhadla Solar Park in Rajasthan anchors capital deployment for utility-scale ground mount installations, drawing foreign developers through central government auctions under India's PLI scheme.
United States
Texas and California concentrate independent power producer activity, with ERCOT's nodal market enabling merchant-exposed capacity. FERC Order 2023 reshapes interconnection queue priorities toward solar-plus-storage configurations. The Permian Basin and Imperial Valley host multi-hundred-megawatt tracking arrays serving corporate offtakers.
India
Gujarat and Rajasthan state-level solar parks attract domestic and foreign developers through production-linked incentive auctions. CEA technical standards enforce domestic content requirements that filter module sourcing toward local manufacturing. The Bhadla and Pavagada ultra-mega solar parks concentrate above-100 MW deployments.
Germany
Corporate power purchase agreements displace traditional utility procurement in Bavaria and Brandenburg. EU Green Deal carbon intensity mandates force grid operators to rebalance capacity auctions toward zero-carbon assets. The former lignite mining regions of Lusatia host bifacial tracking installations optimized for snow-belt albedo gains.
Spain
Andalusia and Extremadura attract independent power producers with streamlined permitting for above-50 MW installations. EU CSRD disclosure rules pressure developers to document supply chain carbon intensity for corporate buyers. The Guadalquivir valley concentrates agrivoltaic deployments combining elevated tracking arrays with olive cultivation.
Australia
Queensland and New South Wales host merchant solar developments targeting the National Electricity Market. State renewable portfolio standards tighten carbon intensity rules for grid-connected capacity. The Darling Downs and Riverina regions concentrate fixed-tilt arrays serving rural cooperative utilities.
Ground Mount PV Utility Market Competitive Landscape
The competitive structure tilts toward vertically integrated module manufacturers with captive polysilicon supply. Tier-one Chinese producers dominate shipment volumes through in-house wafer and cell production, while thin-film specialists occupy defensible niches in tariff-sensitive markets. Strategic archetypes include integrated silicon-to-module conglomerates, cadmium telluride thin-film pure-plays, and racking system specialists. Capacity expansion and supply chain traceability certification represent the dominant competitive moves.
Among integrated Chinese manufacturers, JinkoSolar, LONGi Solar, and Trina Solar exemplify the scale-driven archetype with captive upstream production. First Solar occupies a distinct position as a thin-film specialist avoiding polysilicon exposure entirely. GameChange Solar and Arctech represent the racking system tier, supplying structural hardware to project developers across multiple geographies.
| Leading Market Players |
|---|
| GameChange Solar |
| Ameresco |
| Arctech |
| Clenergy |
| JinkoSolar |
| First Solar |
| Canadian Solar |
| LONGi Solar |
| Trina Solar |
| Others |
Supply & Pricing Matrix
Module efficiency-performance bifurcation separates premium monocrystalline-bifacial arrays from commodity polycrystalline units, with that divergence manifesting in tiered EPC contract structures and polysilicon sourcing strategies across Indian PLI auctions and European CSRD-compliant tenders. Price premiums for tracking-enabled, high-albedo-optimized configurations flow directly to integrated manufacturers with captive wafer capacity, while buyers without domestic content certification face extended procurement cycles and tariff-adjusted landed costs.
Pricing Analysis
Value-based pricing anchors on guaranteed energy yield outcomes, with developers paying premiums for bifacial rear-side gain warranties and tracking system performance guarantees in Rajasthan and Texas desert installations. Price differentiation rests on module efficiency tier and CEA domestic content certification, with non-compliant foreign equipment facing disqualification from Indian government auctions. Cost compression in fixed-tilt polycrystalline segments is intensifying because of polysilicon spot market volatility and steel racking input inflation. Independent power producers exhibit highest price sensitivity on balance-of-system components, while utility offtakers prioritize performance certainty over unit cost minimization.
Supply Chain Analysis
India's CEA technical standards and the EU's carbon border adjustment mechanisms are reshaping sourcing toward qualified domestic manufacturers and low-carbon-intensity suppliers in Southeast Asia. Geographic supply concentration centers on China for polysilicon purification and wafer slicing, Vietnam for cell and module assembly qualifying for tariff avoidance, and India for PLI-incentivized domestic manufacturing. Raw material dependencies include metallurgical-grade silicon, silver paste for cell metallization, and aluminum extrusions for racking structures. Single-source vulnerability in polysilicon purification exposes project timelines to trade policy friction. Distribution runs through vertically integrated manufacturers delivering direct to EPC contractors, with racking specialists supplying structural hardware through regional fabrication partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polysilicon purification capacity constraints prop pricing power for integrated manufacturers with captive upstream supply, creating a supply-constrained market structure favoring early procurement commitment and long-term offtake contracting.
For Market Incumbents: Hedge against tariff exposure by diversifying module assembly footprints into Vietnam and India, while securing silver paste and aluminum supply through multi-year contracts with commodity traders. Defend margin position by accelerating CEA certification timelines for Indian government auction eligibility, insulating against emerging thin-film competitors in North American utility tenders.
For New Entrants and Emerging Players: Launch via agrivoltaic EPC partnerships in Southern Europe and Gujarat, where elevated tracking arrays unlock rural land access with faster permitting cycles than conventional ground-mount projects. Target the 11-50 MW distributed utility segment in Spain and Germany, where corporate PPA demand outstacks local development capacity and CSRD disclosure requirements filter out undercapitalized competitors.
For Investors and Strategic Acquirers: Re-rating potential sits with racking system specialists possessing patented tracking mechanics and established EPC relationships, given FERC Order 2023's acceleration of solar-plus-storage interconnection timelines driving tracking adoption. Long-term viability over the coming decade hinges on backward integration into steel fabrication and software-defined plant controls. The signal to watch is bifacial module penetration rates in high-albedo installations, indicating technology transition momentum and margin capture opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Certification | CEA qualification unlocks Indian PLI auction participation and preferential offtake terms. |
| Tracking System Patent Portfolio | Proprietary single-axis mechanics command EPC margin premiums in Texas and Gujarat high-irradiance zones. |
| Polysilicon Supply Agreement | Long-term purification contracts insulate module costs from spot market volatility and trade friction. |
| Agrivoltaic EPC Capability | Elevated array engineering expertise opens rural land access in EU Green Deal procurement windows. |
| Solar-Plus-Storage Integration | Co-located battery qualification accelerates grid interconnection under revised FERC Order 2023 frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across utility planning officers, IPP project developers, EPC contractors, and grid operators. MNRE auction results, FERC interconnection queue databases, and EU CSRD disclosure filings provided project-level validation. Bottom-up capacity installation tracking and top-down policy impact modeling were triangulated against module shipment data from major manufacturers.
Segmentation-level granularity modeled module technology, installation configuration, power capacity tier, and end-user archetype across the projection horizon. CAGRs were derived from capacity deployment trajectories under evolving renewable portfolio standards and carbon intensity mandates. Forecast inputs incorporated interconnection queue processing rates, domestic content requirement phase-in schedules, and tracking system cost learning curves.
Polysilicon supply disruption, tariff regime recalibration, and interconnection backlog resolution are the dominant revision risks to deployment assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Italy Distributed Solar Power Generation Market