
 Solar Photovoltaic Material Market | 2026-2036
Solar Photovoltaic Material Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Photovoltaic Material Market Outlook
Performance-based operations and maintenance contracts are decoupling revenue from hardware shipments across the solar value chain. LONGi Green Energy Technology Co Ltd anchors its position through captive polysilicon and wafer capacity spanning western China. Jinko Solar competes through vertically integrated cell and module output serving utility-scale tenders across Southeast Asia and the Middle East. DuPont differentiates via specialty encapsulant and metallization pastes that extend module lifespans in high-UV environments.
Solar photovoltaic material encompasses the active and passive substances—silicon wafers, thin-film semiconductors, encapsulants, backsheets, and conductive pastes—engineered to convert photons into direct-current electricity, with monocrystalline silicon achieving laboratory efficiencies above 26% and commercial modules typically operating between 20-22%. Crystalline silicon occupies the dominant share of material demand due to established supply chains and continuous cost reduction through diamond-wire sawing and PERC cell architectures. Thin-film alternatives, particularly cadmium telluride, sustain niche positions where weight constraints or high-temperature coefficients favor non-silicon absorption layers. Bifacial panels represent the fastest-growing technology segment as dual-sided energy capture improves levelized cost of electricity in utility-scale deployments.
The US IRA production tax credits and domestic content bonuses are reshaping where polysilicon and ingot capacity locates, while EU Green Deal carbon-border adjustments pressure embodied emissions in imported wafers. China's MIIT efficiency benchmarks and GB standards for module recycling create compliance thresholds that filter smaller material suppliers. India BIS certification requirements and PLI scheme disbursements condition market access for foreign cell and module producers. Stakeholders must track how jurisdiction-specific content rules and carbon-accounting protocols reroute capital toward localized ingot and wafer investments.
Market Dynamics
Polysilicon supply concentration in western China is forcing module manufacturers to reconfigure procurement strategies as geopolitical trade barriers harden. This upstream bottleneck cascades through wafer pricing and shapes competitive positioning across cell and module tiers.
Growth Catalysts
- IRA domestic content bonuses:US production tax credits incentivize ingot and wafer capacity relocation from Asia to American soil. Utility-scale developers now specify domestic content thresholds in procurement tenders.
- EU Green Deal carbon-border adjustments:Embodied emissions accounting in imported wafers and cells pressures suppliers to decarbonize polysilicon refining. European module buyers increasingly demand supply chain transparency documentation.
- Bifacial panel architecture:Dual-sided energy capture improves levelized cost economics in desert and high-albedo installations. EPC contractors specify bifacial glass-glass modules for utility-scale projects.
Market Restraints
- Polysilicon price volatility:Energy-intensive Siemens process refining concentrates in coal-dependent regions of Xinjiang and Inner Mongolia. Input cost swings compress margin predictability for wafer manufacturers.
- Silver paste dependency:Metallization pastes for PERC and TOPCon cells require 15-20 milligrams of silver per watt. Precious metal supply constraints and price spikes threaten cell cost reduction trajectories.
- Encapsulant material limitations:Ethylene vinyl acetate dominates but degrades under high-UV and high-humidity conditions. Alternative polyolefin encapsulants face qualification timeline delays with IEC 61215 certification bodies.
Strategic Opportunities
- India PLI scheme disbursements:Production-linked incentives for polysilicon-to-module integrated capacity attract capital away from pure-play module assembly. Domestic content requirements in government tenders secure offtake.
- Building-integrated photovoltaics:Thin-film cadmium telluride and copper indium gallium selenide enable aesthetic solar facades and skylight applications. Commercial real estate developers specify colored and semi-transparent modules.
- Module recycling infrastructure:China's GB standards for end-of-life recovery create compliance thresholds that filter smaller suppliers. Glass, aluminum frame, and silver recovery economics improve with scale.
Industry Challenges
- Cell metallization engineering talent:Fine-line screen printing and laser-doped selective emitter optimization require specialized process engineers. Universities in Germany and Japan produce limited graduates with relevant compound semiconductor backgrounds.
- TOPCon migration capex burden:Tunnel oxide passivated contact cell lines require $50-70 million per gigawatt of new equipment. Legacy PERC manufacturers face stranded asset risk during technology transition.
- Carbon accounting verification:Scope 3 emissions disclosure for polysilicon, ingot, and wafer tiers demands third-party audit infrastructure. Suppliers lack standardized methodologies aligned with ISO 14064.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Photovoltaic Material Market |
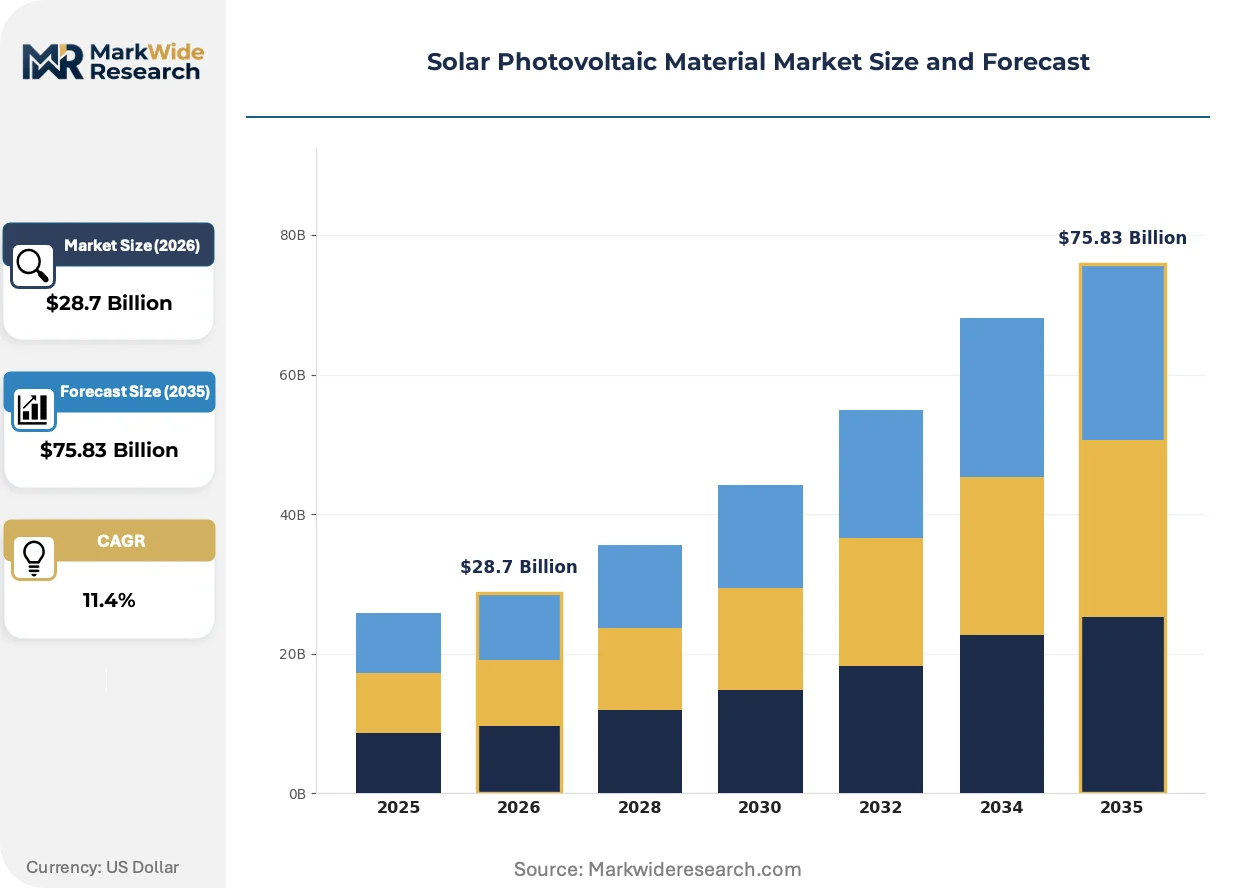
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon, Cadmium Telluride, Copper Indium Gallium Selenide, Organic Photovoltaics Application: Residential, Commercial, Utility-scale, Off-grid Technology: Thin Film, Crystalline Silicon, Bifacial Panels, Concentrated PV End User: Installers, Manufacturers, System Integrators, Project Developers |
| Companies Covered | Jinko Solar, LONGi Green Energy Technology Co Ltd, Trina Solar, JA Solar, Tongwei Co., Ltd., DuPont, Honeywell International Inc., Wacker Chemie AG, Targray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Photovoltaic Material Market Strategic Shifts
Heterojunction and TOPCon cell architectures are consolidating manufacturing investment as passivated contact designs displace legacy PERC dominance. Equipment suppliers and material formulators must align roadmaps with this process technology inflection.
Tunnel oxide passivated contact technology is consolidating cell efficiency roadmaps above 25% in mass production. Tier-one manufacturers in Anhui and Jiangsu provinces are converting PERC lines to TOPCon through selective equipment retrofits. This migration is compressing the competitive window for legacy aluminum back-surface field designs.
The EU F-Gas Regulation phase-down is forcing fluorinated greenhouse gas elimination from solar manufacturing processes. Etching and cleaning chemistries in wafer texturing must transition to plasma-based or aqueous alternatives. European module assemblers face compliance deadlines that accelerate supplier qualification cycles for low-carbon process materials.
Utility-scale developers are unbundling module supply from engineering-procurement-construction contracts. Independent power purchasers now negotiate direct multi-year supply agreements with cell and wafer manufacturers. This disintermediation is most visible in Saudi Arabia and the United Arab Emirates, where sovereign wealth-backed project vehicles seek supply chain transparency.
Solar Photovoltaic Material Market Segmentation
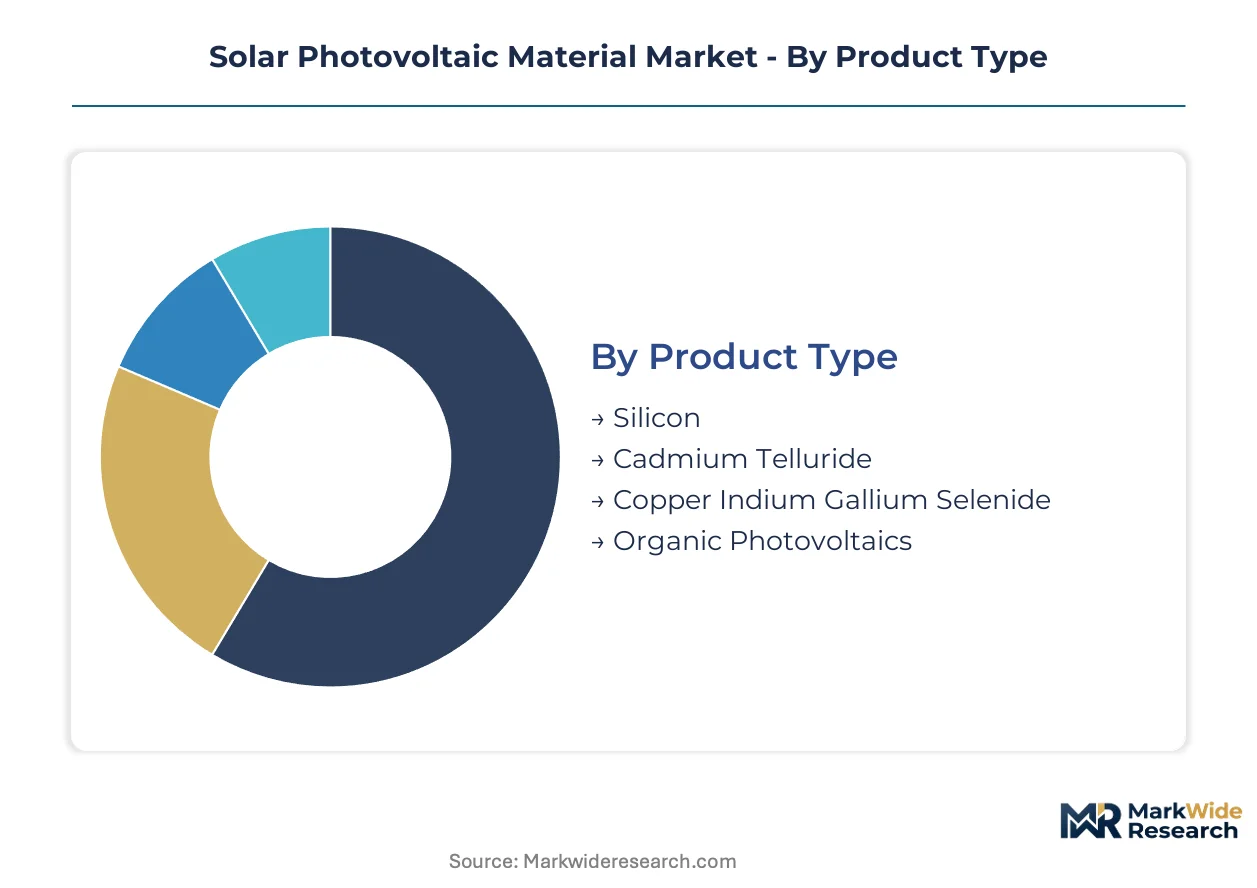
Segmentation in solar photovoltaic materials reveals how capital deployment, technology risk, and regulatory incentives distribute across distinct supply chain tiers. Understanding these divisions clarifies where margin pools concentrate and which material categories face substitution pressure from next-generation architectures.
Product Type:
Silicon refining and thin-film deposition demand vastly different capital structures, with polysilicon plants requiring billion-dollar scale commitments versus modular thin-film lines.
- Silicon:Metallurgical-grade silicon undergoes energy-intensive purification through the Siemens process to reach 9N purity for semiconductor-grade wafers. Polysilicon capacity clusters in Xinjiang and Inner Mongolia where captive coal power subsidizes input costs, though EU carbon-border adjustments now threaten this cost advantage for exports into European module assembly.
- Cadmium Telluride:Vapor transport deposition onto glass substrates eliminates wafer slicing losses and enables monolithic integration. First Solar dominates commercial manufacturing in Ohio and Malaysia, targeting utility-scale tenders in the US Southwest where high-temperature coefficients favor thin-film stability over crystalline silicon degradation.
- Copper Indium Gallium Selenide:Sputtered or co-evaporated chalcogenide layers achieve flexible form factors for building-integrated applications. Japanese and South Korean equipment suppliers control turnkey line supply, limiting new entrant proliferation outside established thin-film clusters.
- Organic Photovoltaics:Solution-processed polymers and small-molecule acceptors enable roll-to-roll manufacturing at ambient pressure. Laboratory efficiency gains from non-fullerene acceptors attract specialty chemical investment, though commercial module lifespans remain below IEC 61215 qualification thresholds for utility deployment.
Most installed capacity flows through Silicon. Expansion is steepest in Cadmium Telluride.
Application:
Customer procurement patterns diverge sharply between fragmented residential rooftops and concentrated utility-scale offtake, reshaping material specification priorities.
- Residential:Distributed generation systems under 20 kilowatts prioritize aesthetic integration and rapid installation. Module manufacturers specify black silicon cells and slim frames to satisfy homeowner association restrictions in suburban US markets and German Mittelstand housing stock.
- Commercial:Flat-roof and parking canopy installations balance structural loading constraints with energy yield optimization. Bifacial glass-glass modules gain specification share in California and Australian commercial portfolios where albedo from concrete or membrane roofing boosts rear-side generation.
- Utility-scale:Centralized solar farms above 100 megawatts drive procurement volume and dictate polysilicon contract structures. Saudi Arabia's PIF-backed project vehicles and Indian SECI tenders specify domestic content thresholds that filter eligible cell and module suppliers.
- Off-grid:Remote industrial and rural electrification applications prioritize reliability over levelized cost minimization. Lead-acid battery pairing with polycrystalline modules persists in sub-Saharan African and Southeast Asian island installations where supply chain fragility discourages lithium-ion dependency.
Utility-scale procurement commands the dominant revenue share. Commercial bifacial adoption is climbing the fastest.
Technology:
Process technology migration from PERC to TOPCon and heterojunction is reallocating equipment and material demand across cell architectures.
- Thin Film:Cadmium telluride and copper indium gallium selenide deposition bypasses silicon wafering entirely, reducing capital intensity per watt but locking manufacturers into specialized equipment ecosystems. US IRA domestic content bonuses advantage First Solar's Ohio cadmium telluride capacity over imported crystalline modules.
- Crystalline Silicon:Diamond-wire sawn monocrystalline wafers with passivated emitter and rear contact architecture still dominate mass production. Chinese manufacturers in Anhui and Jiangsu provinces are selectively retrofitting PERC lines to tunnel oxide passivated contact designs without full greenfield investment.
- Bifacial Panels:Dual-sided energy capture requires transparent backsheet or glass-glass construction with modified encapsulant formulations. Desert installations in Morocco and the UAE specify bifacial modules for high-albedo sand reflection, improving project IRRs through enhanced capacity factors.
- Concentrated PV:III-V multijunction cells under Fresnel lens concentration achieve laboratory efficiencies above 40 percent but require dual-axis tracking and direct normal irradiance above 2,000 kWh per square meter. Niche deployment concentrates in Saudi Arabia's Tabuk region and Arizona utility test beds.
Crystalline silicon retains the dominant production footprint. Bifacial panel manufacturing is gaining share fastest.
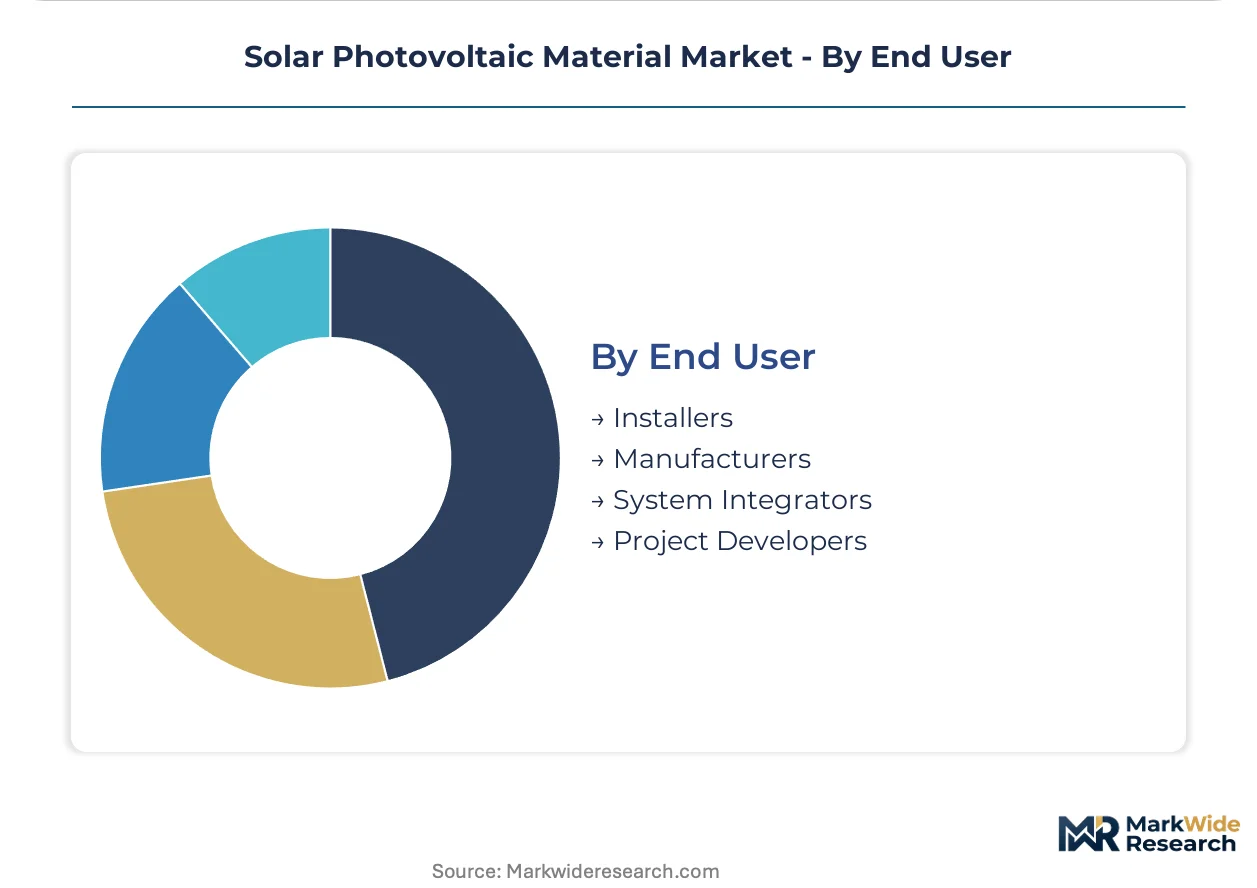
End User:
Supply chain position determines whether material procurement emphasizes spot market flexibility or long-term contract security.
- Installers:Residential and small commercial contractors source modules through distributor networks with limited influence over upstream material specifications. German and Australian installer cooperatives aggregate purchasing volume to negotiate cell efficiency minimums with tier-one module brands.
- Manufacturers:Vertically integrated cell and module producers secure polysilicon and wafer supply through multi-year offtake agreements. LONGi and Jinko Solar maintain captive ingot capacity to insulate margin from spot price volatility in Xinjiang polysilicon.
- System Integrators:Engineering-procurement-construction firms bundle module supply with installation services for commercial and utility clients. Saudi ACWA Power and Indian Tata Power Solar specify module suppliers in tender responses, intermediating between project developers and cell manufacturers.
- Project Developers:Independent power producers and yieldcos negotiate direct module supply agreements separate from EPC contracts. Masdar and EDF Renewables in the UAE pursue supply chain transparency documentation to satisfy EU Green Deal carbon-accounting requirements for exported electricity.
Manufacturers control the dominant procurement volume. Project developer direct contracting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's concentration of polysilicon refining capacity contrasts sharply with the United States' push to rebuild domestic ingot and wafer supply chains through IRA incentives. Germany and India represent alternative poles of demand growth, each deploying distinct regulatory levers to reshape material procurement patterns.
China
Western provinces host the dominant share of metallurgical-grade silicon purification through energy-intensive Siemens process operations. MIIT efficiency benchmarks and GB standards for module recycling filter smaller material suppliers from government tender eligibility. Xinjiang and Inner Mongolia clusters concentrate polysilicon output where captive coal power subsidizes refining economics.
United States
IRA production tax credits and domestic content bonuses redirect capital toward American ingot and wafer fabrication. FERC interconnection queue reforms accelerate utility-scale solar deployment timelines in Texas and California. Ohio hosts thin-film manufacturing capacity serving Southwest desert installations where high-temperature coefficients favor non-silicon absorption layers.
Germany
EU Green Deal carbon-border adjustments pressure embodied emissions in imported wafers and cells from Asian suppliers. ECHA REACH compliance requirements and F-Gas Regulation phase-downs force fluorinated greenhouse gas elimination from wafer texturing processes. Bavaria and Saxony-Anhalt retain module assembly infrastructure serving distributed generation demand across Mittelstand housing stock.
India
SECI utility-scale tenders specify domestic content thresholds that filter eligible cell and module suppliers. BIS certification requirements and PLI scheme disbursements condition market access for foreign producers. Gujarat and Andhra Pradesh attract polysilicon-to-module integrated capacity through production-linked incentive disbursements.
Saudi Arabia
PIF-backed project vehicles negotiate direct multi-year supply agreements with cell and wafer manufacturers separate from EPC contracts. Tabuk region installations specify concentrated PV systems under Fresnel lens concentration achieving laboratory efficiencies above 40 percent. Sovereign wealth deployment seeks supply chain transparency documentation for exported electricity streams.
Solar Photovoltaic Material Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated producers commanding upstream material tiers while pure-play assemblers compete on module cost. The vendor base concentrates around three strategic archetypes: captive polysilicon refiners securing margin insulation, specialty chemical formulators extending module lifespans, and thin-film deposition specialists bypassing silicon wafering entirely. Dominant competitive moves include selective PERC-to-TOPCon line retrofits and direct offtake negotiations with utility-scale developers.
Among Chinese vertically integrated producers, LONGi Green Energy Technology Co Ltd and Jinko Solar occupy positions exemplifying captive ingot capacity strategies, while DuPont represents specialty material formulation archetypes serving encapsulant and metallization paste demand. These three anchors illustrate how geographic clustering and supply chain positioning differentiate competitive postures without requiring identical strategic moves.
| Leading Market Players |
|---|
| Jinko Solar |
| LONGi Green Energy Technology Co Ltd |
| Trina Solar |
| JA Solar |
| Tongwei Co., Ltd. |
| DuPont |
| Honeywell International Inc. |
| Wacker Chemie AG |
| Targray |
| Others |
Value Chain & Pricing Dynamics
Polysilicon spot price indices from Xinjiang and Inner Mongolia cascade through wafer contract structures into three-tier pricing stratification across premium, standard, and economy module tiers. IRA domestic content bonuses and EU carbon-border adjustments are rerouting procurement premiums toward American ingot capacity and low-carbon polysilicon supply.
Pricing Analysis
Capacity additions in Anhui and Jiangsu provinces are reshaping price floors for tunnel oxide passivated contact cells as legacy PERC manufacturers liquidate inventory. Pricing stratifies across premium, standard, and economy tiers based on cell efficiency certification and volume scale of utility-scale offtake agreements. Cost compression in standard-tier modules is intensifying because silver paste input volatility compresses metallization margins. Residential installers exhibit highest price sensitivity, while sovereign wealth-backed project developers in Saudi Arabia prioritize supply chain transparency over unit cost minimization.
Supply Chain Analysis
Module recycling flows and end-of-life silver recovery are creating reverse-logistics infrastructure requirements under China's GB standards for glass and aluminum frame reclamation. Polysilicon refining draws from captive coal power in Xinjiang, metallurgical-grade silicon feedstock from Yunnan, and high-purity quartz crucibles from Hubei. Single-source vulnerability concentrates in western China polysilicon clusters exposed to geopolitical trade barrier escalation. Distribution runs through vertically integrated cell and module producers negotiating direct multi-year supply agreements with utility-scale developers, bypassing traditional EPC intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where IRA production tax credits and EU Green Deal carbon-border adjustments are accelerating capital deployment into localized ingot and wafer investments.
For Market Incumbents: Hedge against silver paste dependency by qualifying copper metallization alternatives and securing polyolefin encapsulant supply ahead of IEC 61215 certification timeline compression. Captive polysilicon capacity in Xinjiang insulates margin from spot volatility but exposes balance sheets to EU carbon-border adjustment penalties; backward integration into American ingot fabrication captures IRA domestic content bonuses. For New Entrants and Emerging Players: Capture white-space in building-integrated photovoltaics through cadmium telluride facade systems and organic photovoltaic skylight applications where aesthetic specifications filter incumbent crystalline silicon suppliers. India's PLI scheme disbursements for polysilicon-to-module integrated capacity offer the most penetrable geography; partner with Gujarat-based EPC contractors to secure government tender offtake. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty chemical formulators supplying low-carbon process materials for EU F-Gas Regulation compliance and third-party carbon accounting verification services. Five-to-ten year viability hinges on technology migration from PERC to TOPCon and heterojunction architectures; monitor equipment supplier order backlogs for inflection signals on cell line retrofit velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | TOPCon cell line retrofits in Anhui and Jiangsu consolidate efficiency roadmaps above 25% mass production. |
| Backward Integration | Captive polysilicon refining in Xinjiang insulates wafer margins from spot price volatility. |
| Long-term Supply Agreement | Direct multi-year offtake contracts with Saudi PIF-backed project vehicles secure utility-scale volume. |
| Technology Licensing | TOPCon equipment retrofits license tunnel oxide passivated contact process IP to legacy PERC manufacturers. |
| Green Certification Program | Third-party ISO 14064 carbon accounting verification unlocks EU Green Deal compliant wafer procurement. |
Study Parameters
Coverage spans China, the United States, Germany, India, and Saudi Arabia, with primary inputs from each market cluster. Polysilicon plant managers, utility-scale EPC contractors, module procurement leads at independent power producers, and carbon accounting verification specialists contributed structured interviews. Secondary validation drew from MIIT efficiency benchmark disclosures, IRA domestic content guidance documents, EU ETS carbon price data, and SECI tender specifications. Bottom-up cell and wafer capacity tallies triangulated against top-down module shipment aggregates.
Rate-of-change decomposition separates volume growth from price trajectory shifts across the analysis window. Segmentation dimensions modeled include material type, cell architecture, application scale, and regulatory framework cluster. CAGRs derive from polynomial trend fitting of historical capacity additions against policy incentive phase-in schedules. Forecast inputs incorporate silver paste price volatility bands and F-Gas Regulation compliance cost curves for wafer texturing chemistries.
Polysilicon price volatility, EU carbon-border adjustment enforcement timing, and TOPCon migration capex availability are the dominant revision risks to modeled outputs. Practitioners should monitor equipment supplier order backlogs, IRA domestic content bonus qualification thresholds, and EU ETS carbon price trajectories for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
3D Printed Solar Energy Trees Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Netherlands Solar Energy Market