
 Soft Tissue Release Systems Market | 2026-2036
Soft Tissue Release Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Tissue Release Systems Market Analytics
Buyer concentration among outpatient orthopedic clinics is recalibrating procurement patterns across the soft tissue release systems landscape. Arthrex, Inc. leverages its arthroscopy-derived tool expertise to dominate sports therapy channels. Medtronic anchors hospital system contracts through its broad surgical portfolio. Stryker Corporation differentiates via integrated power tool platforms that span release and debridement applications.
Soft tissue release systems encompass manual instruments, powered devices, and combination platforms engineered to mechanically or electro-mechanically disrupt fascial adhesions and myofascial trigger points, typically operating at percussion frequencies between 2000-3200 strokes per minute or delivering focused ultrasound at 1-3 MHz for therapeutic depth penetration. These systems serve primary commercial purposes in musculoskeletal rehabilitation, perioperative tissue preparation, and athletic recovery protocols where manual therapy alone proves insufficient. Electrical Devices command margin pools due to premium pricing on ultrasound and electrostimulation modalities, while Combination Systems represent the fastest-growing configuration as clinics seek versatile single-unit investments. Manual Tools retain volume leadership in price-sensitive physiotherapy centers where capital budgets constrain technology adoption.
FDA 510(k) clearance requirements govern Class II device introductions in the United States, while the EU MDR imposes strengthened clinical evidence standards for CE marking across European markets. Japan's PMDA maintains distinct quality management system audits that extend approval timelines for foreign manufacturers. ISO 13485 certification serves as a baseline predicate for regulatory access across all major jurisdictions. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA digital health guidance expansions that could reclassify software-integrated therapeutic platforms.
Market Dynamics
University hospital networks are consolidating sports medicine procurement into centralized purchasing agreements, compressing vendor negotiation cycles and favoring suppliers with broad device portfolios over single-product specialists.
Growth Catalysts
- EU MDR clinical evidence mandates:Strengthened CE marking requirements for Class II devices are filtering out marginal competitors and concentrating contract awards among established manufacturers with robust quality management systems.
- Outpatient orthopedic clinics:Germany's rehabilitation sector is replacing manual tool inventories with powered platforms, creating replacement demand cycles that favor combination systems over standalone devices.
- Percussion frequency optimization:Engineering advances in motor control systems now enable precise stroke rate modulation between 2000-3200 per minute, expanding therapeutic applicability across fascial adhesion severities.
Market Restraints
- Premium component sourcing:Piezoelectric transducers for therapeutic ultrasound modules concentrate among Japanese and German suppliers, exposing manufacturers to input cost volatility and extended lead times.
- FDA 510(k) predicate device requirements:Substantial equivalence determinations for novel electro-mechanical platforms frequently require additional bench testing, extending development timelines by 8-14 months.
- Manual therapy substitution:Low-cost instrument-assisted soft tissue mobilization tools retain preference in price-constrained physiotherapy centers, capping penetration rates for powered alternatives.
Strategic Opportunities
- Japan's aging musculoskeletal patient base:METI reimbursement pathway expansions for outpatient rehabilitation devices are opening procurement channels previously restricted to inpatient surgical equipment.
- Software-integrated therapeutic platforms:Convergence of release system hardware with treatment protocol algorithms and patient outcome tracking is creating service revenue streams beyond device sale margins.
- Direct-to-clinic distribution models:Bypassing traditional medical device distributors through manufacturer-owned sales organizations is capturing margin previously allocated to channel intermediaries.
Industry Challenges
- Biomedical engineering talent scarcity:Cross-disciplinary expertise combining mechanical design, therapeutic ultrasound physics, and regulatory affairs remains concentrated among a limited pool of specialists in Massachusetts and Baden-Württemberg.
- ISO 13485 certification timelines:Notified body audit backlogs are extending quality management system validation periods, delaying market entry for emerging manufacturers.
- Legacy EMR integration complexity:Power tool platforms with embedded software require customized HL7 interface development for each hospital network's electronic medical record architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Tissue Release Systems Market |
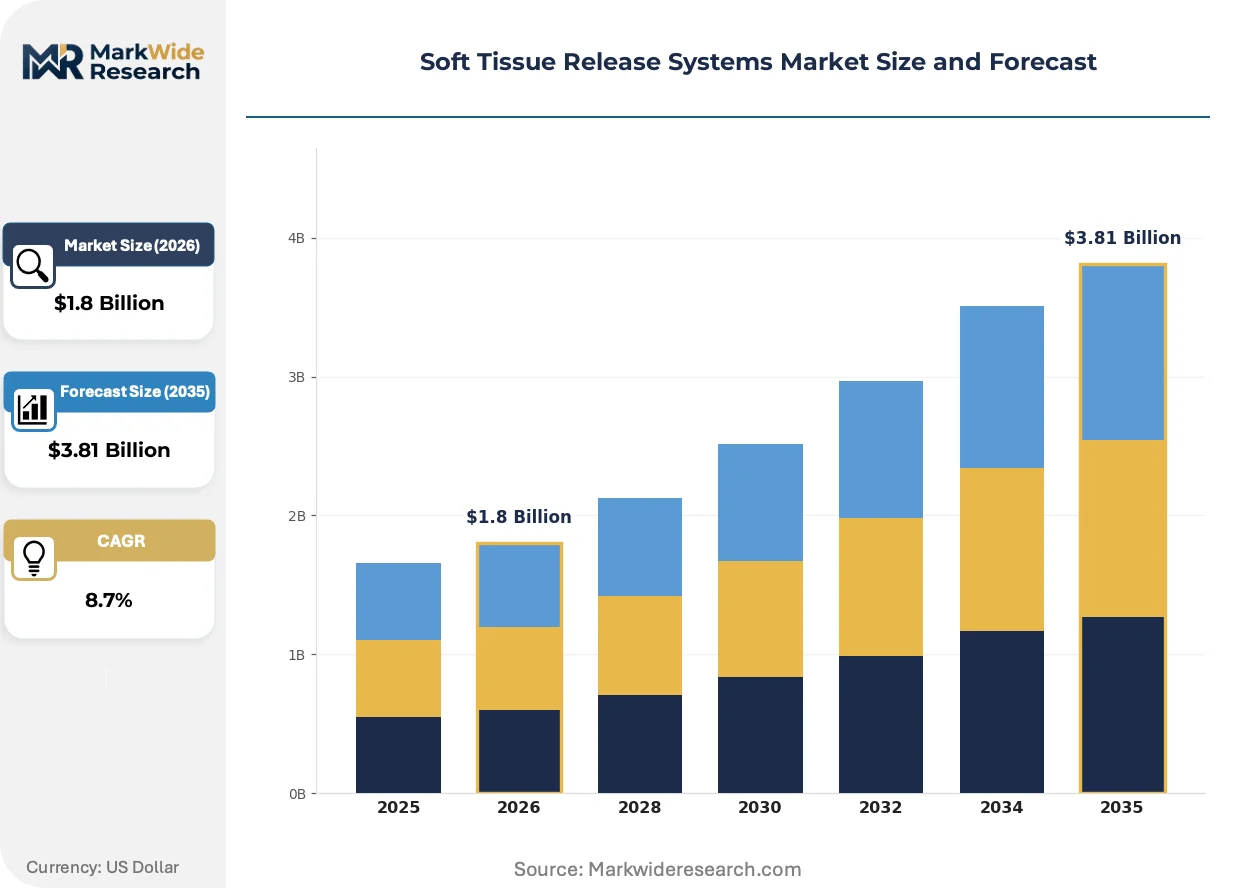
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Tools, Electrical Devices, Combination Systems, Therapeutic Units End User: Clinics, Hospitals, Physiotherapy Centers, Sports Facilities Application: Rehabilitation, Pain Management, Sports Therapy, Muscle Recovery Technology: Ultrasound Therapy, Pressure Therapy, Laser Technology, Electrostimulation |
| Companies Covered | Arthrex, Inc., Medtronic, Stryker Corporation, Smith & Nephew, Johnson & Johnson, Becton, Dickinson and Company, Zimmer Biomet, Integra LifeSciences, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Tissue Release Systems Market Evolving Landscape
Electro-mechanical system architectures are displacing purely pneumatic or manual alternatives across rehabilitation and perioperative settings, compressing the performance gap between outpatient clinics and hospital-based surgical departments.
Combination platforms integrating percussion therapy with focused ultrasound delivery are electrifying treatment protocol standardization, enabling single-device investments that previously required separate capital allocations. Outpatient orthopedic clinics in Germany and university hospital sports medicine departments are adopting these configurations at accelerated replacement cycles. The technology is compressing vendor consolidation timelines as multi-capability systems displace point-solution competitors.
Japan's PMDA has tightened quality management system audit protocols for foreign-manufactured therapeutic devices, extending approval timelines and favoring domestic joint venture structures over direct export models. This regulatory friction is redirecting market entry strategies toward licensing arrangements with established Japanese distributors. European manufacturers with existing PMDA certifications are capturing disproportionate share of new product introductions.
Hospital procurement committees are unbundling after-sales service contracts from device purchase agreements, forcing manufacturers to compete on transparent service pricing rather than bundled lifetime cost models. This behavioral shift is most visible in Germany's university hospital networks, where centralized purchasing offices now mandate separate RFP processes for equipment and maintenance. Distributors with captive service capabilities are losing competitive position to specialized third-party technical service providers.
Soft Tissue Release Systems Market Segmentation
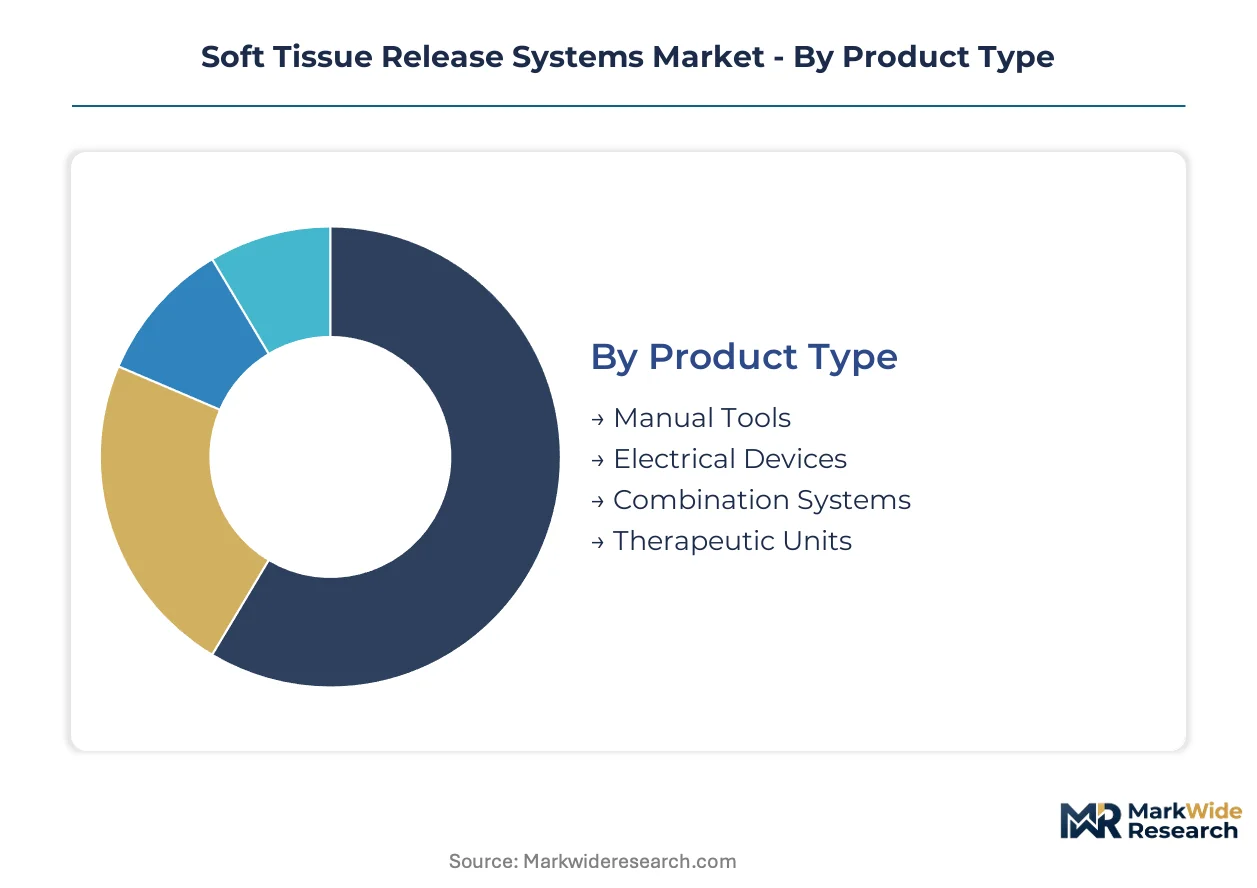
Product configuration and technology integration define procurement decisions across rehabilitation settings. Buyers balance capital constraints against treatment protocol versatility when selecting system architectures.
Product Type:
Volume leadership concentrates in manual instruments, while premium margins flow toward powered and multi-modal platforms.
- Manual Tools:Handheld fascial release instruments fabricated from surgical-grade stainless steel or polymer composites operate without external power. Germany's outpatient physiotherapy networks favor these for cost-contained practices where capital budgets limit technology adoption.
- Electrical Devices:Motorized percussion platforms delivering 2000-3200 strokes per minute with adjustable amplitude settings. University hospital sports medicine departments in the United States prioritize FDA 510(k)-cleared units for perioperative tissue preparation protocols.
- Combination Systems:Integrated platforms merging percussion and thermal modalities. These versatile configurations attract replacement demand from German rehabilitation clinics consolidating multiple treatment capabilities into single-unit investments.
- Therapeutic Units:Fixed-installation systems designed for high-throughput clinical environments. Hospital outpatient departments specify these for standardized treatment protocols across large patient volumes.
Mature deployment sits with Manual Tools. Newer deployment is concentrated in Combination Systems.
End User:
Procurement authority splits between centralized hospital purchasing offices and independent clinic operators with direct vendor relationships.
- Clinics:Outpatient orthopedic and rehabilitation facilities with discrete capital allocation authority. German clinic networks are replacing legacy manual inventories with powered platforms at accelerated replacement cycles.
- Hospitals:Integrated delivery networks with consolidated procurement committees. These buyers unbundle service contracts from device purchases, forcing transparent pricing on maintenance and technical support.
- Physiotherapy Centers:Price-sensitive operators serving chronic pain and post-surgical recovery populations. Manual instrument-assisted soft tissue mobilization retains preference where reimbursement rates constrain technology investment.
- Sports Facilities:Athletic training departments and professional team medical staff. These end users prioritize portable electro-mechanical units for field-side and locker room deployment.
Established purchasing patterns dominate Hospitals. Emerging demand concentrates in Sports Facilities.
Application:
Reimbursement pathways determine addressable market size, with perioperative and athletic applications commanding premium pricing over chronic maintenance protocols.
- Rehabilitation:Post-surgical and injury-recovery protocols requiring progressive tissue mobilization. Outpatient clinics in Germany specify combination systems for versatile treatment progression across recovery phases.
- Pain Management:Chronic myofascial pain interventions targeting trigger point disruption. These applications favor portable electrical devices for home-based therapy extensions.
- Sports Therapy:Acute injury response and performance maintenance for athletic populations. University hospital networks concentrate procurement of percussion platforms with precise frequency modulation for fascial adhesion severities.
- Muscle Recovery:Post-exertion protocols for amateur and professional athletes. Sports facilities drive demand for rapid-deployment units with minimal setup requirements.
Institutionalized protocols anchor Rehabilitation. Fastest share gains appear in Sports Therapy.
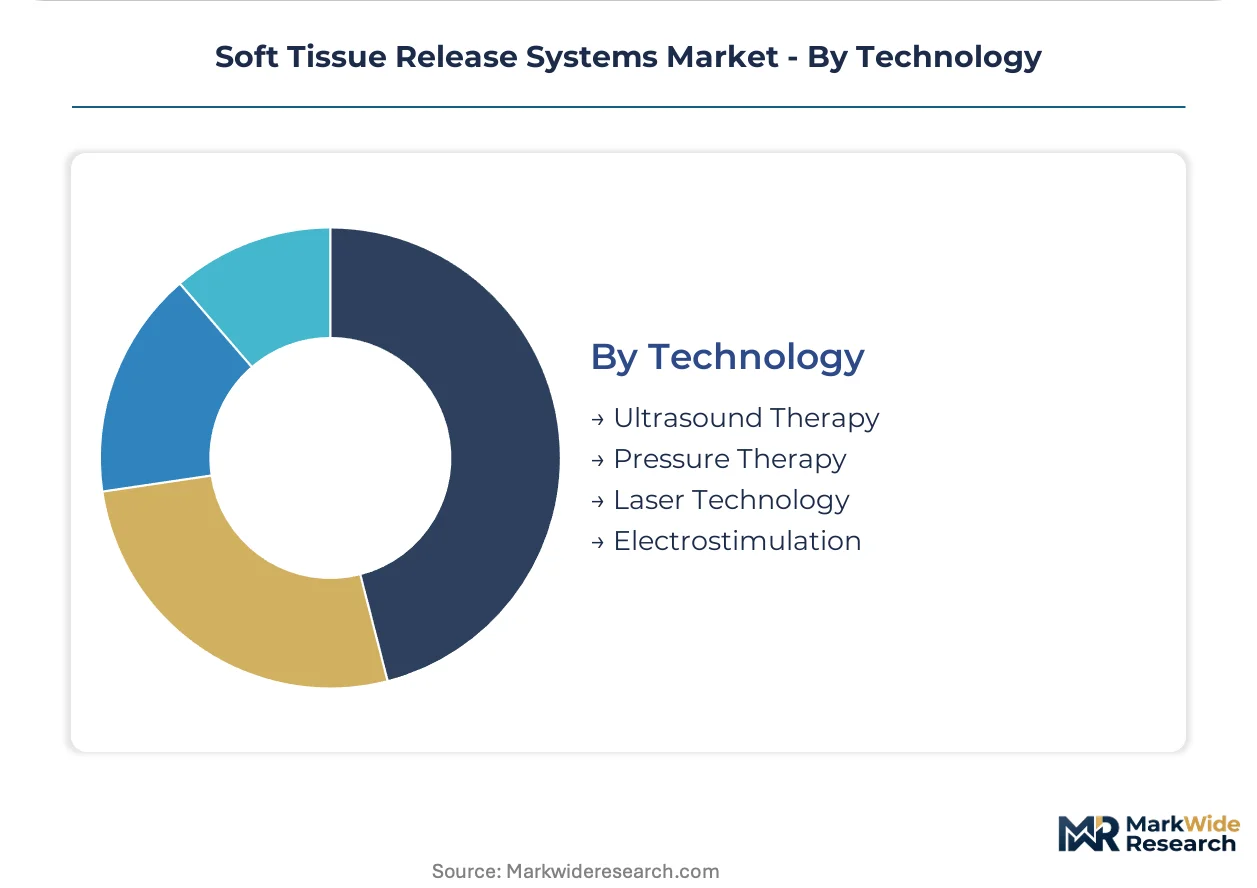
Technology:
Component sourcing geography shapes cost structures, with piezoelectric transducers and precision motors concentrating among Japanese and German suppliers.
- Ultrasound Therapy:Focused acoustic energy delivery at 1-3 MHz for therapeutic depth penetration. These modules command premium pricing due to transducer manufacturing complexity and extended supplier lead times.
- Pressure Therapy:Pneumatic or mechanical compression systems for circulatory and fascial manipulation. Physiotherapy centers favor these for straightforward operation without extensive staff training.
- Laser Technology:Low-level light therapy for tissue stimulation and inflammation modulation. Regulatory clearance requirements vary by jurisdiction, complicating multi-market product launches.
- Electrostimulation:Neuromuscular electrical stimulation for pain gating and muscle activation. Combination platforms increasingly integrate these modalities with percussion hardware for protocol standardization.
Conventional deployment centers on Pressure Therapy. Technology convergence is accelerating fastest in Electrostimulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among German outpatient rehabilitation clinics and United States university hospital networks is redirecting vendor resource allocation toward Western European and North American distribution infrastructure.
United States
University hospital sports medicine departments are consolidating purchasing agreements into centralized procurement offices. FDA 510(k) clearance pathways for Class II medical devices extend development timelines for electro-mechanical platforms. Massachusetts hosts concentrated biomedical engineering talent pools where cross-disciplinary specialists combine mechanical design with therapeutic ultrasound physics.
Germany
Outpatient orthopedic clinics are replacing manual tool inventories with powered combination systems at accelerated replacement cycles. EU MDR strengthened clinical evidence standards for CE marking filter marginal competitors from contract awards. Baden-Württemberg manufacturing clusters supply precision motor components for percussion frequency modulation systems.
Japan
METI reimbursement pathway expansions for outpatient rehabilitation devices open procurement channels previously restricted to inpatient surgical equipment. PMDA quality management system audit protocols for foreign-manufactured therapeutic devices extend approval timelines. Tokyo-based joint venture structures are displacing direct export models for European manufacturers seeking market entry.
China
NMPA regulatory harmonization efforts are streamlining quality management system requirements for domestic rehabilitation device manufacturers. SAMR oversight of medical device advertising claims tightens marketing compliance for powered therapeutic platforms. Yangtze River Delta industrial zones concentrate piezoelectric transducer assembly operations serving ultrasound therapy module producers.
United Kingdom
NHS procurement frameworks for musculoskeletal rehabilitation equipment favor suppliers with ISO 13485 certification and established service networks. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while introducing separate UKCA marking requirements. London and Southeast England hospital trusts are piloting software-integrated therapeutic platforms with embedded treatment protocol algorithms.
Soft Tissue Release Systems Market Competitive Landscape
German precision component producers anchor the supply-side tier; United States surgical device conglomerates hold the hospital contracting tier. The competitive structure concentrates among diversified medical technology portfolios rather than single-product specialists. Three archetypes dominate: arthroscopy-derived tool specialists, broad surgical portfolio anchors, and integrated power platform differentiators. Vendor consolidation accelerates through centralized purchasing agreements and unbundled service contract competitions.
Within the diversified surgical technology tier, Arthrex, Inc., Medtronic, and Stryker Corporation occupy positions reflecting distinct competitive strategies. Arthrex exemplifies the arthroscopy-derived specialist archetype, leveraging procedural tool expertise into sports therapy channels. Medtronic anchors hospital system contracts through portfolio breadth spanning multiple surgical specialties. Stryker represents integrated platform differentiation, spanning release and debridement applications through unified power tool architectures.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Medtronic |
| Stryker Corporation |
| Smith & Nephew |
| Johnson & Johnson |
| Becton, Dickinson and Company |
| Zimmer Biomet |
| Integra LifeSciences |
| Baxter International |
| Others |
Value Network & Pricing Analysis
Captive production of precision motor components and piezoelectric transducers by German and Japanese suppliers anchors both supply security and pricing power for tier-one manufacturers, while outsourced assembly operations in lower-cost geographies feed volume tiers without comparable margin capture.
Pricing Analysis
Volume leadership in manual instruments compresses margins toward commodity levels, while electrical devices and combination systems command premium positioning through FDA 510(k) certification and integrated software capabilities. Price differentiation rests on CE marking tier under EU MDR and after-sales service bundling. Pricing pressure intensifies in physiotherapy centers where reimbursement constraints favor low-cost instrument-assisted alternatives. Hospital procurement committees exhibit lowest price sensitivity, prioritizing broad device portfolios and transparent maintenance contracts.
Supply Chain Analysis
Direct-to-clinic manufacturer sales organizations are displacing traditional medical device distributors, capturing margin previously allocated to channel intermediaries. Component sourcing concentrates in Germany for precision motors, Japan for piezoelectric transducers, and China for polymer composite housings. Supply chain risk centers on single-source vulnerability for therapeutic ultrasound modules. Distribution runs through specialized third-party technical service providers as hospital procurement committees unbundle after-sales contracts from device purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence mandates are filtering marginal competitors from contract awards, consolidating procurement authority among manufacturers with robust quality management systems and established notified body relationships.
For Market Incumbents: Anchor hospital system contracts through portfolio breadth spanning multiple therapeutic modalities, not single-product positioning. Defend against emerging software-integrated platforms by accelerating HL7 interface development for major EMR architectures. Deepen backward integration into precision motor production through Baden-Württemberg manufacturing partnerships. For New Entrants and Emerging Players: Capture outpatient orthopedic clinic demand in Germany's replacement cycle for manual tool inventories, where price-constrained buyers seek versatile combination systems over standalone devices. Exploit PMDA audit backlogs by licensing to established Japanese distributors rather than pursuing direct export models. Lead with portable electro-mechanical units for sports facility deployment, a segment with minimal incumbent saturation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified surgical technology conglomerates seeking arthroscopy-derived tool expertise or integrated power platform capabilities. Long-term viability favors manufacturers with ISO 13485 certification, FDA 510(k) predicate device libraries, and software companion revenue streams. Monitor METI reimbursement pathway expansions for outpatient rehabilitation devices as inflection signal for Japanese market access valuation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Substantial equivalence determinations for electro-mechanical platforms require 8-14 month bench testing cycles. |
| EU MDR CE Marking Investment | Strengthened clinical evidence standards filter marginal competitors from German outpatient clinic contract awards. |
| Hospital System Partnership | Centralized procurement offices at university hospital networks favor suppliers with broad device portfolios. |
| Software Companion Development | Embedded treatment protocol algorithms create service revenue streams beyond device sale margins. |
| PMDA Licensing Arrangement | Joint venture structures with Tokyo-based distributors circumvent extended quality management system audit timelines. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, biomedical engineering specialist consultations, and regulatory affairs director surveys underwrites the qualitative findings. Primary fieldwork engaged GPO contracts managers, outpatient clinic operators, and sports medicine department heads. Secondary validation drew from FDA 510(k) filings, EU MDR notified body registers, and METI reimbursement pathway documentation. Bottom-up demand modeling triangulated against top-down market sizing across product configuration and end-user segments.
Rate-of-change decomposition across the analysis window separates replacement demand cycles from net new adoption, with segmentation dimensions spanning product type, end-user procurement authority, application reimbursement pathway, and technology convergence trajectory. CAGRs derive from installed base evolution and per-unit pricing trends. Forecast inputs incorporate PMDA approval timeline distributions and EU MDR notified body capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory reclassification of software-integrated therapeutic platforms and piezoelectric transducer supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Medical Connector Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
Medical Bionic Implant/Artificial Organs Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Homecare Medical Devices Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
Contact Lenses Market
Medical Devices
Wireless Neurofeedback Device Market
Medical Devices
Digital BTE Market
Medical Devices
Medical Manifolds Market
Medical Devices
Dialysis Catheters Market