
 South Korea Ophthalmic Devices Market | 2026-2036
South Korea Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Ophthalmic Devices Market Analytics
The capital-intensity gap between domestic distributors and multinational manufacturers is collapsing as local hospital procurement consolidates under group purchasing organizations. Carl Zeiss Meditec AG leverages its surgical microscope and diagnostic imaging integration to sustain premium positioning in Seoul's university-affiliated hospitals. Hoya Corporation anchors its intraocular lens portfolio through direct technical service teams embedded in Busan and Daegu surgical centers. Nidek Co. Ltd competes on ophthalmic laser maintenance density, with field engineers stationed across Daejeon and Gwangju metropolitan zones.
Ophthalmic devices encompass precision instruments for vision correction, disease diagnosis, and surgical intervention, typically incorporating optical-grade polymers, femtosecond laser sources, and software-driven image processing with sub-micron resolution thresholds. Their primary commercial purpose is restoring or preserving visual function through refractive correction, cataract extraction, or retinal disease management. Intraocular lenses capture the dominant revenue pool due to South Korea's aging surgical caseload and biocompatible material premiums, while optical coherence tomography systems lead diagnostic technology growth as retina specialists expand screening protocols. Phacoemulsification platforms remain the mature workhorse segment, with replacement cycles tied to MFDS re-registration requirements and hospital capital budget cycles.
MFDS medical device licensing, national health insurance reimbursement schedules, and KOSHA workplace safety standards collectively shape product entry timelines and pricing ceilings for imported ophthalmic equipment. The country's health technology assessment body evaluates new diagnostic platforms against existing fundus camera and OCT benchmarks, creating staged adoption curves for premium technologies. Stakeholders must monitor whether MFDS accelerates software-as-medical-device pathways for AI-enabled diagnostic tools, as this regulatory pivot would reshape competitive requirements for domestic and foreign manufacturers alike.
Market Dynamics
Hospital procurement consolidation under group purchasing organizations is collapsing the capital-intensity gap between domestic distributors and multinational manufacturers, forcing premium-positioned suppliers to defend margins through embedded technical service teams rather than equipment differentiation alone.
Growth Catalysts
- MFDS Re-registration Cycles:Mandatory device re-registration every four years accelerates hospital capital replacement of phacoemulsification platforms, creating predictable demand windows for surgical equipment vendors aligned with national health insurance reimbursement schedules.
- Greater Seoul Metropolitan Clustering:Tertiary eye hospital concentration in the capital region concentrates diagnostic service scaling, driving optical coherence tomography system deployment as retina specialists expand screening protocols.
- Femtosecond Laser Integration:Cataract surgical workflows incorporate femtosecond laser sources for corneal incision precision, with university-affiliated hospitals prioritizing platforms combining optical-grade polymer handling with software-driven image processing.
Market Restraints
- Biocompatible Material Premiums:Intraocular lens manufacturing depends on imported optical-grade polymers and hydrophobic acrylics, exposing margins to raw material cost volatility and yen-dollar exchange rate fluctuations.
- KOSHA Workplace Safety Compliance:Laser safety certification requirements for surgical suites impose capital burdens on private clinic chains, delaying equipment upgrades in secondary cities outside Busan and Daegu.
- Health Technology Assessment Benchmarking:New diagnostic platforms face staged adoption curves against existing fundus camera and OCT baselines, compressing pricing ceilings for AI-enabled screening tools.
Strategic Opportunities
- Gwangju and Daejeon Metropolitan Zones:Ophthalmic laser maintenance density remains below Seoul levels, creating whitespace for field engineering networks targeting mid-tier surgical centers with service-contract bundling.
- Software-as-Medical-Device Pathways:MFDS regulatory pivot toward AI-enabled diagnostic tool classification would reshape competitive requirements, advantaging manufacturers with embedded software validation capabilities.
- Refractive Correction Convergence:Integration of wavefront aberrometry with excimer laser platforms enables premium service tiering in private clinic chains seeking differentiation from national health insurance reimbursement rates.
Industry Challenges
- Retina Specialist Training Pipeline:OCT interpretation and surgical laser operation require fellowship-level expertise, constraining diagnostic service capacity expansion in secondary metropolitan zones.
- Legacy Equipment Integration:New phacoemulsification platforms must interface with existing surgical microscope video systems and hospital information networks, extending installation timelines and acceptance testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Ophthalmic Devices Market |
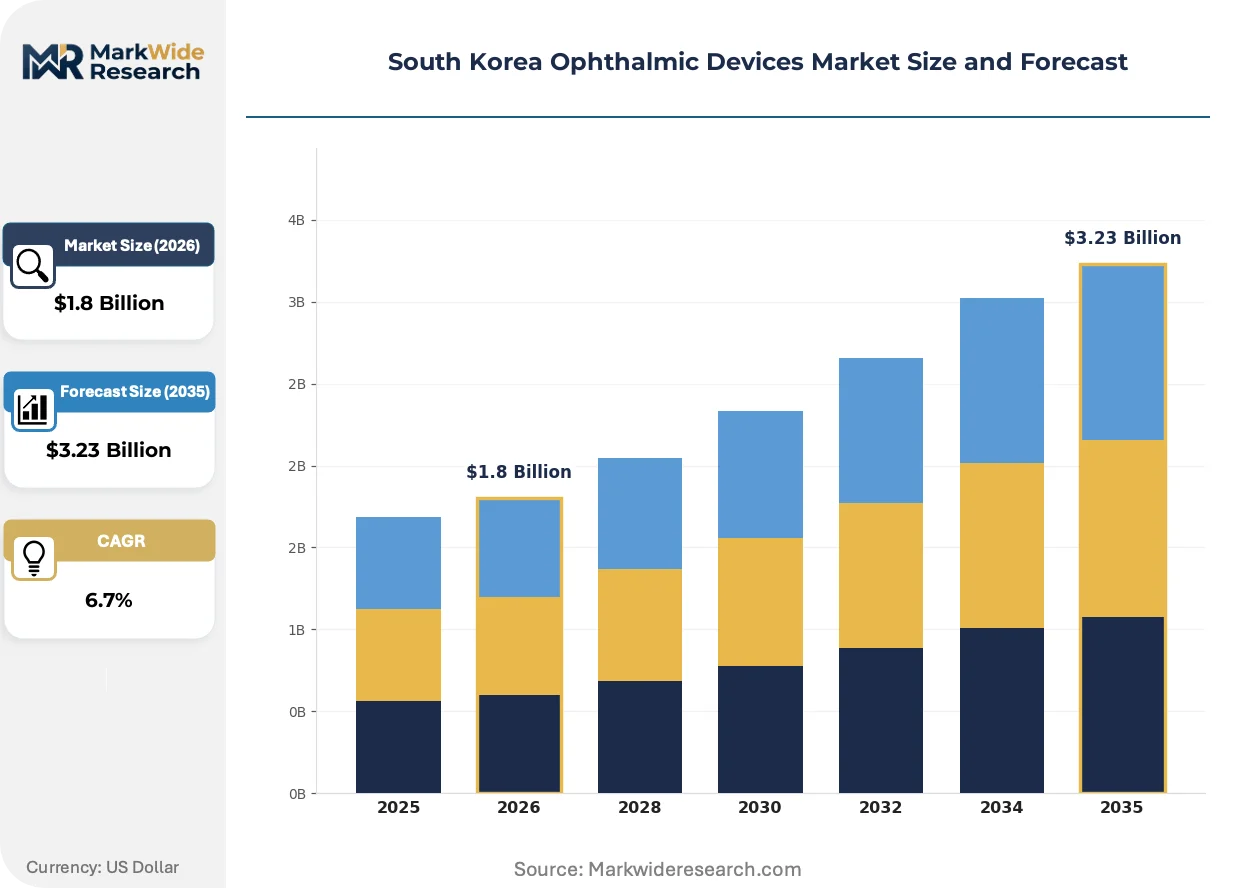
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eyeglasses, Contact Lenses, Intraocular Lenses, Surgical Instruments Technology: Laser Surgery, Optical Coherence Tomography, Phacoemulsification, Fundus Cameras End User: Hospitals, Clinics, Eye Care Centers, Optical Retail Stores Application: Vision Correction, Cataract Surgery, Glaucoma Treatment, Diagnostic Testing |
| Companies Covered | Alcon Inc., Carl Zeiss Meditec AG, Johnson & Johnson Vision, Topcon Corporation, Hoya Corporation, Nidek Co. Ltd, Bausch & Lomb Corp, Ziemer Group AG, EssilorLuxottica, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Ophthalmic Devices Market Evolving Landscape
Three interconnected shifts are compressing equipment replacement cycles and rewiring how diagnostic capabilities reach patients outside Seoul's hospital cluster: component miniaturization, regulatory pathway evolution for software-enabled tools, and procurement consolidation altering vendor selection criteria.
Handheld optical coherence tomography systems are miniaturizing retinal imaging from cart-based hospital installations to point-of-care deployment in private clinic settings. Secondary city ophthalmology practices in Daegu and Gwangju adopt these units to offer screening services without capital commitment to full-platform diagnostics. This miniaturization is compressing the addressable market for traditional cart-based OCT manufacturers while expanding serviceable geography for distributed eye care networks.
MFDS medical device licensing is accelerating software-as-medical-device classification for AI-enabled diagnostic algorithms, creating separate approval tracks from hardware-bound ophthalmic equipment. This regulatory evolution permits standalone algorithm deployment across existing installed bases of fundus cameras and OCT systems. Retina specialists in university-affiliated hospitals are piloting these tools to reduce image interpretation burden, with adoption concentrated in Seoul's tertiary centers where patient volumes justify workflow reconfiguration.
Group purchasing organizations now dominate capital equipment selection for hospital-based surgical departments, consolidating previously fragmented procurement decisions across independent ophthalmology units. Premium-positioned manufacturers respond by embedding technical service teams within purchasing coalitions rather than individual facilities. This buyer concentration is most visible in the Greater Seoul metropolitan area, where tertiary hospital networks negotiate enterprise-level phacoemulsification platform contracts with multi-year maintenance inclusions.
South Korea Ophthalmic Devices Market Segmentation
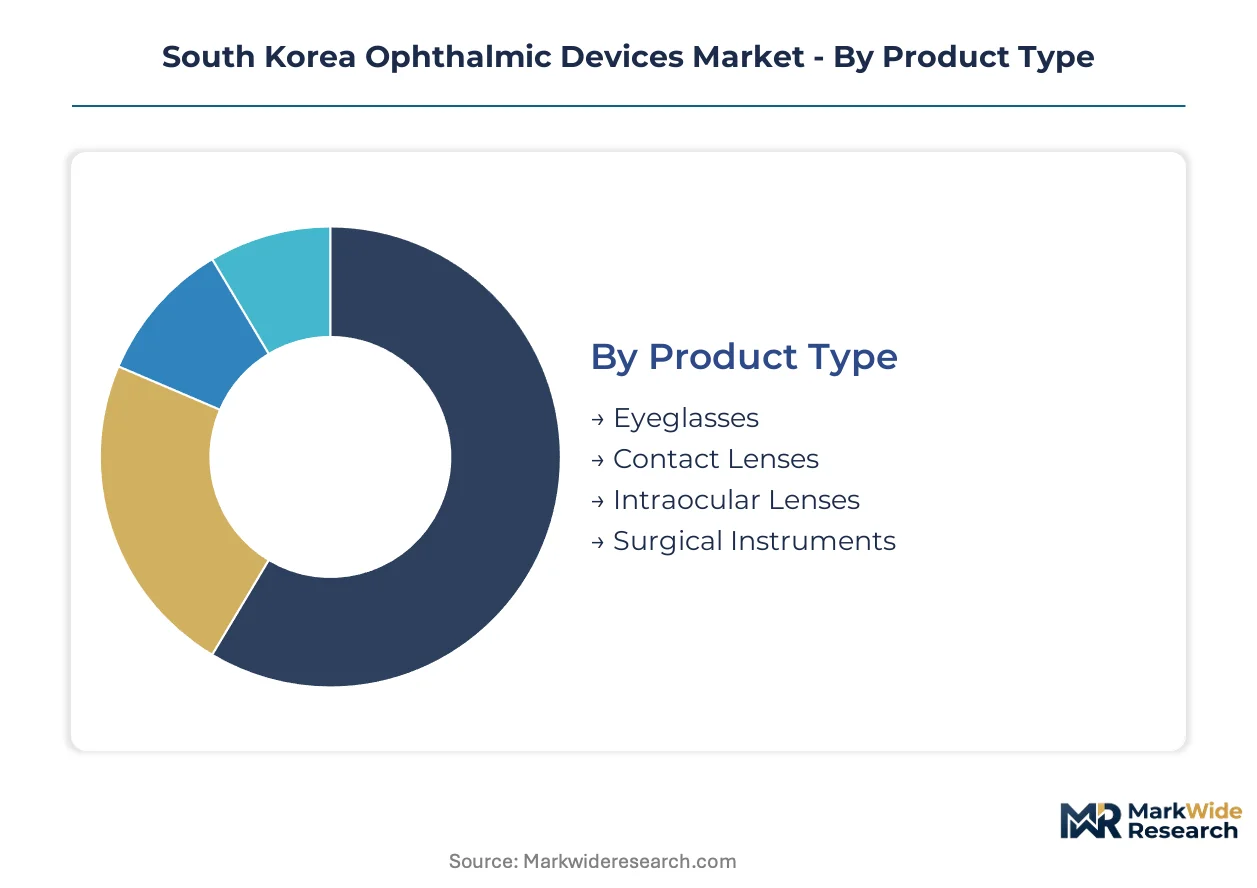
Segmentation reveals how ophthalmic device procurement channels diverge between institutional buyers and retail consumers. Understanding these pathways illuminates where pricing power concentrates and which technologies bypass traditional hospital procurement entirely.
Product Type:
Eyeglasses and contact lenses flow predominantly through optical retail chains, while surgical instruments and intraocular lenses move through consolidated hospital procurement under group purchasing organizations.
- Intraocular Lenses:Hydrophobic acrylic and silicone polymer implants replace natural lenses during cataract extraction. Demand concentrates in Seoul's tertiary eye hospitals where aging surgical caseloads drive volume, with biocompatible material premiums compressing distributor margins on imported optical-grade polymers.
- Surgical Instruments:Precision microsurgical tools including forceps, viscoelastic cannulas, and capsulorhexis cystotomes feature sub-millimeter tolerances for anterior segment procedures. Adoption accelerates in Busan and Daegu surgical centers expanding phacoemulsification capacity, constrained by MFDS four-year re-registration cycles that synchronize replacement demand.
- Eyeglasses:Corrective lenses and frames distributed through optical retail chains and franchise networks across secondary metropolitan zones.
- Contact Lenses:Daily disposable and extended-wear silicone hydrogel products sold through retail optometry channels and direct-to-consumer platforms.
By volume, eyeglasses lead. By growth pace, intraocular lenses are climbing the fastest.
Technology:
Cost tiering separates premium femtosecond laser platforms from mature phacoemulsification systems, with diagnostic imaging occupying a mid-tier capital expenditure bracket.
- Optical Coherence Tomography:Non-invasive interferometric imaging achieves sub-micron retinal resolution for macular disease monitoring. Deployment concentrates in Greater Seoul metropolitan retina specialist practices expanding screening protocols, with handheld miniaturization now penetrating Daegu and Gwangju private clinics seeking point-of-care capability without full-platform capital commitment.
- Phacoemulsification:Ultrasound-based cataract extraction platforms remain the surgical workhorse with established reimbursement codes. Replacement cycles tie directly to MFDS re-registration requirements and hospital capital budget cycles, creating predictable demand windows for vendors aligned with national health insurance schedules.
- Laser Surgery:Excimer and femtosecond laser systems for refractive correction requiring KOSHA workplace safety certification for surgical suite installation.
- Fundus Cameras:Conventional retinal photography systems serving as baseline diagnostic infrastructure in secondary city ophthalmology practices.
By installed base, phacoemulsification dominates. By expansion trajectory, OCT systems are gaining share fastest.
End User:
Customer type determines procurement leverage, with hospital networks exercising consolidated purchasing power against fragmented optical retail demand.
- Hospitals:Tertiary and secondary medical institutions with integrated ophthalmology departments performing complex surgical interventions. University-affiliated facilities in Seoul prioritize platforms combining surgical microscopes with diagnostic imaging integration, negotiating enterprise-level contracts with multi-year maintenance inclusions through group purchasing organizations.
- Clinics:Private ophthalmology practices in Busan, Daegu, and Gwangju metropolitan zones scaling diagnostic service capacity. These facilities favor service-contract bundling for ophthalmic laser maintenance, with field engineering density determining vendor selection over equipment differentiation alone.
- Eye Care Centers:Specialized vision correction facilities focusing on refractive surgery and premium service tiering outside national health insurance reimbursement structures.
- Optical Retail Stores:Franchise and independent outlets distributing corrective eyewear with minimal regulatory friction compared to surgical device procurement.
By procedure volume, hospitals lead. By network expansion pace, private clinics are ahead.
Application:
Maturity stage separates established cataract surgical workflows from emerging AI-enabled diagnostic protocols.
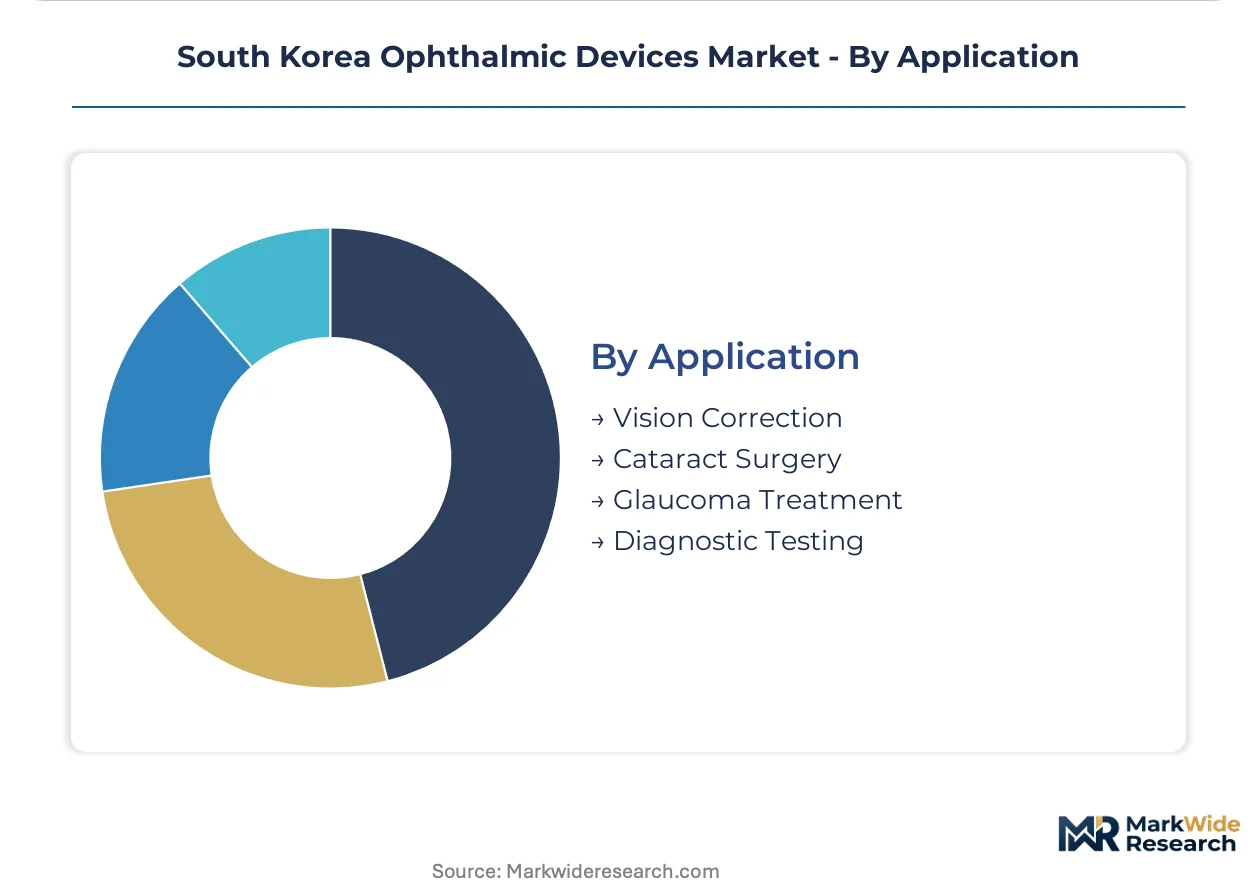
- Cataract Surgery:The dominant procedural category featuring phacoemulsification extraction with intraocular lens implantation. Caseloads concentrate in aging demographics across Seoul's hospital clusters, with femtosecond laser integration creating premium service tiering opportunities for private clinic chains seeking differentiation from standard reimbursement rates.
- Diagnostic Testing:Retinal imaging, visual field assessment, and corneal topography for disease monitoring and surgical planning. Retina specialist training pipeline constraints limit capacity expansion in secondary metropolitan zones, though AI-enabled algorithm deployment promises workflow relief in high-volume tertiary centers.
- Vision Correction:Refractive procedures including LASIK and PRK addressing myopia and astigmatism in younger patient demographics.
- Glaucoma Treatment:Surgical and pharmaceutical interventions for intraocular pressure management, with diagnostic testing overlap for progression monitoring.
By current revenue concentration, cataract surgery leads. By technology refresh rate, diagnostic testing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area commands pricing premiums for phacoemulsification platforms that secondary metropolitan zones cannot replicate, while Busan-Ulsan surgical centers negotiate service-contract bundles that compress equipment margins.
Seoul Capital Area
Tertiary eye hospitals in Gangnam and Jongno districts drive femtosecond laser platform deployment for premium cataract workflows. MFDS four-year re-registration cycles synchronize capital replacement across university-affiliated networks. Samsung Medical Center and Asan Medical Center anchor diagnostic imaging procurement through group purchasing organizations that consolidate previously fragmented ophthalmology unit decisions.
Busan-Ulsan
Surgical centers in Busan's Haeundae and Ulsan's Dong-gu districts scale phacoemulsification capacity for aging coastal demographics. KOSHA workplace safety certification requirements for laser suites impose capital burdens that delay equipment upgrades in private clinic chains. Hoya Corporation embeds direct technical service teams in Busan surgical centers to defend positioning against distributor-based competitors.
Daegu-Gyeongbuk
Kyungpook National University Hospital anchors anterior segment surgical training that sustains instrument demand across the region. National health insurance reimbursement alignment with MFDS device registration accelerates product clearance timelines for imported intraocular lenses. Daegu's Seo-gu district clusters secondary ophthalmology practices seeking service-contract bundling for ophthalmic laser maintenance.
Daejeon-Sejong
Korea University Hospital Daejeon and Sejong Chungnam National University Hospital concentrate high-volume cataract caseloads that justify OCT system deployment. Field engineering density for ophthalmic laser maintenance remains below Seoul levels, creating whitespace for vendors targeting mid-tier surgical centers. The Sejong administrative city presence shapes procurement standardization across public hospital networks.
Gwangju-Honam
Chonnam National University Hospital and private clinic chains in Gwangju's Dong-gu district adopt handheld OCT systems for point-of-care retinal screening without full-platform capital commitment. Retina specialist training pipeline constraints limit diagnostic service capacity expansion beyond the Honam region's primary metropolitan center. Nidek Co. Ltd stations field engineers across the zone to capture maintenance contract opportunities.
South Korea Ophthalmic Devices Market Competitive Landscape
Concentration sits with multinational manufacturers holding integrated surgical microscope and diagnostic imaging portfolios, while domestic distributors compete on service density rather than equipment differentiation. The market structure tiers across premium-positioned technology integrators, mid-tier instrument specialists, and retail-facing optical chains. Strategic moves center on embedding technical service teams within purchasing coalitions and bundling multi-year maintenance inclusions into enterprise-level contracts.
Among Germany-based precision optics manufacturers, Carl Zeiss Meditec AG exemplifies the integrated platform archetype combining surgical visualization with diagnostic imaging. Japanese specialists including Hoya Corporation and Nidek Co. Ltd occupy positions defined by field engineering density and maintenance contract penetration in secondary metropolitan zones. These three anchors represent distinct competitive vectors: technology integration, material science, and service network coverage.
| Leading Market Players |
|---|
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Johnson & Johnson Vision |
| Topcon Corporation |
| Hoya Corporation |
| Nidek Co. Ltd |
| Bausch & Lomb Corp |
| Ziemer Group AG |
| EssilorLuxottica |
| Others |
Value Network & Pricing Analysis
Optical-grade polymer substitution for traditional PMMA intraocular lens substrates simultaneously relocates manufacturing gravity toward Japanese and German material suppliers and compresses margin capture for Korean distributors caught between yen-denominated raw material contracts and national health insurance reimbursement ceilings.
Pricing Analysis
The customization-premium spread between femtosecond laser-integrated phacoemulsification platforms and standard ultrasound-based systems widens as university-affiliated hospitals in Seoul negotiate configured-to-order surgical workflows. Three-tier pricing structure across premium, standard, and economy levels separates equipment with embedded diagnostic imaging from standalone surgical tools. Pricing pressure stems from group purchasing organization consolidation that collapses distributor margins on imported intraocular lenses. Private clinic chains in secondary metropolitan zones exhibit highest price sensitivity, while tertiary eye hospitals in Gangnam prioritize technical service density over unit cost.
Supply Chain Analysis
Inventory lead times for hydrophobic acrylic intraocular lens blanks extend when MFDS re-registration cycles synchronize replacement demand across hospital networks. Manufacturing concentrates in Japan, Germany, and Switzerland for optical-grade polymers and precision laser sources. Raw material dependencies include hydrophobic acrylics, femtosecond laser crystals, and surgical-grade titanium alloys. Single-source vulnerability pervades femtosecond laser engine supply. Distribution runs through group purchasing organizations that consolidate previously fragmented hospital procurement decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution defense against AI-enabled diagnostic algorithms that MFDS may reclassify as standalone medical devices, bypassing traditional hardware-bound equipment procurement channels entirely.
For Market Incumbents: Shield integrated platform positioning by embedding software validation capabilities ahead of potential MFDS software-as-medical-device pathway acceleration. Deepen backward integration into optical-grade polymer handling to offset yen-denominated raw material volatility. Prioritize multi-year maintenance inclusions in enterprise contracts with Seoul's group purchasing organizations to lock out distributor-based competitors.
For New Entrants and Emerging Players: Anchor in Gwangju and Daejeon metropolitan zones where ophthalmic laser maintenance density remains below Seoul levels and field engineering networks are sparse. Target mid-tier surgical centers with service-contract bundling that incumbent multinationals underserve. Pursue handheld OCT miniaturization for private clinic chains seeking point-of-care capability without full-platform capital commitment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic distributors holding established MFDS registration portfolios but lacking technical service density. Five-to-ten year viability hinges on whether AI-enabled diagnostic tools trigger regulatory reclassification that favors software-native entrants over hardware incumbents. Monitor MFDS guidance documents on algorithm validation requirements as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Software-as-Medical-Device Pathway Investment | Early alignment with regulatory pivot advantages manufacturers against hardware-bound competitors when AI diagnostic classification finalizes. |
| Embedded Field Engineering Network Expansion | Service density in Busan and Daegu surgical centers defends positioning as group purchasing organizations consolidate procurement leverage. |
| Optical-Grade Polymer Backward Integration | Captive supply of hydrophobic acrylics insulates margins from yen-dollar exchange rate volatility affecting imported lens substrates. |
| Handheld OCT Miniaturization Development | Point-of-care deployment in Gwangju private clinics expands addressable geography beyond cart-based hospital installations. |
| University-Affiliated Hospital Partnership Program | Enterprise-level contracts with Samsung Medical Center and Asan Medical Center anchor premium platform adoption in Seoul's tertiary cluster. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with ophthalmic device procurement managers, biomedical engineers at tertiary eye hospitals, GPO contracts managers, and retina specialists, alongside secondary validation through MFDS device registration databases, national health insurance reimbursement schedules, hospital procurement records, and Korean customs import data for optical-grade polymers. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates across the projection horizon.
Across the modeling period, the analytical framework segmented demand by product type, technology tier, end-user procurement channel, and metropolitan regional cluster. CAGRs derived from equipment replacement cycle analysis tied to MFDS four-year re-registration requirements and hospital capital budget synchronization. Forecast inputs incorporated femtosecond laser integration adoption curves and AI-enabled diagnostic algorithm pilot deployment rates in Seoul's university-affiliated centers.
Decision-makers should treat outputs as directional under assumptions of stable MFDS regulatory classification and continued group purchasing organization consolidation; material deviation in software-as-medical-device pathway timing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Mask Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Intelligent Prosthetics Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Lactate Meter Market
Medical Devices
Plastic Surgery Scaffolds Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Cyberknife Technology Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Keratoprosthesis (Kpro) Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
ECG Patch and Holter Monitor Market