
 Distraction Osteogenesis Devices Market | 2026-2036
Distraction Osteogenesis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Distraction Osteogenesis Devices Market Analysis
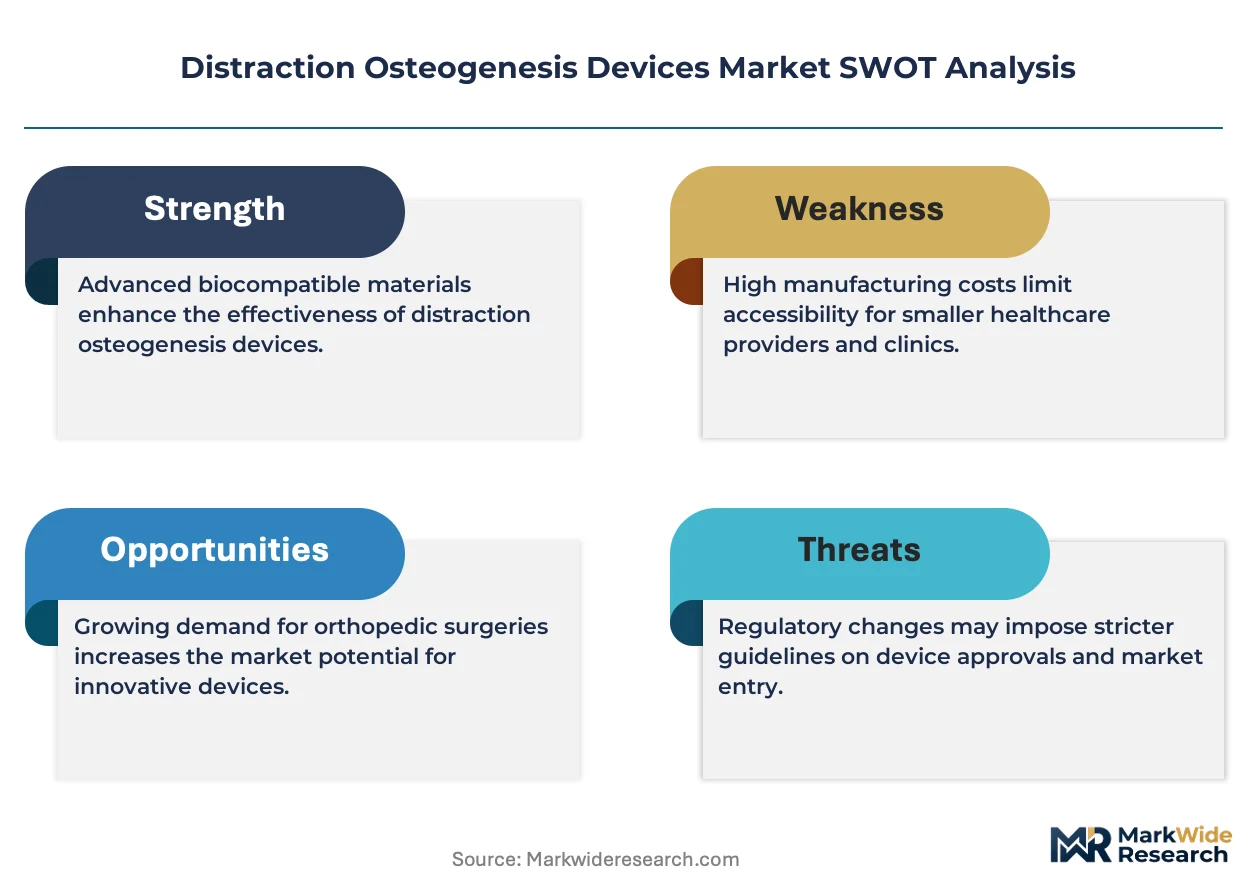
Asset-light leasing models for high-cost external fixator systems is tilting competitive dynamics toward mid-tier hospitals that previously deferred capital expenditure. Stryker Corporation leverages its institutional financing partnerships to place programmable distraction systems in surgical centers without upfront purchase requirements. Zimmer Biomet Holdings anchors its position through captive supply of titanium alloy components that reduce per-procedure material costs for hospital buyers.
Distraction osteogenesis devices are mechanical or electromechanical systems designed to apply controlled, gradual traction forces across a surgically created osteotomy gap, typically achieving distraction rates of 0.5–1.5 mm per day to stimulate de novo bone formation. These systems serve primarily to correct limb length discrepancies, craniofacial deformities, and skeletal defects where conventional grafting proves inadequate. Internal devices command the deepest margin pools due to premium pricing for patient-specific implant geometries and reduced pin-tract infection burden. Smart implant systems represent the fastest-expanding technology category as embedded sensors enable real-time distraction monitoring and automated rate adjustment protocols.
FDA 510(k) clearance requirements govern orthopedic implant commercialization in the United States, while the EU Medical Device Regulation mandates notified body certification and post-market surveillance for European distribution. Japan's PMDA enforces JIS-compliant biocompatibility testing that extends approval timelines for foreign manufacturers. Stakeholders must weigh regulatory capital requirements against the clinical differentiation offered by programmable and sensor-integrated platforms.
Market Dynamics
Programmable distraction systems with embedded sensors are compressing the gap between external fixator affordability and internal implant precision, forcing manufacturers to defend margin pools across both categories simultaneously.
Growth Catalysts
- Pediatric Craniofacial Expansion:University hospital networks in the United States are establishing dedicated distraction osteogenesis units to address congenital mandibular hypoplasia and craniosynostosis. These centers generate procedural volume that amortizes device acquisition costs across high-complexity cases.
- EU Medical Device Regulation Streamlining:MDR Article 52.3 provisions for legacy device equivalence are accelerating notified body certification timelines for iterative implant designs. Manufacturers leveraging this pathway reduce time-to-market for next-generation external fixator platforms.
- Titanium Alloy Biocompatibility:Advances in additive manufacturing of patient-specific internal distractors are eliminating machining constraints on implant geometry. Orthopedic centers in Germany report reduced revision rates when deploying these customized geometries for complex limb lengthening sequences.
Market Restraints
- Niobium-Titanium Supply Concentration:Superelastic alloy feedstock for internal distractor springs concentrates among three Japanese and German metallurgical suppliers. Price volatility in this input directly compresses gross margins for implant manufacturers without backward integration into raw material sourcing.
- PMDA Biocompatibility Testing Burden:Japan's JIS T 0306 cytotoxicity and sensitization requirements extend approval timelines by 14-18 months for foreign manufacturers. This regulatory friction deters mid-tier competitors from entering the Japanese market, preserving incumbent dominance.
- External Fixator Infection Liability:Pin-tract osteomyelitis rates of 15-25% in prolonged external fixation create malpractice exposure that restrains adoption in litigious jurisdictions. Hospital risk committees in the United States increasingly mandate internal device preference for elective lengthening procedures.
Strategic Opportunities
- Leasing Model Penetration:Asset-light financing structures for programmable external systems are unlocking mid-tier surgical centers previously excluded by capital expenditure thresholds. Stryker's institutional partnerships demonstrate viability of subscription-based device access in the United States.
- Smart Implant Convergence:Integration of strain-gauge sensors with Bluetooth telemetry is hybridizing mechanical distraction with real-time bone formation monitoring. This technology convergence commands premium pricing in pediatric orthopedic segments where growth-plate preservation demands precise rate control.
- Brazilian Reimbursement Expansion:ANVISA's 2023 inclusion of congenital limb deficiency in SUS coverage criteria is creating addressable demand for cost-optimized external fixator systems. Manufacturers with localized production through Mercosur trade agreements capture tariff-advantaged positioning.
Industry Challenges
- Craniofacial Surgical Training Bottlenecks:The 6-8 year fellowship pipeline for distraction osteogenesis specialization constrains procedural capacity expansion. Academic medical centers in Germany and the United States compete aggressively for limited qualified surgeons, inflating compensation and limiting device utilization growth.
- 510(k) Predicate Device Saturation:FDA's narrowing of acceptable predicates for internal distractor submissions is extending clearance timelines and increasing clinical data requirements. Manufacturers face escalating regulatory affairs expenditure to establish substantial equivalence for iterative designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distraction Osteogenesis Devices Market |
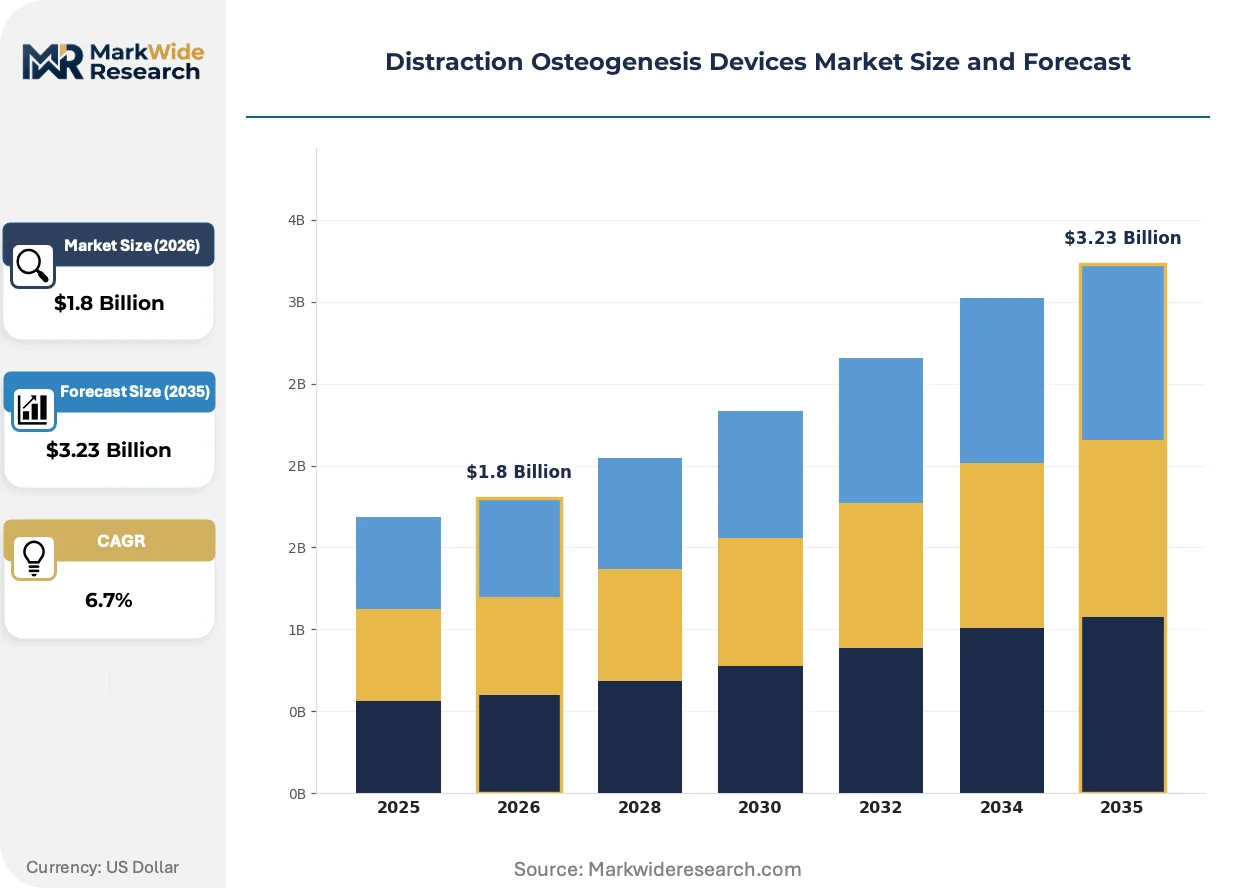
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Devices, External Devices, Hybrid Devices, Biodegradable Devices Application: Craniofacial Surgery, Limb Lengthening, Orthopedic Reconstructive Surgery, Maxillofacial Procedures End User: Hospitals, Clinics, Surgical Centers, Research Institutions Technology: Mechanical Distraction, Electrical Distraction, Programmable Devices, Smart Implant Systems |
| Companies Covered | Acumed LLC, Stryker Corporation, Johnson & Johnson, KLS Martin Group, Zimmer Biomet Holdings, Jeil Medical Corporation, OsteoMed, Titamed, Arthrex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distraction Osteogenesis Devices Market Emerging Trajectories
Sensor-integrated distraction platforms are collapsing the distinction between intraoperative precision and postoperative monitoring, enabling closed-loop rate adjustment that reduces physician intervention burden and patient compliance failure.
Shape-memory alloy actuation is hybridizing external fixator affordability with internal device automation. Nitinol-based motorized distractors eliminate manual turning protocols while maintaining percutaneous adjustability. Pediatric orthopedic centers in the United States are piloting these systems for femoral lengthening in adolescent patients. This hybridization is compressing the price-performance gap between mechanical external frames and fully implanted programmable units.
MDR Article 83 post-market surveillance requirements are mandating systematic implant registry participation across European Economic Area member states. Manufacturers must now fund prospective clinical follow-up studies as a condition of continued CE marking. High-volume limb lengthening centers in Germany and France are consolidating their purchasing toward suppliers with demonstrated registry compliance, disadvantaging smaller competitors with limited pharmacovigilance infrastructure.
Hospital procurement committees are unbundling device acquisition from surgical training and postoperative monitoring services. Orthopedic centers in the United States now separately contract distraction osteogenesis education programs from academic affiliates rather than accepting vendor-bundled packages. This disintermediation is visible most acutely in Texas and California, where surgical volume concentration gives buyers leverage to demand transparent service line-item pricing from Stryker and Zimmer Biomet representatives.
Distraction Osteogenesis Devices Market Segmentation
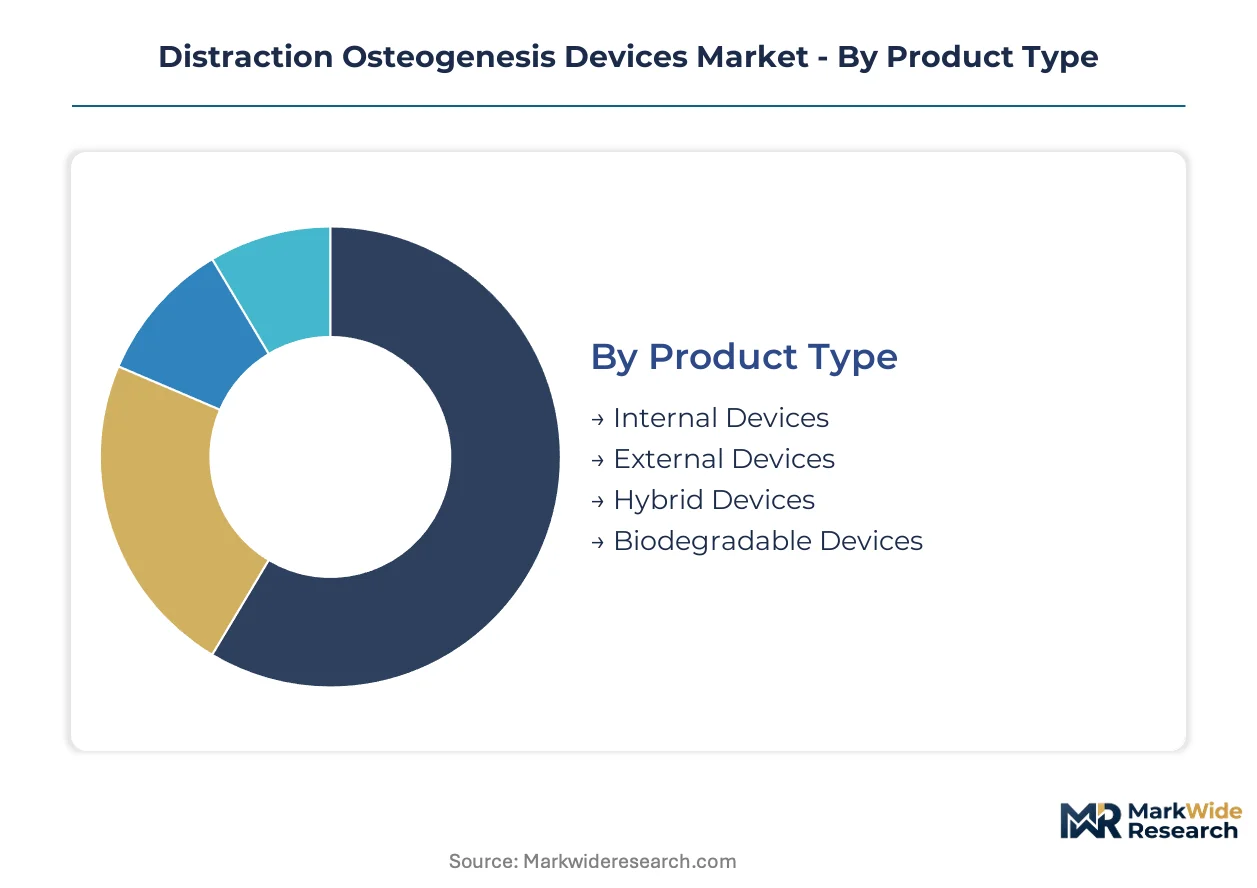
Distraction osteogenesis devices fragment across mechanical sophistication, anatomical target, and care setting economics. Segmentation reveals where premium pricing power concentrates versus where volume commoditization threatens margin pools.
Product Type:
Use-case spectrum spans fully implanted precision systems to percutaneous external frames, with hybrid architectures emerging at the interface.
- Internal Devices:Fully implanted titanium or cobalt-chrome distractors with integrated activation mechanisms eliminate pin-tract infection pathways. German university hospitals report preference for these systems in elective limb lengthening where cosmetic outcome drives patient selection. Premium pricing reflects patient-specific additive manufacturing and reduced revision liability.
- External Devices:Ring fixators and unilateral frames apply distraction through percutaneous pins connected to external mechanical assemblies. Mid-tier surgical centers in the United States leverage Stryker's leasing models to access programmable external systems without capital outlay. Infection burden and patient compliance gaps constrain adoption in litigious jurisdictions.
- Hybrid Devices:Percutaneous systems with motorized internal components bridge external adjustability with automated rate control.
- Biodegradable Devices:Poly-lactic acid and magnesium alloy constructs eliminate explantation surgery in pediatric craniofacial applications.
Established volume favors External Devices; emerging adoption favors Smart Implant Systems.
Application:
Anatomical complexity and reimbursement density shape segment profitability across cranial, facial, and appendicular targets.
- Craniofacial Surgery:Mandibular and midface distraction for congenital hypoplasia and craniosynostosis requires submillimeter precision with growth-plate preservation protocols. Pediatric orthopedic centers in the United States are establishing dedicated units for these procedures, generating procedural volume that amortizes device acquisition costs. FDA 510(k) predicates for craniofacial distractors face narrowing acceptance, extending clearance timelines.
- Limb Lengthening:Femoral and tibial distraction for congenital deficiency or post-traumatic discrepancy commands the largest absolute procedure volume. German limb lengthening units report reduced revision rates when deploying patient-specific internal geometries for complex sequences. Titanium alloy biocompatibility advances are eliminating machining constraints on implant geometry.
- Orthopedic Reconstructive Surgery:Post-oncologic and post-infectious bone defect reconstruction utilizes distraction osteogenesis where grafting proves inadequate.
- Maxillofacial Procedures:Alveolar ridge distraction for dental implant site preparation represents a volume-constrained niche with high margin per procedure.
Procedure concentration favors Limb Lengthening; technology premium capture favors Craniofacial Surgery.
End User:
Capital intensity and case complexity stratify demand across integrated delivery networks and ambulatory settings.
- Hospitals:Academic medical centers with fellowship-trained craniofacial surgeons capture high-complexity cases requiring hybrid operating room infrastructure. University hospital networks in the United States compete aggressively for limited qualified surgeons, inflating compensation and consolidating device purchasing leverage. Risk committees increasingly mandate internal device preference for elective lengthening.
- Surgical Centers:Ambulatory facilities with institutional financing partnerships access programmable external systems through subscription models. Texas and California surgical volume concentration gives buyers leverage to demand transparent service line-item pricing.
- Clinics:Outpatient settings concentrate on postoperative monitoring and rehabilitation rather than device-intensive procedures.
- Research Institutions:Academic centers drive smart implant development through NIH and EU Horizon funding for sensor-integrated platforms.
Purchasing consolidation favors Hospitals; financing innovation favors Surgical Centers.
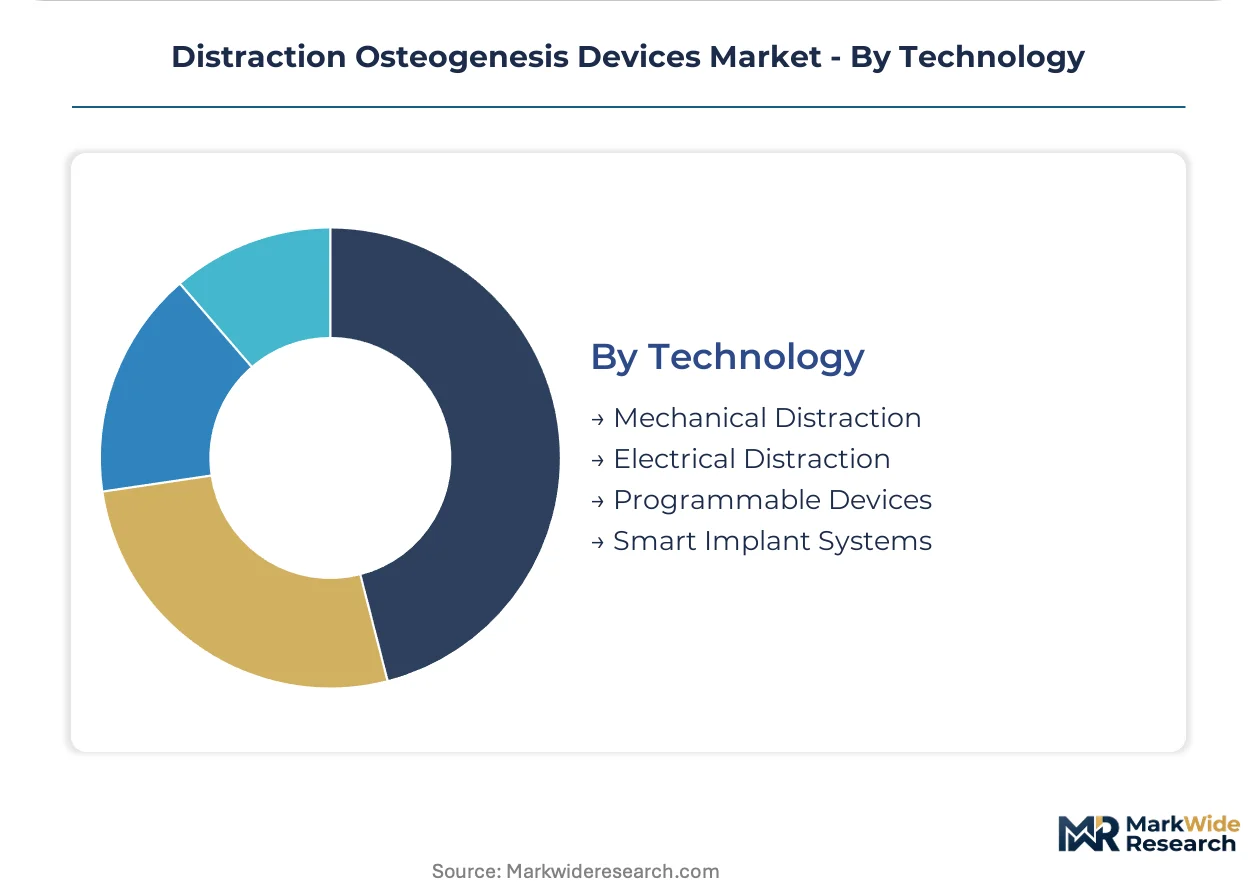
Technology:
Automation sophistication and data integration define competitive differentiation across mechanical, electromechanical, and sensor-embedded architectures.
- Smart Implant Systems:Strain-gauge sensors with Bluetooth telemetry enable real-time bone formation monitoring and closed-loop rate adjustment. Pediatric orthopedic segments command premium pricing where growth-plate preservation demands precise control. These systems are expanding most quickly as embedded sensors collapse the distinction between intraoperative precision and postoperative monitoring.
- Programmable Devices:Motorized distraction with pre-set rate protocols reduces physician intervention burden and patient compliance failure. EU MDR Article 83 post-market surveillance mandates systematic registry participation, consolidating purchasing toward suppliers with demonstrated compliance.
- Mechanical Distraction:Manual turning protocols dominate cost-sensitive markets and legacy installed bases.
- Electrical Distraction:Piezoelectric and electromagnetic actuation remains experimental outside Japanese and German research centers.
Revenue concentration favors Programmable Devices; steepest expansion trajectory favors Smart Implant Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement expansion for congenital limb deficiency and craniofacial reconstruction is redirecting procurement investment toward specialized orthopedic centers across multiple geographies. Regulatory streamlining in the European Union and targeted coverage mandates in Brazil are accelerating device placement timelines. Academic medical networks compete aggressively for fellowship-trained surgeons to staff dedicated distraction osteogenesis units.
United States
Pediatric orthopedic centers at university hospitals are establishing standalone craniofacial surgery programs with dedicated distraction units. FDA's 510(k) clearance pathway for orthopedic implants shapes product development timelines, though predicate device saturation is extending submissions for iterative internal distractor designs. Texas and California surgical volume concentration gives buyers leverage to demand transparent service line-item pricing from device representatives.
Germany
University hospitals maintain specialized limb lengthening units that generate procedural volume amortizing device acquisition costs across high-complexity cases. EU Medical Device Regulation Article 52.3 provisions for legacy device equivalence accelerate notified body certification timelines for iterative implant designs. High-volume centers in Germany and France consolidate purchasing toward suppliers with demonstrated MDR Article 83 registry compliance, disadvantaging smaller competitors.
Japan
PMDA enforces JIS T 0306 cytotoxicity and sensitization requirements that extend approval timelines by 14-18 months for foreign manufacturers. This regulatory friction deters mid-tier competitors from entering the Japanese market, preserving incumbent dominance. Superelastic alloy feedstock for internal distractor springs concentrates among Japanese metallurgical suppliers, creating supply-side dependencies for implant manufacturers without backward integration.
Brazil
ANVISA's 2023 inclusion of congenital limb deficiency in SUS coverage criteria creates addressable demand for cost-optimized external fixator systems. Manufacturers with localized production through Mercosur trade agreements capture tariff-advantaged positioning. Hospital procurement committees in São Paulo and Rio de Janeiro surgical clusters prioritize suppliers offering bundled training and postoperative monitoring services.
United Kingdom
NHS England specialized commissioning frameworks for rare congenital conditions concentrate distraction osteogenesis procedures at designated supra-regional centers. MHRA post-Brexit regulatory alignment with EU MDR maintains CE marking recognition for legacy devices while requiring UKCA marking for new submissions. London and Birmingham academic medical centers compete for limited fellowship-trained craniofacial surgeons, inflating compensation and consolidating device purchasing leverage.
Distraction Osteogenesis Devices Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where leasing innovation and captive supply chains determine account access. The vendor base stratifies between diversified orthopedic conglomerates with institutional financing partnerships and mid-tier specialists with metallurgical or regional advantages. Three archetypes dominate: scale-driven platform suppliers with subscription-based device access, precision-manufacturing specialists with titanium alloy backward integration, and regional champions with regulatory home-field advantage. Competitive moves center on M&A to secure sensor-integrated technology and capacity expansion into Mercosur production zones.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings occupy positions as scale-driven platform suppliers with institutional financing partnerships enabling asset-light device placement. Johnson & Johnson represents the integrated health systems archetype with captive supply chain leverage. KLS Martin Group exemplifies the European precision-manufacturing specialist with metallurgical capabilities. Jeil Medical Corporation anchors the regional champion position with PMDA regulatory home-field advantage in Japan.
| Leading Market Players |
|---|
| Acumed LLC |
| Stryker Corporation |
| Johnson & Johnson |
| KLS Martin Group |
| Zimmer Biomet Holdings |
| Jeil Medical Corporation |
| OsteoMed |
| Titamed |
| Arthrex Inc. |
| Others |
Supply Flow & Price Mechanics
Japanese and German metallurgical suppliers control niobium-titanium superelastic alloy feedstock, anchoring margin pools in internal distractor manufacturing and forcing device makers without backward integration to absorb raw material volatility. This upstream concentration shapes downstream pricing power, as captive alloy sourcing separates premium internal implant producers from external fixator competitors exposed to spot market swings.
Pricing Analysis
Certification level creates the primary spread across FDA 510(k)-cleared, CE-marked, and non-certified tiers. Three-tier pricing structure across premium, standard, and economy levels reflects patient-specific additive manufacturing, programmable automation, and manual mechanical systems. Cost compression in standard-tier external fixators is intensifying because Stryker's leasing models eliminate capital barriers for mid-tier surgical centers. Hospital purchasing committees exhibit highest price sensitivity for external devices, while pediatric craniofacial centers demonstrate lowest sensitivity due to malpractice liability and growth-plate precision requirements.
Supply Chain Analysis
Extended payment terms from Japanese metallurgical suppliers and supply-chain finance facilities from institutional equipment lessors shape working capital structures for device manufacturers. Production concentrates in Germany, Japan, and the United States for precision-machined titanium components and sensor-integrated assemblies. Feedstock draws from niobium-titanium alloy, cobalt-chrome bar stock, and piezoelectric sensor substrates. Single-source vulnerability in Japanese superelastic alloy supply creates tariff-exposed risk for European and North American implant makers. Distribution runs through orthopedic GPOs, direct hospital contracting, and surgical center subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defensive moats in distraction osteogenesis devices rest on regulatory entrenchment, where FDA 510(k) predicate saturation and EU MDR registry compliance create switching costs that lock in incumbent hospital relationships.
For Market Incumbents: Entrench position through captive niobium-titanium alloy sourcing and MDR Article 83 registry infrastructure that smaller competitors cannot replicate. Additive manufacturing capacity in Germany preserves margin pools against emerging hybrid device threats. Certification investment in Brazil's ANVISA pathway captures SUS reimbursement expansion before regional champions consolidate. For New Entrants and Emerging Players: Pursue white-space in cost-optimized external fixator systems for Brazil's SUS-covered congenital limb deficiency segment. Target mid-tier surgical centers in Texas and California with transparent service line-item pricing that disintermediates vendor-bundled packages. Go-to-market angle: subscription-based device access with bundled postoperative monitoring education. For Investors and Strategic Acquirers: Capital is best deployed toward precision-manufacturing specialists with metallurgical backward integration and demonstrated MDR registry compliance. Long-term viability favors suppliers with sensor-integrated platform pipelines and pediatric orthopedic center relationships. Signal to watch: consolidation of purchasing toward registry-compliant suppliers in German and French high-volume limb lengthening centers.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Article 83 Registry Compliance | CE marking continuation in EU requires systematic implant registry participation, consolidating purchasing leverage. |
| Sensor-Integrated Platform Development | Bluetooth telemetry and strain-gauge integration commands premium pricing in pediatric growth-plate preservation segments. |
| Niobium-Titanium Backward Integration | Captive superelastic alloy sourcing insulates gross margins from Japanese-German supplier price volatility. |
| Brazilian Localized Production | Mercosur tariff advantages position cost-optimized external fixators for ANVISA SUS reimbursement expansion. |
| Leasing Model Penetration | Asset-light financing unlocks mid-tier surgical centers previously excluded by capital expenditure thresholds. |
Methodological Framework
A spread of perspectives from orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation against FDA 510(k) filings, EU MDR notified body certifications, CMS Medicare reimbursement databases, and orthopedic GPO contract repositories. Bottom-up procedural volume estimates triangulated against top-down device manufacturer revenue disclosures.
Demand-supply balance across the analysis window reflects modeled segmentation by device type, anatomical application, end-user setting, and automation technology tier. CAGRs derived from procedure volume growth rates, reimbursement expansion trajectories, and replacement cycle dynamics for programmable and smart implant systems. Forecast inputs include fellowship-trained surgeon pipeline constraints, predicate device saturation effects on FDA clearance timelines, and MDR registry compliance consolidation patterns.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, orthopedic implant reimbursement rates, or titanium alloy commodity pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory streamlining, training pipeline expansion, and sensor-integrated platform adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Global Pupillometer Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Creatinine Meter Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Asia-Pacific General Surgical Devices Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
Global Artificial Organ Market