
 Phlebotomy Equipments Market | 2026-2036
Phlebotomy Equipments Market Size, Share, and Industry Trends Forecast 2026-2036
Phlebotomy Equipments Market Outlook
Modular bundling of blood collection tubes with safety-engineered needle systems is hardening as the preferred procurement format for hospital systems. Becton, Dickinson and Company leverages its integrated manufacturing footprint to dominate this bundled segment. Cardinal Health anchors its position through extensive distributor relationships across acute-care networks. Greiner Bio-One differentiates via specialization in plastic-engineered tube technologies with advanced additive coatings.
Phlebotomy equipments comprise instruments and consumables engineered for venous access, blood specimen collection, and containment, with tube specifications defined by draw volume, anticoagulant type, and closure material to preserve sample integrity for downstream analysis. Blood collection tubes command the largest product segment due to recurring consumption volume and material formulation requirements. Safety devices represent the fastest-expanding category, driven by OSHA needlestick regulations and institutional liability reduction priorities. Diagnostic laboratories generate the highest-margin end-user demand through high-throughput processing requirements and premium product specifications.
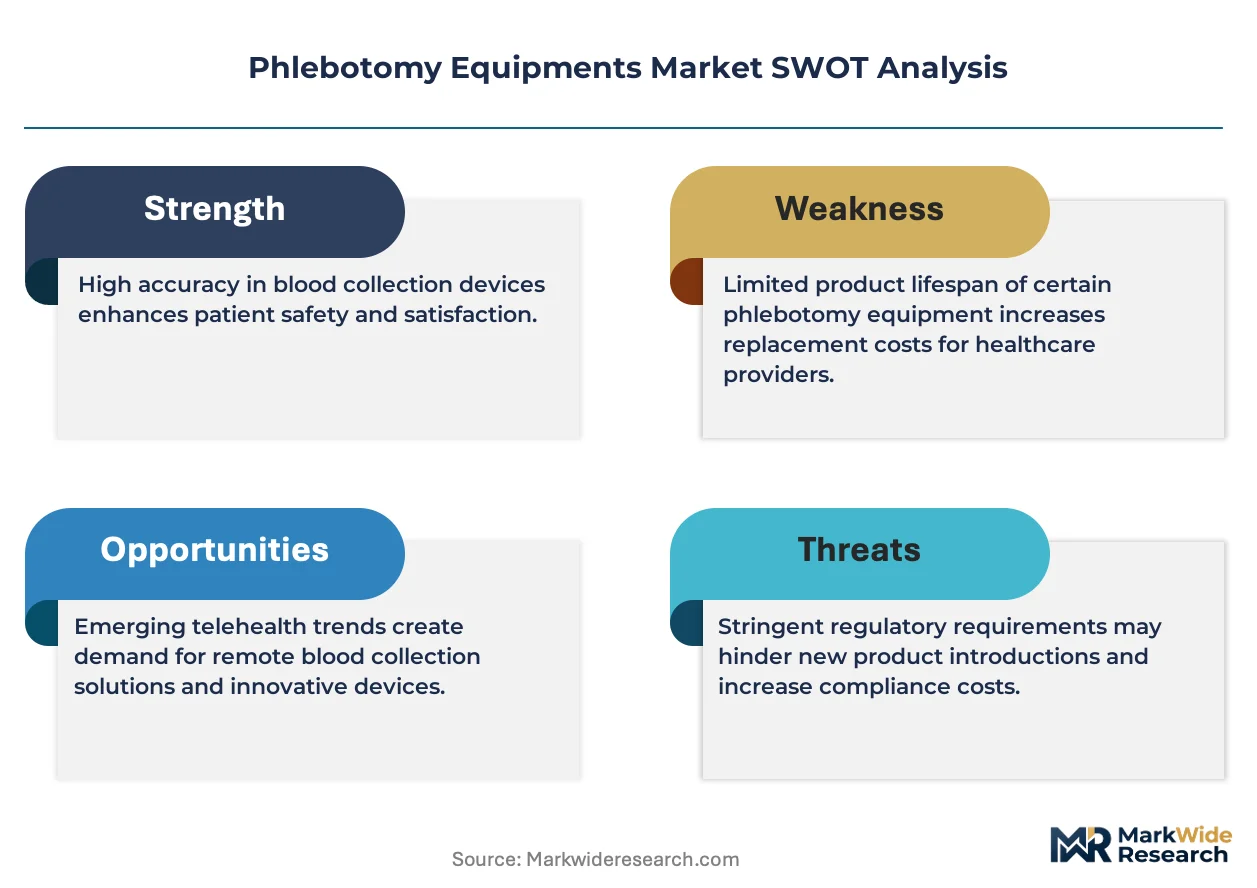
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard govern product safety and worker protection requirements in the United States, while EU MDR and REACH frameworks regulate material biocompatibility and chemical composition across European markets. These regulatory layers elevate compliance costs for new entrants while reinforcing incumbent positions through established quality management systems. Stakeholders must monitor evolving needlestick prevention mandates and sustainability requirements for single-use plastics as these forces reshape product design priorities and supplier qualification criteria.
Market Dynamics
Automated venous access systems are compressing manual collection workflows across high-throughput diagnostic networks, while OSHA needlestick mandates and EU MDR material restrictions simultaneously elevate compliance thresholds and procurement specifications.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Mandatory safety-engineered device adoption in US healthcare facilities drives replacement cycles for conventional needle systems.
- Diagnostic laboratory consolidation:Large-scale reference labs in Germany and China are standardizing on automated tube handling platforms to reduce pre-analytical error rates.
- Plastic-engineered tube coatings:Advanced additive formulations that stabilize coagulation markers are commanding premium positioning in specialized testing segments.
Market Restraints
- Petroleum-derived resin volatility:Polypropylene and polyethylene terephthalate input costs fluctuate with crude oil indices, squeezing margin predictability for tube manufacturers.
- Single-source sterilization dependency:Gamma irradiation capacity concentrates in Belgium and Illinois, creating geographic vulnerability for sterile device supply.
- EU REACH chemical restrictions:Phthalate plasticizer bans complicate closure seal formulations and force reformulation investments.
Strategic Opportunities
- India's diagnostic infrastructure expansion:Tier-2 and Tier-3 cities lack standardized phlebotomy protocols, opening channels for integrated collection system providers.
- Point-of-care molecular testing convergence:RNA stabilization tube technology paired with portable extraction platforms addresses decentralized infectious disease surveillance needs.
- US sustainability procurement mandates:Hospital GPOs are incorporating recycled content thresholds into supplier scorecards ahead of anticipated EPA single-use plastic guidelines.
Industry Challenges
- Phlebotomy technician certification bottlenecks:Training program capacity lags automated device deployment schedules in Brazil and Mexico, limiting effective utilization rates.
- Legacy LIS integration complexity:Automated tube labelers require middleware development for hospital information systems with customized specimen tracking protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phlebotomy Equipments Market |
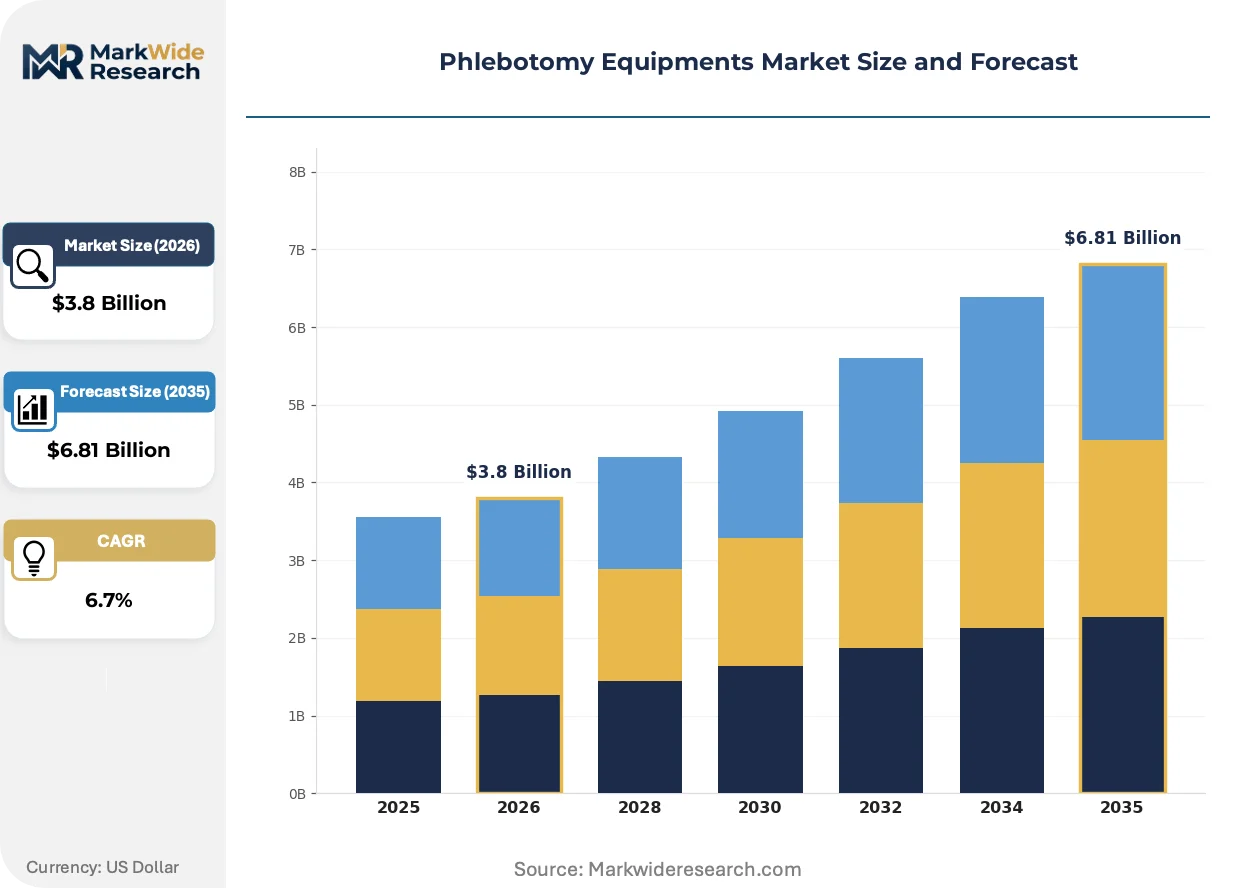
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Collection Tubes, Needles, Tourniquets, Safety Devices End User: Hospitals, Clinics, Blood Banks, Diagnostic Laboratories Delivery Mode: Direct Sales, Distributors, Online Retail, Institutional Sales Application: Blood Testing, Transfusions, Donations, Research |
| Companies Covered | Becton, Dickinson and Company, Cardinal Health, Terumo Medical Corporation, Greiner Bio-One, SARSTEDT AG & Co. KG, Medline Industries, Inc., Heathrow Scientific LLC, Vitrex Medical A/S, Marketlab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phlebotomy Equipments Market Strategic Shifts
Device intelligence and material science are converging to reshape specimen integrity assurance, with regulatory chemistry restrictions and procurement centralization acting as simultaneous forcing mechanisms across developed markets.
Robotic venipuncture assistance platforms are automating needle insertion depth and angle calibration in emergency department settings, reducing hemolysis rates and operator-dependent variability. Academic medical centers in the United States are piloting these systems for difficult-access patients. The technology is automating skill transfer from experienced phlebotomists to novice clinical staff, compressing training timelines and standardizing first-attempt success metrics.
EU MDR Annex I general safety and performance requirements are mandating clinical evidence packages for legacy safety needle devices previously cleared under notified body opinions. Manufacturers must now submit post-market surveillance data demonstrating sustained injury reduction. Tube and needle system suppliers with established quality management systems in Germany and Ireland are absorbing compliance costs more readily than smaller competitors.
Consolidated procurement through integrated delivery networks is displacing individual hospital purchasing autonomy in the United States, with GPO contracts bundling blood collection tubes, safety needles, and disposal containers into multi-year agreements. This concentration rewards suppliers with comprehensive product portfolios and penalizes single-category specialists. The shift is most visible in California and Texas, where IDN penetration exceeds national averages by substantial margins.
Phlebotomy Equipments Market Segmentation
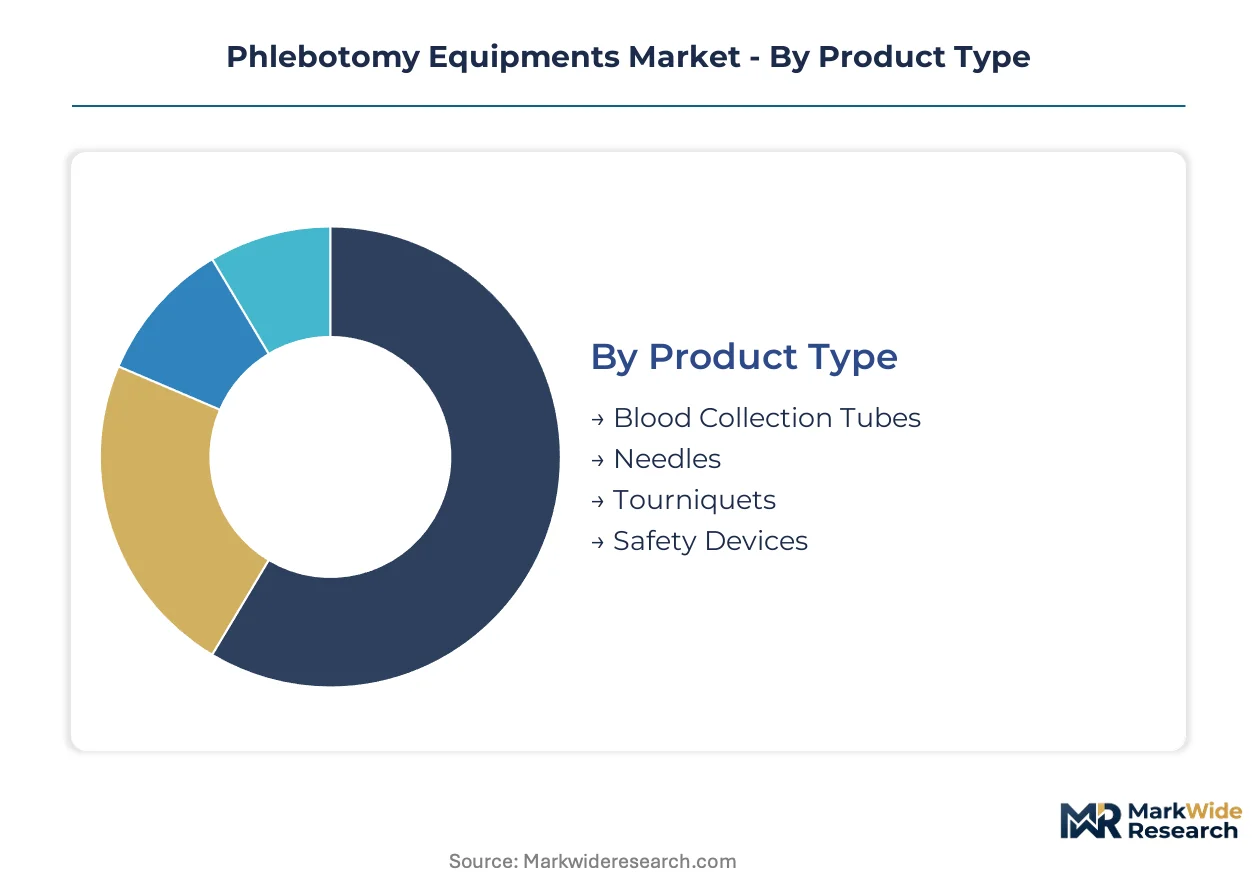
Phlebotomy equipment procurement patterns diverge sharply across clinical settings, with high-throughput laboratories prioritizing automation compatibility while acute-care facilities emphasize safety-engineered configurations. Understanding these segment boundaries enables suppliers to align formulation investments with specific workflow requirements and regulatory compliance thresholds.
Product Type:
Customization intensity spans from commodity consumables to precision-engineered safety systems, with material science investments clustering at the specialized end of this spectrum.
- Blood Collection Tubes:Polypropylene and polyethylene terephthalate vessels with vacuum-draw calibration and additive coatings for coagulation stabilization. Demand concentrates in diagnostic laboratories across Germany and China, where automated handling platforms require dimensional precision for robotic gripper compatibility.
- Safety Devices:Retractable and shielded needle systems engineered for OSHA needlestick prevention compliance. Hospitals in the United States drive procurement volume through institutional liability reduction mandates and worker protection protocols.
- Needles:Stainless steel cannulas with gauge specifications calibrated for venous access depth and viscosity requirements.
- Tourniquets:Latex and latex-free constriction bands for venous engorgement prior to puncture.
Most installed capacity flows through Blood Collection Tubes. Expansion is steepest in Safety Devices.
End User:
Margin structures stratify by specimen volume throughput and standardization maturity, with centralized reference laboratories commanding premium product specifications.
- Diagnostic Laboratories:High-throughput processing facilities with automated pre-analytical workflows and stringent quality control protocols. Germany's reference laboratory networks and China's hospital-affiliated lab chains are standardizing on integrated tube-labeler systems to reduce pre-analytical error rates.
- Hospitals:Acute-care and emergency department settings with diverse patient access challenges and safety compliance requirements. United States health systems bundle procurement through GPO contracts spanning collection tubes, safety needles, and sharps disposal containers.
- Blood Banks:Collection and processing facilities for transfusion services with specialized donor chair configurations and high-volume draw protocols.
- Clinics:Outpatient and primary care settings with lower throughput and manual collection workflows.
Diagnostic Laboratories absorb the highest-margin product configurations. Volume growth is climbing fastest in Hospital systems consolidating through integrated delivery networks.
Delivery Mode:
Channel economics reflect inventory carrying costs versus technical support requirements, with complex system implementations favoring direct engagement.
- Distributors:Third-party logistics networks with regional warehousing and same-day replenishment capabilities for high-frequency consumables. Cardinal Health maintains extensive coverage across United States acute-care networks through established distributor relationships.
- Direct Sales:Manufacturer-led account management for automated platform installations and multi-year service agreements. Becton, Dickinson and Company leverages integrated manufacturing footprints to support bundled system deployments.
- Institutional Sales:Contracted procurement through GPO and IDN frameworks with standardized specifications and volume commitments.
- Online Retail:E-commerce channels for small-quantity orders and replacement component procurement.
Distributors handle the majority of consumable volume. Direct Sales channels are gaining share fastest in automated system implementations.
Application:
Testing complexity and regulatory scrutiny determine product specification intensity, with clinical diagnostics imposing stricter material biocompatibility requirements than research applications.
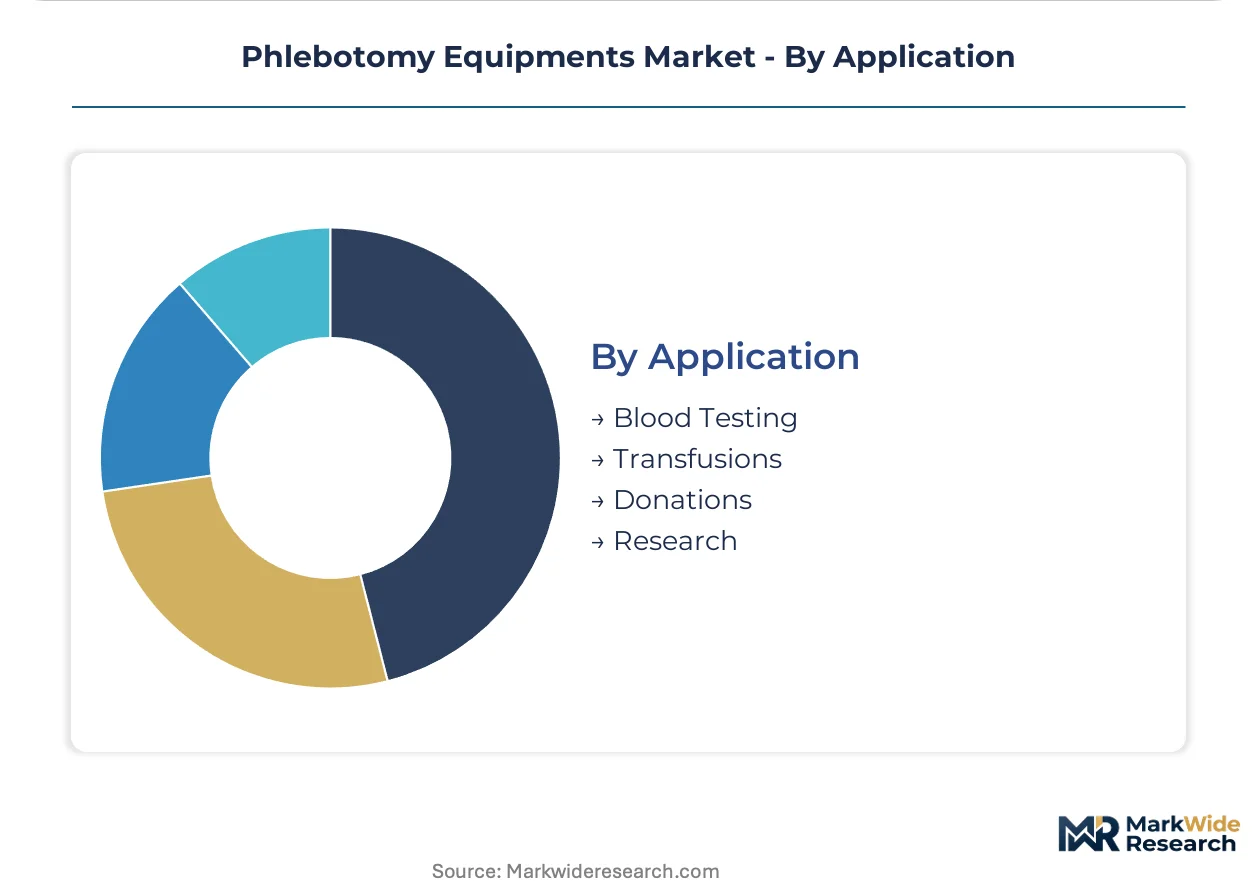
- Blood Testing:Clinical chemistry, hematology, and immunoassay applications requiring additive stability and analyte preservation. EU REACH chemical restrictions and FDA material biocompatibility standards govern tube closure formulations and plasticizer content.
- Donations:Whole blood and apheresis collection with donor safety protocols and high-volume draw specifications. Blood banking facilities in the United States coordinate with FDA compliance frameworks for donor screening and collection documentation.
- Transfusions:Patient blood product administration with compatibility testing and cross-matching requirements.
- Research:Investigational and biomarker discovery applications with variable protocol specifications and lower regulatory burden.
Blood Testing commands the largest installed base. RNA stabilization tube technology paired with point-of-care platforms is expanding most quickly in infectious disease surveillance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Venous access technology originated in German industrial laboratories during the mid-twentieth century, with vacuum tube systems later scaling through US hospital procurement networks. Diagnostic infrastructure now concentrates in three distinct national clusters governed by divergent compliance frameworks.
United States
OSHA Bloodborne Pathogens Standard mandates safety-engineered device adoption across acute-care facilities, driving replacement cycles for conventional needle systems. FDA 510(k) clearance pathways govern product safety and worker protection requirements. California and Texas integrated delivery networks bundle procurement through GPO contracts exceeding national penetration averages.
Germany
Reference laboratory networks standardize on automated tube handling platforms to reduce pre-analytical error rates. EU MDR Annex I general safety and performance requirements mandate clinical evidence packages for legacy safety needle devices. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host quality management systems for tube and needle system suppliers.
China
Hospital-affiliated laboratory chains expand automated pre-analytical workflows with stringent quality control protocols. NMPA regulates material biocompatibility and chemical composition for domestic and imported devices. Yangtze River Delta manufacturing bases supply dimensional precision tubes for robotic gripper compatibility.
India
Tier-2 and Tier-3 cities lack standardized phlebotomy protocols, opening channels for integrated collection system providers. CDSCO oversight governs medical device registration and import licensing requirements. Maharashtra and Karnataka diagnostic infrastructure expansion attracts distributors with regional warehousing capabilities.
Brazil
Phlebotomy technician certification bottlenecks limit effective utilization rates for automated device deployment schedules. ANVISA compliance frameworks coordinate with hospital accreditation standards for specimen collection documentation. São Paulo and Rio de Janeiro metropolitan areas concentrate training program capacity and reference laboratory investment.
Phlebotomy Equipments Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with integrated manufacturing footprints. Three to five multinational suppliers command bundled procurement contracts across major health systems. Strategic archetypes span full-line manufacturers, specialized tube engineers, and distributor-anchored logistics networks. Capacity expansion and portfolio diversification through automated platform integration represent dominant competitive moves.
Among US-based diversified manufacturers, Becton, Dickinson and Company and Cardinal Health occupy positions exemplifying the full-line archetype with integrated system capabilities. Greiner Bio-One represents the specialized engineering tier with Austrian origins and focused tube technology expertise. These three anchors demonstrate how geographic manufacturing concentration and product portfolio breadth determine contract access within consolidated procurement frameworks.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Cardinal Health |
| Terumo Medical Corporation |
| Greiner Bio-One |
| SARSTEDT AG & Co. KG |
| Medline Industries, Inc. |
| Heathrow Scientific LLC |
| Vitrex Medical A/S |
| Marketlab |
| Others |
Value Chain & Pricing Dynamics
Automated tube handling platform adoption across German and Chinese diagnostic laboratories simultaneously compresses per-unit procurement costs and concentrates purchasing leverage among consolidated reference networks. This technology shift rewards suppliers with integrated manufacturing footprints while squeezing margin predictability for single-category specialists dependent on spot-market resin purchases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates additive-coated tubes for specialized coagulation testing from commodity polypropylene vessels and basic latex tourniquets. Price differentiation hinges on FDA 510(k) certification tier and volume scale commitments through GPO frameworks. Cost compression in the economy tier is intensifying because petroleum-derived resin volatility feeds directly into tube manufacturing economics. Hospital systems consolidating through integrated delivery networks exhibit lowest price sensitivity, while independent clinics and Tier-3 Indian diagnostic facilities demonstrate highest elasticity.
Supply Chain Analysis
Regional distribution centers in Belgium and Illinois anchor hub-and-spoke patterns for gamma-sterilized devices, with spoke nodes extending through Cardinal Health's acute-care network coverage and Becton, Dickinson's direct hospital system partnerships. Manufacturing concentrates in Germany's Baden-Württemberg industrial cluster, China's Yangtze River Delta, and United States heartland states. Raw material flows draw from Saudi and Qatari petroleum feedstocks for polypropylene resin, Belgian sterilization capacity for terminal processing, and Austrian precision molding equipment. Single-source sterilization dependency creates geographic vulnerability for sterile device supply. Distribution runs through third-party logistics networks with same-day replenishment capabilities for high-frequency consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phlebotomy equipments market functions as a stable compounder anchored by recurring consumable demand from diagnostic laboratories with automated workflow investments. OSHA needlestick mandates and EU MDR material restrictions create sustained replacement cycles that insulate incumbent revenue streams from cyclical volatility.
For Market Incumbents: To counter distributor-anchored competitors with extensive acute-care network coverage, deepen backward integration into polypropylene resin compounding and additive formulation capabilities. Prioritize capacity addition in India's Maharashtra and Karnataka clusters to capture diagnostic infrastructure expansion ahead of CDSCO registration requirements tightening for imports.
For New Entrants and Emerging Players: RNA stabilization tube technology paired with portable extraction platforms offers entry into point-of-care molecular testing convergence. White-space concentrates in India's Tier-2 and Tier-3 cities lacking standardized phlebotomy protocols, with Brazil's São Paulo metropolitan area presenting secondary opportunity despite ANVISA compliance complexity. Go-to-market leverage rests on integrated collection system bundling rather than single-product positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized tube engineers with Austrian or German manufacturing heritage and established EU MDR quality management systems. Long-term viability across the analysis window favors suppliers with comprehensive portfolios spanning tubes, safety needles, and disposal containers. Signal to monitor: EPA single-use plastic guideline progression triggering hospital GPO recycled content threshold acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance pathways for safety-engineered needle devices govern US hospital procurement eligibility. |
| CE Marking Pathway | EU MDR Annex I compliance mandates clinical evidence packages for legacy device market access. |
| Hospital System Partnership | Integrated delivery network contracts in California and Texas bundle multi-year consumable commitments. |
| Software Companion Development | Middleware for legacy LIS integration enables automated tube labeler deployment in customized environments. |
| Reimbursement Strategy | OSHA compliance documentation supports institutional liability reduction claims and worker protection budgets. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Brazil, with primary inputs from each market cluster combined with secondary validation. Interviews engaged hospital purchasing committee members, GPO contracts managers, biomedical engineers, diagnostic laboratory directors, and phlebotomy technician training program administrators. Secondary sources included FDA 510(k) clearance databases, EU MDR notified body opinions, hospital procurement databases, GPO contract disclosures, and customs records tracking polypropylene resin trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic healthcare expenditure models.
Granularity-level framing applied product type, end user, delivery mode, and application dimensions at country-level resolution throughout the projection horizon. CAGRs derived from regression analysis against diagnostic laboratory automation penetration curves and safety device replacement cycle data. Industry-specific inputs incorporated OSHA enforcement activity indices, EU MDR implementation timelines, and NMPA domestic manufacturing incentive programs.
The model holds under stable regulatory enforcement intensity and petroleum feedstock price bands; deviation in gamma sterilization capacity utilization or REACH chemical restriction expansion would shift supply cost assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Global Hip Implant Market
Medical Devices
Transportable Ventilator Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Global Nasal Cannula Market
Medical Devices
Silastic Implant Market
Medical Devices
Global External Fixators Market
Medical Devices
Intervertebral Implants Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Asia-Pacific Radiotherapy Market