
 Deflectable Catheters Market | 2026-2036
Deflectable Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Deflectable Catheters Market Analysis
Buyer concentration among integrated hospital networks is realigning procurement patterns for deflectable catheter systems. Boston Scientific Corporation leverages its electrophysiology portfolio to secure multi-year supply agreements with large health systems. Medtronic anchors its position through backward integration into catheter shaft manufacturing and proprietary handle mechanisms. Abbott competes on magnetic navigation compatibility across its diagnostic and interventional catheter lines.
Deflectable catheters are steerable medical devices constructed from braided stainless steel or nickel-titanium alloy shafts layered with thermoplastic polymers such as Pebax or nylon, featuring pull-wire actuation systems that enable tip deflection angles typically ranging from 90 to 180 degrees for precise intravascular navigation. Their primary purpose is to access tortuous anatomical pathways during minimally invasive cardiac, neurological, and oncological interventions without open surgery. Guide catheters dominate volume due to their utility across multiple access procedures, while magnetic navigation technology commands premium positioning as robotic catheterization systems expand in tertiary care centers. Electromechanical platforms represent the fastest-growing technology segment as hospitals integrate sensor-feedback systems for real-time torque and force measurement.
FDA 510(k) clearance requirements and EU MDR technical documentation standards govern material biocompatibility, electrical safety, and sterilization validation for deflectable catheter systems entering their respective markets. Japan's PMDA enforces JIS-compliant quality management systems that foreign manufacturers must satisfy through in-country representation. Stakeholders must monitor evolving reimbursement thresholds for robotic-assisted catheter procedures and the pace of MDR notified body capacity expansion in Europe.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins for deflectable catheter manufacturers while simultaneously demanding integrated electromechanical platforms with real-time sensor feedback. Integrated delivery networks now negotiate multi-year enterprise agreements that bundle diagnostic and interventional catheter lines, forcing suppliers to absorb sterilization validation costs and provide dedicated clinical support teams.
Growth Catalysts
- Electrophysiology lab expansion:Hospital systems in the United States, Germany, and Japan are scaling catheterization laboratory networks to address rising atrial fibrillation caseloads, directly expanding installed base for steerable ablation catheters.
- MDR technical documentation standards:EU MDR conformity requirements are accelerating biocompatibility testing investments, which paradoxically advantages established manufacturers with validated polymer supply chains and notified body relationships.
- Magnetic navigation compatibility:Robotic catheterization systems in tertiary care centers are creating pull-through demand for magnetic-navigation-ready deflectable shafts across diagnostic and therapeutic procedures.
Market Restraints
- Nickel-titanium alloy supply concentration:Shape-memory alloy sourcing clusters in specific Asian manufacturing regions create vulnerability to export restriction scenarios and price volatility for braided catheter shafts.
- FDA 510(k) clearance timelines:Pre-market notification pathways for novel electromechanical platforms now average 12-18 months, delaying revenue recognition for iterative product improvements.
- Reusable catheter reprocessing:Third-party sterilization services for diagnostic catheters are capturing procedure volume in cost-constrained European markets, compressing single-use device demand.
Strategic Opportunities
- Underpenetrated neurological applications:Steerable access for intracranial aneurysm embolization and stroke thrombectomy remains technically underserved relative to cardiac segments, offering first-mover positioning.
- Japan PMDA quality system recognition:Foreign manufacturers establishing in-country representation and JIS-compliant manufacturing partnerships gain preferential access to the world's second-largest aging population for interventional cardiology.
- Sensor-feedback electromechanical convergence:Integration of torque and force measurement with haptic feedback interfaces creates premium pricing tiers distinct from conventional pull-wire mechanisms.
Industry Challenges
- Polymer extrusion specialist scarcity:Thin-wall Pebax and nylon multi-lumen shaft manufacturing requires technicians with 5-7 year apprenticeship cycles, constraining production scaling for emerging suppliers.
- EU MDR notified body capacity:Technical documentation review queues for Class III devices now extend 14-22 months, forcing manufacturers to maintain dual CE mark and legacy directive certifications during transition periods.
- Legacy hospital inventory integration:Electromechanical platforms with proprietary handle interfaces face resistance from cath lab managers seeking standardization across mixed-vendor catheter fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deflectable Catheters Market |
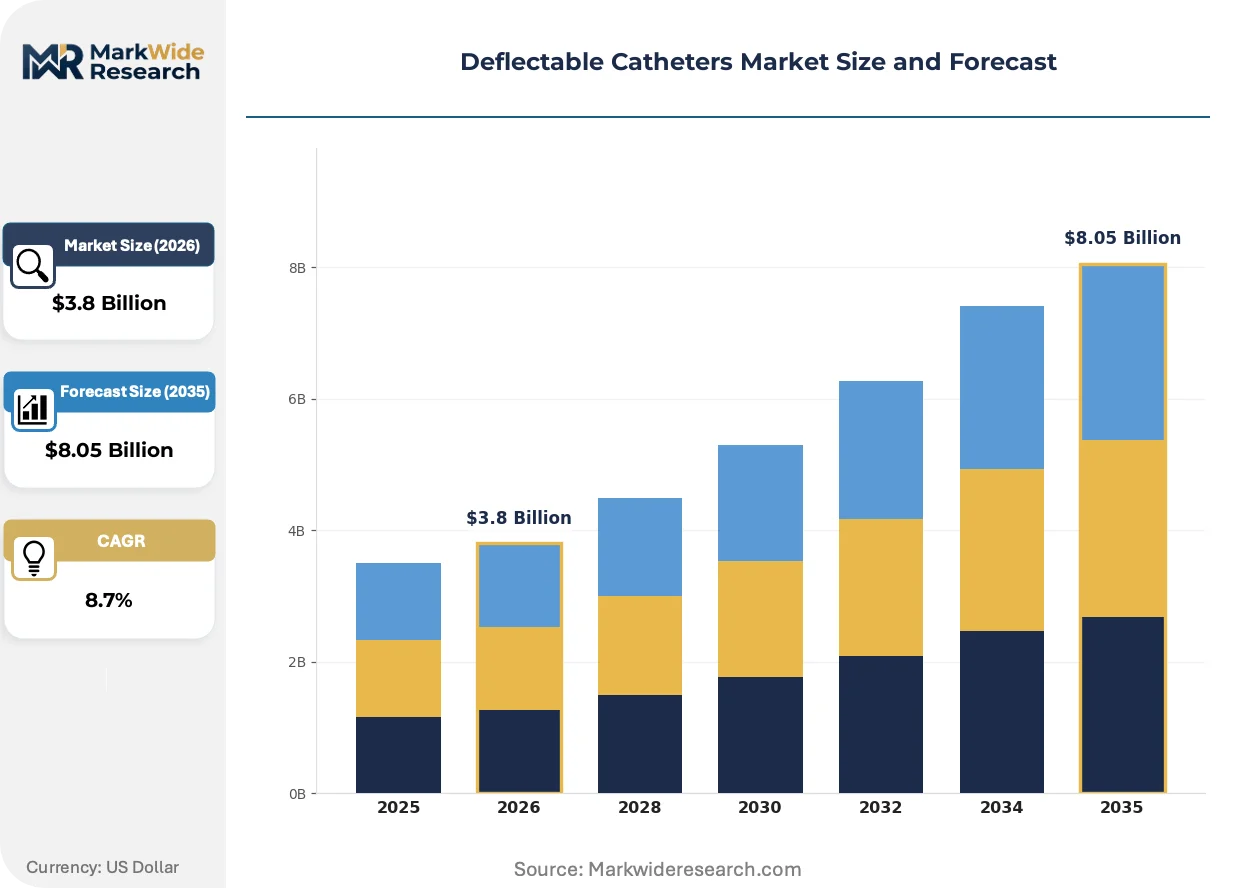
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
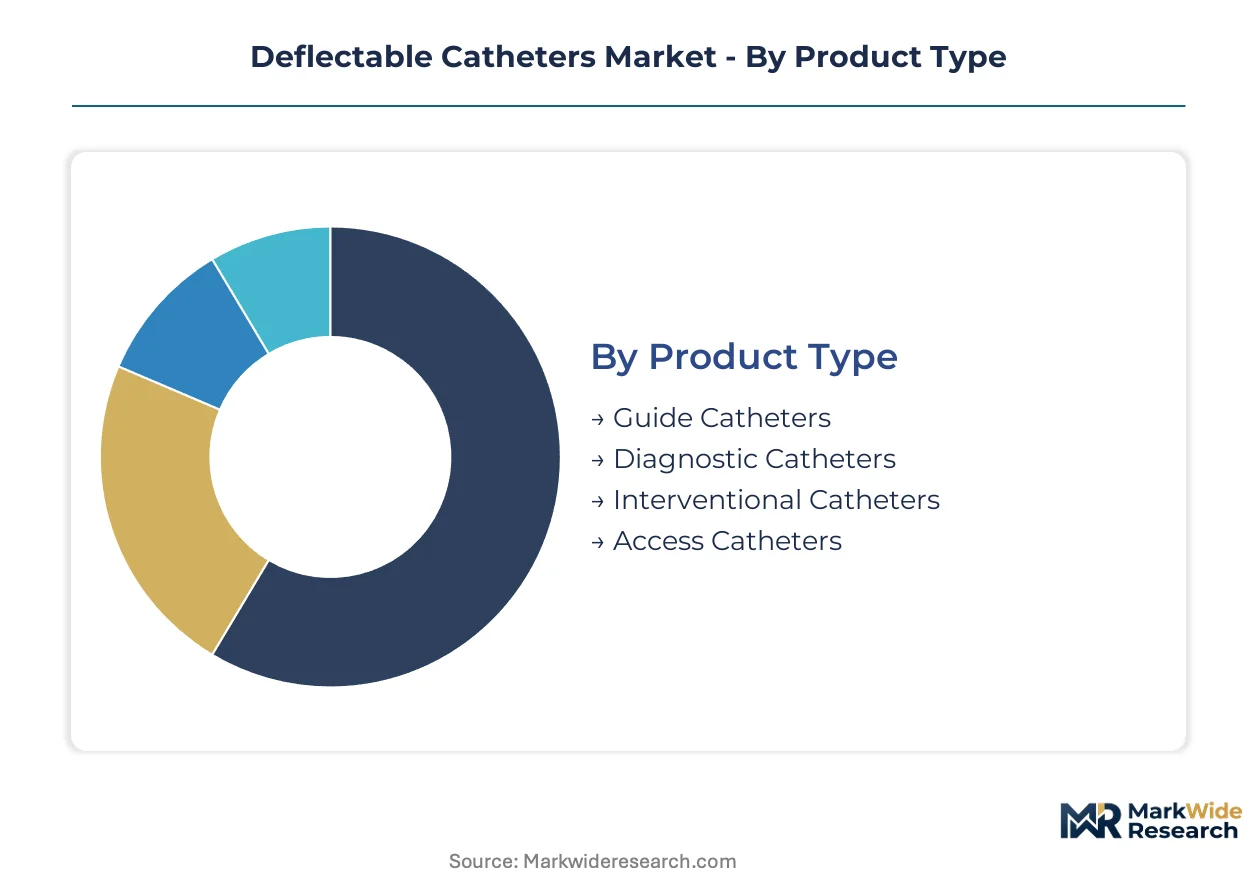
| Segmentation | Product Type: Guide Catheters, Diagnostic Catheters, Interventional Catheters, Access Catheters End User: Hospitals, Outpatient Surgical Centers, Specialty Clinics, Research Laboratories Technology: Electromechanical, Manual, Hybrid, Magnetic Navigation Application: Cardiology, Oncology, Neurology, Gastroenterology |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott, Teleflex Incorporated, Johnson & Johnson, Merit Medical Systems, Biosense Webster, Biomerics, CathRx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deflectable Catheters Market Emerging Trajectories
Real-time sensor integration is transforming deflectable catheters from passive mechanical tools into active feedback systems that reduce fluoroscopy exposure and improve procedural precision. This convergence of miniaturized electronics with traditional polymer-shaft construction is creating new competitive dimensions beyond deflection angle specifications.
Multi-axis force-sensing technology embedded at the catheter tip is electrifying procedural workflows by enabling operators to detect tissue contact pressure without radiographic confirmation. Tertiary electrophysiology labs in the United States and Germany are adopting these platforms for complex atrial substrate mapping procedures. The technology is compressing training curves for new operators while reducing procedure times and contrast agent volumes.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for all Class III active implantable accessories, including electromechanical catheter systems. Manufacturers must submit post-market surveillance plans and periodic safety update reports that extend liability timelines beyond product launch. European notified bodies are prioritizing review capacity for magnetic navigation-compatible devices, creating regulatory queue advantages for robotic-integrated platforms.
Hospital procurement departments are consolidating catheter purchasing through integrated delivery network formulary committees that evaluate total procedure cost rather than device unit price. Group purchasing organizations are displacing direct manufacturer relationships for standard guide catheters while preserving premium channels for electromechanical platforms with exclusive training commitments. This bifurcation is most visible in United States health systems where value-based care contracts penalize readmission rates for atrial fibrillation procedures.
Deflectable Catheters Market Segmentation
Deflectable catheter procurement patterns diverge sharply across product categories and clinical settings. Hospital formulary committees evaluate segments through distinct regulatory, reimbursement, and technical lenses that reshape vendor competitive positioning.
Product Type:
FDA 510(k) pathways apply uniformly across these segments, though EU MDR technical documentation intensity varies with shaft complexity and electrical component integration.
- Guide Catheters:Multi-lumen braided shafts constructed from Pebax or nylon polymers enable femoral and radial access across diverse interventional suites. Demand concentrates in United States integrated delivery networks scaling catheterization laboratory networks for atrial fibrillation ablation volumes. Procurement committees prioritize shaft torque response and hydrophilic coating durability over deflection angle specifications.
- Interventional Catheters:Electromechanical platforms with embedded force sensors command premium positioning in tertiary cardiac centers performing complex substrate mapping. German electrophysiology labs are expanding installed base for robotic-compatible steerable shafts that reduce fluoroscopy exposure.
- Diagnostic Catheters:Single-use electrophysiology mapping devices face reimbursement compression from third-party reprocessing services in European markets.
- Access Catheters:Sheath introducers with integrated hemostasis valves support transseptal puncture procedures in structural heart interventions.
Leading the category by volume: Guide Catheters. Growing fastest: Interventional Catheters.
End User:
Cost tier stratification separates capital-intensive electromechanical platform adopters from price-sensitive standard catheter purchasers.
- Hospitals:Tertiary academic medical centers in Japan, Germany, and the United States anchor demand for magnetic navigation-ready systems with dedicated clinical engineering support. PMDA quality system requirements and FDA electrical safety standards govern procurement specifications for integrated catheterization laboratory networks.
- Outpatient Surgical Centers:Ambulatory settings in United States markets favor manual pull-wire catheters with simplified sterilization workflows and lower per-procedure capital overhead.
- Specialty Clinics:Electrophysiology-focused practices negotiate direct manufacturer relationships for diagnostic catheter bundles outside group purchasing organization channels.
- Research Laboratories:Preclinical testing facilities drive demand for custom-deflection profile catheters with validated biocompatibility documentation for investigational device exemption submissions.
Volume concentrates in Hospitals. Steepest expansion trajectory: Outpatient Surgical Centers.
Technology:
Application maturity separates established manual mechanisms from emerging sensor-feedback platforms requiring extended regulatory validation cycles.
- Magnetic Navigation:Robotic catheterization systems in tertiary United States and German centers create pull-through demand for nickel-titanium alloy shafts with proprietary interface compatibility. FDA premarket notification timelines for novel magnetic platform iterations now extend 12-18 months.
- Electromechanical:Real-time torque and force measurement integration is displacing conventional tactile feedback in complex atrial ablation procedures.
- Manual:Pull-wire actuation with polymer shaft construction maintains cost advantage in high-volume diagnostic applications.
- Hybrid:Combined mechanical-electronic platforms bridge price-performance gaps for mid-tier hospital systems.
Manual systems lead by procedure volume. Electromechanical platforms are gaining share fastest.
Application:
Supply concentration in polymer extrusion and shape-memory alloy sourcing shapes segment-specific production scaling constraints.
- Cardiology:Electrophysiology and interventional cardiology procedures consume the majority of deflectable catheter volumes, with atrial fibrillation ablation driving steerable sheath and mapping catheter demand in United States, German, and Japanese hospital systems.
- Neurology:Intracranial aneurysm embolization and stroke thrombectomy access remains technically underserved relative to cardiac segments, with thinner-wall shaft requirements constraining supplier participation.
- Oncology:Transarterial chemoembolization and radioembolization procedures utilize medium-deflection access catheters for hepatic artery navigation.
- Gastroenterology:Biliary drainage and endoscopic retrograde cholangiopancreatography applications favor lower-cost manual deflection mechanisms.
Cardiology dominates procedure volume. Neurology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel-titanium alloy sourcing clusters in specific Asian manufacturing regions create geographic vulnerability for braided catheter shaft production. Hospital catheterization laboratory networks in the United States, Germany, and Japan anchor demand concentration for steerable ablation systems.
United States
Tertiary academic medical centers in Boston, Cleveland, and Minneapolis are scaling electrophysiology lab networks to address rising atrial fibrillation caseloads. FDA 510(k) clearance pathways for novel electromechanical platforms now average 12-18 months, compressing revenue recognition timelines. Integrated delivery networks in the Southeast and Midwest negotiate multi-year enterprise agreements that bundle diagnostic and interventional catheter lines.
Germany
Electrophysiology laboratories in Berlin, Munich, and Hamburg are expanding installed base for robotic-compatible steerable shafts that reduce fluoroscopy exposure. EU MDR technical documentation requirements mandate clinical evidence for Class III active implantable accessories, extending liability timelines beyond product launch. The Baden-Württemberg and Bavaria industrial corridors concentrate polymer extrusion specialists for thin-wall Pebax multi-lumen shaft manufacturing.
Japan
PMDA enforces JIS-compliant quality management systems that foreign manufacturers must satisfy through in-country representation. Tokyo and Osaka metropolitan areas anchor demand for magnetic navigation-ready systems with dedicated clinical engineering support. The aging population demographic drives interventional cardiology procedure volume in Kanto and Kansai regions.
China
NMPA registration requirements for imported deflectable catheter systems mandate local clinical trials and manufacturing audits. Shanghai and Beijing hospital systems are expanding catheterization laboratory networks for structural heart interventions. The Yangtze River Delta concentrates domestic polymer extrusion capacity for catheter shaft components.
Switzerland
Swissmedic maintains stringent biocompatibility documentation standards for polymer-based steerable shafts entering the European market. Zurich and Geneva medical technology clusters host precision manufacturing capabilities for pull-wire actuation mechanisms. The country's central European location positions it as a distribution hub for EU MDR-compliant catheter systems.
Deflectable Catheters Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-feedback electromechanical convergence. The vendor base stratifies across three tiers: integrated multinationals with backward integration into shaft manufacturing, mid-scale specialists with notified body relationships, and regional fabricators serving price-sensitive diagnostic segments. Dominant competitive moves include capacity expansion in polymer extrusion capabilities and strategic partnerships for magnetic navigation platform compatibility.
Among United States-based multinationals, Boston Scientific Corporation and Medtronic exemplify the integrated tier with captive supply chain control over nickel-titanium alloy sourcing. Abbott occupies a position within the magnetic navigation compatibility vector. These three anchors represent divergent strategic archetypes: Boston Scientific Corporation leverages electrophysiology portfolio breadth, Medtronic emphasizes in-house production of proprietary handle mechanisms, and Abbott competes on robotic system integration.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott |
| Teleflex Incorporated |
| Johnson & Johnson |
| Merit Medical Systems |
| Biosense Webster |
| Biomerics |
| CathRx |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in the United States, Germany, and Japan now command enterprise-scale procurement leverage that compresses per-unit margins while elevating electromechanical platform premiums. Hospital formulary committees evaluate total procedure cost rather than device unit price, forcing suppliers to absorb sterilization validation expenses and bundle clinical support services into multi-year agreements.
Pricing Analysis
Volume concentrates in standard guide catheters where per-unit margins face compression from group purchasing organization aggregation, while electromechanical platforms with embedded force sensors sustain premium positioning through exclusive training commitments and robotic system compatibility. Price differentiation hinges on FDA 510(k) clearance tier and magnetic navigation interface certification, with tertiary academic medical centers showing lowest price sensitivity and ambulatory surgical centers exhibiting highest. Pricing pressure stems from third-party reprocessing services capturing diagnostic catheter volume in European markets, eroding single-use device demand.
Supply Chain Analysis
Freight cost volatility for nickel-titanium alloy shipments from Asian manufacturing clusters has intensified sourcing diversification efforts among braided catheter shaft producers. Raw material dependencies center on Pebax and nylon polymer extrusion capacity concentrated in Germany and Switzerland, nickel-titanium shape-memory alloy supply anchored in specific Asian regions, and specialized pull-wire actuation components. Single-source vulnerability in shape-memory alloy sourcing creates exposure to export restriction scenarios. Distribution runs through integrated delivery network formulary committees in the United States and hospital procurement consortia in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over polymer extrusion capabilities and proprietary handle mechanism production separates sustainable competitors from margin-squeezed assemblers. Players are pursuing backward integration into catheter shaft manufacturing to defend positioning against procurement consolidation.
For Market Incumbents: Deepen captive supply chain control over nickel-titanium alloy sourcing and polymer extrusion capacity to offset GPO margin compression. Secure multi-year enterprise agreements with integrated delivery networks that bundle diagnostic and interventional lines while absorbing sterilization validation costs. Invest in notified body relationship maintenance to navigate EU MDR technical documentation queues extending 14-22 months. For New Entrants and Emerging Players: Begin with neurological applications for intracranial aneurysm embolization and stroke thrombectomy access, where thinner-wall shaft requirements have constrained established supplier participation and created technical white space. Target mid-tier hospital systems in Japan seeking magnetic navigation-ready systems with JIS-compliant quality documentation. Pursue direct manufacturer relationships with electrophysiology-focused specialty clinics outside GPO channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor polymer extrusion specialists with 5-7 year technician apprenticeship pipelines and validated Pebax multi-lumen capabilities in the Baden-Württemberg and Bavaria industrial corridors. Long-term viability over a multi-year horizon rests on sensor-feedback electromechanical convergence and robotic platform compatibility. Monitor EU MDR notified body capacity expansion as the inflection signal for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shaft Manufacturing | Captive Pebax extrusion capacity insulates margin pressure from polymer supply volatility. |
| Magnetic Navigation Compatibility Certification | FDA 510(k) clearance for robotic interface compatibility unlocks tertiary center premium pricing. |
| EU MDR Notified Body Relationship Investment | Priority review queue positioning accelerates Class III device market access timelines. |
| Hospital System Partnership with Training Commitments | Exclusive clinical support teams secure formulary placement against GPO aggregation. |
| Sensor-Feedback Electromechanical Platform Development | Real-time torque measurement creates pricing tiers distinct from conventional pull-wire mechanisms. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with electrophysiology lab directors, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and polymer extrusion specialists. FDA 510(k) clearance databases, EU MDR technical documentation filings, PMDA quality system registrations, and hospital procurement databases provided validation anchors. Bottom-up procedure volume estimates triangulated against top-down catheter manufacturer revenue disclosures.
Granularity-level modeling proceeded at the product-type, end-user, technology, and application segment intersections, with regional regulatory clusters and reimbursement frameworks as cross-cutting dimensions. CAGRs derived from fitted growth curves anchored to hospital catheterization laboratory expansion trajectories and atrial fibrillation procedure incidence patterns across the analysis window. Forecast inputs incorporated electrophysiology lab network scaling plans, MDR notified body capacity constraints, and nickel-titanium alloy supply concentration risk factors.
Underlying measurement precision varies by segment; electromechanical platform volumes carry tighter precision than emerging neurological application estimates due to established hospital reporting channels. Forecasts reflect assumptions regarding regulatory clearance timelines, reimbursement stability, and supply chain continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vascular Screening Devices Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Radial Access Catheter Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
Epilepsy Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Implantable Pulse Generator Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Global Artificial Skin Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Pre-Filled Hemostasis Agents Market