
 Peri-Implantitis Market | 2026-2036
Peri-Implantitis Market Size, Share, and Industry Trends Forecast 2026-2036
Peri-Implantitis Market Analysis
Specialized periodontal practices are bifurcating from general dentistry as the dominant buyer archetype for peri-implantitis interventions. Straumann Group leverages its integrated implant-to-maintenance portfolio to capture recurring revenue from long-term patient monitoring. Nobel Biocare anchors its position through premium surgical kit ecosystems designed for complex defect reconstruction. Geistlich Pharma differentiates via biologic graft materials that command preference in regenerative protocols across European teaching hospitals.
Peri-implantitis denotes an inflammatory pathological condition affecting the soft and hard tissues surrounding an endosseous dental implant, characterized by progressive crestal bone loss exceeding 2 mm accompanied by bleeding on probing and suppuration. The condition arises from biofilm-mediated dysbiosis at the implant-abutment interface, necessitating mechanical debridement combined with adjunctive antimicrobial or regenerative therapy to preserve implant function. Antimicrobial agents represent the most mature revenue pool, while surgical intervention segments capture expanding margin as clinicians adopt flap access and guided bone regeneration for advanced defects. Bone grafts occupy a premium tier where synthetic-versus-xenograft material selection drives procedure economics and reimbursement positioning.
The FDA regulates antimicrobial device coatings as combination products, creating dual-pathway clearance requirements that extend development timelines and elevate compliance costs for manufacturers. The EU Medical Device Regulation (MDR) reclassifies many active implantable accessories, compelling Straumann and Dentsply Sirona to renew technical documentation and clinical evidence portfolios for continued CE marking. ISO 19474 standards for peri-implant disease classification provide the methodological backbone for clinical trial design, yet regional divergence in adoption between the FDA, EMA, and Japan's PMDA complicates multi-jurisdictional study execution. Stakeholders must monitor how reimbursement authorities in Germany, France, and South Korea codify maintenance therapy intervals into fee schedules, as this will determine whether prevention-focused service models displace episodic intervention revenue.
Market Dynamics
The FDA's dual-pathway clearance framework for antimicrobial device coatings is compressing development timelines while elevating compliance costs, forcing manufacturers to restructure clinical evidence portfolios around combination product standards.
Growth Catalysts
- Installed Base Expansion:South Korea's dental implant penetration rates are deepening maintenance protocol adoption as clinicians confront aging implant cohorts requiring intervention.
- EU MDR Reclassification:The Medical Device Regulation's upgraded evidence requirements for active implantable accessories is accelerating portfolio consolidation among manufacturers with robust technical documentation capabilities.
- Laser-Assisted Debridement:Erbium-doped laser systems are gaining preference in German periodontal practices for their precision in implant surface decontamination without structural damage.
Market Restraints
- Xenograft Supply Concentration:Porcine-derived bone substitute sourcing depends on Danish and Swiss abattoir networks, exposing manufacturers to veterinary health policy volatility.
- Reimbursement Fragmentation:Germany's statutory health insurance maintains separate fee schedules for preventive maintenance versus surgical intervention, distorting clinical decision economics.
- Technical Limitation:Current mechanical debridement instruments cannot reliably access implant thread geometries below 3 mm diameter, leaving residual biofilm in narrow defect morphologies.
Strategic Opportunities
- Underpenetrated Geography:Brazil's private dental insurance expansion is creating first-mover advantage for maintenance protocol education among São Paulo's implantology referral centers.
- Technology Convergence:Digital impression systems combined with chairside 3D printing are enabling same-day custom healing abutments that reduce bacterial ingress at the implant-abutment interface.
- Regulatory Tailwind:France's ANSM is piloting accelerated assessment pathways for antimicrobial coatings demonstrating biofilm inhibition in standardized in-vitro models.
Industry Challenges
- Specialist Workforce Scarcity:European periodontal residency programs graduate insufficient numbers to match implant maintenance demand, forcing general practitioners into complex surgical interventions.
- ISO 19474 Implementation:Divergent adoption timelines between FDA, EMA, and PMDA for peri-implant disease classification standards complicate multi-regional clinical trial design and data pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peri-Implantitis Market |
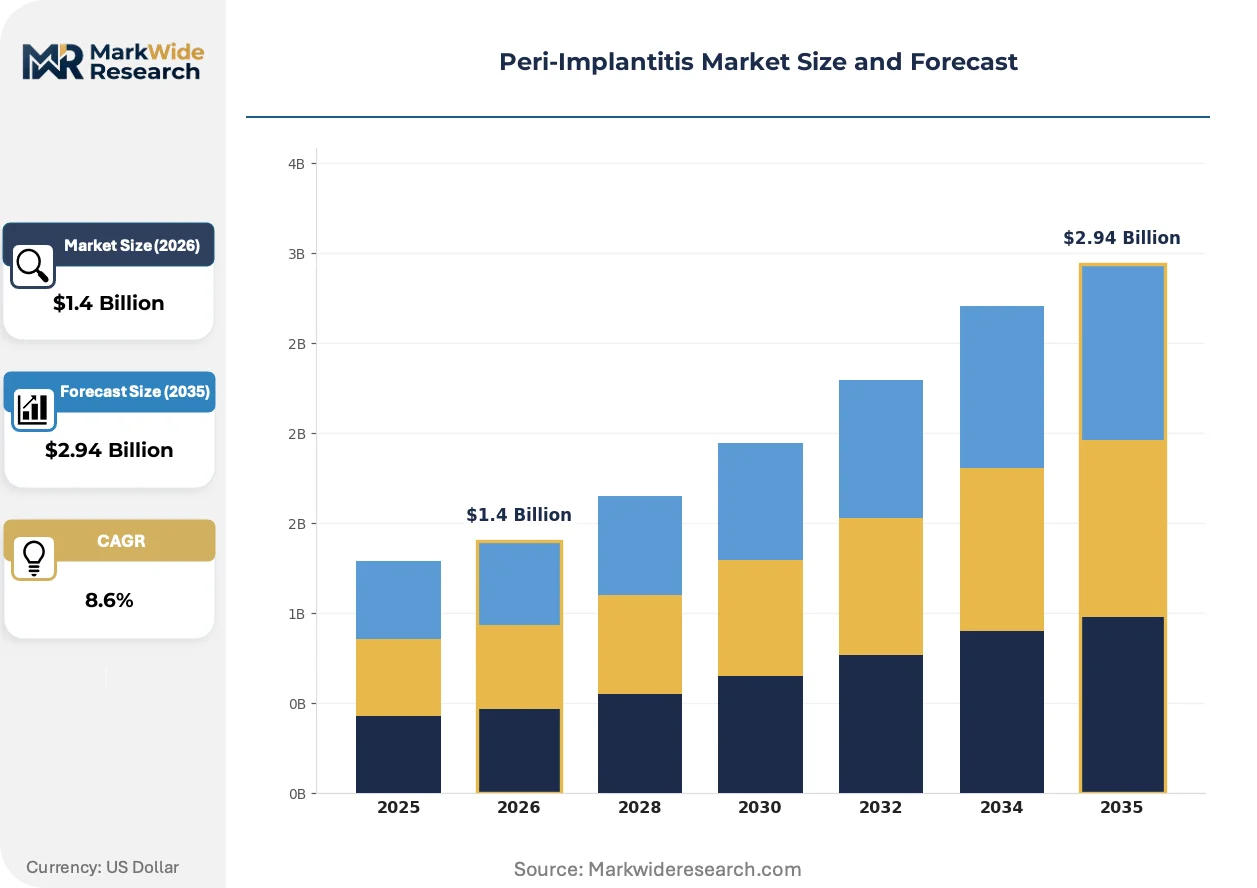
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial Agents, Surgical Kits, Implant Devices, Bone Grafts End User: Dental Clinics, Hospitals, Research Laboratories, Universities Treatment Method: Non-surgical Therapy, Surgical Intervention, Laser Treatment, Antibiotic Therapy Distribution Channel: Direct Sales, Online Sales, Third-Party Distributors, Wholesalers |
| Companies Covered | Straumann Group, Nobel Biocare, Dentsply Sirona, Zimmer Biomet, Geistlich Pharma, Pfizer Inc., BioHorizons, Osstem Implant, Henry Schein Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peri-Implantitis Market Emerging Trajectories
Digital workflow integration and surface engineering advances are restructuring how clinicians approach biofilm management and tissue regeneration around compromised implants.
Photodynamic therapy systems utilizing methylene blue-activated diode lasers are supplanting conventional chlorhexidine protocols in French and German university clinics. Periodontal residents prefer these modalities for their tissue-selective bacterial destruction without antibiotic resistance induction. The shift is compressing antimicrobial agent revenue pools while expanding capital equipment and photosensitizer consumable streams.
The EU MDR's reclassification of active implantable accessories is compelling manufacturers to renew CE marking through notified body review rather than self-certification. Straumann and Dentsply Sirona are absorbing elevated technical documentation costs across their surgical kit portfolios. German teaching hospitals now demand MDR-compliant clinical evidence before adding new regenerative materials to formulary.
Subscription-based implant monitoring programs are displacing episodic intervention billing in South Korean and US metropolitan markets. Dental service organizations bundle radiographic surveillance with professional cleaning at fixed intervals, capturing patient lifetime value through retention rather than procedure volume. This model concentrates in Seoul and Los Angeles where implant density supports panel-style economics.
Peri-Implantitis Market Segmentation
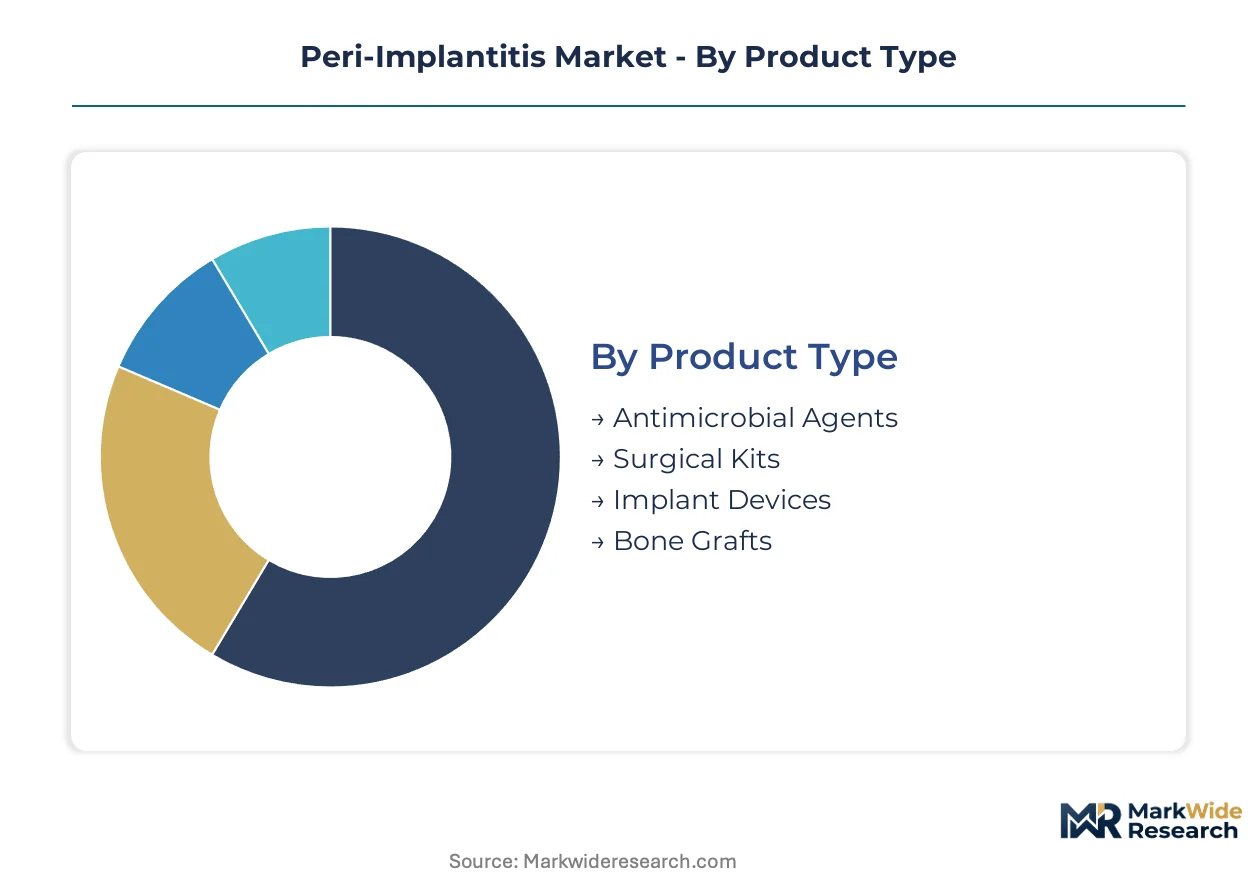
Segmentation in peri-implantitis care reveals how treatment complexity, reimbursement structures, and clinical setting specialization fragment purchasing authority across distinct buyer archetypes. Each dimension exposes different margin profiles and substitution vulnerabilities that reshape competitive strategy.
Product Type:
Antimicrobial agents face intensifying substitution pressure from photodynamic therapy systems and laser-based decontamination protocols that displace chemical irrigation in premium European practices.
- Antimicrobial Agents:Chlorhexidine gluconate and minocycline microspheres dominate maintenance-phase protocols. Demand concentrates in United States dental service organizations where bundled preventive contracts favor low-cost chemical regimens over capital-intensive alternatives.
- Surgical Kits:Flap access instruments and guided bone regeneration templates command premium positioning in defect reconstruction cases. German periodontal practices drive kit specification due to statutory insurance reimbursement differentials favoring surgical intervention over maintenance therapy.
- Implant Devices:Surface-modified healing abutments and cover screws incorporate antimicrobial coatings regulated as FDA combination products.
- Bone Grafts:Xenograft and synthetic substitute selection hinges on Danish and Swiss abattoir network reliability for porcine-derived materials.
Antimicrobial agents anchor the volume base while surgical kits gain share at the steepest rate as clinicians confront aging implant cohorts requiring defect reconstruction.
End User:
Cost tier stratification separates high-complexity academic centers from volume-driven private practice chains, with reimbursement models determining procurement centralization versus decentralized purchasing.
- Dental Clinics:Private periodontal practices and general dentistry chains generate procedure volume through subscription monitoring programs. Seoul and Los Angeles metropolitan markets concentrate demand where implant density supports panel-style patient retention economics.
- Hospitals:Academic medical centers and oral surgery departments manage complex revision cases requiring interdisciplinary coordination. South Korean university hospitals drive adoption of advanced regenerative protocols given their integrated implant-to-maintenance service lines.
- Research Laboratories:Preclinical testing facilities evaluate antimicrobial coating efficacy under ISO 19474 classification frameworks.
- Universities:European periodontal residency programs supply insufficient specialist workforce, forcing teaching hospitals to absorb general practitioner referral overflow.
Dental clinics dominate absolute procedure volume while hospitals capture the highest per-case revenue through complex reconstruction bundling.
Treatment Method:
Technology maturity curves separate established mechanical debridement from emerging laser modalities, with reimbursement codification determining adoption velocity across national health systems.
- Non-surgical Therapy:Mechanical debridement combined with local antimicrobial delivery remains the first-line intervention for early-stage peri-implant mucositis. French clinics prefer this approach given ANSM reimbursement structures that favor conservative management before surgical escalation.
- Surgical Intervention:Flap access with guided bone regeneration addresses advanced crestal bone loss exceeding 2 mm. German statutory health insurance maintains separate fee schedules that distort clinical decision economics toward surgical versus preventive pathways.
- Laser Treatment:Erbium-doped systems enable precise implant surface decontamination without structural damage.
- Antibiotic Therapy:Systemic and local antimicrobial delivery confronts biofilm-mediated dysbiosis at the implant-abutment interface.
Non-surgical therapy retains the largest installed base while laser treatment expands most quickly as German and French university clinics validate tissue-selective bacterial destruction protocols.
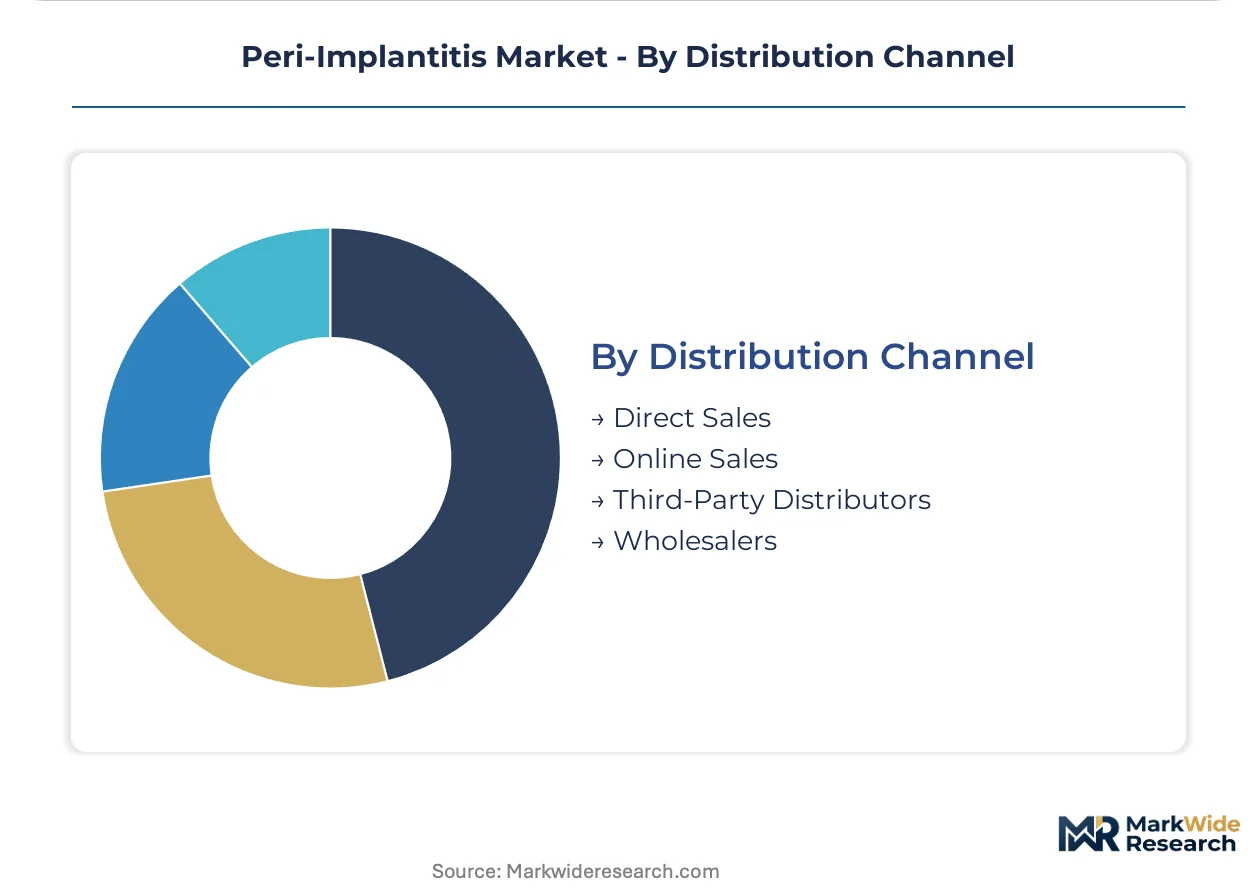
Distribution Channel:
Supply concentration in Danish and Swiss xenograft sourcing networks dictates procurement channel selection, with direct relationships securing volume commitments against wholesale spot-market volatility.
- Direct Sales:Straumann Group and Nobel Biocare deploy field specialists to high-volume periodontal practices for surgical kit and regenerative material specification. United States dental service organizations negotiate enterprise contracts capturing patient lifetime value through integrated implant-to-maintenance portfolios.
- Third-Party Distributors:Regional dental supply houses manage inventory for mid-tier clinics lacking procurement scale. Brazilian private dental insurance expansion in São Paulo creates first-mover advantage for distributor-led maintenance protocol education.
- Online Sales:E-commerce platforms serve low-acuity consumables and replacement instrument components.
- Wholesalers:Aggregated purchasing networks reduce per-unit costs for independent practices.
Direct sales commands the premium tier while third-party distributors capture volume growth in underpenetrated geographies lacking manufacturer field presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland exports precision-manufactured regenerative materials to German university hospitals, while South Korean implantology clusters supply maintenance protocols to Southeast Asian dental chains.
United States
Dental service organizations in Los Angeles and New York Metro bundle implant monitoring into subscription contracts, locking patient lifetime value through panel-style economics. The FDA regulates antimicrobial device coatings as combination products, forcing dual-pathway clearance timelines that elevate compliance costs for manufacturers. Henry Schein deploys field specialists to high-volume periodontal practices across the Southwest and Northeast Corridor.
Germany
Statutory health insurance maintains separate fee schedules for preventive maintenance versus surgical intervention, distorting clinical decision economics toward flap access procedures. The EU Medical Device Regulation reclassifies active implantable accessories, compelling manufacturers to renew CE marking through notified body review. Erbium-doped laser systems gain preference in Bavarian and North Rhine-Westphalian periodontal practices for implant surface decontamination.
South Korea
Seoul Capital Area dental clinics confront aging implant cohorts requiring intervention as penetration rates deepen maintenance protocol adoption. The MFDS aligns with ISO 19474 classification standards for peri-implant disease, streamlining domestic clinical trial design. Osstem Implant anchors integrated implant-to-maintenance service lines across Busan-Ulsan referral centers.
France
ANSM reimbursement structures favor conservative management before surgical escalation, channeling early-stage cases toward non-surgical therapy. The national regulator pilots accelerated assessment pathways for antimicrobial coatings demonstrating biofilm inhibition in standardized in-vitro models. Photodynamic therapy systems utilizing methylene blue-activated diode lasers supplant chlorhexidine protocols in Paris and Lyon university clinics.
Brazil
Private dental insurance expansion in São Paulo creates first-mover advantage for maintenance protocol education among implantology referral centers. ANVISA oversight of imported xenograft materials concentrates procurement through distributor networks with established import licensing. Third-party distributors capture volume growth in underpenetrated geographies lacking manufacturer field presence.
Peri-Implantitis Market Vendor Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and integrated portfolio breadth. The vendor base stratifies into three tiers: multinational conglomerates with full implant-to-maintenance ecosystems, mid-cap regional champions with concentrated geographic presence, and niche biologic material specialists. Strategic archetypes include integrated platform providers, regenerative material pure-plays, and capital equipment innovators. Portfolio diversification and M&A consolidation represent the dominant competitive moves as manufacturers absorb EU MDR documentation costs.
Within the integrated platform tier, Straumann Group and Nobel Biocare exemplify archetypes competing on recurring revenue capture from long-term patient monitoring. Dentsply Sirona occupies a position bridging capital equipment and consumable supply across dental clinic chains. Geistlich Pharma anchors the regenerative material specialist segment, commanding preference in European teaching hospital formulary decisions. These three entities represent distinct strategic postures without implying specific market share or financial performance claims.
| Leading Market Players |
|---|
| Straumann Group |
| Nobel Biocare |
| Dentsply Sirona |
| Zimmer Biomet |
| Geistlich Pharma |
| Pfizer Inc. |
| BioHorizons |
| Osstem Implant |
| Henry Schein Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German university hospitals and Danish xenograft processors lock in supply access while anchoring price visibility for porcine-derived bone substitutes. These contracts insulate premium regenerative material tiers from spot-market volatility in abattoir-sourced inputs.
Pricing Analysis
Current-generation photodynamic therapy systems command 40-60% premiums over prior-generation chlorhexidine protocols, while next-generation laser-assisted decontamination platforms are entering at standard-tier price points to drive adoption. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in economy-tier antimicrobial agents is intensifying because dental service organizations negotiate enterprise volume contracts. General dentistry chains exhibit highest price sensitivity, whereas German periodontal practices demonstrate lowest sensitivity due to statutory insurance reimbursement differentials favoring surgical intervention.
Supply Chain Analysis
Danish and Swiss abattoir networks constitute a chokepoint for porcine-derived xenograft materials, with veterinary health policy shifts capable of disrupting global regenerative material availability. Manufacturing concentration centers on Switzerland for precision-machined surgical instruments, South Korea for laser system components, and Germany for antimicrobial coating substrates. Raw material dependencies include veterinary-sourced bone matrix, erbium-doped laser crystals, and methylene blue photosensitizers. Single-source vulnerability runs through Danish porcine processing facilities. Distribution runs through direct sales forces for premium surgical kits and third-party distributors for mid-tier consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photodynamic therapy and laser-based decontamination systems threaten to displace chemical antimicrobial agents, forcing incumbents to defend substitution-exposed revenue pools while capturing equipment-based replacement streams.
For Market Incumbents: Secure backward integration into xenograft processing capabilities to insulate margin from Danish abattoir network volatility. Anchor recurring revenue through subscription-based implant monitoring programs that displace episodic intervention billing in Seoul and Los Angeles metropolitan markets. For New Entrants and Emerging Players: Lead with maintenance protocol education in São Paulo's implantology referral centers, where private dental insurance expansion creates first-mover advantage before manufacturer field presence solidifies. Target Brazilian distributor networks for channel access, positioning against premium European imports through localized technical support. For Investors and Strategic Acquirers: Regenerative material specialists with EU MDR-compliant technical documentation portfolios present acquisition targets given elevated barriers to renewed CE marking. Monitor France's ANSM accelerated assessment pathway pilots as inflection indicators for antimicrobial coating approval velocity and associated valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Renewal | Compels Straumann and Dentsply Sirona to absorb elevated notified body review costs across surgical kit portfolios. |
| Subscription Monitoring Program Rollout | Captures patient lifetime value through retention economics in Seoul and Los Angeles implant-dense markets. |
| Photodynamic Therapy Platform Launch | Displaces chlorhexidine revenue pools in French and German university clinics preferring tissue-selective bacterial destruction. |
| Xenograft Supply Agreement Restructuring | Mitigates Danish abattoir concentration risk through diversified porcine sourcing from Swiss veterinary networks. |
| Laser-Assisted Debridement Certification | Enables premium positioning in Bavarian periodontal practices seeking precision implant surface decontamination. |
Methodological Framework
Cross-validation between periodontal practice procurement records and hospital formulary databases anchors the qualitative findings in documented purchasing behavior. Primary interviews with implantology specialists, GPO contracts managers, biomedical engineers, and dental clinic chain procurement directors combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, ISO 19474 implementation trackers, and hospital procurement registries. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis triangulate market sizing.
Sensitivity analysis across treatment method adoption curves, reimbursement policy scenarios, and regulatory approval timelines shapes the analytical framework. Segmentation dimensions modeled include product type, end user, treatment method, and distribution channel, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs derive from procedure volume projections and average selling price trajectories across the analysis window. Forecast inputs incorporate implant installed base aging curves and maintenance protocol penetration rates by metropolitan market density.
Forecasts assume regulatory continuity in FDA combination product pathways, EU MDR notified body review processes, and France's ANSM pilot programs; material policy shifts would require re-modeling of antimicrobial coating revenue timelines. Scenario risks include veterinary health policy disruptions to xenograft supply, reimbursement authority fee schedule revisions in Germany and South Korea, and ISO 19474 adoption divergence between FDA, EMA, and PMDA complicating multi-regional clinical trial pooling. Practitioners should keep alternative scenarios live as laser modality validation data and photodynamic therapy reimbursement codification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Auto Keratometer Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Eye Examination Equipment Market
Medical Devices
Thrombectomy System Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Spectacle Lens Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
Global Disposable Medical Sensors Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Hyperpigmentation Treatment Devices Market