
 Social Gaming Market | 2026-2036
Social Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Social Gaming Market Intelligence
The unbundling of social interaction features from single-game environments into platform-wide layers is repositioning how users engage and form communities. Tencent Holdings Limited leverages its vast social network infrastructure to integrate gaming seamlessly. Zynga Inc. specializes in accessible, casual titles for mobile platforms, while Roblox Corporation operates a unique user-generated content ecosystem that fosters social creation.
Social gaming refers to online games that facilitate interaction between players through social networks or in-game systems. These games often utilize platform APIs for friend lists and employ real-time data synchronization for multiplayer experiences. The mobile platform type commands the largest user base. Within monetization models, free-to-play combined with in-game purchases is the dominant revenue strategy, especially for the high-volume casual game genre.
Regulatory frameworks significantly shape market access and design. In China, the NMPA enforces strict content approval and youth playtime limits. The EU's GDPR governs player data privacy, while the US FTC scrutinizes disclosures for in-game purchases. Developers must continually adapt monetization and engagement strategies to comply with shifting platform rules and global digital privacy standards.
Market Dynamics
The unbundling of social features from discrete game environments into overarching platform layers represents the central structural force in the market. This shift redefines community formation and user identity, moving value from individual titles to the network itself.
Growth Catalysts
- Expanded Mobile Infrastructure:The rollout of 5G networks in markets like India and Brazil reduces latency, significantly improving the quality and accessibility of real-time multiplayer experiences on mobile devices and driving user engagement in the casual gaming segment.
- Blockchain Integration:The adoption of blockchain technology enables new play-to-earn (P2E) monetization models, creating verifiable ownership of in-game assets and attracting players motivated by economic incentives in addition to entertainment.
- Cross-Platform Functionality:Advances in cloud gaming and universal software development kits (SDKs) allow for seamless social interaction and gameplay across PC, console, and mobile, broadening the potential player base for any single game community.
Market Restraints
- Stringent Regulatory Approvals:Government bodies such as China's NMPA impose strict, lengthy content review processes and mandate youth playtime restrictions, creating significant barriers to market entry and capping monetization potential in a key geography.
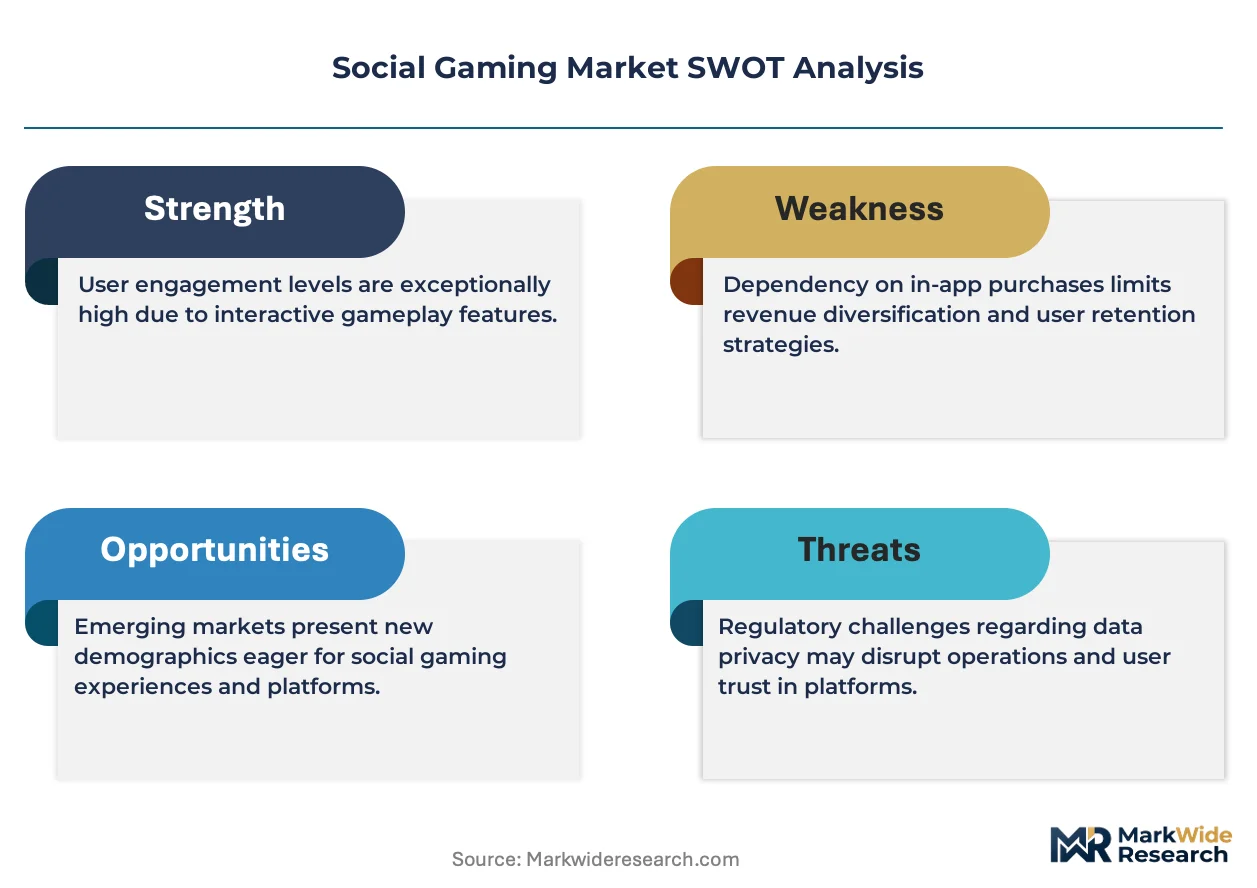
- User Acquisition Costs:The market for casual mobile games is highly saturated, leading to intense competition for user attention and escalating customer acquisition costs, which pressures profit margins for developers and publishers.
- Platform Dependency Risks:Developers are subject to the policies and commission fees of dominant distribution platforms like the Apple App Store and Google Play, creating risk from sudden changes to revenue-sharing models or content guidelines.
Strategic Opportunities
-
*AR and VR Integration: The convergence of social gaming with augmented and virtual reality technologies presents an opportunity to create deeply immersive, persistent social worlds, moving beyond screen-based interaction into embodied digital presence.
- Expansion into Southeast Asia:Markets such as Vietnam and Indonesia, characterized by young, mobile-first populations and rising disposable incomes, represent a significant, underpenetrated geographic opportunity for social game publishers. *Corporate and Educational Gamification: Applying social gaming mechanics to non-entertainment sectors like enterprise training, employee onboarding, and higher education offers a new avenue for growth, leveraging engagement loops for learning and development.
Industry Challenges
- Global Compliance Complexity:Developers face the operational burden of adhering to a fragmented landscape of data privacy regulations, including the EU's GDPR and various US state-level laws, requiring constant adaptation of data handling practices.
- Moderating User-Generated Content:Platforms built on user-generated content (UGC) face a significant challenge in effectively moderating vast quantities of player-created material to ensure brand safety and prevent toxic behavior at scale.
- Talent Scarcity:A shortage of professionals with hybrid skills in live-ops management, community moderation, and data science limits the ability of companies to effectively operate and scale live-service social games.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Gaming Market |
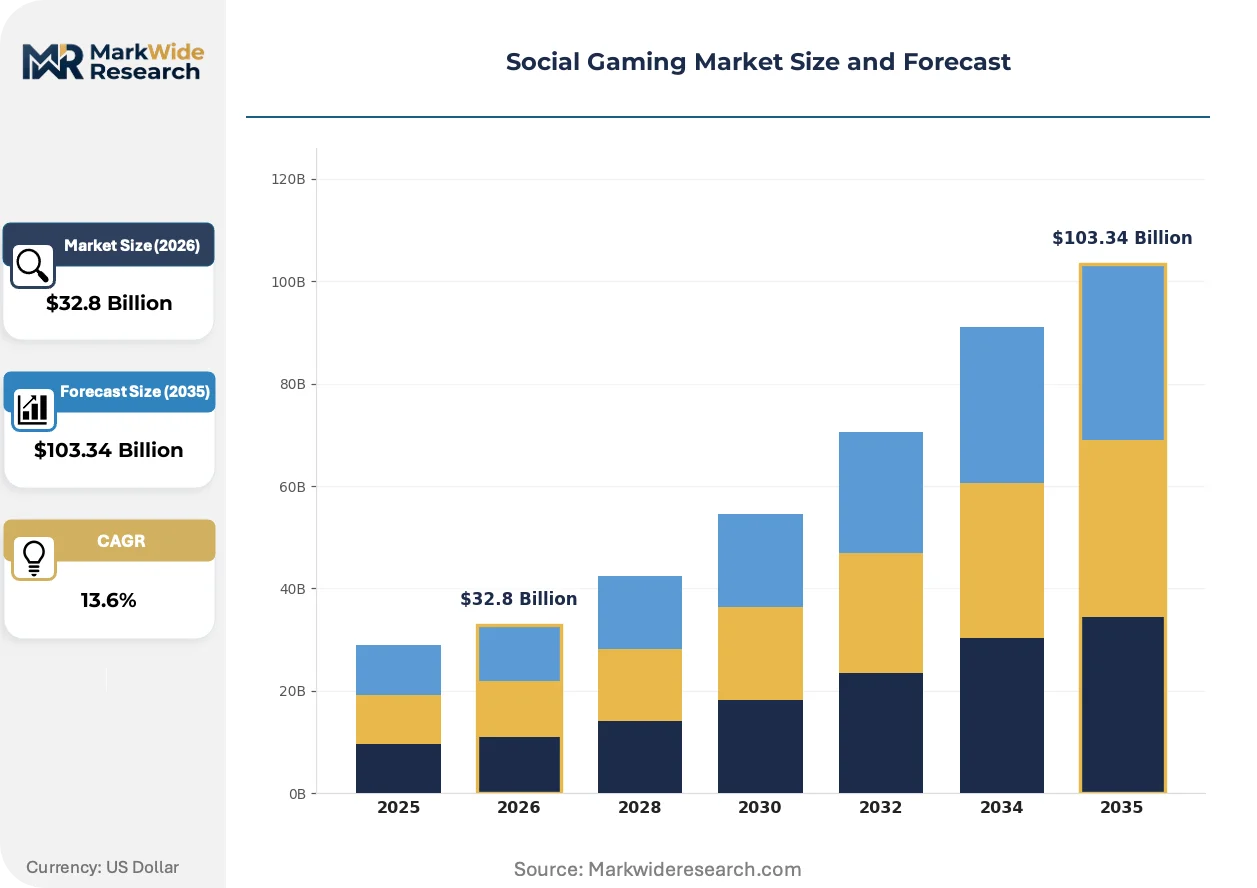
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $103.34 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Mobile, PC, Console, Web-based Game Genre: Casual, Strategy, Role-playing, Simulation Monetization Model: Free-to-play, Subscription, Pay-to-play, In-game Purchases Player Type: Individual, Group, Competitive, Collaborative |
| Companies Covered | Zynga Inc., Electronic Arts Inc., Activision Blizzard, Inc., Tencent Holdings Limited, Supercell Oy, King Digital Entertainment, Playtika Holding Corp., Roblox Corporation, NetEase, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Gaming Market Strategic Shifts & Innovations
The market's evolution is defined by the transition toward persistent, cross-game social identities. This trend prioritizes the player's network and digital presence over allegiance to a single game, fundamentally altering how value is created and captured within the ecosystem.
Technology and Asset Ownership
Blockchain technology is being integrated to support verifiable, player-owned digital assets through non-fungible tokens (NFTs). This model is gaining traction among developers aiming to build more open, player-driven economies. This technology is decentralizing control over in-game items and currencies, shifting power from a centralized developer to the distributed player community and enabling real-world trading.
Regulatory Scrutiny of Platforms
The European Union's Digital Services Act (DSA) is introducing new rules for large online platforms, including major gaming ecosystems. The act mandates greater transparency in content moderation and algorithmic systems used for recommending social connections or games. The casual mobile game segment, which depends on platform discovery mechanisms, is most affected and must now re-evaluate its strategies for user acquisition and community engagement.
Demand for Persistent Social Identity
Players increasingly value social identities that are portable across multiple games and platforms, including friend lists, achievements, and cosmetic items. This behavioral shift challenges the traditional model of creating a new, isolated profile for every game. The trend is most prominent in the PC gaming segment, where dedicated communities form around personalities and social groups rather than a single title.
Social Gaming Market Segmentation
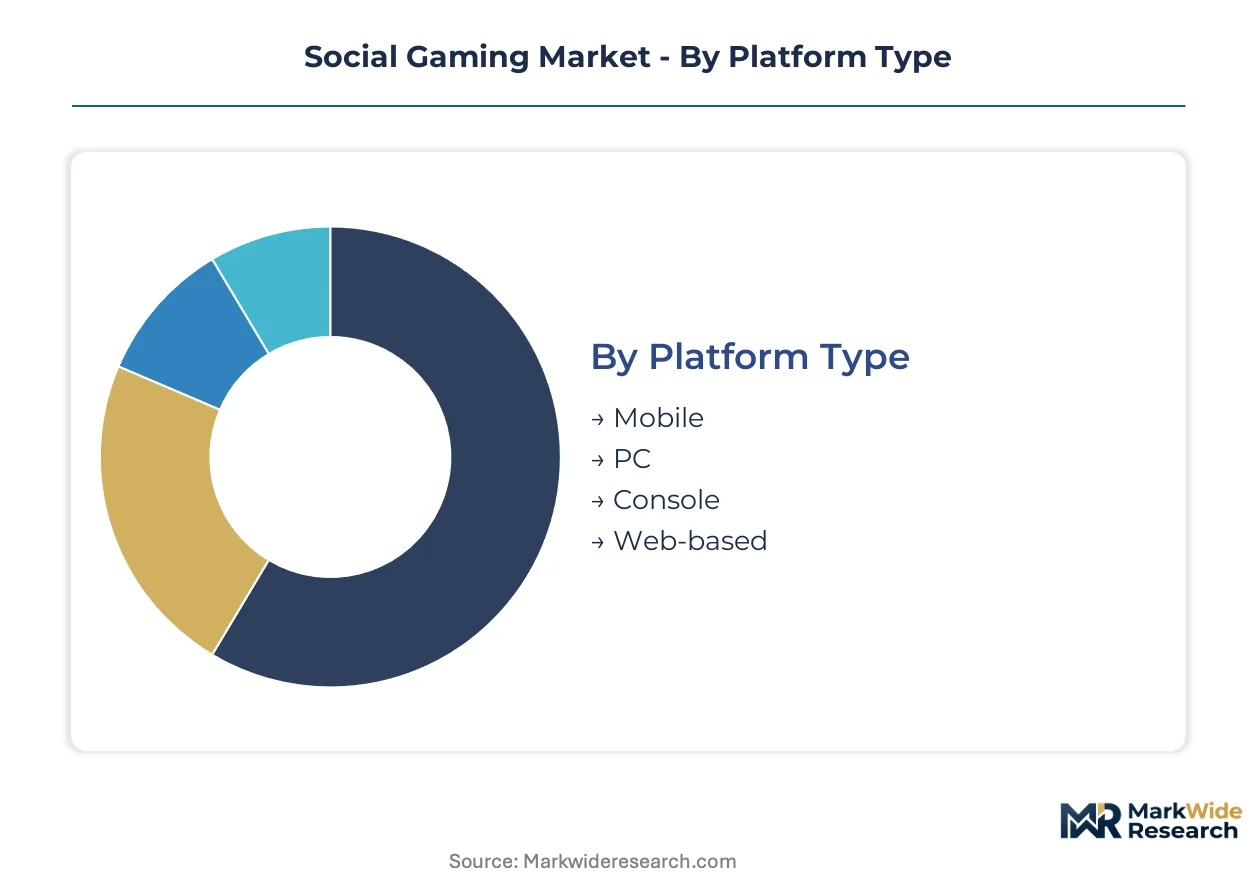
Segmentation provides a granular view of the social gaming market, revealing the distinct characteristics and preferences that shape player engagement and revenue generation. Understanding these segments allows developers and publishers to tailor content, monetization strategies, and marketing efforts more effectively.
Platform Type:
Players in the social gaming market differentiate their platform choice based on accessibility, graphical fidelity, and the depth of social integration offered by the device.
- Mobile:These devices offer unparalleled portability and immediate access, leveraging touch interfaces and integrated communication features. Demand concentrates in high-growth markets such as India and Brazil, driven by expanding mobile internet access and affordable smartphone penetration.
- PC:Personal computers provide a powerful environment for complex social games, supporting high-fidelity graphics, intricate controls, and robust community tools. Demand stems from dedicated communities that prioritize deep social interaction and user-generated content creation within platforms like Roblox.
- Console:These platforms offer immersive, high-fidelity gaming experiences, often centered around living room entertainment and specific gaming ecosystems.
- Web-based:Accessible directly through browsers, these games offer low barriers to entry and often leverage existing social network integrations.
Volume sits with Mobile; growth tilts toward PC due to expanding cross-platform functionality.
Game Genre:
The variety of social gaming experiences spans genres that cater to different player preferences for engagement, complexity, and competitive intensity.
- Casual:Characterized by simple mechanics, short play sessions, and broad appeal, these games are designed for immediate enjoyment and wide accessibility. Demand is concentrated on mobile devices, where ease of access and quick play sessions align with user behavior.
- Strategy:These games involve complex decision-making, resource management, and often require cooperative or competitive planning among players. Demand is notable in regions with established PC gaming cultures, where players seek deeper, long-term engagement and intellectual challenge.
- Role-playing:These genres immerse players in narrative-driven worlds, fostering social bonds through shared adventures and character development.
- Simulation:Players engage with realistic or abstract systems, often collaborating to build, manage, or optimize virtual environments.
Casual genres attract the largest player base, while strategy games are expanding most quickly in terms of engagement depth.
Monetization Model:
Monetization strategies in social gaming vary significantly, reflecting different approaches to player value capture and accessibility.
- Free-to-play:This model offers core game content without an upfront cost, relying on optional purchases or advertisements for revenue generation. Demand concentrates in the casual mobile gaming segment, where low entry barriers attract a massive user base.
- In-game Purchases:Players acquire virtual goods, cosmetic items, or gameplay advantages through microtransactions within the game environment. This model is dominant across mobile social games, where it drives significant revenue from engaged users seeking customization or progression boosts.
- Subscription:Players pay a recurring fee for access to content, often including exclusive features or a full game library.
- Pay-to-play:This traditional model requires an upfront purchase of the game, providing full access to its content and social features.
Free-to-play models generate the broadest user acquisition, with in-game purchases representing the primary revenue engine for developers.
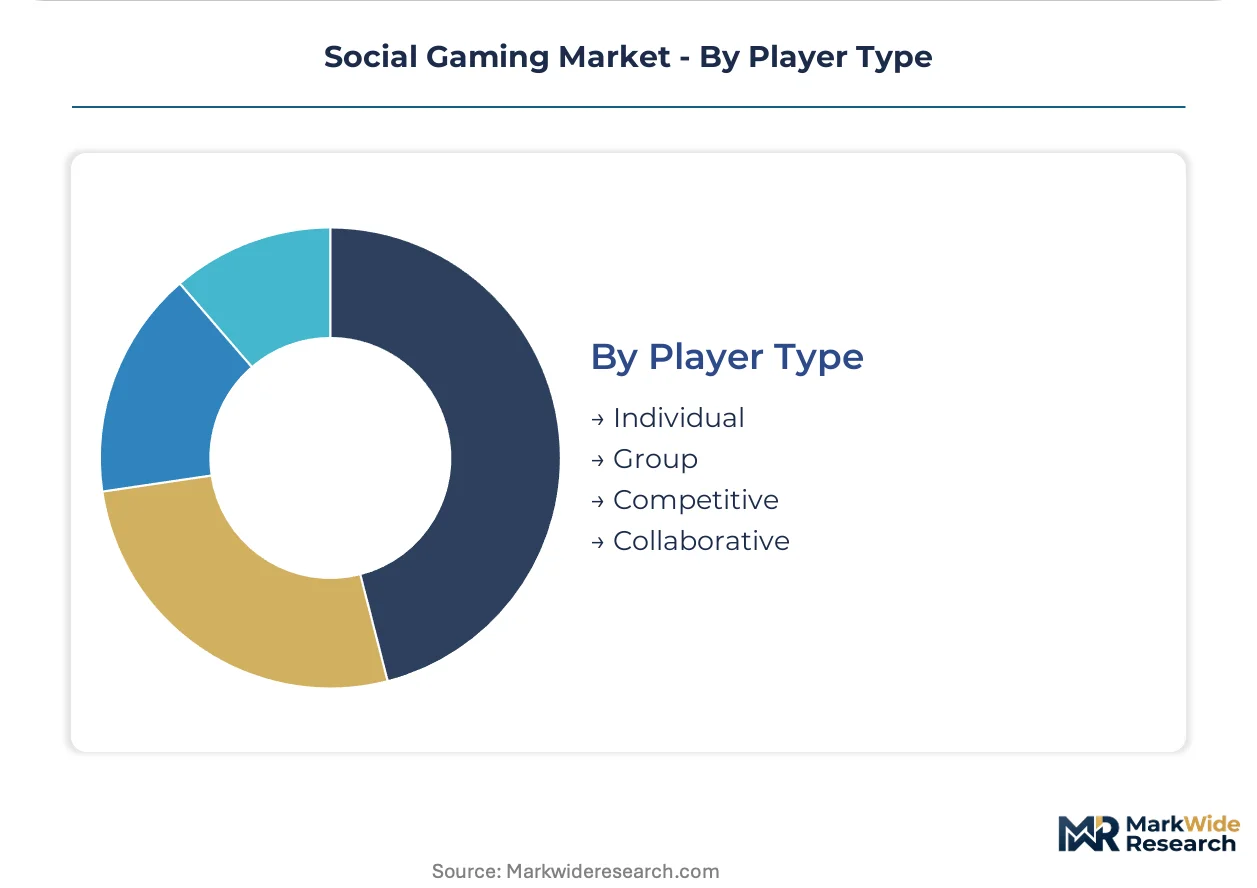
Player Type:
The social gaming market serves diverse player types, each driven by distinct motivations for interaction and engagement.
- Group:These players primarily engage in social games as part of pre-existing or in-game formed teams, guilds, or communities. Demand for group-oriented features is high in persistent online worlds and competitive multiplayer titles, fostering strong community bonds.
- Collaborative:Players work together towards shared objectives, requiring coordinated effort and communication to achieve in-game goals. This type of engagement is crucial in cooperative PvE (Player versus Environment) games and user-generated content platforms where joint creation is central.
- Individual:These players primarily engage with social games for personal entertainment, though they may still interact passively with others.
- Competitive:Focused on performance and ranking, these players seek direct confrontation with others to prove skill and achieve dominance.
Group play forms the core of social interaction, while collaborative engagement is driving innovation in persistent world design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The social gaming market exhibits a pronounced divide between content consumption and regulatory oversight. Demand for mobile social games concentrates heavily in emerging economies, while mature markets often drive innovation and platform development. Regulatory frameworks significantly shape market access and design across different geographies.
United States
The United States market sees robust demand for both casual mobile titles and complex PC-based social games. The US FTC scrutinizes disclosures for in-game purchases, influencing monetization strategies. Major tech hubs like Silicon Valley and Los Angeles drive significant innovation in social platform integration and game development.
China
China's vast mobile-first population creates immense demand for social gaming, particularly in the casual segment. The NMPA enforces strict content approval and youth playtime limits, significantly impacting market entry. Major cities like Shanghai and Shenzhen are central to game development and publishing, with large companies driving innovation.
India
India experiences surging demand for mobile social games, propelled by expanding mobile internet access and 5G network rollouts. The country's regulatory landscape is evolving, with increasing focus on data protection and user safety. Bengaluru and Mumbai are becoming important hubs for mobile game development, attracting both domestic and international studios.
Brazil
Brazil's market for social gaming is fueled by rising smartphone penetration and a highly engaged social media user base. The LGPD governs player data privacy, aligning with global data protection standards. São Paulo and Rio de Janeiro are primary centers for game consumption and a growing local development scene.
Germany
Germany demonstrates consistent demand across PC and mobile social gaming, supported by high digital literacy and disposable incomes. The EU's GDPR significantly influences player data privacy practices for all developers operating in the region. Berlin and Hamburg stand out as key European game development centers, fostering creative social game design.
Social Gaming Market Key Industry Players
The competitive structure tilts toward a fragmented landscape, with numerous developers vying for user attention across diverse platforms. This market includes large platform operators, specialized casual game publishers, and user-generated content ecosystem providers. Strategic archetypes encompass those leveraging existing social networks, those focused on rapid mobile content iteration, and those building persistent virtual worlds. Portfolio diversification and geographic expansion represent dominant competitive moves among market participants.
Among the major players, Tencent Holdings Limited exemplifies the integration of vast social network infrastructure with gaming, creating seamless user engagement. Zynga Inc. occupies a position as a specialist in accessible, casual titles for mobile platforms, catering to a broad user base. Roblox Corporation represents a unique user-generated content ecosystem, fostering social creation and interaction within its platform. These companies showcase distinct approaches to capturing and retaining social gaming audiences.
| Leading Market Players |
|---|
| Zynga Inc. |
| Electronic Arts Inc. |
| Activision Blizzard, Inc. |
| Tencent Holdings Limited |
| Supercell Oy |
| King Digital Entertainment |
| Playtika Holding Corp. |
| Roblox Corporation |
| NetEase, Inc. |
Cost & Logistics Intelligence
Premium social gaming experiences, often found on PC platforms, exhibit a pricing divergence from casual mobile titles, influencing both content development pipelines and global distribution strategies. This bifurcation dictates resource allocation for high-fidelity assets versus broad accessibility.
Pricing Analysis
Margin tightening in the casual mobile segment reflects intense user acquisition costs, pressuring developers to optimize monetization funnels. Free-to-play with in-game purchases represents the dominant revenue model, relying on volume scale and player engagement loops. Brand premium and customization level serve as key price differentiation drivers. High-volume casual players demonstrate significant price sensitivity, while dedicated competitive players accept higher spending for performance advantages.
Supply Chain Analysis
Reverse logistics for digital assets, while not physical, involves managing account transfers and blockchain-based asset ownership for play-to-earn games. Geographic supply of game development talent concentrates in China, the United States, and Europe, particularly Germany. Core dependencies include cloud infrastructure providers and specialized game engines. Platform dependency risks represent a structural supply chain risk, as dominant app stores control access and revenue shares. Distribution runs through digital storefronts and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The social gaming market is framed as a vertical-integration race, with major players pursuing deeper control over platform infrastructure to secure user engagement and content distribution.
For Market Incumbents: Lock in existing user bases through cross-game identity systems and exclusive content partnerships, countering emerging blockchain-enabled play-to-earn threats. Integrate social features directly into operating systems or proprietary launchers, leveraging vast network effects to maintain platform stickiness. Investment in community moderation tools represents a critical lever against toxic behavior and brand dilution.
For New Entrants and Emerging Players: Blockchain-enabled asset ownership presents a technology-first wedge for new players to disrupt traditional monetization models, targeting players seeking economic incentives. Focus on underpenetrated geographic markets like Southeast Asia, leveraging mobile-first strategies and localized content. A strong go-to-market angle involves direct community building and influencer marketing within specific gaming niches.
For Investors and Strategic Acquirers: Re-rating potential sits with platforms fostering user-generated content and robust creator economies, given their sustainable growth loops. Long-term viability favors companies able to port social identities and assets across multiple digital environments over the next decade. Acquisition targets should include studios specializing in AR/VR social experiences or those with strong intellectual property in emerging markets. The signal to watch is the widespread adoption of verifiable digital identity standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Platform Identity Development | This initiative enhances player retention by allowing seamless social profiles across diverse gaming ecosystems. |
| Blockchain-Enabled Asset Integration | Implementing verifiable digital ownership attracts players seeking economic participation and real-world trading. |
| User-Generated Content Platform Expansion | Fostering creator economies drives organic content creation and strengthens community engagement within the platform. |
| Localized Content and Marketing | Tailoring game experiences for specific high-growth markets like India captures new mobile-first audiences. |
| AR/VR Social Experience Investment | Developing immersive virtual worlds positions companies at the forefront of future embodied digital interaction. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, complemented by primary interviews. Industry stakeholders included game developers, platform executives, community managers, and marketing leads. Secondary sources comprised app store analytics, gaming industry reports, and financial disclosures from public companies. This approach ensured robust bottom-up and top-down triangulation of market data.
Data-stream reconciliation integrated various market inputs to model segmentation dimensions including platform type, game genre, monetization model, and player type. Regional regulatory frameworks also served as a key modeling input across the analysis window. Compound annual growth rates were derived by assessing historical trends and projecting future adoption curves based on technological advancements and demographic shifts. Mobile internet access in emerging economies was a critical forecast input.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in consumer privacy preferences. Forecasts reflect assumptions documented regarding technological adoption rates and regulatory stability. Practitioners should monitor platform policy changes and blockchain infrastructure advancements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
VR Gaming Console Market
Gaming
United Kingdom Online Gambling Market
Gaming
Global Trading Card Games Market
Gaming
PC Games Market
Gaming
MMORPG Gaming Market
Gaming
Cloud Gaming Market
Gaming
Global Online Adventure Games Market
Gaming
Gaming Controller Market
Gaming
VR Racing Gaming Market
Gaming
China Casino Tourism Market
Gaming
Global Gaming Headset Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Africa Gaming Market
Gaming
Global Gaming Market
Gaming
Online Strategy Games Market
Gaming
India Gaming Market