
 Global Gaming Headset Market | 2026-2036
Global Gaming Headset Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gaming Headset Market Analysis
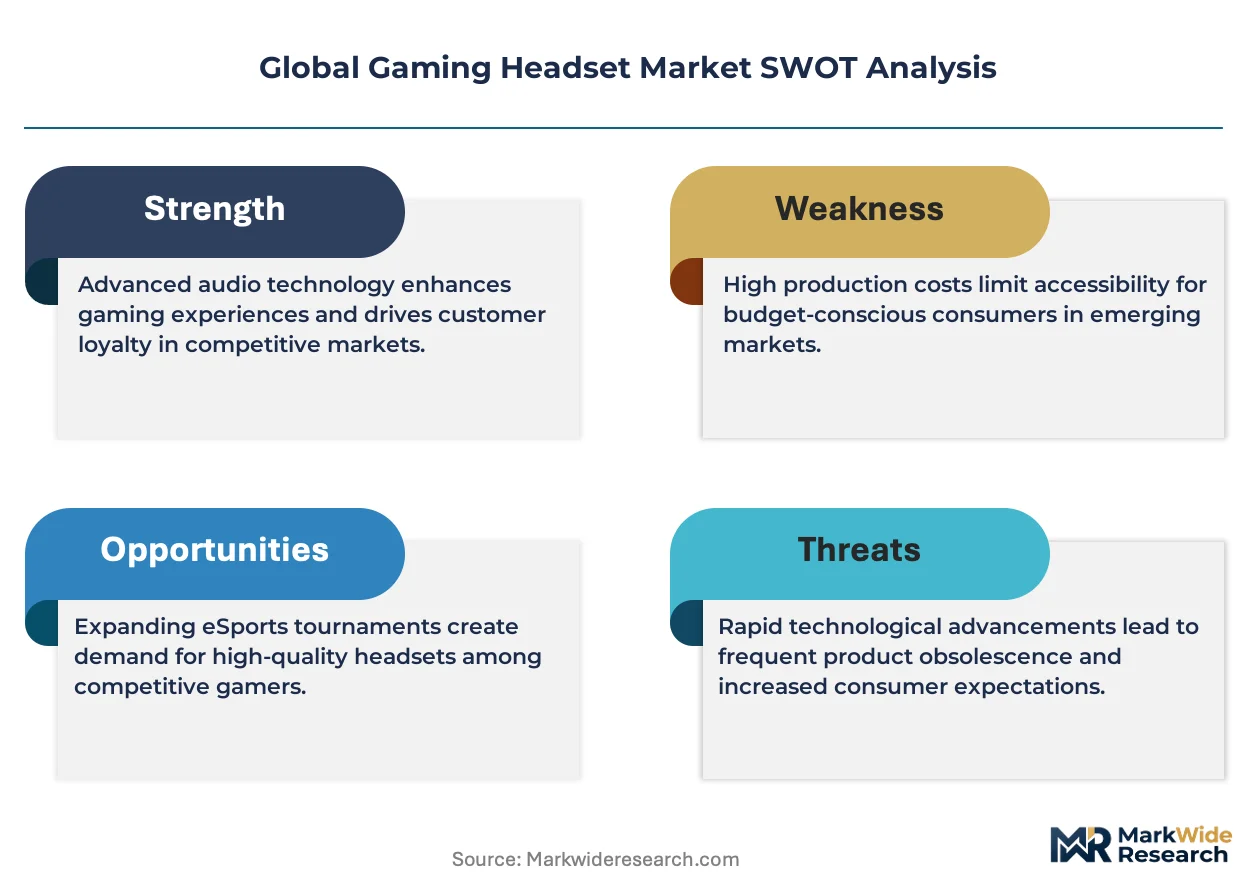
Aluminum alloy is restructuring housing economics across premium gaming headset tiers, displacing heavier stamped steel and reducing unit weight by meaningful margins. Razer leverages in-house acoustic engineering to sustain brand cachet in RGB-integrated wireless lines. Logitech anchors its position through manufacturing scale across Southeast Asian facilities, while Sennheiser competes on transducer heritage in audiophile crossover segments.
A gaming headset is a wearable audio peripheral engineered for immersive sound reproduction, typically incorporating 40–50 mm dynamic drivers, circumaural or supra-aural ear cup architectures, and unidirectional or bidirectional microphone arrays for voice communication. Its primary commercial purpose is to deliver positional audio accuracy and noise-isolated voice capture during interactive entertainment, competitive play, and live content production. Wireless headsets now command the fastest expansion trajectory as low-latency 2.4 GHz protocols displace legacy Bluetooth for competitive applications, while VR compatible headsets represent a concentrated margin pool tethered to spatial audio firmware licensing. Console gaming sustains the largest absolute volume channel, though esports applications are pulling premium pricing through tournament-grade certification requirements.
The FCC governs radio frequency emissions for wireless gaming headsets sold in the United States, while REACH restricts phthalates and flame retardants in European-bound products, and China's SAMR enforces GB standard compliance for acoustic output limits. These frameworks collectively elevate compliance costs for multi-region portfolios but also create barriers against uncertified entrants. Stakeholders must monitor evolving interoperability mandates between console platforms and third-party audio accessories, as ecosystem lock-in risks redrawing competitive boundaries independent of hardware performance.
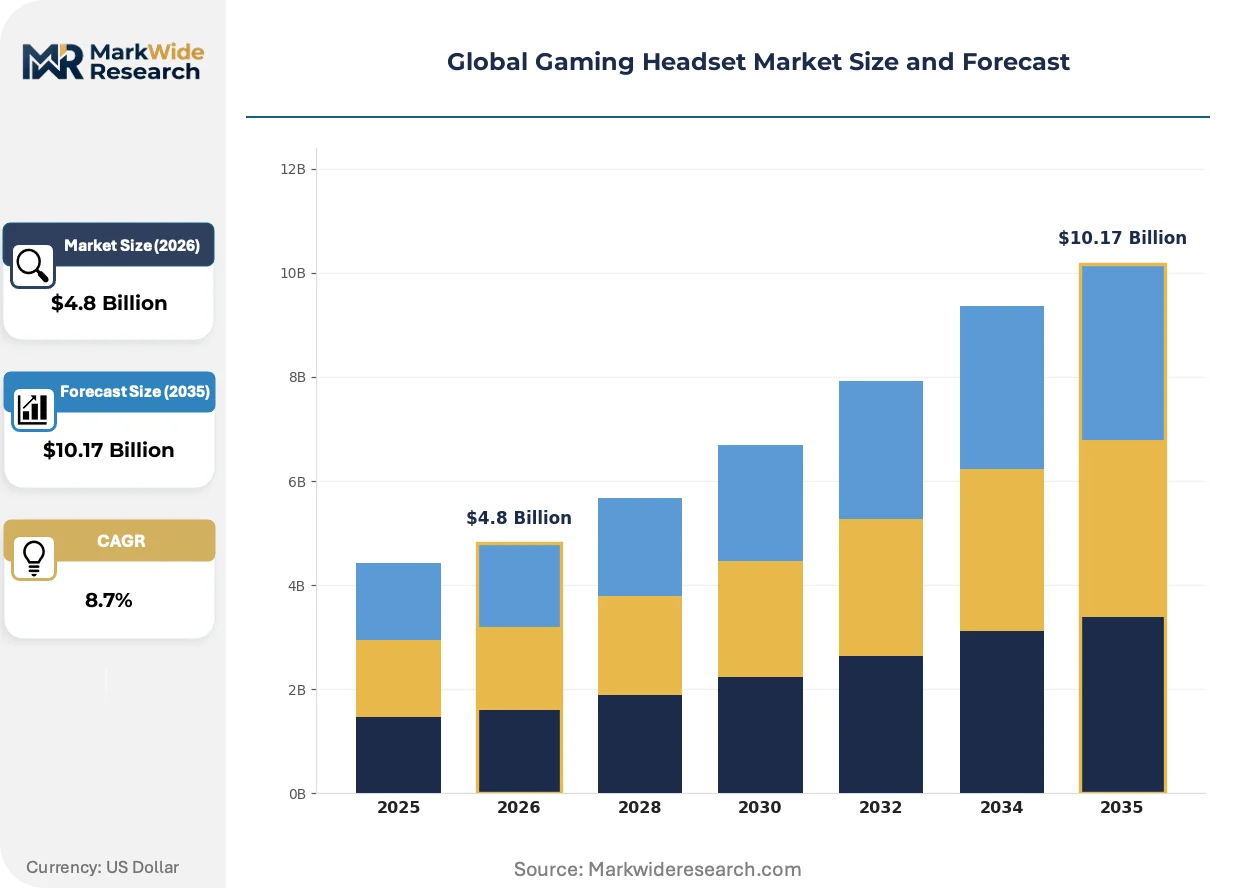
Market Dynamics
Wireless audio protocols are compressing latency benchmarks below 20 milliseconds, forcing manufacturers to abandon legacy Bluetooth stacks in favor of proprietary 2.4 GHz implementations. This technical transition is restructuring R&D allocation across the value chain while elevating certification costs for multi-platform compatibility.
Growth Catalysts
- REACH substance restrictions:European chemical regulations on phthalates and flame retardants are accelerating reformulation of cable insulation and ear cushion foams, creating first-mover advantages for compliant suppliers.
- Esports tournament infrastructure:Professional gaming leagues are mandating broadcast-grade audio certification, pulling replacement cycles toward premium transducer tiers.
- South Korean gaming clusters:Concentrated professional player bases in Seoul and Busan sustain accelerated hardware refresh rates for spatial audio accuracy.
Market Restraints
- Neodymium magnet supply:Rare earth processing concentration in Chinese refining facilities exposes driver manufacturing to input volatility and export quota fluctuations.
- Multi-regional certification costs:FCC emissions testing for US-bound wireless units, combined with SAMR acoustic output compliance for China, elevates fixed costs for diversified product portfolios.
- Spatial audio firmware licensing:Proprietary Dolby and DTS encoding requirements extract per-unit royalties that compress margins on mid-tier hardware.
Strategic Opportunities
- VR tethered headsets:Six-degrees-of-freedom audio tracking represents an underdeveloped margin pool requiring binaural rendering partnerships with immersive platform operators.
- India's esports infrastructure:Arena construction in Mumbai and Bangalore is outpacing local headset supply, creating white space for tournament-grade distribution partnerships.
- EU Green Deal circularity:Extended producer responsibility mandates for electronics are incentivizing modular driver architectures and replaceable ear cushion programs.
Industry Challenges
- Acoustic engineering talent scarcity:Transducer design expertise resides with a limited pool of German and Japanese specialists, constraining in-house R&D scaling.
- Platform interoperability fragmentation:Sony, Microsoft, and Nintendo maintain incompatible wireless pairing protocols, forcing SKU proliferation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gaming Headset Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Headsets, Wireless Headsets, USB Headsets, Bluetooth Headsets, VR Compatible Headsets Technology: Virtual Surround Sound, Noise Cancellation, RGB Lighting, Haptic Feedback, Microphone Quality Application: Console Gaming, PC Gaming, Mobile Gaming, Esports, Streaming End User: Casual Gamers, Professional Gamers, Game Developers, Content Creators, Streamers |
| Companies Covered | Logitech, Razer, HyperX, Corsair, Turtle Beach, SteelSeries, Sony, Sennheiser, EPOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gaming Headset Market Emerging Trajectories
Audio-hardware convergence with biometric sensing and AI-driven noise suppression is redefining peripheral value propositions. Manufacturers now compete on firmware sophistication rather than driver specifications alone.
Beamforming microphone arrays are unifying voice isolation with environmental awareness functions in single hardware packages. Tournament organizers are adopting these configurations for broadcast clarity without secondary boom mics. This convergence is unifying previously separate product categories—streaming microphones and gaming headsets—into single-SKU solutions that compress average revenue per user while expanding addressable market breadth.
REACH substance restrictions are compelling polyurethane foam suppliers to eliminate toluene diisocyanate from ear cushion production. Reformulated viscoelastic memory foams now require 18-month validation cycles before OEM qualification. European-bound product lines bear the steepest compliance burden, with manufacturers maintaining parallel material stacks for EU and non-EU markets.
Direct-to-consumer subscription models for hardware refresh programs are displacing traditional retail channel dependence. Razer and Logitech pilot membership tiers offering annual headset upgrades with trade-in credits. South Korean and Japanese consumers exhibit highest enrollment elasticity, where upgrade cadences already exceed 24-month replacement cycles in professional gaming segments.
Global Gaming Headset Market Segmentation
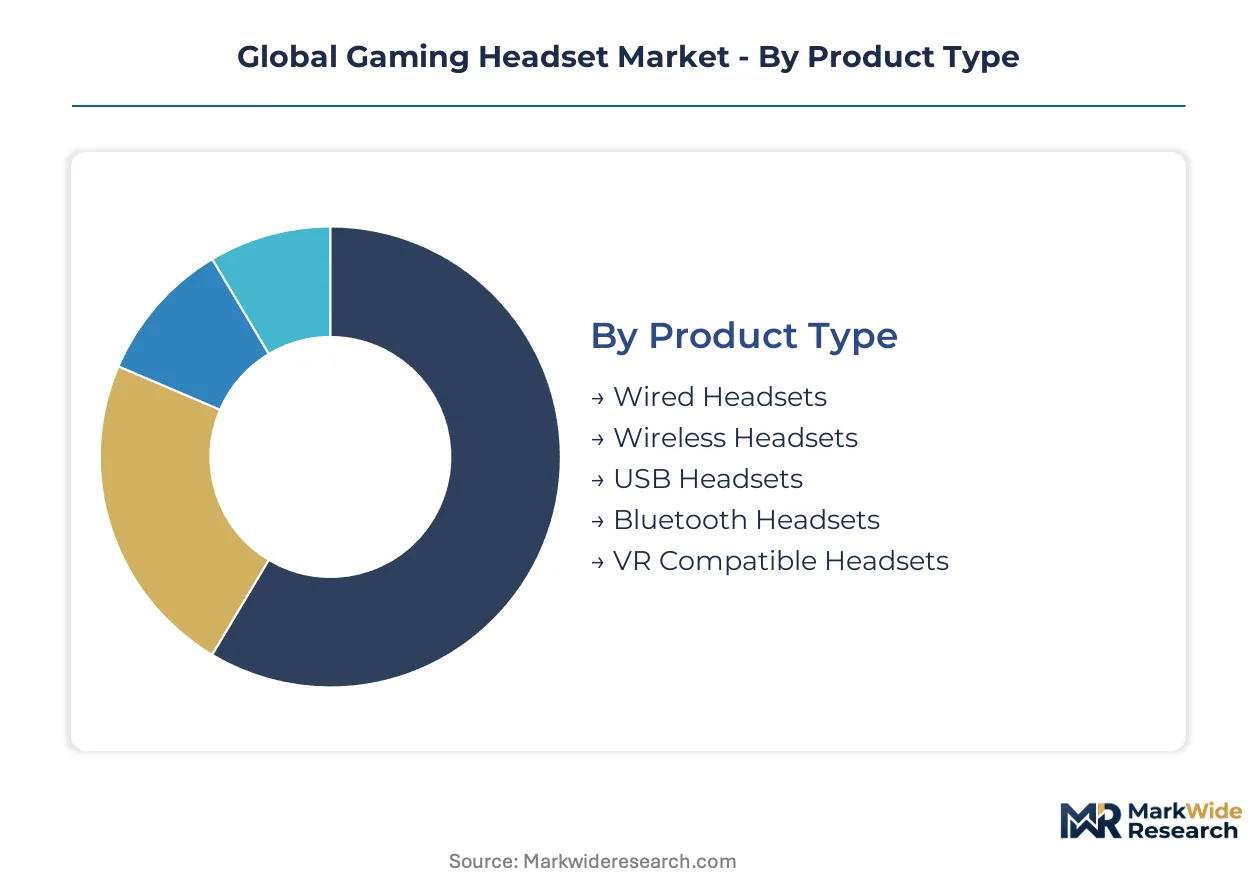
Gaming headset segmentation reveals divergent procurement patterns across competitive tiers. Manufacturers must align transducer specifications, wireless protocols, and certification grades with distinct buyer willingness-to-pay thresholds.
Product Type:
Buyers in this category differentiate by latency tolerance and platform mobility requirements.
- Wireless Headsets:Proprietary 2.4 GHz implementations now compress latency below 20 milliseconds, displacing legacy Bluetooth for competitive applications in South Korean esports clusters. Tournament-grade certification requirements pull replacement cycles toward premium transducer tiers.
- Wired Headsets:Analog connectivity persists in console gaming for zero-latency reliability and eliminates battery weight penalties. USB-C and 3.5 mm configurations dominate absolute volume through bundled OEM sales with gaming peripherals.
- USB Headsets:Digital signal processing enables firmware-upgradable EQ profiles favored by PC gaming enthusiasts.
- Bluetooth Headsets:Standard Bluetooth stacks retain utility in mobile gaming and casual commuting use cases where latency tolerance exceeds 40 milliseconds.
- VR Compatible Headsets:Six-degrees-of-freedom audio tracking demands binaural rendering partnerships with immersive platform operators, creating concentrated margin pools.
Volume sits with wired configurations; growth tilts toward wireless headsets.
Technology:
Technology selection tracks the shift from hardware specifications toward firmware sophistication and sensory convergence.
- Virtual Surround Sound:Dolby and DTS spatial audio encoding extracts per-unit royalties that compress margins on mid-tier hardware. Proprietary implementations by Razer and Logitech circumvent licensing costs in premium tiers.
- Noise Cancellation:Beamforming microphone arrays unify voice isolation with environmental awareness, eliminating secondary boom mics for tournament broadcast clarity.
- RGB Lighting:Addressable LED ecosystems drive brand differentiation in streaming-visible setups.
- Haptic Feedback:Vibration motors synchronized to low-frequency audio enhance immersion in racing and combat simulation titles.
- Microphone Quality:Unidirectional and bidirectional arrays remain the primary voice capture specification for competitive communication.
Revenue concentrates in virtual surround implementations; expansion accelerates most quickly in noise cancellation.
Application:
Application segmentation maps directly to hardware certification requirements and replacement cycle velocity.
- Console Gaming:Sony, Microsoft, and Nintendo maintain incompatible wireless pairing protocols, forcing SKU proliferation and inventory complexity across platform-specific product lines.
- Esports:Professional leagues mandate broadcast-grade audio certification, sustaining accelerated refresh rates in Seoul and Busan professional player bases.
- PC Gaming:Open ecosystem compatibility enables multi-platform wireless dongles and software-customizable audio profiles.
- Mobile Gaming:Bluetooth dominance persists where form factor constraints prioritize portability over positional audio accuracy.
- Streaming:Beamforming arrays compress previously separate microphone and headset categories into single-SKU solutions.
Console gaming anchors absolute volume; esports commands premium pricing expansion.
End User:
End user categories stratify by upgrade cadence and sensitivity to transducer heritage versus ecosystem integration.
- Professional Gamers:Spatial audio accuracy requirements in South Korean and Japanese markets drive sub-24-month replacement cycles, with highest enrollment elasticity in direct-to-consumer subscription programs.
- Content Creators:Broadcast-grade voice isolation and RGB visibility for on-camera setups command tiered pricing premiums.
- Casual Gamers:Price-sensitive procurement concentrates in bundled retail channels and entry-level USB configurations.
- Streamers:Unified microphone-headset convergence reduces equipment complexity for solo broadcast operations.
- Game Developers:Reference-grade transducer accuracy for audio asset validation pulls toward audiophile crossover segments.
Professional gamers concentrate replacement velocity; content creators capture expanding margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Songdo International Business District hosts concentrated esports infrastructure that accelerates hardware procurement cycles for broadcast-grade audio equipment. Tax incentives for gaming technology firms in this zone pull manufacturing partnerships toward Incheon and Seoul.
United States
FCC emissions testing mandates for wireless gaming headsets elevate compliance costs for multi-platform product lines. The IRA's domestic manufacturing incentives support acoustic engineering facilities in Austin and Seattle. Tournament organizers in Los Angeles and Atlanta drive certification requirements for professional-grade transducer specifications.
Germany
REACH substance restrictions on phthalates and flame retardants compel reformulation of cable insulation and ear cushion foams. ECHA enforcement creates first-mover advantages for compliant polyurethane suppliers. Industrial clusters in Bavaria and Baden-Württemberg concentrate transducer heritage expertise for audiophile crossover segments.
China
SAMR enforces GB standard compliance for acoustic output limits on consumer electronics. Rare earth processing concentration in Chinese refining facilities exposes driver manufacturing to neodymium magnet supply volatility. Shenzhen and Dongguan anchor contract manufacturing scale for wireless protocol implementations.
Japan
METI standards govern radio frequency allocations for low-latency gaming peripherals. Spatial audio firmware licensing requirements from Dolby and DTS extract per-unit royalties that compress margins on mid-tier hardware. Tokyo and Osaka sustain professional player bases with sub-24-month headset replacement cycles.
Global Gaming Headset Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium tiers consolidating around acoustic engineering heritage while volume production fragments across Southeast Asian facilities. Three archetypes dominate: transducer-heritage audio houses, ecosystem-integrated peripheral giants, and esports-certified specialists. Competitive maneuvering concentrates on strategic partnerships with immersive platform operators and backward integration into rare earth magnet supply chains.
Within the transducer-heritage tier, Sennheiser and EPOS exemplify engineering-first positioning anchored by German acoustic R&D traditions. Razer occupies a position representing the ecosystem-integrated archetype, leveraging in-house firmware development and direct-to-consumer subscription programs. Logitech anchors the scale-driven segment through manufacturing footprint diversification across multiple Southeast Asian facilities.
| Leading Market Players |
|---|
| Logitech |
| Razer |
| HyperX |
| Corsair |
| Turtle Beach |
| SteelSeries |
| Sony |
| Sennheiser |
| EPOS |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up peripheral specialists now dominate mid-tier manufacturing, compressing procurement timelines and enforcing stricter payment discipline on polyurethane foam and driver component suppliers. This ownership pattern concentrates pricing power with consolidated OEMs while fragmenting margin retention across Southeast Asian contract manufacturers.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to tournament-grade certification batches, while spot inventory of legacy Bluetooth SKUs trades at distressed clearing levels. Pricing stratifies across premium, standard, and economy tiers, with esports certification and spatial audio licensing driving differentiation. Cost compression in mid-tier wireless units is intensifying because Dolby and DTS per-unit royalties extract fixed percentage points regardless of hardware BOM. Casual gamers in bundled retail channels exhibit highest price sensitivity, while professional players in Seoul and Busan demonstrate lowest elasticity.
Supply Chain Analysis
Workforce availability constraints in Dongguan and Shenzhen are elevating wage premiums for RF engineering talent specialized in 2.4 GHz protocol implementation. Manufacturing concentrates in China, Vietnam, and Malaysia, with rare earth magnet processing tethered to Chinese refining facilities. Supply chain risk centers on neodymium export quota volatility from concentrated refining operations. Distribution runs through direct-to-consumer subscription platforms and specialized esports retail channels in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-regional certification cost escalation is forcing sub-scale manufacturers toward distressed exits, creating consolidation opportunities for well-capitalized incumbents with compliant material stacks already validated.
For Market Incumbents: Acquire acoustic engineering talent pools in Bavaria and Baden-Württemberg to secure transducer design capabilities against Japanese specialist competition. Backward integration into rare earth magnet supply chains mitigates Chinese export quota exposure. Invest in REACH-compliant polyurethane foam qualification to maintain EU market access while competitors face eighteen-month validation delays. For New Entrants and Emerging Players: India's esports infrastructure construction in Mumbai and Bangalore represents an underserved buyer archetype with accelerating arena procurement timelines. Tournament-grade distribution partnerships offer the most penetrable entry vector against established brand recognition in developed markets. Direct-to-consumer subscription pilots in South Korea demonstrate enrollment elasticity that can fund initial scale. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with existing FCC and SAMR certification portfolios in Vietnam and Malaysia. Long-term viability hinges on captive relationships with immersive platform operators for spatial audio firmware licensing. Watch neodymium export quota announcements from Chinese authorities as the primary inflection indicator for input cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Spatial Audio Firmware Partnership | Dolby and DTS licensing agreements secure margin-protected premium tier positioning. |
| REACH-Compliant Material Reformulation | ECHA-validated polyurethane foams create eighteen-month competitive moats in European markets. |
| Direct-to-Consumer Subscription Launch | South Korean and Japanese consumer enrollment patterns fund accelerated R&D cycles. |
| Rare Earth Magnet Backward Integration | Captive neodymium supply insulates driver manufacturing from Chinese export quota volatility. |
| VR Platform Binaural Rendering Integration | Six-degrees-of-freedom audio tracking partnerships unlock concentrated margin pools. |
Methodological Framework
Multi-period observation of wireless protocol adoption rates, certification timeline compression, and esports tournament procurement cycles anchored the trend analysis, supplemented by interviews with acoustic engineering directors, esports league operations managers, polyurethane foam procurement leads, and retail channel category buyers. Secondary validation drew from FCC equipment authorization databases, ECHA REACH registration dossiers, SAMR GB standard filings, and customs trade records for neodymium magnet imports. Bottom-up headset shipment modeling triangulated against top-down gaming peripheral market sizing.
Segment-weighting across product type, technology tier, application, and end-user archetype informed volume and value outputs throughout the forecast period. CAGRs derived from replacement cycle velocity differentials between professional and casual gamer segments, with spatial audio firmware penetration and VR headset attach rates as gaming-specific demand drivers. Regional weightings reflected esports infrastructure investment pipelines and regulatory compliance cost burdens.
Revisions become necessary when neodymium export quota restrictions, REACH substance list expansions, or console platform interoperability mandates materialize outside baseline assumptions. Forecasts reflect documented input parameters and scenario-tested elasticity coefficients. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
India Gaming Market
Gaming
VR Melee Games Market
Gaming
Console Games Market
Gaming
Galgames Market
Gaming
China Gaming Headsets Market
Gaming
Global Battle Royale Games Market
Gaming
Gaming Accessories Market
Gaming
SLG Game Market
Gaming
Simulation Video Game Market
Gaming
Mobile Game Software Market
Gaming
Gaming As a Service Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
GCC Gaming Headsets Market
Gaming
AAA Games Market
Gaming
VR Racing Gaming Market
Gaming
United States Gaming Market