
 PC Games Market | 2026-2036
PC Games Market Size, Share, and Industry Trends Forecast 2026-2036
PC Games Market Analysis
The gap between premium AAA releases and free-to-play live service titles is recalibrating how studios allocate development budgets and monetization engineering. Valve Corporation anchors its position through Steam's control of digital distribution infrastructure and workshop creator economies. Epic Games leverages its Unreal Engine licensing to sustain cross-platform technology leadership while operating the Epic Games Store as a direct retail channel.
PC games constitute interactive software applications designed for personal computer hardware configurations, typically requiring discrete graphics processing units with dedicated video memory and operating through keyboard-mouse or controller input schemes for real-time user feedback. Their commercial purpose centers on delivering immersive entertainment experiences while generating recurring revenue through ongoing content updates and player engagement systems. Digital download distribution now captures the dominant volume flow, while subscription payment models are expanding fastest among casual gamers seeking catalog breadth over individual title ownership. In-game purchases within free-to-play structures concentrate the highest margin pools, particularly in multiplayer RPG and simulation genres where cosmetic and progression-based microtransactions sustain long-tail monetization.
China's NMPA and SAMR jointly govern content licensing and anti-addiction playtime restrictions for domestic releases, directly shaping product design requirements and market access timelines for publishers targeting that territory. The EU's GDPR and Digital Services Act impose data handling transparency obligations on platforms collecting player behavioral analytics across European markets. Stakeholders must monitor how fragmented regulatory frameworks around loot box probability disclosures and minor protection standards are diverging across jurisdictions, forcing region-specific compliance architectures rather than unified global product builds.
Market Dynamics
The convergence of live-service monetization and cloud-streaming infrastructure is compressing development cycles while fragmenting player loyalty across competing platforms.
Growth Catalysts
- Esports Broadcasting Investment:Professional leagues in South Korea and Brazil draw sustained capital from streaming platforms and endemic sponsors, expanding tournament prize pools and viewership infrastructure.
- MIIT Content Acceleration:China's Ministry of Industry and Information Technology has tightened domestic approval timelines, reducing publisher wait periods for monetization licenses.
- Ray Tracing Hardware:NVIDIA DLSS and AMD FSR upscaling technologies lower GPU entry barriers, enabling real-time lighting effects on mid-tier hardware configurations.
Market Restraints
- Silicon Supply Concentration:Taiwan Semiconductor Manufacturing anchors advanced node production for discrete GPUs, creating single-point vulnerability in graphics card availability.
- SAMR Anti-Addiction Enforcement:China's State Administration for Market Regulation mandates strict playtime tracking and spending caps for minors, forcing region-specific build architectures.
- Live-Service Burnout:Player retention fatigue across battle royale and extraction shooter genres elevates customer acquisition costs for new entrants.
Strategic Opportunities
- India Broadband Expansion:Reliance Jio's fiber rollout and affordable 5G pricing create first-wave PC gaming adoption in tier-2 cities previously constrained by connectivity.
- GDPR Analytics Innovation:EU publishers are pioneering privacy-preserving behavioral modeling that complies with data minimization while sustaining engagement personalization.
- Modding Platform Monetization:Steam Workshop and Nexus Mods enable creator economies where user-generated content extends title lifecycles without studio development overhead.
Industry Challenges
- Shader Programming Talent:Real-time graphics engineering expertise concentrates at established studios, constraining indie teams from optimizing for diverse hardware configurations.
- Multi-Platform Certification:Anti-cheat kernel-level drivers require separate validation paths for Windows, Linux, and cloud-streaming environments, extending QA timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PC Games Market |
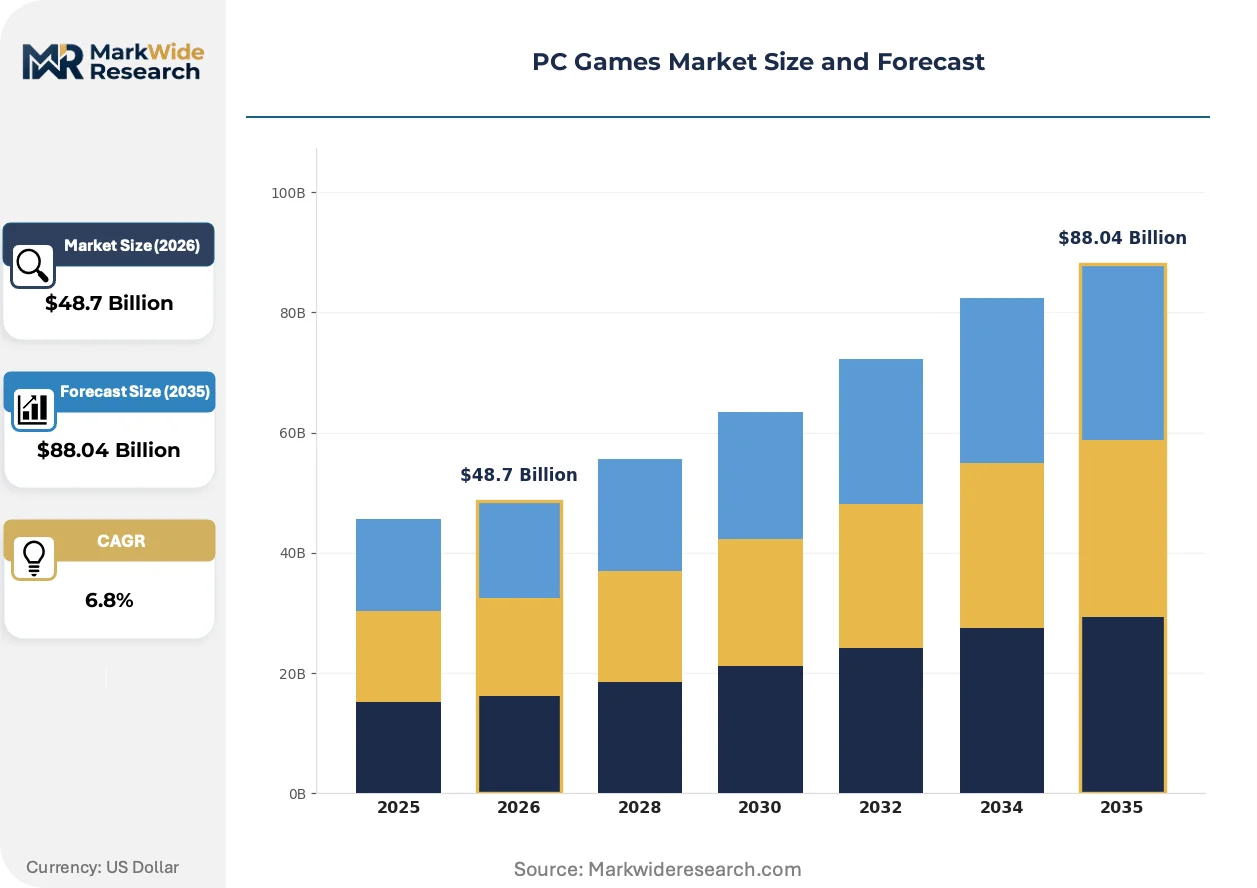
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Action, Adventure, RPG, Simulation Distribution Channel: Digital Download, Retail, Streaming, Subscription User Demographics: Casual Gamers, Competitive Gamers, Esports Players, Content Creators Payment Model: Free-to-Play, Premium, Pay-to-Play, In-Game Purchases |
| Companies Covered | Tencent Interactive Entertainment, Epic Games, Valve Corporation, Take-Two Interactive, Roblox Corporation, Electronic Arts, NetEase Games, Nexon, Microsoft Gaming, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PC Games Market Emerging Trajectories
Generative tooling and decentralized distribution are redrawing how titles reach audiences and how studios resource production pipelines.
AI-assisted asset generation is overtaking manual environment art pipelines. Mid-size studios deploy Stable Diffusion and proprietary machine learning models for texture synthesis and concept iteration. This compression of pre-production labor is enabling smaller teams to ship open-world scope without proportional headcount expansion.
GDPR's Digital Services Act transparency mandates force platforms to disclose recommendation algorithms and player data flows. European publishers now architect consent-layered analytics that preserve engagement measurement while satisfying CNIL and national data protection authority audits. Studios targeting EU distribution must maintain separate telemetry builds from North American and Asian deployments.
Subscription catalog breadth is displacing individual title ownership among casual segments. Xbox Game Pass and Humble Choice aggregate libraries where discovery replaces purchase intent. This rotation toward access-over-ownership concentrates player hours in service-based titles, pressuring premium single-release economics in Germany and Nordic markets where subscription penetration runs highest.
PC Games Market Segmentation
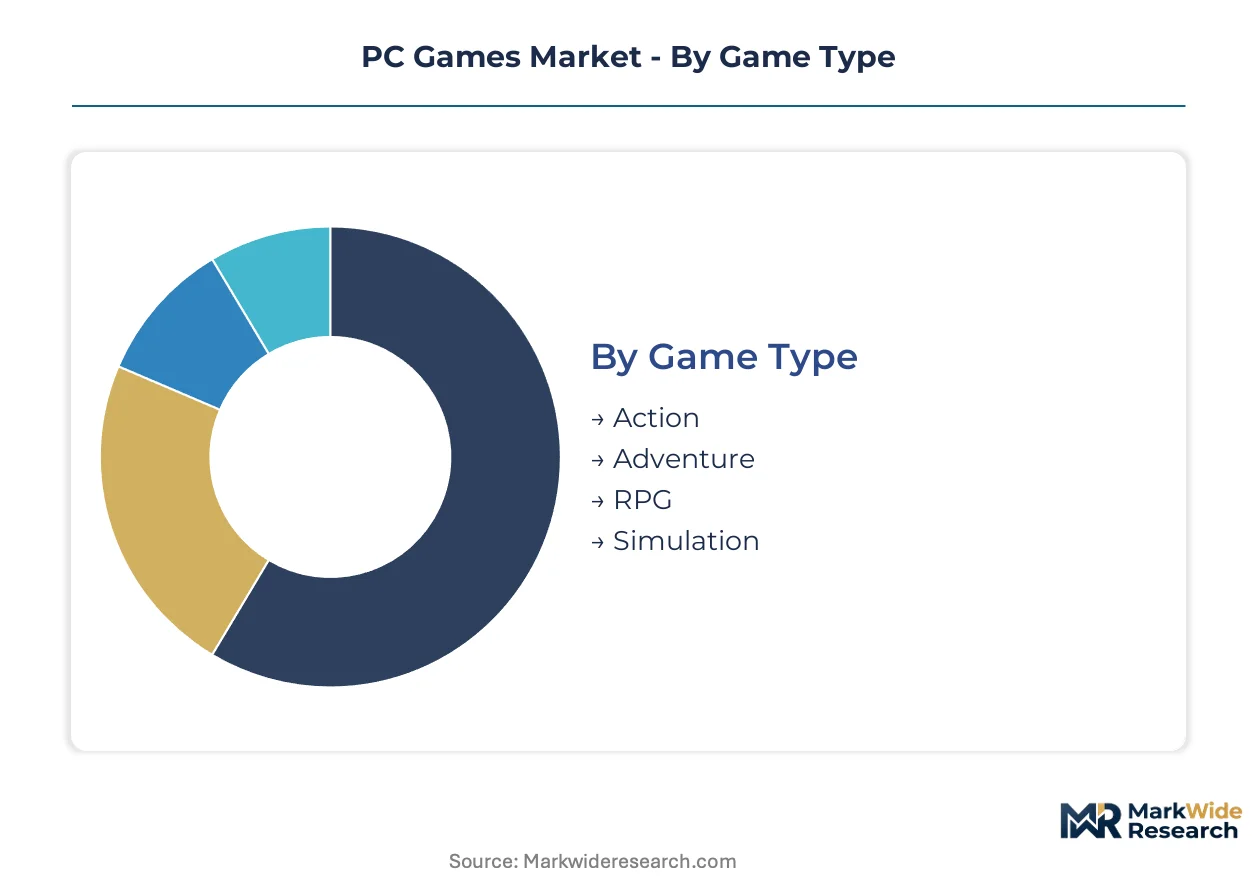
PC games segment across four critical dimensions that determine monetization architecture and distribution strategy. Each category carries distinct margin profiles, player engagement patterns, and regulatory exposure that shape studio resource allocation.
Game Type:
Volume concentrates in multiplayer service titles while premium single-player releases command higher per-unit economics.
- Action:Fast-twitch combat mechanics dominate player hours in South Korea's PC bang venues. Competitive ranking systems sustain retention through seasonal battle passes and cosmetic microtransactions.
- RPG:Narrative-driven progression systems with character customization generate the highest per-player lifetime value. China's SAMR anti-addiction rules force session-length engineering compromises in this segment.
- Adventure:Exploration-focused mechanics attract episodic content models. Environmental storytelling reduces localization costs for multi-territory releases.
- Simulation:Sandbox mechanics enable user-generated content ecosystems. Modding platform integration extends commercial lifecycles without studio development overhead.
Today's leader: Action. Tomorrow's challenger: RPG.
Distribution Channel:
Digital infrastructure is displacing physical retail while subscription models reshape discovery economics.
- Digital Download:Steam and Epic Games Store control discovery algorithms that determine indie commercial viability. Platform fee structures concentrate margin pressure on sub-$30 price points.
- Subscription:Xbox Game Pass and Humble Choice aggregate libraries where access replaces ownership. This model concentrates player hours in service-based titles across Germany and Nordic markets.
- Streaming:Cloud infrastructure reduces GPU hardware barriers for emerging markets. Latency constraints limit competitive multiplayer viability in India's tier-2 cities.
- Retail:Physical box sales survive in collector's editions and hardware bundles. Shelf space contraction accelerates margin compression outside Japan's specialty retailers.
Digital download holds installed base dominance. Subscription services are climbing the fastest.
User Demographics:
Engagement depth and spending willingness diverge sharply across player motivation profiles.
- Competitive Gamers:Ranked ladder systems drive daily active user metrics. Anti-cheat kernel-level investments consume disproportionate QA resources.
- Esports Players:Tournament infrastructure and streaming revenue share sustain professional viability. South Korea's Kespa and Brazil's CBLOL anchor regional league economics.
- Content Creators:Streaming platform algorithm visibility determines title commercial success. OBS integration and spectator modes become standard development requirements.
- Casual Gamers:Session-length constraints favor mobile-to-PC crossover titles. China's MIIT content approval timelines directly shape release calendars for this segment.
Competitive gamers generate the highest revenue density. Content creators determine organic acquisition efficiency.
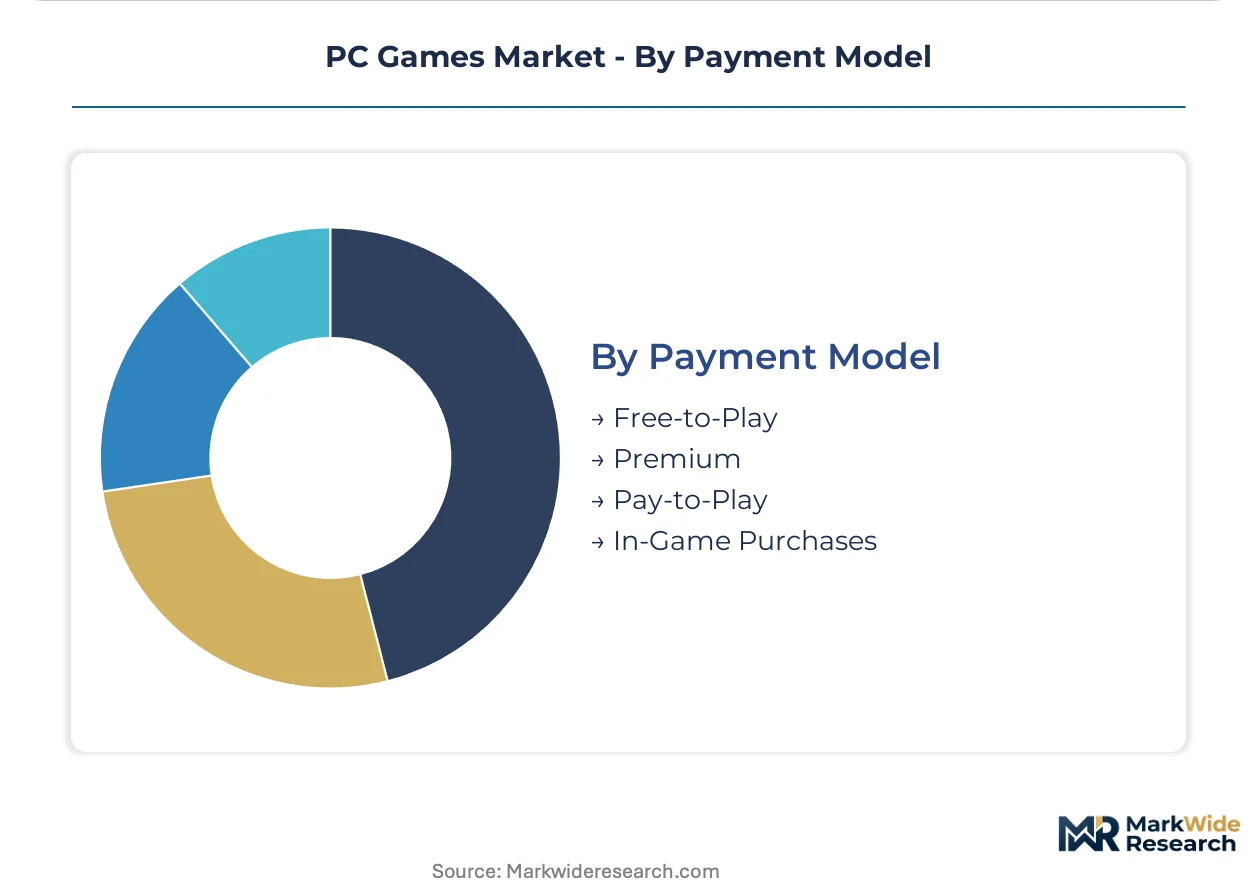
Payment Model:
Free entry with monetized progression now outperforms upfront purchase economics at scale.
- Free-to-Play:Zero barrier to entry maximizes addressable audience. In-game purchase conversion optimization consumes majority of live-service engineering headcount.
- In-Game Purchases:Cosmetic and progression microtransactions yield 70%+ gross margins. Loot box probability disclosure requirements fragment compliance architectures across EU, China, and US jurisdictions.
- Premium:Upfront purchase with post-launch expansion packs sustains single-player economics. Steam's regional pricing tools enable purchasing power parity across emerging markets.
- Pay-to-Play:Subscription-based access with content gates survives in MMO legacy titles. Player resistance to recurring fees limits new entrant viability.
Free-to-play commands player hour share. In-game purchases deliver the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Shenzhen, Seoul, and Austin anchor regional competitive dynamics. Publisher headquarters concentrate in these metros, driving divergent regulatory compliance and monetization architectures.
United States
Esports broadcasting infrastructure and streaming platform investment sustain tournament economics in Los Angeles and Austin. The FTC monitors loot box probability disclosures under consumer protection statutes. Seattle hosts Valve Corporation's Steam operations, controlling digital distribution algorithms that determine indie commercial viability.
China
Domestic publishers face compressed approval timelines under MIIT's tightened content licensing procedures. SAMR enforces anti-addiction playtime restrictions and spending caps for minors, forcing region-specific build architectures. Shenzhen's Tencent Interactive Entertainment anchors the country's multiplayer service title development.
South Korea
PC bang venue culture sustains daily active user metrics for competitive multiplayer titles. The country's game rating board enforces age verification and playtime tracking standards. Seoul's Gangnam district concentrates esports league headquarters and professional team operations.
Germany
Subscription catalog penetration runs highest among casual segments in Berlin and Hamburg. GDPR and the Digital Services Act impose data handling transparency obligations on platforms collecting player behavioral analytics. Munich hosts several mid-size studios pioneering privacy-preserving engagement modeling.
India
Reliance Jio's fiber rollout and affordable 5G pricing enable first-wave PC gaming adoption in tier-2 cities. The country's national telecommunications regulator oversees broadband infrastructure standards without direct content restrictions. Bangalore's technology corridor attracts mobile-to-PC crossover title development.
PC Games Market Vendor Landscape
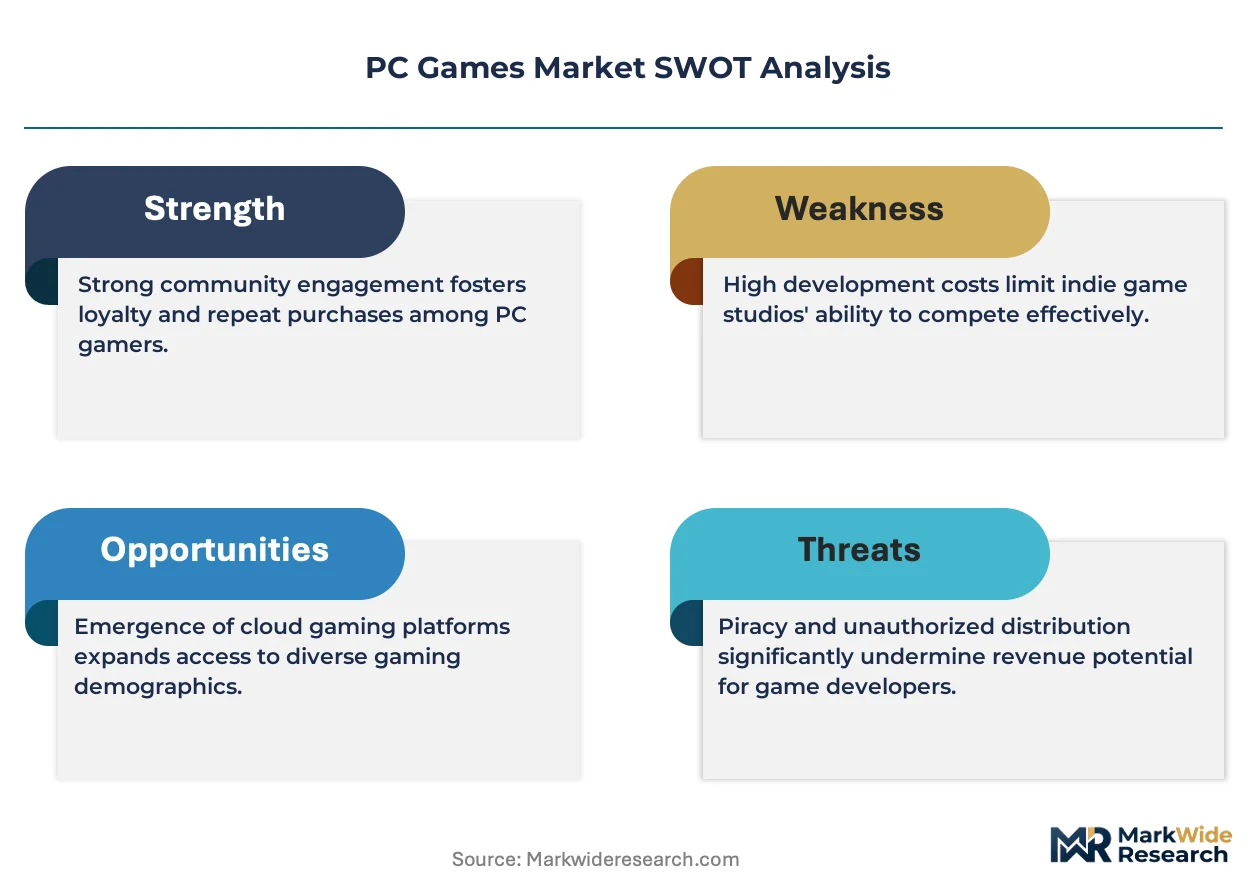
Capital-heavy platform operators compete with asset-light studio developers across divergent monetization models. The structure concentrates around three dominant archetypes: infrastructure owners controlling distribution chokepoints, engine licensors extracting technology rents, and content studios competing for player attention. Strategic moves center on exclusive catalog acquisition and cross-platform technology standardization.
Within the infrastructure-owner tier, Valve Corporation and Epic Games exemplify divergent approaches to digital distribution control. Tencent Interactive Entertainment anchors the Asia-Pacific multiplayer service segment. These entities occupy positions that determine discovery economics for smaller studios dependent on their platforms.
| Leading Market Players |
|---|
| Tencent Interactive Entertainment |
| Epic Games |
| Valve Corporation |
| Take-Two Interactive |
| Roblox Corporation |
| Electronic Arts |
| NetEase Games |
| Nexon |
| Microsoft Gaming |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and associated data center efficiency mandates gate both qualified GPU supply and premium-tier cloud gaming pricing access, as sustainability compliance becomes a prerequisite for hyperscaler procurement contracts and consumer-facing subscription tiers.
Pricing Analysis
The bundled-vs-unbundled service split defines PC gaming's pricing architecture. Subscription catalog access through Xbox Game Pass and Humble Choice displaces individual title ownership in Germany and Nordic markets, while free-to-play monetization with cosmetic microtransactions sustains highest-margin economics in South Korea's PC bang venues. Price differentiation hinges on content exclusivity windows and cross-platform progression features. Cost compression in mid-tier GPU hardware is intensifying because NVIDIA DLSS and AMD FSR upscaling reduce entry-barrier specifications. Casual gamers exhibit greatest price sensitivity, whereas esports competitors accept premium peripheral and subscription costs for competitive integrity.
Supply Chain Analysis
Advanced node GPU supply rests on Taiwan Semiconductor Manufacturing, South Korean memory fabricators, and NVIDIA's fabless design operations in the United States. Silicon wafer processing, GDDR6X memory modules, and vapor chamber cooling assemblies constitute critical input dependencies. Single-source vulnerability concentrates in TSMC's 4nm and 5nm foundry capacity, where geopolitical exposure and earthquake risk in Hsinchu create supply continuity threats. Distribution runs through Valve's Steam platform and Epic Games Store for digital titles, with physical retail surviving only in Japan's specialty collector markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PC gaming represents a margin-expansion story as cloud infrastructure amortization and AI-assisted asset generation compress per-title development costs while premium live-service economics concentrate player spending.
For Market Incumbents: Anchor platform dominance through exclusive catalog acquisition and cross-platform save-state standardization. Defend against emerging cloud-native entrants by deepening Steam Workshop creator economies that extend title lifecycles without studio overhead. Prioritize kernel-level anti-cheat R&D investments as regulatory fragmentation across China's SAMR and EU GDPR forces separate build architectures. For New Entrants and Emerging Players: Launch via India's tier-2 city broadband expansion as Reliance Jio's fiber rollout creates first-wave adoption without entrenched platform loyalty. Target simulation and adventure genres where modding platform integration reduces content production requirements. Pursue direct-to-creator distribution through Nexus Mods and itch.io to bypass Steam's 30% platform fee. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-size studios with proprietary engine technology and established live-service operations. Long-term viability favors entities with privacy-preserving analytics capabilities compliant with GDPR's Digital Services Act transparency mandates. Watch cloud-streaming latency improvements in competitive multiplayer as the inflection signal for infrastructure-heavy platform bets.| Strategic Initiative | Industry Significance |
|---|---|
| Live-Service Platform Integration | Steam's workshop creator economies extend commercial lifecycles without proportional development headcount expansion. |
| Cross-Platform Save-State Standardization | Epic Games' Epic Online Services enables player progression continuity across PC, console, and mobile deployments. |
| Privacy-Preserving Analytics Investment | Munich-based studios pioneer GDPR-compliant behavioral modeling that satisfies CNIL audits while sustaining engagement personalization. |
| Cloud-Native Development Pipeline | AI-assisted asset generation through Stable Diffusion compression reduces pre-production labor for open-world scope titles. |
| Emerging Market Distribution Partnership | Reliance Jio's fiber infrastructure in India's tier-2 cities enables first-wave PC gaming adoption without GPU hardware barriers. |
Methodological Framework
Direct dialogue with game development executives, platform engineering leads, esports league operators, and regulatory affairs specialists at publishers targeting China and EU territories grounded this analysis. Secondary validation drew from NMPA content licensing disclosures, GDPR enforcement actions by CNIL and national data protection authorities, SEC filings by publicly traded platform operators, and Steam concurrent player statistics. Bottom-up title-level revenue modeling and top-down platform fee structure analysis were triangulated against regional hardware shipment data.
Segmentation outputs across game type, distribution channel, user demographic, and payment model were generated through the projection horizon. CAGRs were derived from installed base expansion in broadband-enabled markets and monetization rate evolution in free-to-play service titles. Forecast inputs incorporated MIIT approval timeline volatility, SAMR anti-addiction enforcement intensity, and cloud-streaming latency improvement trajectories in competitive multiplayer segments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios or sudden regulatory tightening in China's content licensing regime. Forecasts reflect assumptions regarding sustained esports broadcasting investment and stable GPU pricing following node transition cycles. A small set of named triggers—MIIT approval backlog spikes, TSMC foundry allocation shifts, and EU Digital Services Act enforcement patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Racing Games Market
Gaming
Connected Game Console Market
Gaming
Gaming Software Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
United Kingdom Online Gambling Market
Gaming
3D Gaming Technology Market
Gaming
South Asia Mobile Gaming Market
Gaming
Online Casual Games Market
Gaming
Video Game Software Market
Gaming
Shooter Game Market
Gaming
Serious Games Market
Gaming
Animation, VFX & Game Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Global Gaming Headset Market
Gaming
Metaverse in Gaming Market