
 VR Gaming Console Market | 2026-2036
VR Gaming Console Market Size, Share, and Industry Trends Forecast 2026-2036
VR Gaming Console Market Analytics
Arcade and location-based entertainment venues is repositioning toward home consumer segments as tethered installations give way to portable standalone systems. Meta leverages its social platform ecosystem to anchor hardware-software integration across consumer channels. Sony sustains competitive pressure through exclusive content pipelines tied to its established gaming franchises. Valve differentiates by cultivating enthusiast-grade PC-connected ecosystems with open distribution architecture.
A VR gaming console denotes a dedicated computing device engineered to render stereoscopic 3D environments at refresh rates exceeding 90 Hz through integrated or tethered head-mounted displays, employing inside-out or external tracking systems for six-degrees-of-freedom positional input. These systems serve commercial and consumer markets by delivering immersive interactive entertainment, training simulations, and spatial computing experiences. Standalone consoles capture the fastest expansion trajectory as system-on-chip advances reduce reliance on external processing hardware. PC-connected consoles retain margin concentration among enthusiast segments demanding uncompromised visual fidelity. Hybrid consoles attract transitional users seeking flexibility between portable and docked operational modes.
The FCC governs wireless spectrum allocation and RF exposure limits for untethered VR headsets in the United States, while the EU AI Act imposes algorithmic transparency obligations on adaptive rendering and biometric tracking features. CE marking and RoHS compliance shape hardware import pathways and material selection across European distribution channels. Stakeholders must monitor evolving electromagnetic emissions thresholds and content rating harmonization as regulatory fragmentation threatens cross-border deployment scalability.
Market Dynamics
Standalone system-on-chip architectures are compressing the addressable market for tethered PC-dependent headsets while forcing incumbents to reconfigure content licensing and hardware margin structures around portable form factors.
Growth Catalysts
- EU AI Act transparency mandates:Biometric tracking restrictions in the European Union are accelerating on-device inference chip deployment, creating hardware upgrade cycles among privacy-conscious consumers.
- Location-based entertainment venue expansion:Arcade operators in Japan and the United States are deploying wireless headsets for multiplayer immersive attractions, driving bulk procurement contracts.
- Eye-tracking foveated rendering:This display technology reduces GPU load by 40-50% in supported titles, extending battery life in standalone units and lowering thermal design constraints.
Market Restraints
- Display panel supply concentration:High-resolution micro-OLED fabrication capacity clusters in South Korean and Chinese foundries, creating input bottlenecks for mid-tier manufacturers.
- GDPR biometric data classification:Pupil dilation and gaze pattern collection triggers heightened consent requirements in European markets, complicating adaptive rendering feature rollouts.
- Smartphone-based VR substitution:Samsung and Apple smartphone-tethered viewers capture casual immersive gaming demand at sub-console price points.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor assembly and testing are attracting contract manufacturers to establish regional headset production.
- Enterprise training simulation convergence:Aviation and healthcare sectors are repurposing consumer-grade motion controllers for procedural training, opening B2B licensing channels.
- Cloud-rendering hybrid architectures:5G edge computing partnerships allow lightweight headsets to stream high-fidelity experiences, reducing hardware BOM costs for price-sensitive segments.
Industry Challenges
- Motion-to-photon latency engineering:Sub-20 millisecond pipeline optimization requires specialized signal processing talent that remains scarce outside Apple, Meta, and Sony engineering centers.
- FCC RF exposure certification timelines:Untethered headset approvals for Wi-Fi 6E and 60 GHz mmWave bands face 8-14 month evaluation queues, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Gaming Console Market |
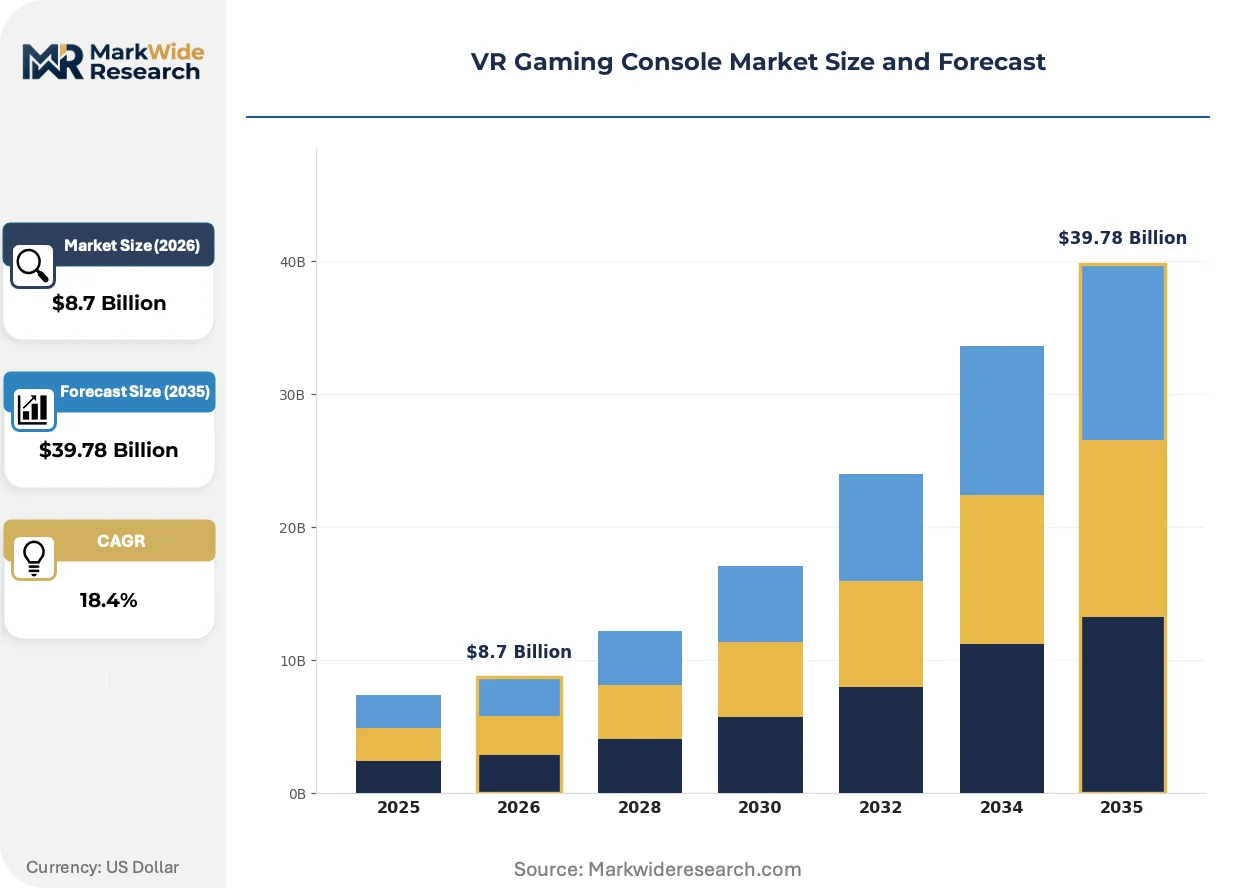
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Consoles, PC-Connected Consoles, Mobile-Integrated Consoles, Hybrid Consoles End User: Casual Gamers, Hardcore Gamers, Educational Institutions, Corporate Training Content Type: Exclusive Games, Multi-Platform Games, Educational Content, Simulation Experiences Distribution Channel: Online Retail, Brick-and-Mortar Stores, Direct Sales, Subscription Services |
| Companies Covered | Samsung, Pico Interactive, Meta, Lenovo, Valve, Sony, HTC, Magic Leap, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Gaming Console Market Evolving Landscape
Compute migration from host PCs toward headset-integrated processors is reconfiguring content distribution economics and thermal engineering priorities across the hardware stack.
Inside-out tracking systems utilizing integrated depth cameras and SLAM algorithms are decentralizing spatial computing hardware requirements. Mid-tier manufacturers in China and Taiwan are adopting Qualcomm Snapdragon XR2+ platforms to bypass external base station dependencies. This silicon integration is compressing the premium attached to room-scale VR and enabling warehouse-scale deployments without infrastructure retrofit.
GDPR Article 35 data protection impact assessments now extend to eye-tracking and biometric inference in immersive environments. European manufacturers are embedding privacy-by-design chipsets that process gaze data locally rather than transmitting to cloud servers. France's CNIL and Germany's regional data protection authorities are auditing adaptive difficulty algorithms for prohibited emotional manipulation, affecting product roadmap prioritization.
Subscription-based content libraries are displacing unit-sale software economics as the dominant monetization model. Meta's Horizon platform and Sony's PSVR2 store are bundling exclusive titles with hardware financing, locking consumers into multi-year content commitments. This shift concentrates recurring revenue with platform operators while compressing margins for independent studios, particularly visible in North American and Japanese consumer segments where premium interactive entertainment spending remains highest.
VR Gaming Console Market Segmentation
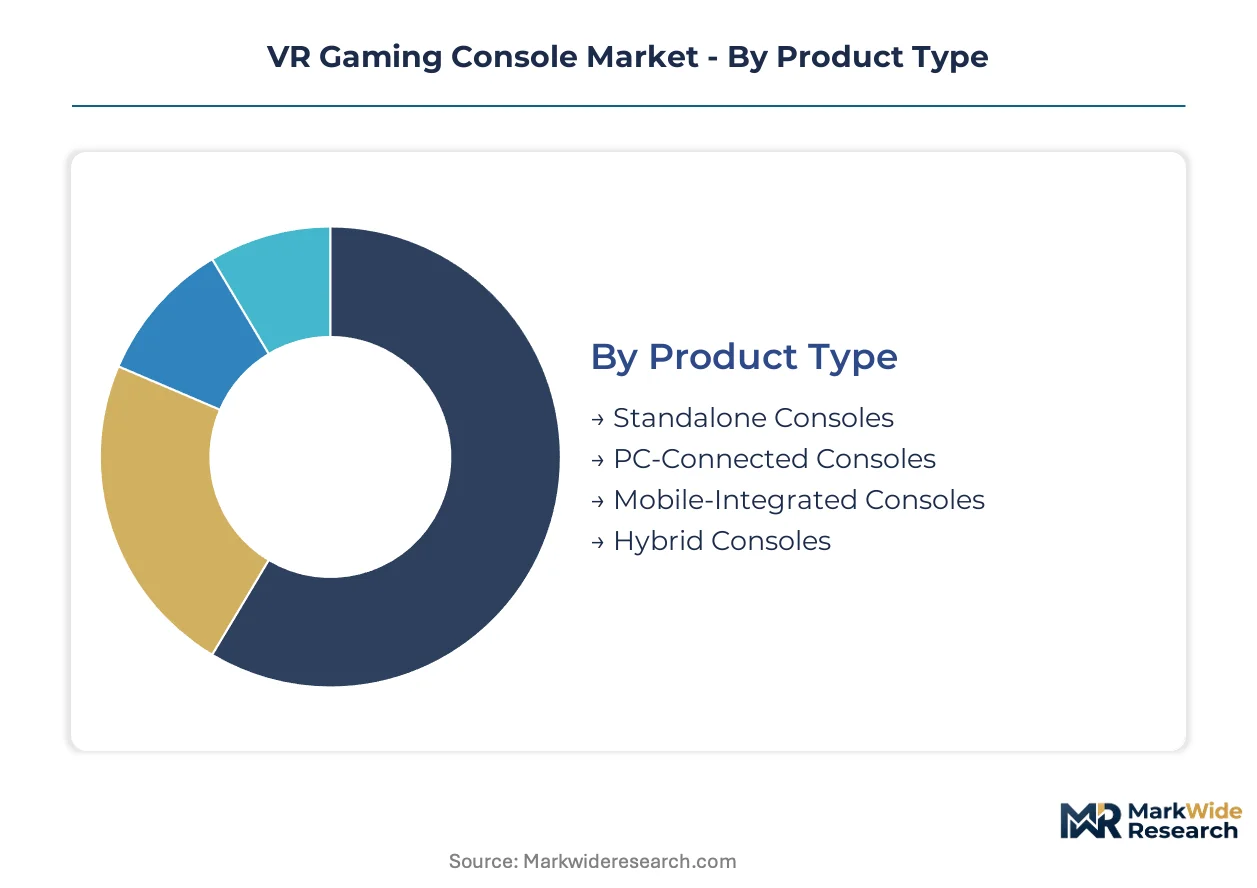
Segmentation in VR gaming consoles reveals how hardware architecture, user sophistication, and content economics split addressable demand into distinct investment profiles. Each dimension carries implications for thermal engineering priorities, licensing structures, and go-to-market economics.
Product Type:
Capital intensity varies sharply across form factors, with integrated system-on-chip designs demanding upfront silicon tape-out costs while tethered configurations externalize compute investment to consumer-owned PCs.
- Standalone Consoles:These headsets embed Qualcomm Snapdragon XR2+ or equivalent SoCs with integrated rendering pipelines, thermal management systems, and battery subsystems. Demand concentrates in the United States and Japan where consumers prioritize untethered mobility for location-based entertainment venues and residential room-scale experiences. Qualcomm's reference design program accelerates time-to-market for mid-tier OEMs.
- PC-Connected Consoles:Tethered headsets rely on external GPU horsepower via DisplayPort or USB-C, minimizing on-device processing and enabling higher-resolution panels. Hardcore gamers in China and South Korea drive procurement for competitive titles demanding sub-20ms motion-to-photon latency.
- Mobile-Integrated Consoles:Smartphone-dependent viewers leverage host device compute and displays, reducing headset BOM to optics and IMU sensors. Samsung and Apple ecosystem lock-in shapes regional penetration patterns.
- Hybrid Consoles:Dockable systems switch between standalone operation and PC-tethered modes, adding mechanical complexity and thermal design challenges. Transitional users in European markets value flexibility amid GDPR-driven local processing requirements.
Standalone configurations absorb the bulk of installed capacity; hybrid designs are expanding most quickly as manufacturers hedge against silicon supply volatility.
End User:
Customer lifetime value diverges dramatically between segments, with institutional buyers negotiating multi-year fleet deployments while individual purchasers drive volatile seasonal demand patterns.
- Casual Gamers:Price-sensitive consumers prioritize content accessibility over technical specifications, typically purchasing through subscription bundles that amortize hardware costs. Meta's Horizon platform captures this segment through social feature integration.
- Hardcore Gamers:Enthusiasts demand 120Hz refresh rates, eye-tracked foveated rendering, and haptic feedback precision. Sony's exclusive content pipeline anchors retention in this high-ARPU cohort.
- Educational Institutions:Schools and universities procure standalone units for STEM visualization and remote collaboration, with procurement cycles tied to fiscal year budgets and grant funding availability.
- Corporate Training:Aviation and healthcare sectors repurpose consumer motion controllers for procedural simulation, requiring enterprise-grade support SLAs and content customization services.
Hardcore gamers generate the highest per-unit margins; corporate training applications are climbing the fastest as safety-critical industries accelerate immersive simulation adoption.
Content Type:
Recurring revenue economics favor platform-controlled distribution, with exclusive titles serving as hardware differentiation while multi-platform availability maximizes addressable audience.
- Exclusive Games:First-party studios develop titles optimized for specific hardware capabilities—eye-tracking, finger tracking, or haptic gloves—creating switching costs for installed bases.
- Multi-Platform Games:Cross-compatible releases from Unity and Unreal Engine developers minimize porting overhead and extend commercial lifespan across console generations.
- Educational Content:Curriculum-aligned experiences in anatomy, physics, and historical reconstruction carry institutional procurement certification requirements distinct from entertainment ratings.
- Simulation Experiences:Non-game spatial computing applications—architectural visualization, therapeutic interventions, social presence platforms—attract B2B licensing models with annual subscription structures.
Exclusive games command premium attach rates at hardware launch; simulation experiences are gaining share fastest as enterprise verticals diversify beyond entertainment.
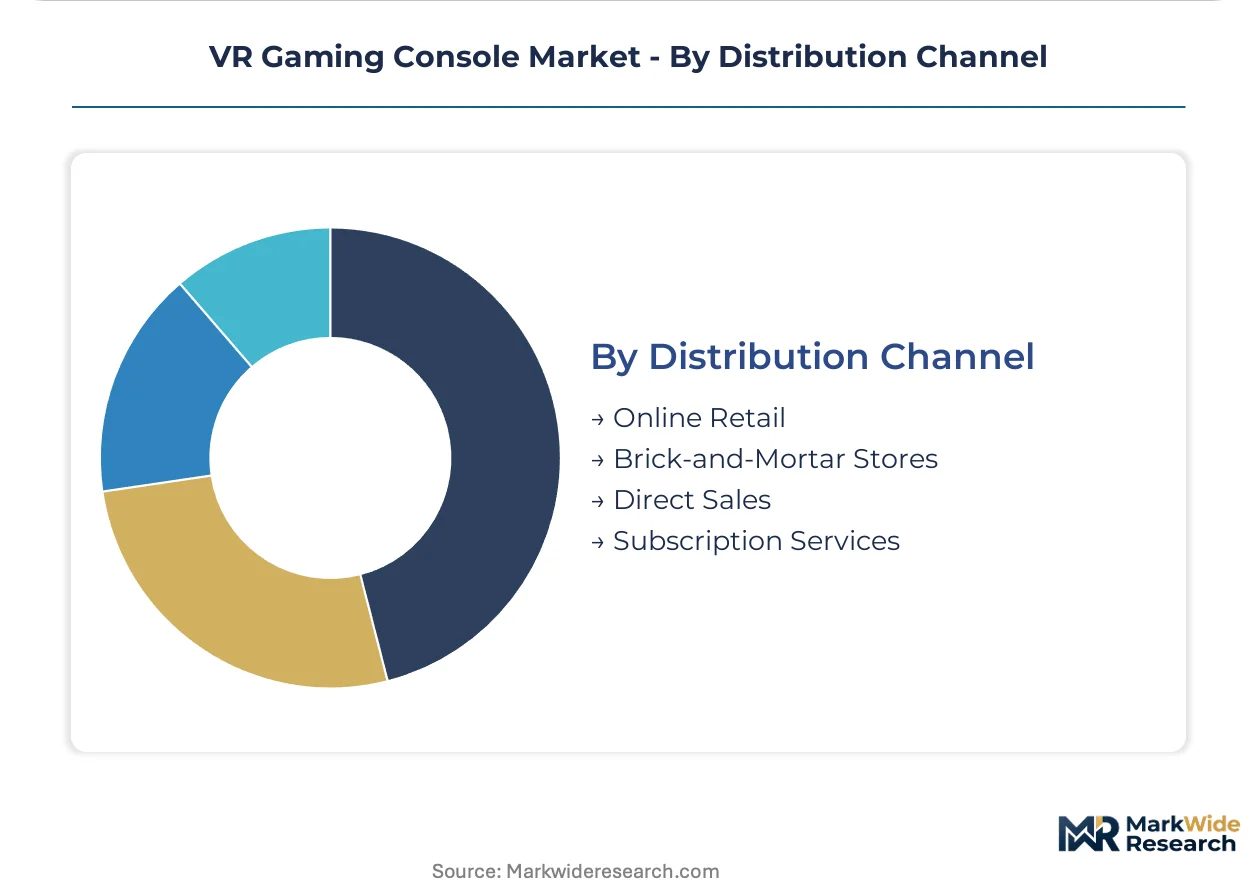
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition cost structures, with direct sales minimizing margin leakage while retail partnerships accelerate mass-market penetration.
- Online Retail:Amazon and specialized electronics marketplaces dominate headset sales in North America and Western Europe, with logistics networks enabling 24-hour fulfillment for impulse purchases.
- Brick-and-Mortar Stores:Physical retail locations in Japan and South Korea provide hands-on demonstration critical for first-time VR adopters, with dedicated floor space driving conversion rates above digital-only channels.
- Direct Sales:Manufacturer-owned storefronts and websites capture full margin and first-party customer data, supporting subscription attach and accessory upsell.
- Subscription Services:Hardware financing bundled with content libraries—Meta Quest+, Sony PSVR2 store—lock consumers into multi-year commitments and reduce upfront price sensitivity.
Online retail moves the highest unit volumes; subscription services are expanding most quickly as platform operators prioritize recurring revenue predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate contract manufacturing capacity for VR headset assembly, while R&D tax credits in California and Tokyo anchor design engineering clusters for next-generation optics.
United States
FCC RF exposure certification timelines shape product launch cadences for Meta and Apple headset releases. The CHIPS and Science Act directs federal funding toward domestic semiconductor packaging facilities in Arizona and Texas. Seattle hosts engineering centers optimizing motion-to-photon latency algorithms for standalone architectures.
China
Pico Interactive and HTC drive procurement of Qualcomm Snapdragon XR2+ reference designs for domestic and export markets. MIIT certification requirements for wireless transmission equipment add 4-6 months to product registration timelines. Shenzhen's Nanshan district clusters lens molding and display driver IC assembly operations for mid-tier OEMs.
Japan
Sony's exclusive content pipeline anchors hardcore gamer demand for PSVR2 hardware. METI subsidies for next-generation display manufacturing support micro-OLED pilot lines in Nagano prefecture. Tokyo's Shibuya and Osaka's Umeda districts concentrate location-based entertainment venues deploying wireless multiplayer systems.
Germany
GDPR biometric data classification complicates eye-tracking feature rollouts for consumer headsets. The KBA and regional data protection authorities audit adaptive difficulty algorithms for prohibited emotional manipulation. Munich's engineering clusters specialize in thermal management solutions for standalone SoC integration.
South Korea
Samsung leverages smartphone ecosystem integration to capture mobile-integrated VR demand. The MFDS and national standards body coordinate electromagnetic emissions testing for Wi-Fi 6E and 60 GHz mmWave bands. Seoul's Gangnam district hosts flagship retail locations driving hands-on demonstration conversion rates above digital channels.
VR Gaming Console Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform operators capturing recurring revenue through content ecosystems while hardware OEMs compete on bill-of-material efficiency. The vendor base concentrates around three strategic archetypes: social platform-integrated ecosystem operators, exclusive content-anchored gaming specialists, and open-architecture PC-connected enthusiasts. Competitive positioning hardens through hardware-software bundling and regional content licensing partnerships.
Among platform-integrated ecosystem operators, Meta exemplifies the social-first archetype through Horizon platform integration. Sony occupies a position as the exclusive content-anchored gaming specialist leveraging established franchise pipelines. Valve sits within the open-architecture enthusiast tier cultivating PC-connected distribution architectures.
| Leading Market Players |
|---|
| Samsung |
| Pico Interactive |
| Meta |
| Lenovo |
| Valve |
| Sony |
| HTC |
| Magic Leap |
| Apple |
| Others |
Value Network & Pricing Analysis
Optical engineering talent clusters in Shenzhen and Taoyuan drive labor-cost differentials that widen spreads between premium micro-OLED headsets and mid-tier LCD alternatives. GDDR memory pricing volatility feeds directly into standalone SoC BOM structures, compressing margins for manufacturers without captive silicon supply.
Pricing Analysis
Lead-time premiums attach to Qualcomm Snapdragon XR2+ reference designs with sub-90-day delivery windows, while spot inventory of prior-generation XR2 silicon trades at discounts. Three-tier pricing structure across premium eye-tracked units, standard standalone headsets, and economy mobile-tethered viewers dominates procurement patterns. Cost compression in the mid-tier is intensifying because display panel supply bottlenecks force manufacturers to absorb component inflation. Casual gamers through subscription bundles show highest price sensitivity; hardcore enthusiasts demonstrate lowest elasticity for sub-20ms latency specifications.
Supply Chain Analysis
CE marking and FCC RF exposure certification gates concentrate qualified supplier pools around established Taiwanese and South Korean foundries with proven regulatory track records. High-resolution micro-OLED fabrication draws from South Korean and Chinese foundries; precision lens molding rests on Japanese and Taiwanese optics houses; battery cell assembly feeds from Chinese and South Korean suppliers. Single-source vulnerability in Qualcomm's XR silicon roadmap threatens second-tier OEM procurement flexibility. Distribution runs through contract manufacturers in Shenzhen and Nanshan for final assembly, with direct-to-consumer channels capturing margin for platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Standalone system-on-chip architectures are displacing tethered PC-dependent configurations, compressing the addressable premium for external GPU horsepower as headset-integrated rendering achieves parity.
For Market Incumbents: Lock in exclusive content pipelines through first-party studio acquisitions before multi-platform engine standardization erodes hardware switching costs. Deepen backward integration into custom silicon design to escape Qualcomm reference design dependency. Eye-tracking foveated rendering IP represents the critical lever for sustaining margin premiums against emerging Chinese OEMs. For New Entrants and Emerging Players: Begin with corporate training simulation verticals where procurement cycles favor new vendors without installed base legacy. India's PLI scheme for electronics manufacturing offers the most penetrable geography for establishing cost-competitive assembly operations. Target aviation and healthcare sectors with motion controller customization services as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with thermal management solution providers given standalone SoC power density challenges and European GDPR-driven local processing mandates. Long-term viability favors vendors with vertical control over optics and silicon rather than pure software platform plays. Watch for FCC certification queue lengths as an inflection indicator for new product launch cadences and working capital intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Development | Reduces Qualcomm dependency for Meta and Apple while enabling proprietary rendering pipelines. |
| First-Party Studio Acquisition | Sony's exclusive content pipeline anchors hardcore gamer retention against multi-platform drift. |
| Enterprise Training Vertical Entry | Aviation sector procurement of repurposed motion controllers opens B2B licensing channels. |
| PLI Scheme Manufacturing Relocation | India's electronics incentives attract contract manufacturers seeking tariff-advantaged export capacity. |
| Privacy-by-Design Chipset Integration | GDPR Article 35 compliance drives European OEMs toward local gaze data processing architectures. |
Research Methodology
Independent corroboration across hardware engineering directors at Meta and Sony, procurement leads at location-based entertainment venue operators, and regulatory affairs specialists at European data protection authorities underwrites the qualitative findings. Primary fieldwork with thermal management engineers in Munich and optical designers in Nagano combined with secondary validation from FCC equipment authorization databases, MIIT certification filings, and Qualcomm reference design disclosures. Bottom-up bill-of-material analysis and top-down market sizing triangulate volume estimates.
Comparable historical periods anchored the projection framework against prior console generation transitions and smartphone-tethered VR adoption curves. Segmentation dimensions span product architecture, end-user sophistication, content monetization model, and regional regulatory cluster. CAGRs derive from installed base growth rates, replacement cycle compression, and content attach rate trajectories. Forecast inputs include SoC power efficiency roadmaps, micro-OLED fab capacity expansion timelines, and 5G edge computing partnership announcements.
GDPR enforcement variance, FCC certification queue extensions, and Qualcomm supply allocation shifts are the dominant revision risks. A model refresh is warranted upon material change in on-device inference chip deployment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
South Korea Gaming Peripherals Market
Gaming
Europe Casino Gambling Market
Gaming
Puzzle Video Game Market
Gaming
Gaming Chair Market
Gaming
Online Casino Market
Gaming
VR Gaming Controller Market
Gaming
Global Casino and Gaming Market
Gaming
VR Racing Gaming Market
Gaming
North America Gaming Market
Gaming
United States Gaming Accessories Market
Gaming
Lottery Market
Gaming
Cloud Gaming Market
Gaming
Australia Casino Tourism Market
Gaming
United Kingdom Online Gambling Market
Gaming
3D Gaming Technology Market
Gaming
China Subscription-Based Gaming Market