
 Video Player Market | 2026-2036
Video Player Market Size, Share, and Industry Trends Forecast 2026-2036
Video Player Market Intelligence
The customer base for video players is broadening from large entertainment companies to a fragmented landscape of individual content creators and small enterprises. Sony Corporation leverages its deep integration with content production to offer premium playback experiences. Roku Inc. specializes in the streaming services segment, building an ecosystem around its hardware. Samsung Electronics Co. Ltd. sustains its market position through the dominance of its hardware-integrated players in the smart TV division.
A video player is software or a hardware-based system designed to decode and render digital video data for playback. These systems support various codecs, such as H.265, and protocols for adaptive bitrate streaming to ensure quality on different networks. Streaming services and SaaS deployment models are seeing high uptake from enterprises and educational institutions. While HTML5 technology has become the standard for web players, AI-powered features for analytics and personalization are an emerging area of differentiation.
Regulatory frameworks directly influence player design and functionality. The European Union's GDPR governs the collection and use of viewer data for analytics, while United States FCC rules mandate accessibility features like closed captioning. These standards compel developers to prioritize both privacy and inclusivity. Key decisions for vendors now revolve around balancing advanced monetization tools with a seamless user experience to secure audience loyalty.
Market Dynamics
The central structural force shaping the video player market is the fragmentation of the user base. Demand is shifting from a concentrated group of large media corporations to a diffuse landscape of small businesses, educational bodies, and individual creators, forcing vendors to adapt product strategies and pricing models.
Growth Catalysts
- Technology Standards:The widespread adoption of efficient codecs like H.265 (HEVC) and protocols for adaptive bitrate streaming enables high-quality video delivery over variable network conditions, supporting expansion in mobile-first markets.
- Educational Sector Uptake:Educational institutions are rapidly integrating video players into online learning platforms and digital curricula, creating a substantial and growing source of demand for reliable, feature-rich playback solutions.
- Advanced Infrastructure:High-speed internet penetration and advanced digital infrastructure in markets such as South Korea and Japan create a fertile ground for sophisticated video services, driving demand for high-performance players.
Market Restraints
- Codec Licensing Complexity:The intricate and often costly patent licensing structures associated with modern codecs, including H.265/HEVC and its successor VVC, create significant financial and legal overhead for player developers.
- Native Platform Competition:The dominance of integrated video playback functionality within major social media and content platforms presents a substitution threat, reducing the need for standalone players for many casual content creators.
- Data Privacy Regulation:Stringent regulations like the EU's GDPR impose strict requirements on obtaining and managing user consent for data collection, complicating the implementation of viewer analytics and personalization features.
Strategic Opportunities
- AI-Powered Analytics:There is a significant opportunity to develop and monetize advanced features using artificial intelligence, such as predictive analytics for audience engagement, automated content tagging, and enhanced personalization engines.
- Interactive Video for Commerce:The convergence of video playback with e-commerce functionalities, such as shoppable tags and in-player checkout, opens new revenue streams for vendors targeting the retail and marketing sectors.
- Emerging Market Expansion:Improving digital infrastructure in regions like Southeast Asia and Latin America presents an opportunity for market entry, targeting a new wave of businesses and content creators coming online.
Industry Challenges
- System Integration Friction:Developers face the operational challenge of ensuring seamless integration of their video players with a diverse and fragmented ecosystem of third-party systems, including content management systems and ad servers.
- Accessibility Compliance:Adhering to evolving accessibility mandates, such as the rules set by the United States FCC for closed captioning and audio descriptions, requires continuous investment in development and testing resources.
- Bandwidth Management:Delivering high-resolution video, including 4K and 8K formats, at scale poses a persistent challenge related to managing server load and last-mile bandwidth costs for content distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Player Market |
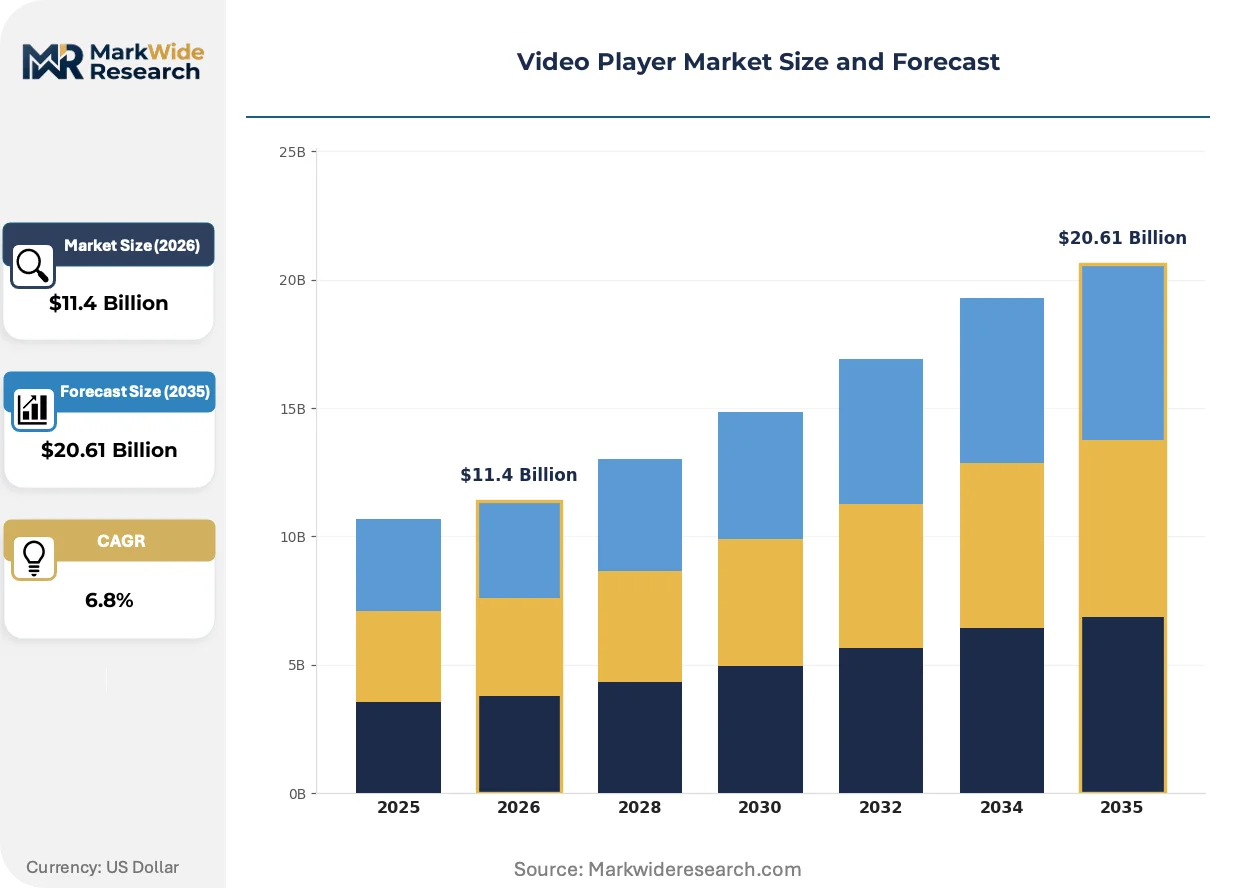
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
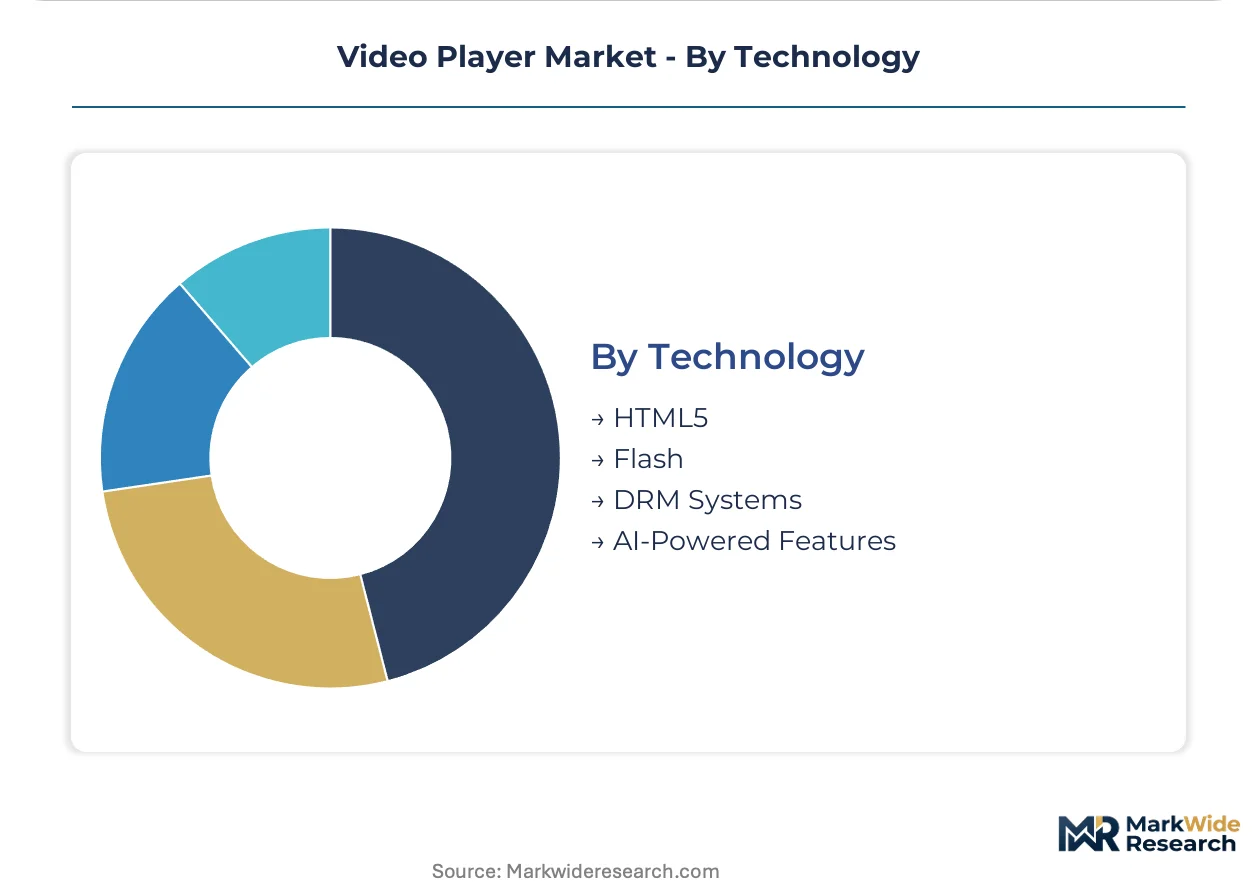
| Segmentation | Product Type: Web Players, Mobile Players, Desktop Applications, Streaming Services Deployment Model: Cloud-Based, On-Premises, Hybrid Solutions, SaaS End User: Content Creators, Entertainment Companies, Educational Institutions, Enterprises Technology: HTML5, Flash, DRM Systems, AI-Powered Features |
| Companies Covered | Samsung Electronics Co. Ltd., LG Electronics Inc., Sony Corporation, Panasonic Corporation, Toshiba Corporation, Philips, Haier Electronics Group Co. Ltd., Roku Inc., Hisense Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Player Market Strategic Shifts & Innovations
The function of a video player is evolving beyond simple media rendering. It is becoming a sophisticated tool for audience engagement, data collection, and monetization, with development focused on intelligence and interactivity rather than just playback stability.
HTML5 technology provides a plugin-free standard for embedding video directly into web pages. Both enterprise and individual users are adopting HTML5 players as the default for web and mobile content delivery. This universal standard is consolidating the development landscape, forcing vendors to compete on advanced features and user experience rather than basic cross-browser compatibility.
The European Union's AI Act establishes a risk-based framework that governs the use of artificial intelligence. This regulation directly shapes the design of AI-driven player features like content recommendation engines and automated video analysis. Vendors operating in or selling into the EU must now build for algorithmic transparency and user control, influencing product roadmaps globally.
A definitive behavioral change is the move from one-time software purchases to recurring, subscription-based SaaS models. This transition affects procurement for both large enterprises and small businesses, which increasingly prefer the financial flexibility and continuous updates of cloud-hosted player platforms. The shift is most apparent in corporate training and digital marketing verticals, where scalability is a primary concern.
Video Player Market Segmentation
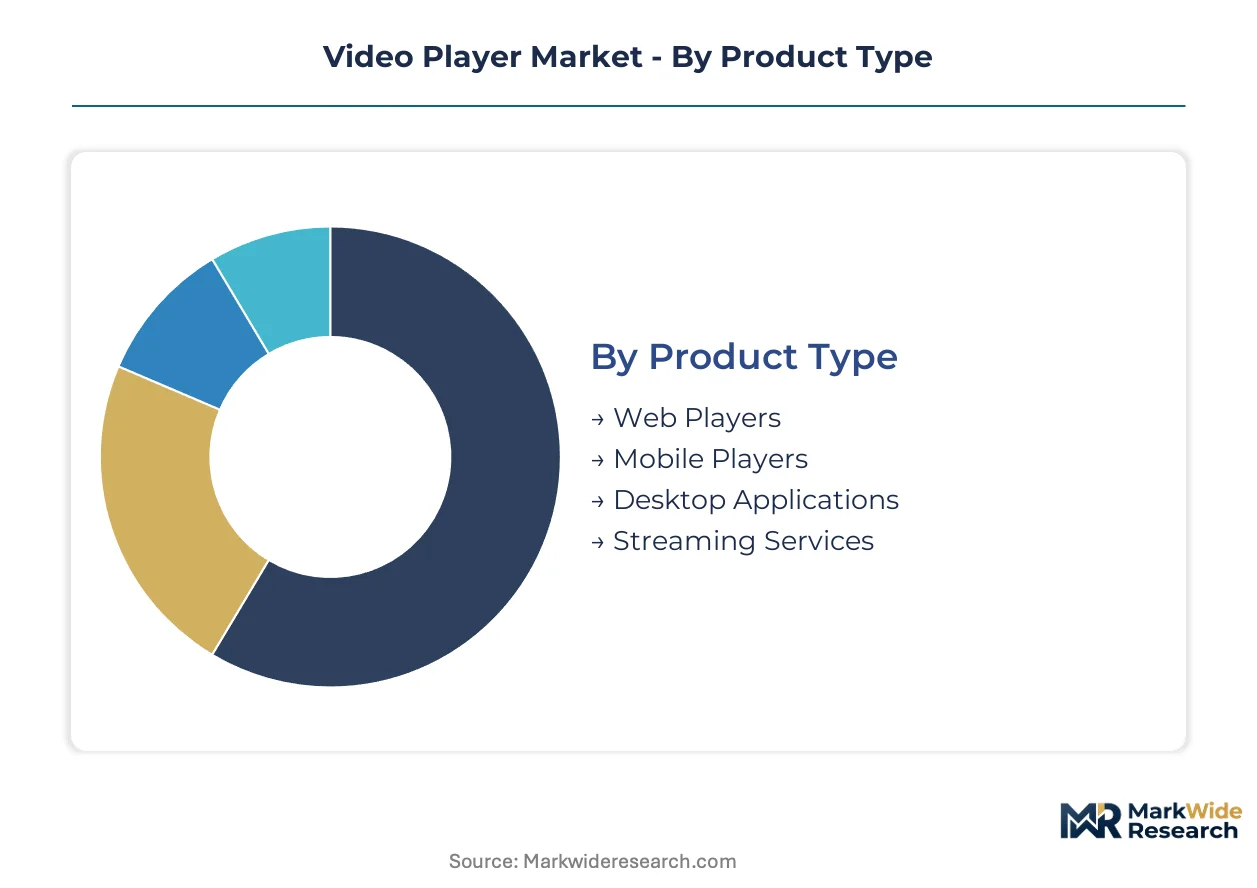
Segmentation of the video player market reveals diverse product forms and deployment strategies tailored to varied user needs. Understanding these distinctions is crucial for vendors to align their offerings with specific customer groups and technological requirements. This analysis dissects the market across product types, deployment models, end-users, and underlying technologies.
Product Type:
The market for video players differentiates significantly based on the integration depth and platform where content is consumed.
- Web Players:Web Players embed directly into websites, utilizing HTML5 technology to provide universal playback across browsers without plugins. Demand concentrates among individual content creators and small enterprises seeking accessible, cross-platform delivery for their digital content.
- Mobile Players:Mobile Players are optimized for smartphone and tablet environments, supporting various operating systems like iOS and Android.
- Desktop Applications:Desktop Applications provide advanced playback controls and offline viewing capabilities for professional users and dedicated media consumption.
- Streaming Services:Streaming Services integrate player functionality directly into their platforms, offering a curated content experience often bundled with subscription models. Major entertainment companies drive this segment, prioritizing seamless user experience and robust content protection features.
Volume placements concentrate in Web Players; the faster expansion belongs to Streaming Services.
Deployment Model:
Cost considerations and infrastructure preferences significantly influence the choice of deployment model for video player solutions.
- Cloud-Based:Cloud-Based deployment offers scalable and flexible infrastructure, hosting player services on remote servers accessible via the internet. Educational institutions and enterprises increasingly adopt this model for its reduced operational overhead and global content delivery capabilities.
- On-Premises:On-Premises solutions involve installing and managing player software directly on a client's own servers, offering maximum control over data.
- Hybrid Solutions:Hybrid Solutions combine elements of both cloud and on-premises deployments, balancing data security with scalability for specific workflows.
- SaaS:SaaS (Software-as-a-Service) models deliver video player functionality as a subscription service, abstracting underlying infrastructure complexities from the user. Small businesses and content creators prefer SaaS for its predictable costs and continuous feature updates.
Scalability requirements drive the adoption of Cloud-Based solutions, while SaaS models are gaining momentum due to their operational simplicity.
End User:
The diverse requirements of various customer types dictate specialized features and support within the video player market.
- Content Creators:Content Creators, including YouTubers and independent filmmakers, use players for distributing their work across various platforms.
- Entertainment Companies:Entertainment Companies, such as broadcasters and streaming giants, demand advanced DRM and monetization tools for their premium content.
- Educational Institutions:Educational Institutions utilize video players for online learning platforms, virtual classrooms, and digital course content delivery. High demand for accessibility features and robust analytics drives innovation in this sector.
- Enterprises:Enterprises leverage video players for internal communications, corporate training, and marketing content, often requiring secure, high-quality streaming. Integration with existing IT infrastructure remains a primary concern for these large organizations.
The largest user base resides with Entertainment Companies, but Educational Institutions are expanding most quickly.
Technology:
Technological advancements define the core capabilities and differentiation points for video player offerings across the market.
- HTML5:HTML5 represents the foundational technology for modern web-based video players, enabling direct browser playback without external plugins. This standard facilitates broad compatibility and powers most content delivery platforms globally.
- Flash:Flash, once dominant for web video, is now largely deprecated due to security vulnerabilities and lack of mobile support.
- DRM Systems:DRM Systems protect copyrighted video content from unauthorized access and distribution, essential for premium media providers.
- AI-Powered Features:AI-Powered Features include intelligent content recommendation, automated video analysis, and personalized user experiences. The European Union's AI Act influences the ethical development and deployment of these advanced functionalities.
Ubiquitous adoption characterizes HTML5 technology, while AI-Powered Features show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for video players concentrates in markets with advanced digital infrastructure and high consumer adoption of digital content. This trend shapes vendor strategies and product development across different regions. Specific regulatory frameworks also influence market dynamics and feature implementation globally.
South Korea
South Korea exhibits strong demand for sophisticated video players, driven by its advanced digital infrastructure and high consumer adoption of streaming content. The country's data privacy regulations influence how viewer analytics and personalization features are developed. The Seoul Metropolitan Area serves as a hub for media technology companies, fostering innovation in interactive video experiences.
Japan
Japan's market for video players benefits from widespread high-speed internet and advanced digital infrastructure. The Ministry of Economy, Trade and Industry (METI) supports initiatives promoting digital content delivery and technological innovation. Major consumer electronics firms in Tokyo and Osaka integrate advanced player functionalities into smart devices.
United States
The United States market sees substantial demand from both large entertainment companies and a growing base of individual content creators. FCC rules mandate accessibility features like closed captioning, directly shaping player design. Technology hubs in Silicon Valley and Los Angeles drive innovation in streaming platforms and interactive video solutions.
Germany
Germany demonstrates significant uptake of video players within its enterprise and educational sectors. The EU's AI Act and GDPR heavily influence the development of AI-powered features and data handling. Technology clusters in Berlin and Munich are actively developing privacy-compliant and feature-rich player solutions.
India
India presents an emerging market opportunity, driven by improving digital infrastructure and a vast mobile-first user base. The Telecom Regulatory Authority of India (TRAI) influences policies related to digital content distribution and internet services. Technology centers in Bengaluru and Mumbai are seeing increased development of localized streaming platforms and player technologies.
Video Player Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue advanced AI-powered features and interactive video commerce. The video player market exhibits a tiered structure, ranging from integrated hardware providers to specialized software-as-a-service platforms. Archetypes include hardware-centric innovators, streaming ecosystem builders, and content production-aligned solution providers. Key competitive moves involve strategic partnerships for ecosystem expansion, continuous technology licensing for codec advancements, and targeted geographic expansion into high-growth digital markets.
Specialists in hardware-integrated experiences include Samsung Electronics Co. Ltd. and Sony Corporation, both large multinational entities. These companies represent a segment focused on delivering premium playback through their extensive consumer electronics portfolios. Roku Inc., an American corporation, exemplifies the streaming ecosystem builder archetype, concentrating on platform-based content delivery. Its strategy reflects a broader trend of leveraging proprietary hardware and software to curate user access to diverse media services. These distinct approaches underscore how diverse business models contribute to the overall competitive landscape.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd. |
| LG Electronics Inc. |
| Sony Corporation |
| Panasonic Corporation |
| Toshiba Corporation |
| Philips |
| Haier Electronics Group Co. Ltd. |
| Roku Inc. |
| Hisense Group |
Cost & Logistics Intelligence
The European Union's AI Act gates qualified supply and premium-tier pricing access for AI-powered features, forcing developers to invest heavily in compliant design. This regulation directly impacts the cost structure for vendors targeting European markets, influencing both product development and pricing strategies.
Pricing Analysis
Volume sales often prioritize cost-effectiveness, while specialized features command higher margins. The dominant pricing structure for video players increasingly favors SaaS subscription models, offering scalability and continuous updates. Price differentiation drivers include advanced AI-powered analytics and robust content protection features like DRM. Pricing softness stems from the widespread availability of basic integrated players within major platforms. Large entertainment companies exhibit lower price sensitivity compared to individual content creators, who remain highly cost-conscious.
Supply Chain Analysis
Data privacy regulations, such as the EU's GDPR, reshape sourcing decisions for cloud infrastructure and AI model development, influencing where compliant services are hosted. Geographic supply concentration for core development resides in technology hubs like Silicon Valley, Berlin, and Seoul. The market depends on codec licenses, including those for H.265/HEVC, and specialized cloud infrastructure services. Codec licensing complexity presents a significant structural supply chain risk. Distribution runs through direct sales for SaaS platforms and integrated channels for hardware-centric players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European Union's GDPR creates a significant barrier-to-entry moat for compliant players, framing this market as a cost-of-compliance story. Vendors must prioritize data privacy and ethical AI development to gain market acceptance, especially in regulated geographies.
For Market Incumbents: Acquire specialized AI talent to fortify proprietary analytics and recommendation engines. Deepen platform integration with content management systems to counter native platform competition. Invest in R&D for advanced content protection and interactive video functionalities. Expanding into emerging markets represents a strategic defensive move against market saturation in established regions.
For New Entrants and Emerging Players: Enter via niche segments like interactive video for commerce or specialized educational tools. Target underpenetrated small business and educational institution markets in regions like Southeast Asia. Offer flexible SaaS models with transparent pricing as a specific go-to-market angle. Focus on developing AI-powered features that prioritize user control and algorithmic transparency to comply with evolving regulations.
For Investors and Strategic Acquirers: Adoption rates of AI-powered features in enterprise and educational sectors are the leading indicator that validates long-term market viability. The market remains strong over a 5-10 year window, driven by digital transformation across sectors. Target specialized AI/analytics firms or interactive video platform developers for acquisition. Watch for increasing enterprise spending on video-based training and communication solutions as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-Powered Analytics | Enhances personalization and audience engagement for content providers. |
| Expand SaaS Deployment Models | Offers financial flexibility and continuous updates for enterprises and small businesses. |
| Strengthen DRM Capabilities | Protects premium content from unauthorized access for entertainment companies. |
| Develop Interactive Video Tools | Unlocks new monetization channels in e-commerce and digital marketing. |
| Target Emerging Digital Markets | Captures new waves of content creators and businesses coming online. |
Research Approach
Independent corroboration across industry reports, academic literature, and company financial filings underwrites the qualitative findings within this analysis. The methodology combines primary interviews with industry stakeholders, including product managers, software engineers, IT procurement officers, and content strategists, with secondary validation. Bottom-up and top-down triangulation ensures robust data integrity and comprehensive market understanding.
The rate-of-change decomposition framing informs the quantitative model, segmenting the market by product type, deployment model, end-user, technology, and regional adoption. CAGRs were derived from historical growth patterns and projected future demand drivers over the projection horizon. Key industry-specific forecast inputs include global internet penetration rates and streaming service subscription growth figures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of rapid technological shifts or evolving regulatory landscapes. The analytical framework reflects assumptions regarding economic stability and continued digital content consumption trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
US Animation, Vfx and Post Production Market
Digital Media
Asia-Pacific (APAC) Media and Entertainment Market
Digital Media
APAC Media and Entertainment Market
Digital Media
Stock Music Software Market
Digital Media
Anime Merchandising Market
Digital Media
North America Online Gambling Market
Digital Media
Digital Music Content Market
Digital Media
Europe Online Gambling Market
Digital Media
India Webtoons Market
Digital Media
North America Webtoons Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
Digital Entertainment in the Home Market
Digital Media
Online Gambling Market
Digital Media
China Webtoons Market
Digital Media
Mexico Webtoons Market
Digital Media
4K Content Market