
 Adaptive Content Publishing Market | 2026-2036
Adaptive Content Publishing Market Size, Share, and Industry Trends Forecast 2026-2036
Adaptive Content Publishing Market Analysis
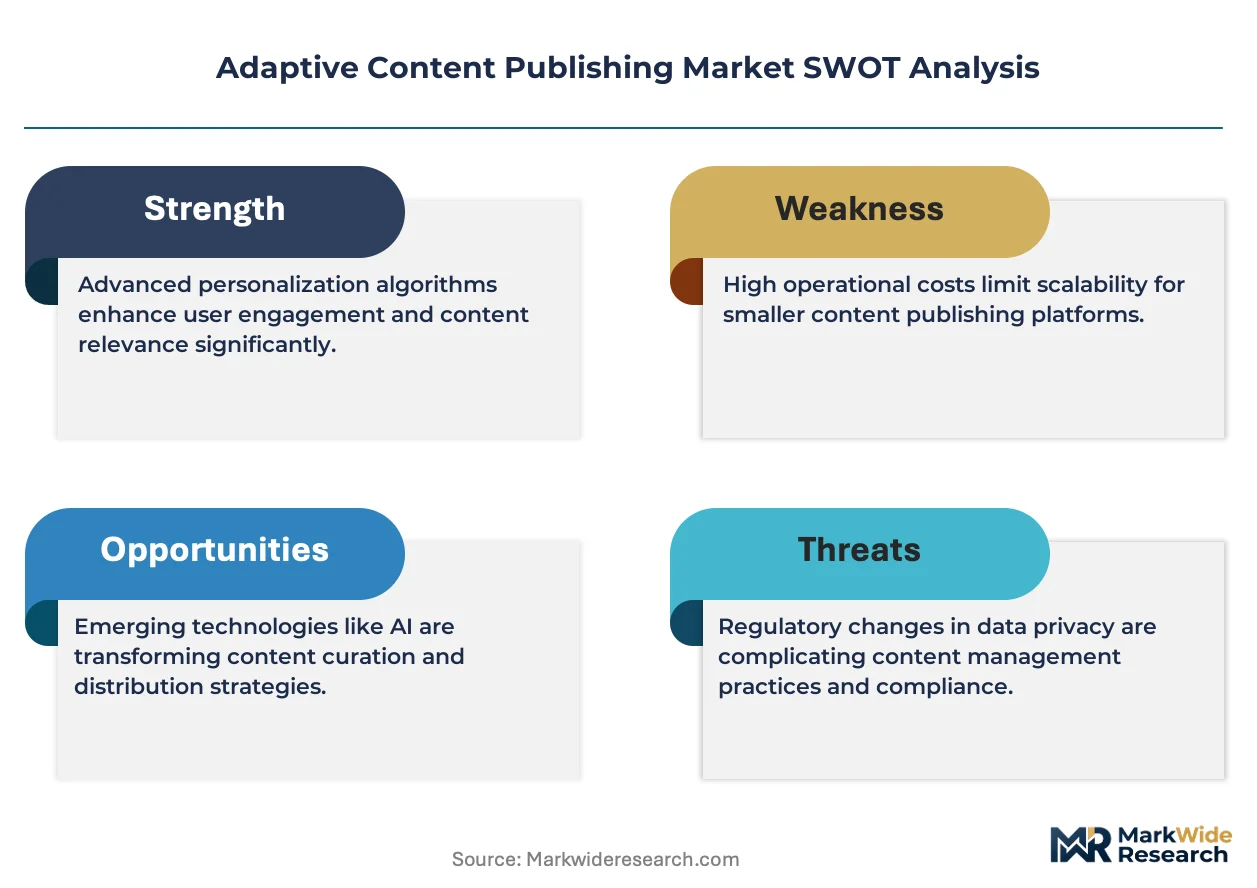
GDPR enforcement on automated profiling is realigning procurement priorities across European content operations. Adobe leverages its creative cloud integration to sustain platform stickiness among enterprise creative teams. Sitecore specializes in composable architecture that anchors complex multi-site deployments for regulated industries. IBM navigates hybrid cloud requirements that differentiate its governance layer from pure SaaS competitors.
Adaptive content publishing denotes systems that dynamically assemble, personalize, and distribute digital assets across channels using real-time audience signals and rules-based automation, typically operating through headless CMS architectures with JSON API delivery and edge caching below 100ms latency. These platforms serve commercial purposes spanning automated product description generation, localized campaign versioning, and compliance-controlled pharmaceutical detailing. Text-centric workflows occupy the largest operational footprint among publishers managing high-volume editorial pipelines, while video delivery through streaming modes captures the fastest expansion as bandwidth infrastructure improves. Cloud-based integration levels now dominate new deployments, though API-native configurations attract developer-heavy organizations seeking custom orchestration layers.
The EU AI Act and GDPR jointly constrain how European publishers deploy automated content personalization, forcing explicit consent architectures and audit trails into platform specifications. The Federal Trade Commission in the United States has intensified scrutiny of dark pattern design in adaptive interfaces, elevating compliance tooling from optional to mandatory in vendor evaluations. Stakeholders must now weigh jurisdictional regulatory load against latency performance when selecting deployment regions and data residency configurations.
Market Dynamics
Headless CMS architectures are compressing content delivery latencies below 100ms while EU AI Act transparency mandates force publishers to rebuild consent infrastructure from the ground up.
Growth Catalysts
- EU AI Act:Automated content personalization systems now require explicit audit trails, creating procurement urgency among European enterprise publishers seeking compliant platforms.
- Edge caching infrastructure:CDN providers have expanded point-of-presence density to sub-50ms thresholds, enabling real-time adaptive assembly for streaming video workflows.
- Multi-brand conglomerates:US-based media holding companies demand unified orchestration layers to manage fragmented channel ecosystems across dozens of properties.
Market Restraints
- Consent architecture costs:GDPR-mandated explicit consent systems add 15-25% to platform implementation budgets for European deployments.
- Developer talent scarcity:API-native configurations require specialized GraphQL and edge-computing expertise concentrated in San Francisco, London, and Bangalore metro areas.
- Hybrid cloud complexity:Regulated industries face data residency requirements that fragment infrastructure across multiple sovereign cloud zones.
Strategic Opportunities
- Pharmaceutical detailing:Compliance-controlled content versioning for drug promotion remains underpenetrated, with only 30% of top-20 pharma firms deploying adaptive systems.
- Voice-activated delivery:Smart speaker ecosystems and in-car infotainment systems create new channels requiring JSON-API content pipelines.
- CSRD reporting mandates:European sustainability disclosure requirements drive demand for automated ESG content assembly across corporate communications.
Industry Challenges
- Legacy CMS migration friction:Monolithic WordPress and Adobe Experience Manager installations resist decomposition into headless architectures without 12-18 month timelines.
- Algorithmic bias auditing:Content personalization engines require continuous fairness testing that most publishers lack internal capability to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adaptive Content Publishing Market |
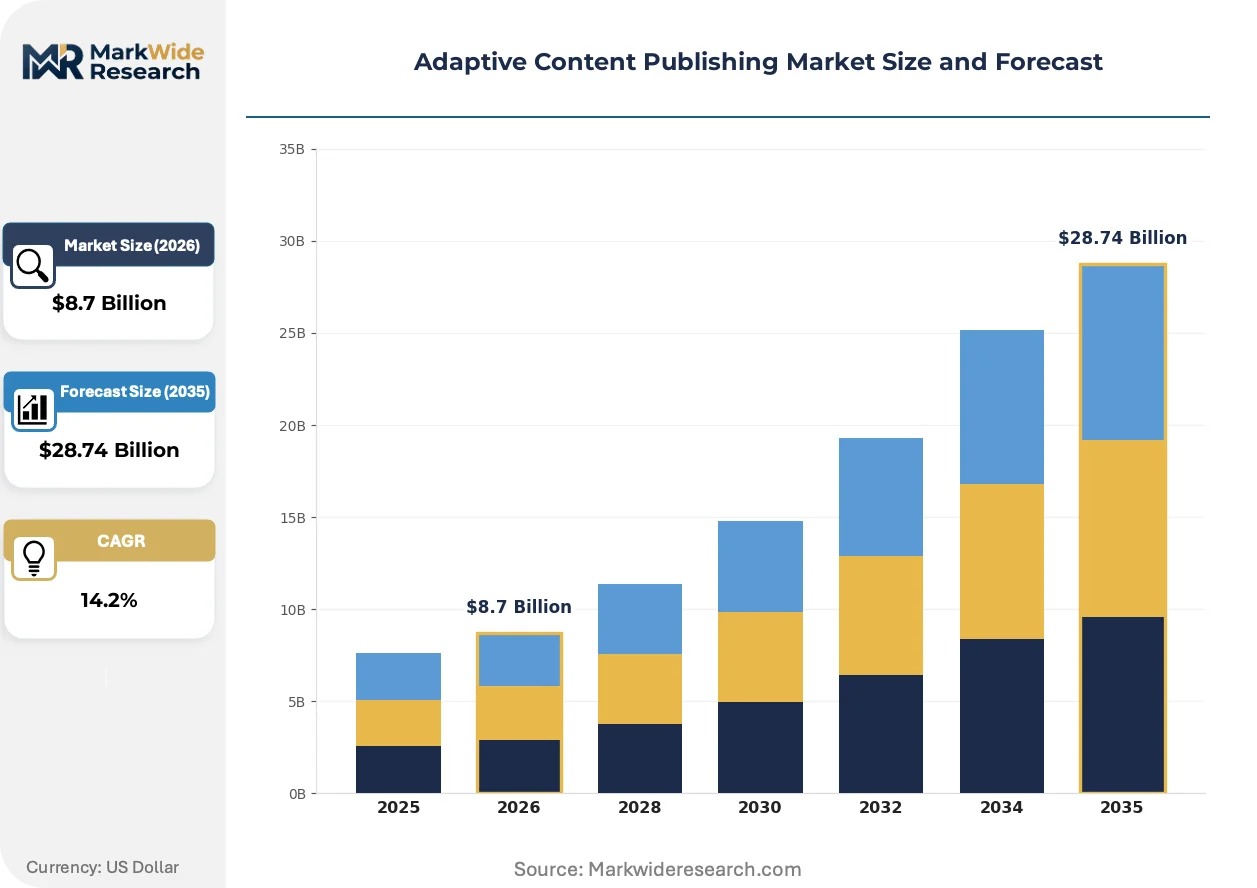
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Text, Video, Audio, Image Delivery Mode: Streaming, Downloadable, Live, On-Demand End User: Publishers, Brands, Agencies, Freelancers Integration Level: API, Plug-in, Standalone, Cloud-Based |
| Companies Covered | Salesforce, HubSpot, Adobe, Contentstack, Crownpeak, Google, IBM, Sitecore, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adaptive Content Publishing Market Emerging Trajectories
Real-time audience signal processing is displacing batch-based content scheduling, while regulatory pressure forces architectural choices that prioritize transparency over pure performance optimization.
Generative AI content augmentation is converging with headless CMS workflows to enable dynamic product description generation at scale. E-commerce operators with catalogs exceeding 100,000 SKUs are deploying these hybrid systems to reduce manual copywriting overhead by 60-80%. The structural consequence is compressing traditional agency relationships as in-house platforms assume creative production tasks.
The EU AI Act's transparency obligations for algorithmic curation are forcing publishers to deploy explainable recommendation engines with documented decision trails. Industrial consequence includes mandatory human-in-the-loop review stages for high-risk content categories. Financial services and healthcare publishers in Germany, France, and the Netherlands are most affected, responding with dedicated AI ethics officer hires and external audit retainers.
Enterprise buyers now demand consumption-based pricing tied to actual content deliveries rather than seat-based licenses. The agency channel faces disintermediation as direct platform procurement grows 40% annually among mid-market publishers. This shift is most visible in the United Kingdom and Nordics, where procurement teams prioritize operational expenditure flexibility over capital-intensive perpetual licenses.
Adaptive Content Publishing Market Segmentation
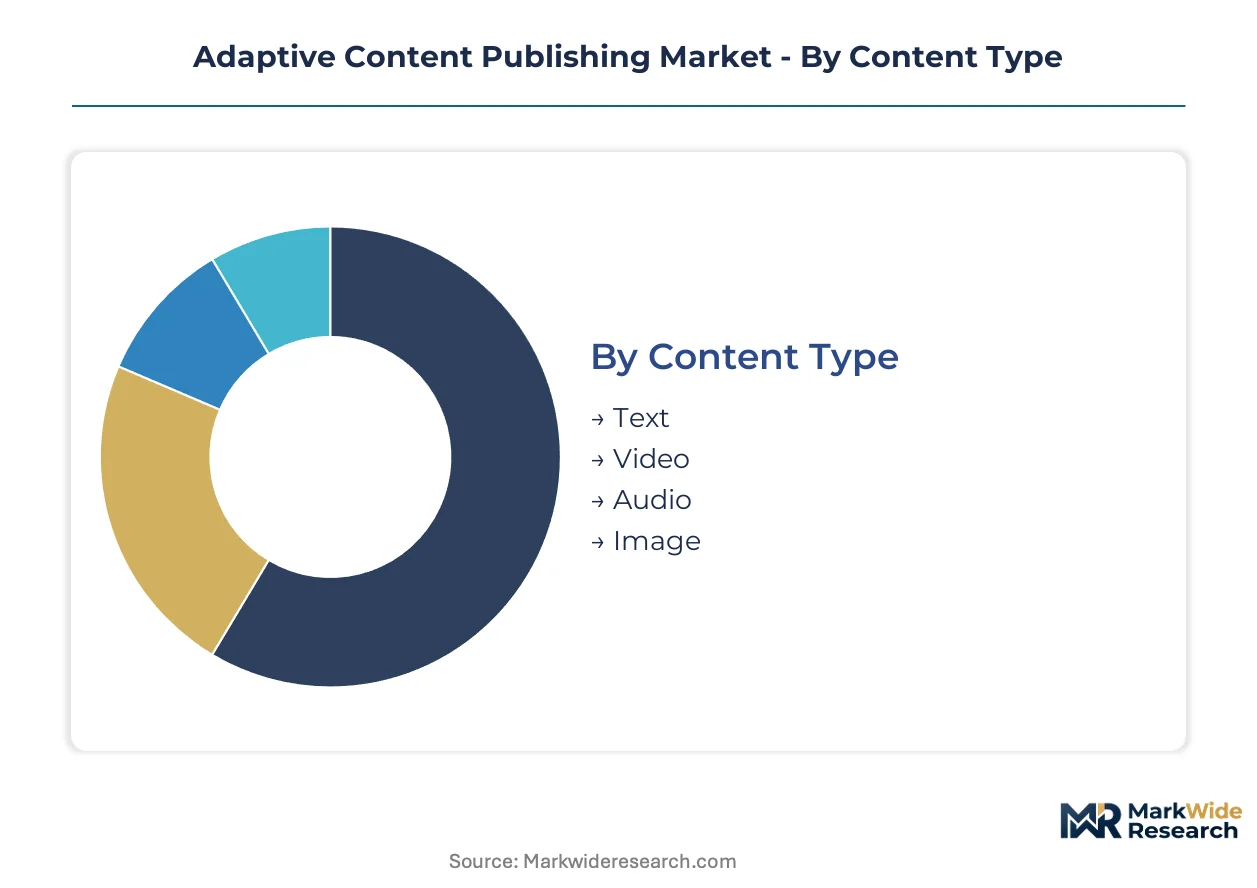
Adaptive content publishing platforms fragment across four structural dimensions that determine procurement patterns and implementation complexity. Content type and delivery mode define technical architecture, while end-user profiles and integration depth shape vendor selection criteria and pricing models.
Content Type:
Integration depth varies sharply by content format, with text workflows embedding most deeply into editorial systems while video often operates as standalone streaming infrastructure.
- Text:JSON-API pipelines dominate high-volume editorial operations, with German and French newsrooms driving demand for GDPR-compliant automated versioning systems. The EU AI Act's transparency mandates force explicit audit trails into headline generation and personalized article curation.
- Video:Edge-cached streaming below 50ms latency enables real-time adaptive assembly for product demos and localized advertising. US media conglomerates with multi-brand portfolios concentrate procurement here, seeking unified orchestration across fragmented channel ecosystems.
- Audio:Podcast and voice-activated content pipelines leverage headless CMS architectures for smart speaker distribution.
- Image:Dynamic asset transformation and responsive delivery power e-commerce catalogs and programmatic advertising workflows.
Text leads volumes today; video is gaining share fastest.
Delivery Mode:
Cost tier stratification separates capital-intensive live infrastructure from operational expenditure models favoring on-demand and downloadable delivery.
- Streaming:CDN point-of-presence expansion to sub-50ms thresholds enables adaptive bitrate assembly for personalized video experiences. Financial services publishers in the Netherlands deploy these systems for compliance-controlled client communications with mandatory human-in-the-loop review stages.
- Downloadable:Offline-capable content packages serve pharmaceutical detailing workflows where field representatives require localized drug information without continuous connectivity. Only 30% of top-20 pharma firms currently deploy adaptive systems here.
- Live:Real-time adaptive personalization for breaking news and sports betting interfaces demands sub-100ms latency with edge computing infrastructure.
- On-Demand:Consumption-based pricing models attract mid-market publishers in the United Kingdom and Nordics prioritizing operational expenditure flexibility.
On-demand delivery commands the largest installed base; live infrastructure shows steepest expansion trajectory.
End User:
Customer type determines platform sophistication, with enterprise publishers demanding governance layers that freelancers and small agencies rarely require.
- Publishers:Multi-brand media holding companies in the United States seek unified content orchestration across dozens of properties, driving demand for composable architecture with sovereign cloud zone compliance. Adobe leverages creative cloud integration to sustain platform stickiness among these enterprise creative teams.
- Brands:Direct-to-consumer operators with catalogs exceeding 100,000 SKUs deploy generative AI hybrid systems for dynamic product description generation, compressing traditional agency relationships.
- Agencies:The agency channel faces disintermediation as direct platform procurement grows annually among mid-market publishers.
- Freelancers:Seat-based licensing persists at the low end despite enterprise migration toward consumption-based models.
Publishers dominate current procurement value; brands are expanding their platform investments most aggressively.
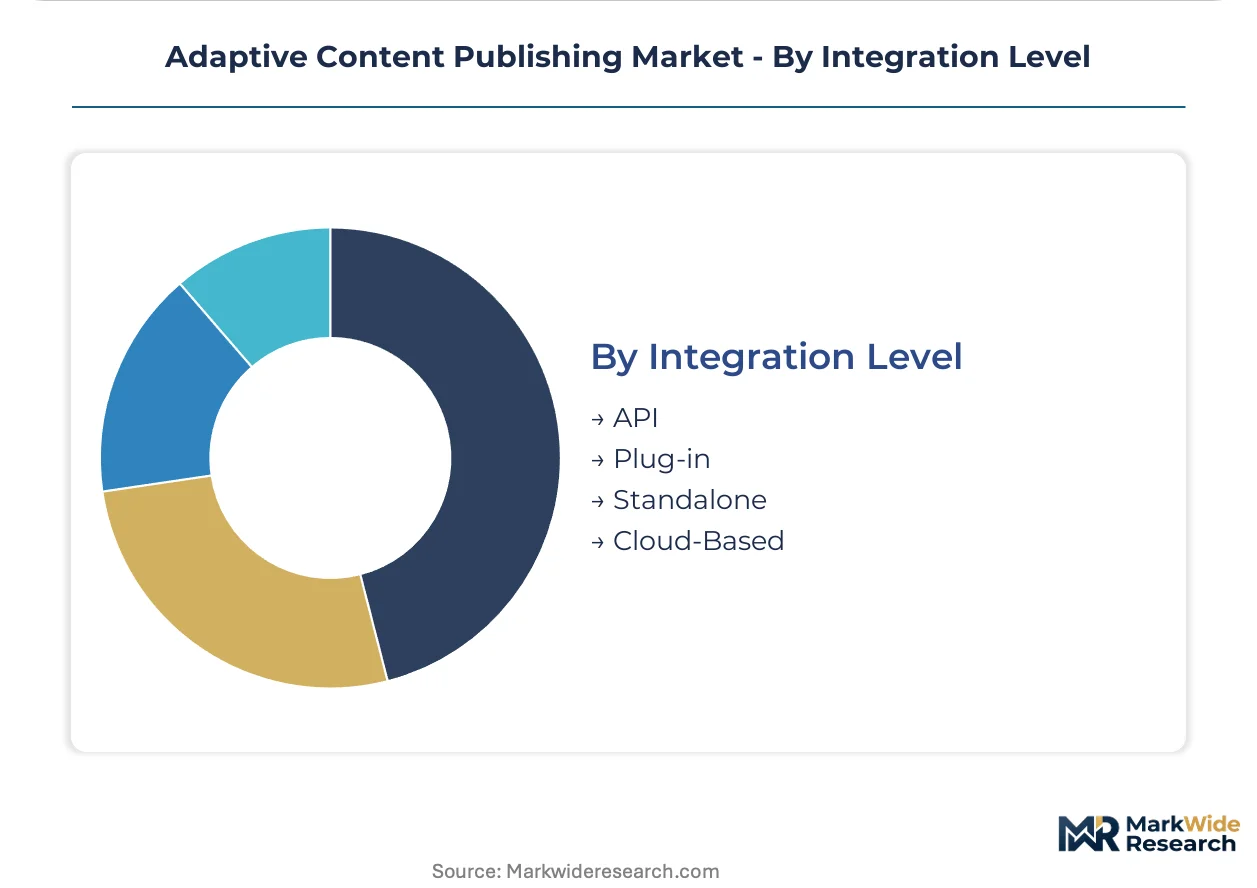
Integration Level:
Maturity gradients separate legacy monolithic deployments from API-native configurations requiring specialized developer expertise concentrated in San Francisco, London, and Bangalore metro areas.
- API:GraphQL and RESTful architectures enable custom orchestration layers for developer-heavy organizations. Sitecore specializes in composable architecture anchoring complex multi-site deployments for regulated industries with hybrid cloud requirements.
- Cloud-Based:New deployments predominantly favor cloud integration levels, though data residency requirements fragment infrastructure across multiple sovereign cloud zones for regulated European publishers.
- Plug-in:Extension-based integration extends existing CMS investments without full platform replacement, appealing to publishers with 12-18 month migration timelines.
- Standalone:Self-contained systems persist in closed-loop pharmaceutical detailing and financial services communications where air-gapped compliance is mandatory.
Cloud-based integration leads new deployment volumes; API-native configurations are climbing the fastest among technology-forward organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The adaptive content publishing industry traces its commercial origins to enterprise software development clusters in the United States, where early headless CMS architectures emerged from San Francisco Bay Area infrastructure investments during the 2010s cloud computing expansion.
United States
Multi-brand media holding companies headquartered in New York and Los Angeles drive procurement volumes for unified content orchestration platforms. FTC scrutiny of dark pattern design in adaptive interfaces elevates compliance tooling to mandatory status in vendor evaluations. The San Francisco Bay Area anchors developer talent concentration for API-native configurations requiring GraphQL and edge-computing expertise.
Germany
Financial services and healthcare publishers in Frankfurt and Munich respond to EU AI Act transparency mandates with dedicated AI ethics officer hires and external audit retainers. GDPR enforcement on automated profiling realigns procurement priorities toward explicit consent architectures. The Rhine-Main metropolitan region hosts the densest cluster of compliance-controlled pharmaceutical detailing deployments in Europe.
United Kingdom
Mid-market publishers in London and Manchester prioritize operational expenditure flexibility, accelerating direct platform procurement that grows annually against traditional agency channels. Consumption-based pricing models displace seat-based licenses among procurement teams. The Southeast England corridor concentrates SaaS vendor development operations serving European regulatory requirements.
France
Newsrooms in Paris and Lyon demand GDPR-compliant automated versioning systems for high-volume editorial operations. CNIL guidance on algorithmic transparency forces explicit audit trails into headline generation workflows. The Île-de-France region hosts enterprise creative teams sustained by Adobe's creative cloud integration stickiness.
Netherlands
Financial services publishers in Amsterdam deploy edge-cached streaming infrastructure for compliance-controlled client communications with mandatory human-in-the-loop review stages. The Dutch national pharmaceutical regulator shapes content versioning requirements for drug promotion materials. The Randstad metropolitan cluster leads European adoption of hybrid cloud configurations fragmenting infrastructure across sovereign zones.
Adaptive Content Publishing Market Vendor Landscape
The competitive structure tilts toward diversified technology conglomerates with adjacent cloud infrastructure assets. Enterprise software vendors with creative suite integration and composable architecture specialists divide procurement decisions across regulated and unregulated verticals. Two strategic archetypes dominate: horizontal platform providers leveraging existing enterprise relationships, and vertical specialists anchoring complex multi-site deployments. Competitive moves concentrate on API-native capability expansion and sovereign cloud zone certification for European data residency requirements.
Within the horizontal platform tier, Adobe and Salesforce represent archetypes of creative cloud integration and enterprise CRM anchoring respectively. IBM occupies a position bridging hybrid cloud governance requirements that differentiate from pure SaaS competitors. Sitecore exemplifies the composable architecture specialist archetype, anchoring complex multi-site deployments for regulated industries with fragmented infrastructure needs across sovereign zones. These three companies collectively illustrate the strategic divergence between consolidation through adjacent service integration and specialization through modular deployment flexibility.
| Leading Market Players |
|---|
| Salesforce |
| HubSpot |
| Adobe |
| Contentstack |
| Crownpeak |
| IBM |
| Sitecore |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
GraphQL and edge-computing expertise concentrated in San Francisco, London, and Bangalore metro areas creates labor-cost differentials that widen pricing-tier spreads between API-native configurations and plug-in integration levels. European publishers absorbing GDPR-mandated explicit consent architecture costs face 15-25% implementation budget premiums that compress margin structures for mid-market deployments.
Pricing Analysis
Consumption-based pricing tied to actual content deliveries now dominates enterprise procurement, displacing seat-based licenses among mid-market publishers prioritizing operational expenditure flexibility. Price differentiation hinges on integration complexity and compliance certification tier, with sovereign cloud zone configurations commanding premiums over standard SaaS deployments. Cost compression in cloud-based tiers is intensifying because hyperscaler infrastructure commoditization erodes platform margins. Freelancers and small agencies exhibit highest price sensitivity, while regulated pharmaceutical and financial services publishers accept premium positioning for audit-trail capabilities.
Supply Chain Analysis
GDPR and EU AI Act certification gating restricts vendor qualification to platforms with documented consent architectures and explainable recommendation engines, concentrating compliant supply among established enterprise software providers with dedicated compliance engineering. Platform development draws from cloud infrastructure services anchored in the United States, Ireland, and Singapore, with edge caching hardware sourced from Taiwan and South Korea. Single-source vulnerability in specialized GraphQL developer talent pools creates delivery bottlenecks for complex multi-site deployments. Distribution runs through direct procurement channels growing annually against traditional agency intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adaptive content publishing market functions as a stable compounder, with regulatory compliance mandates across European jurisdictions generating durable procurement urgency that sustains platform replacement cycles.
For Market Incumbents: Lock in platform stickiness through creative cloud integration and composable architecture certification for sovereign cloud zones. Defensive moves should emphasize hybrid cloud governance layers that differentiate from pure SaaS competitors, while capacity investment in explainable AI audit tooling addresses EU AI Act transparency mandates. The priority lever centers on API-native capability expansion to capture developer-heavy organizations seeking custom orchestration layers. For New Entrants and Emerging Players: Voice-activated delivery channels represent the most penetrable white-space target, with smart speaker ecosystems and in-car infotainment systems requiring JSON-API content pipelines that incumbent platforms have underdeveloped. Pharmaceutical detailing workflows offer secondary entry, with only 30% of top-20 pharma firms currently deploying adaptive systems. A vertical-specific go-to-market angle targeting compliance-controlled content versioning for drug promotion materials bypasses direct competition with horizontal platform providers. For Investors and Strategic Acquirers: Cloud infrastructure providers with adjacent enterprise relationships are the most active acquirer in this space, seeking to anchor content orchestration within broader digital transformation stacks. The long-term viability window favors platforms with demonstrated sovereign zone certification and hybrid deployment flexibility. Acquisition targets should display composable architecture specialization with regulated industry penetration. The signal to watch is mandatory human-in-the-loop review stage adoption rates among financial services and healthcare publishers in Germany, France, and the Netherlands.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Creative cloud integration sustains stickiness among enterprise creative teams in media holding companies. |
| Sovereign Cloud Certification | GDPR-mandated data residency requirements fragment infrastructure across multiple European cloud zones. |
| Generative AI Augmentation | Dynamic product description generation reduces manual copywriting overhead for e-commerce catalogs exceeding 100,000 SKUs. |
| Compliance Tooling Investment | Explainable recommendation engines with documented decision trails address EU AI Act transparency obligations. |
| API-Native Capability Expansion | GraphQL and edge-computing expertise enables custom orchestration layers for developer-heavy organizations in San Francisco and London. |
Methodological Framework
Direct dialogue with CTOs, IT procurement officers, platform engineers, and integration specialists grounded the qualitative assessment, supplemented by secondary validation against SEC filings, hyperscaler capex disclosures, and enterprise software vendor financial reports. Bottom-up sizing from individual deployment metrics and top-down triangulation against aggregate platform revenue disclosures ensured methodological cross-checking.
Market value and volume outputs across the analysis window reflect segmentation modeling across content type, delivery mode, end-user profile, and integration depth dimensions, with CAGRs derived from regression analysis against technology adoption curves and regulatory implementation timelines. Edge caching infrastructure expansion rates and consent architecture deployment costs served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for headless CMS migration would alter the outlook if legacy monolithic decomposition timelines compress or extend beyond baseline assumptions. Forecasts reflect documented assumptions regarding EU AI Act implementation enforcement intensity and GDPR automated profiling interpretation consistency. A model refresh is warranted upon material change in regulatory penalty structures or edge computing latency threshold breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
China Catalog Market
Digital Publishing
France Catalog Market
Digital Publishing
Newspaper Market
Digital Publishing
Comic Book Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Magazine Subscription Service Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
GCC Commercial Printing Market
Digital Publishing
Global E-Book Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Digital Comics Market
Digital Publishing
Mexico Commercial Printing Market
Digital Publishing
Digital Publishing Platforms Market